
 Europe Blanket Aerogel Market | 2026-2036
Europe Blanket Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blanket Aerogel Market Analytics
Buyer concentration among European oil and gas contractors is decoupling from legacy insulation supply agreements as project specifications tighten thermal performance requirements. Aspen Aerogels Inc. sustains technology leadership in flexible blanket formats for subsea pipeline wraps. Cabot Corporation leverages its silica precursor supply chain to dominate raw material cost structures. Svenska Aerogel AB anchors Nordic manufacturing capacity with proximity to pulp-and-paper industry retrofit demand.
Blanket aerogel comprises a flexible, low-density silica matrix with porosity exceeding 90 percent, manufactured through supercritical drying of alkoxide-derived wet gels to achieve thermal conductivity below 0.020 W/m·K for extreme-temperature industrial insulation. Construction applications lead volume absorption as the EU Green Deal drives deep retrofit mandates across residential and commercial building stocks. Oil and gas insulation represents the fastest-growing application segment, with aerogel blankets displacing multilayer mineral wool systems in LNG transport and refinery maintenance cycles. Composite aerogels command premium positioning where mechanical durability requirements exclude pure silica formulations.
EMA's construction product regulation and REACH compliance protocols govern material safety certification and chemical constituent disclosure for aerogel blanket placement in European buildings. The F-Gas Regulation progressively restricts hydrofluorocarbon blowing agents, redirecting formulation investment toward water-glass and bio-based precursor routes. Stakeholders must monitor evolving CE marking criteria for fire-reaction classification as member states tighten national building codes ahead of unified EU standards.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing specification cycles for superinsulation materials, forcing contractors to abandon mineral wool legacy systems in favor of aerogel blanket formats that meet stricter thermal bridging standards.
Growth Catalysts
- F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon blowing agents redirect formulation R&D toward water-glass and bio-based silica precursors, expanding viable production pathways for European manufacturers.
- Netherlands offshore energy cluster:LNG transport operators specify aerogel blanket wraps for subsea pipeline thermal management, displacing multilayer mineral wool in North Sea infrastructure.
- Germany chemical processing corridor:Refinery maintenance cycles adopt flexible aerogel formats for extreme-temperature vessel insulation, reducing downtime versus rigid board alternatives.
Market Restraints
- Silica precursor cost volatility:Tetraethyl orthosilicate and sodium silicate feedstock prices fluctuate with construction chemical demand, compressing blanket aerogel margins against mineral wool cost structures.
- Nordic supply concentration:Pulp-and-paper industry retrofit demand concentrates procurement power among Swedish and Finnish buyers, limiting pricing leverage for peripheral suppliers.
- REACH compliance friction:ECHA substance registration requirements for nano-scale silica particles extend certification timelines and raise disclosure burdens versus conventional insulation categories.
Strategic Opportunities
- Poland residential retrofit wave:EU cohesion funds target deep energy renovation of communist-era housing stock, creating first-mover advantage for aerogel blanket distributors with local installation partnerships.
- CE marking harmonization:Pending unified fire-reaction classification standards promise to replace fragmented national building codes, reducing cross-border product adaptation costs.
- Composite aerogel-mechanical reinforcement:Fiber-reinforced silica matrices address durability limitations in high-vibration industrial settings, opening refinery and petrochemical applications previously closed to pure formulations.
Industry Challenges
- Supercritical drying technician scarcity:Specialized solvent extraction expertise concentrates among legacy chemical engineering programs in Germany and the Netherlands, constraining production scale-up outside established clusters.
- CE marking fire classification delays:Member state divergence in national building code interpretations creates certification bottlenecks, particularly for residential applications in France and Italy.
- Legacy insulation contractor retraining:Mineral wool installation networks require capability rebuilding to handle fragile aerogel blanket formats without compromising thermal performance through compression damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blanket Aerogel Market |
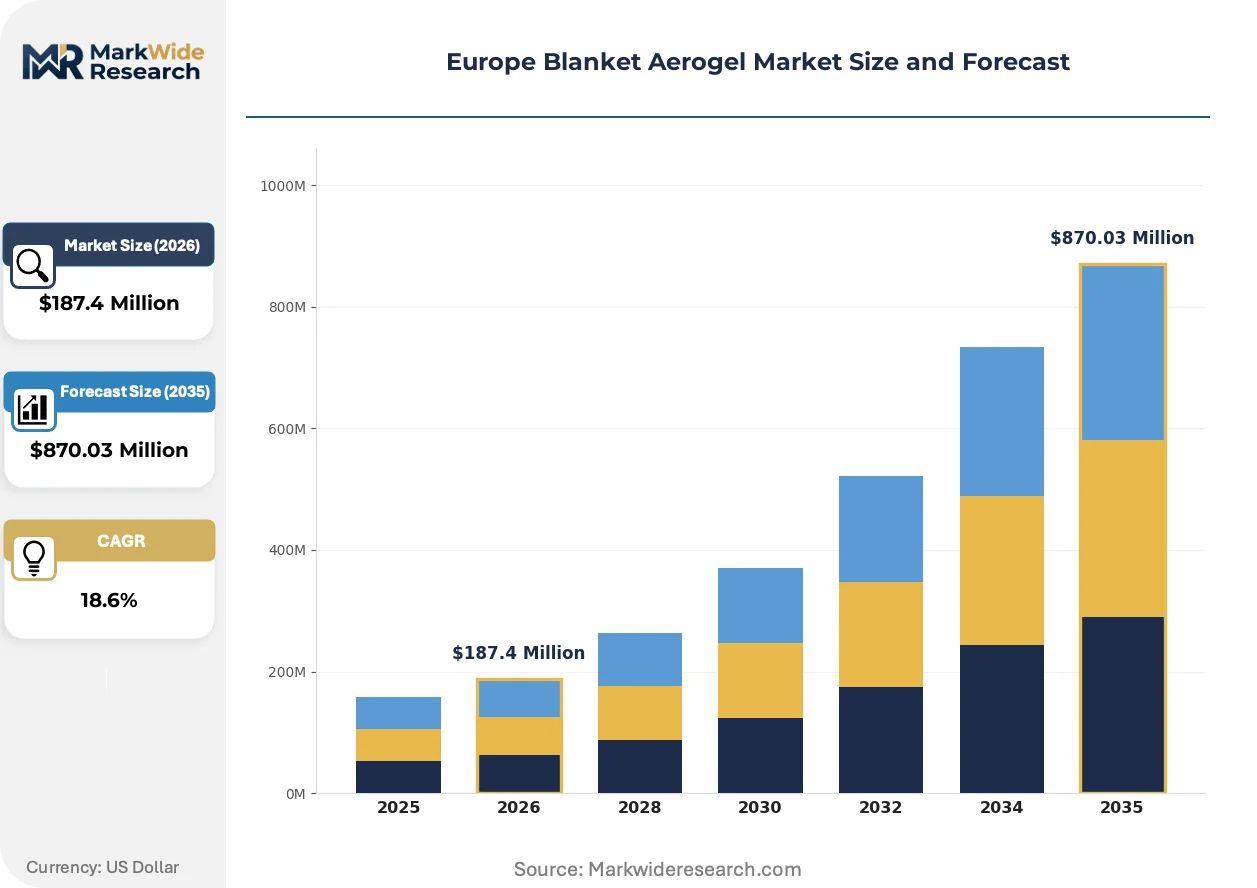
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexibles, Rigid, Aerogel Granules, Composite Aerogels Application: Construction, Automotive Insulation, Oil & Gas, Aerospace End User: Manufacturers, Contractors, OEMs, Research Institutions Distribution Channel: Online Sales, Direct Sales, Distributors, Retailers |
| Companies Covered | Cabot Corporation, Aspen Aerogels Inc., Svenska Aerogel AB, Enersens Aerogel, Active Aerogels, Armacell International S.A., BASF SE, Green Earth Aerogel Technologies, Airglass AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blanket Aerogel Market Evolving Landscape
Water-glass derived aerogel formulations are overtaking alkoxide-based production in European manufacturing, driven by precursor cost advantages and simplified supercritical drying protocols that reduce energy intensity.
Flexible silica matrix blankets with porosity exceeding 90 percent is overtaking rigid board formats in subsea pipeline specifications. North Sea operators prioritize wrap-around installation speed and thermal conductivity below 0.020 W/m·K. The shift compresses project timelines from weeks to days versus multilayer mineral wool systems.
REACH compliance protocols are tightening disclosure requirements for nano-scale silica constituents in building products. ECHA's evolving guidance on substance registration creates competitive differentiation for manufacturers with pre-validated safety dossiers. German and Dutch chemical processors now specify REACH-registered aerogel sources exclusively.
Specification authority is migrating from general contractors to energy performance consultants in EU-funded retrofit programs. Deep renovation mandates in Germany and France require modeled thermal bridging calculations that favor superinsulation materials. Procurement patterns concentrate among engineering firms with building physics simulation capabilities rather than traditional insulation distributors.
Europe Blanket Aerogel Market Segmentation
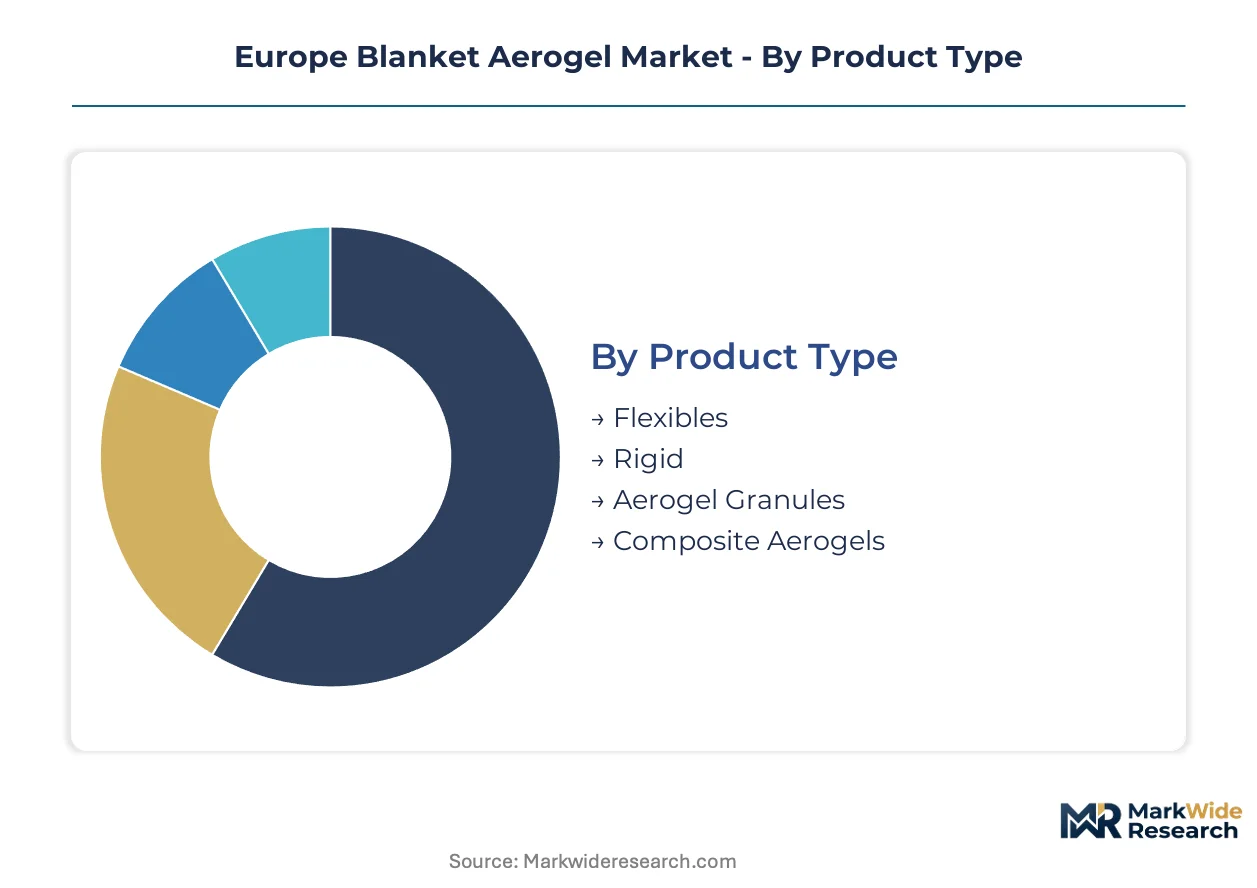
Blanket aerogel procurement patterns diverge sharply across thermal performance requirements, installation complexity, and regulatory exposure. Buyers self-select into distinct specification tiers based on project scale, technical capability, and compliance burden tolerance.
Product Type:
Cost tier differentiation separates specification-grade buyers from commodity procurement in this category.
- Flexibles:Silica matrix blankets with fiber reinforcement enable wrap-around installation on irregular surfaces and subsea pipelines. Demand concentrates among North Sea LNG operators in the Netherlands and Norway where thermal conductivity below 0.020 W/m·K displaces mineral wool in deep-water infrastructure. F-Gas Regulation phase-down accelerates water-glass derived formulations for cost-sensitive projects.
- Composite Aerogels:Fiber-reinforced or polymer-integrated matrices address mechanical durability limits of pure silica in high-vibration refinery settings. Germany's chemical processing corridor specifies these formats for vessel insulation during maintenance cycles, reducing thermal bridging versus rigid alternatives. REACH compliance protocols favor manufacturers with pre-validated nano-silica safety dossiers.
- Rigid:Board formats suit planar industrial surfaces with lower installation complexity requirements.
- Aerogel Granules:Loose-fill applications target cavity insulation and specialized casting processes.
Volume sits with Flexibles; growth tilts toward Composite Aerogels.
Application:
Regulatory intensity and project scale reshape buyer priorities across end-use contexts.
- Construction:Deep retrofit mandates under the EU Green Deal compress specification cycles for superinsulation in residential and commercial building stocks. Germany and France require modeled thermal bridging calculations that favor blanket aerogel over mineral wool in facade renovation. CE marking harmonization pending across member states promises to reduce cross-border adaptation costs.
- Oil & Gas:Subsea pipeline thermal management drives fastest adoption, with LNG transport operators specifying flexible wraps that compress installation timelines from weeks to days. North Sea infrastructure clusters in Norway, the UK, and the Netherlands anchor procurement concentration.
- Automotive Insulation:Electric vehicle battery thermal management and cabin comfort applications target premium vehicle segments.
- Aerospace:Weight-critical insulation for aircraft systems and spacecraft thermal protection.
Construction holds current volume leadership; Oil & Gas climbs the fastest.
End User:
Technical capability and procurement authority determine specification influence in this category.
- Contractors:Installation networks handling EU-funded retrofit programs require retraining from mineral wool techniques to fragile aerogel blanket handling without compression damage. Poland's residential renovation wave creates first-mover advantage for contractors with certified installation partnerships.
- OEMs:Original equipment manufacturers in automotive and aerospace integrate aerogel insulation into system designs during product development phases.
- Manufacturers:Industrial facility operators specify materials for in-house maintenance and capital projects.
- Research Institutions:Academic and government laboratories drive formulation innovation and performance validation.
Contractors dominate near-term procurement volume; OEMs gain specification authority fastest.
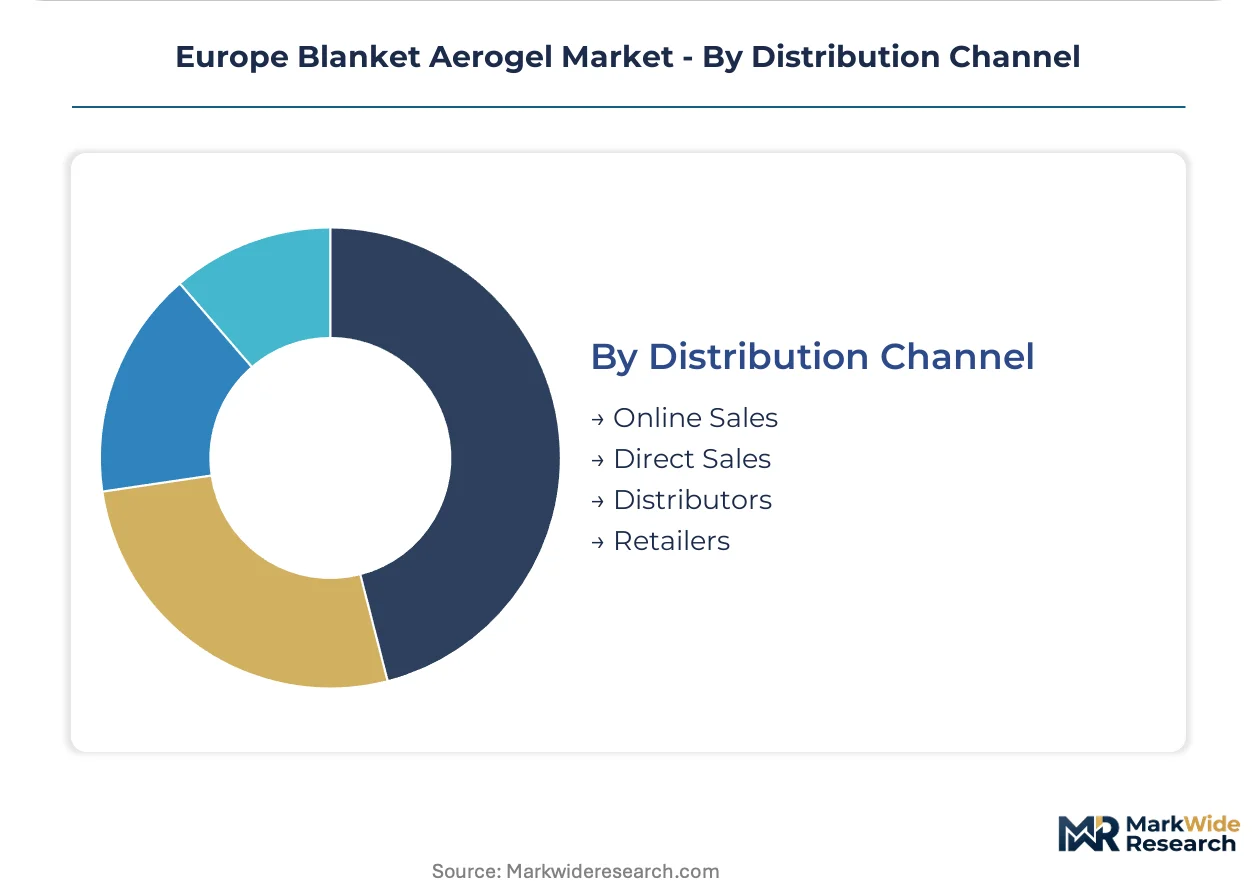
Distribution Channel:
Customer scale and technical support requirements fragment route-to-market strategies.
- Direct Sales:Large-scale oil and gas contractors and chemical processors negotiate volume contracts with manufacturers for project-specific thermal performance guarantees. Nordic pulp-and-paper retrofit demand concentrates procurement power among Swedish and Finnish buyers favoring direct relationships.
- Distributors:Regional insulation specialists serve mid-scale construction contractors with inventory availability and local technical support.
- Online Sales:Small-volume procurement and specification sampling for research or pilot projects.
- Retailers:Limited presence given technical consultation requirements and specialized handling protocols.
Direct Sales capture project value; Distributors expand geographic reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's chemical processing corridor and the Netherlands' offshore energy infrastructure cluster, with Nordic pulp-and-paper retrofits and French deep renovation programs adding volume depth across the region.
Germany
Refinery maintenance cycles and EU Green Deal building retrofits drive specification of flexible aerogel formats for extreme-temperature vessel insulation. The F-Gas Regulation accelerates water-glass derived formulation investment among domestic processors. The Rhine-Ruhr chemical corridor anchors procurement concentration as facility operators displace rigid board alternatives.
Netherlands
North Sea LNG transport operators specify blanket aerogel wraps for subsea pipeline thermal management, compressing installation timelines from weeks to days. REACH compliance protocols govern nano-silica disclosure requirements for offshore applications. The Rotterdam-Antwerp port cluster channels procurement toward contractors with certified marine installation capabilities.
Sweden
Pulp-and-paper industry retrofit demand concentrates procurement power among Swedish buyers favoring direct manufacturer relationships. ECHA substance registration requirements extend certification timelines for nano-scale silica particles. The Stockholm-Uppsala manufacturing belt hosts Nordic production capacity serving regional insulation demand.
France
Deep renovation mandates require modeled thermal bridging calculations that favor superinsulation materials in facade retrofit programs. CE marking harmonization pending across member states creates certification bottlenecks for residential applications. The Paris metropolitan area channels public procurement toward energy performance consultants with building physics simulation capabilities.
Poland
EU cohesion funds target deep energy renovation of communist-era housing stock, creating first-mover advantage for distributors with local installation partnerships. National building code divergence from unified EU standards complicates cross-border product adaptation. The Warsaw-Krakow corridor concentrates contractor retraining programs for fragile aerogel blanket handling protocols.
Europe Blanket Aerogel Market Competitive Landscape
US producers anchor one tier; Nordic specialists hold regional manufacturing proximity. The vendor base splits between scale-driven chemical conglomerates and focused aerogel technology developers. Three archetypes dominate: silica precursor integrated players, flexible format specialists, and regional fabrication licensees. Capacity expansion and strategic partnerships represent the dominant competitive vectors as participants secure feedstock access and installation network coverage.
Within the technology-specialist tier, Aspen Aerogels Inc. exemplifies flexible blanket format leadership, while Cabot Corporation anchors silica precursor supply chain positioning. Svenska Aerogel AB occupies a regional fabrication role with Nordic manufacturing proximity. These three represent distinct strategic positions: format innovation leadership, upstream raw material control, and geographic demand capture respectively.
| Leading Market Players |
|---|
| Cabot Corporation |
| Aspen Aerogels Inc. |
| Svenska Aerogel AB |
| Enersens Aerogel |
| Active Aerogels |
| Armacell International S.A. |
| BASF SE |
| Green Earth Aerogel Technologies |
| Airglass AB |
| Others |
Value Network & Pricing Analysis
North Sea LNG transport operators concentrate procurement power through project-specific volume contracts, anchoring a pricing model that stratifies across REACH-registered premium tiers, standard water-glass formulations, and economy mineral wool alternatives. This buyer archetype's thermal performance guarantees command premium positioning while F-Gas Regulation compliance costs compress margins in lower tiers.
Pricing Analysis
Volume concentrates in standard-tier water-glass formulations while margins accrue to REACH-registered premium grades with pre-validated nano-silica safety dossiers. Price differentiation rests on certification tier and fiber-reinforcement density, with composite aerogels commanding substantial premiums over pure silica matrices. Pricing pressure stems from tetraethyl orthosilicate feedstock volatility linked to construction chemical demand cycles. Chemical processing contractors in Germany's Rhine-Ruhr corridor exhibit lowest price sensitivity due to downtime cost structures, while Polish residential retrofit distributors face acute margin compression.
Supply Chain Analysis
CE marking and REACH registration requirements gate supplier participation, extending certification timelines for nano-scale silica constituents. Manufacturing concentrates in Germany, the Netherlands, and Sweden, with supercritical drying expertise clustering around legacy chemical engineering programs in the Rhine-Ruhr and Rotterdam-Antwerp corridors. Raw material dependencies center on sodium silicate, tetraethyl orthosilicate, and specialized fiber reinforcement substrates. Single-source vulnerability runs through silica precursor supply chains tethered to construction chemical demand fluctuations. Distribution runs through direct sales for large-scale oil and gas contracts, with regional distributors serving mid-scale construction retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH substance registration requirements and evolving CE marking fire-reaction classification standards erect substantial barrier-to-entry moats favoring incumbent players with pre-validated safety dossiers.
For Market Incumbents: Hedge against water-glass formulation margin erosion by securing captive sodium silicate supply through backward integration into construction chemical feedstock networks. Reinforce technology leadership in fiber-reinforced composite matrices to defend against emerging polymer-integrated aerogel entrants targeting high-vibration refinery applications. Prioritize certification investment in unified EU fire-reaction classification standards ahead of member state harmonization. For New Entrants and Emerging Players: Capture Poland's EU cohesion-funded residential retrofit wave through local installation partnerships and contractor retraining programs for fragile blanket handling protocols. Target chemical processing maintenance cycles in Germany's Rhine-Ruhr corridor with composite aerogel formats addressing durability limitations that exclude pure silica from high-vibration vessel insulation. Lead with energy performance consultant relationships rather than traditional insulation distributor channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic manufacturing specialists with proximity to pulp-and-paper retrofit demand and established ECHA registration dossiers in Sweden and Finland. Long-term viability across the projection horizon rests on supercritical drying technician pipelines and REACH compliance infrastructure rather than pure capacity scale. Monitor CE marking harmonization progress as the critical inflection signal for cross-border product adaptation cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursors | Captive sodium silicate supply insulates margin structures from construction chemical demand volatility. |
| REACH Pre-Registration Investment | Pre-validated nano-silica safety dossiers accelerate contractor specification cycles versus unregistered competitors. |
| Composite Aerogel R&D Partnership | Fiber-reinforced matrices open refinery applications previously closed to pure silica formulations. |
| Polish Installation Network Buildout | Local contractor certification captures EU cohesion-funded deep renovation procurement concentration. |
| Supercritical Drying Technician Pipeline | Specialized solvent extraction expertise constrains production scale-up outside established German and Dutch clusters. |
Research Methodology
Independent corroboration across primary interviews with refinery maintenance directors, energy performance consultants, insulation procurement leads, and ECHA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Green Deal implementation reports, ECHA substance registration databases, Cefic construction chemical trade data, and national building code harmonization trackers. Bottom-up project pipeline analysis triangulates against top-down macroeconomic scenario modeling across the analysis window.
Rate-of-change decomposition separates volume growth drivers from price evolution and mix-shift effects throughout the forecast period. Segmentation dimensions span product type tier, application regulatory intensity, end-user technical capability, and distribution channel customer scale. CAGRs derive from installed base replacement cycles, EU renovation mandate implementation pacing, and oil and gas maintenance schedule modeling. Industry-specific inputs include F-Gas Regulation phase-down timelines and REACH compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CE marking harmonization delays, silica precursor commodity cycles, and supercritical drying technician supply constraints. Forecasts reflect documented assumptions about regulatory implementation pacing and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Borophene Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Global Advanced Phase Change Materials Market