
 Europe Next Generation Anode Materials Market | 2026-2036
Europe Next Generation Anode Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Next Generation Anode Materials Market Foresight
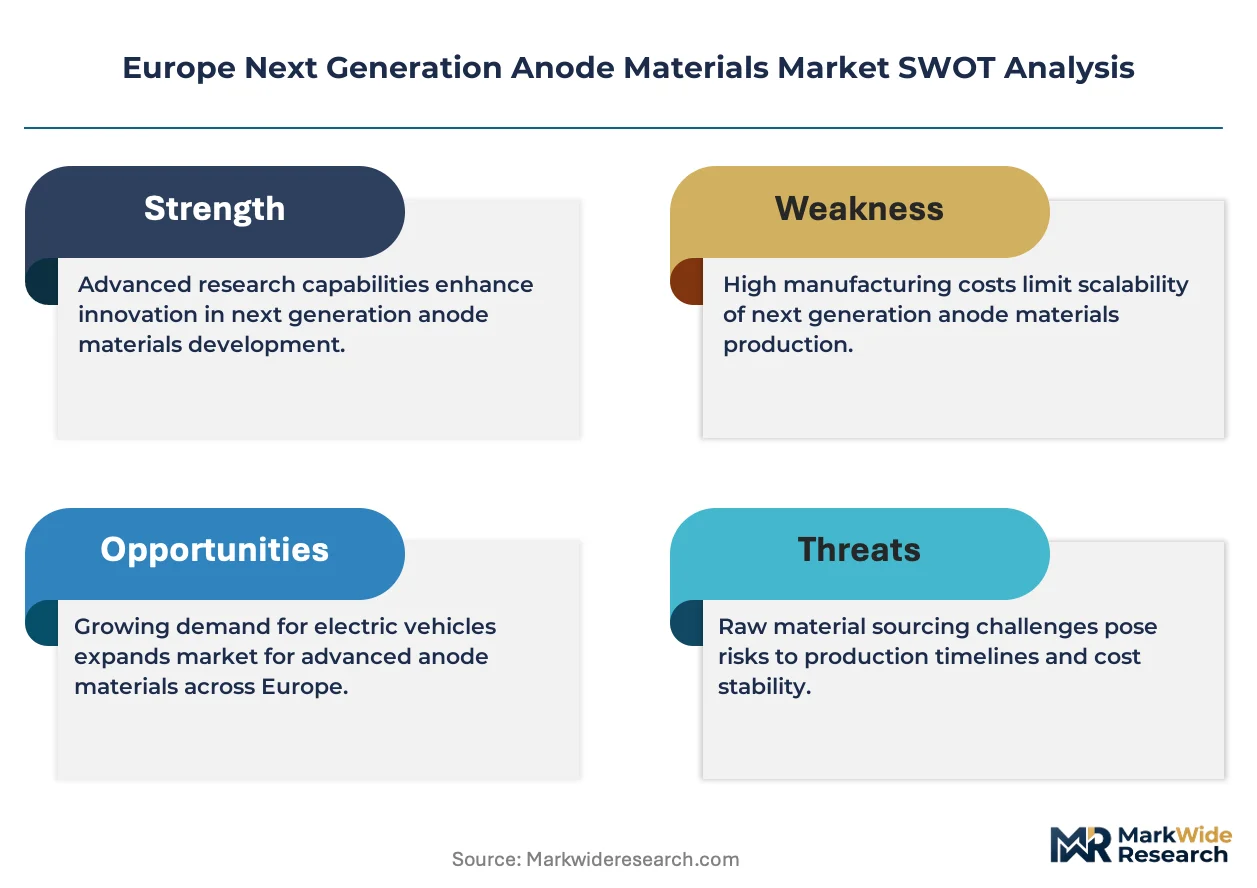
Performance-based material certification and cell qualification services are broadening what anode suppliers monetize beyond commodity powder. Talga Technologies Limited leverages vertical integration from Swedish graphite mines to coated active materials, controlling cost position through captive feedstock. Nexeon Limited specializes in silicon-composite architectures that reduce swelling failure modes in high-energy cells. Resonac Holdings Corporation sustains manufacturing scale across European coating facilities, anchoring supply security for automotive programs.
Europe next generation anode materials encompass engineered powders and composites that store lithium ions during battery discharge, with silicon-based variants achieving theoretical capacities near 4,200 mAh/g against graphite's 372 mAh/g limit. Their primary purpose is extending driving range in electric vehicle packs while maintaining cycle stability. Silicon material type captures the fastest expansion trajectory as automotive OEMs tolerate higher material costs for energy density gains. Solid-state technology segments attract disproportionate R&D allocation despite manufacturing immaturity, with lithium polymer occupying established consumer electronics niches where cycle life requirements remain moderate.
EMA's evolving battery material safety protocols and REACH chemical registration requirements are tightening purity thresholds for imported active materials, reshaping supplier qualification timelines. The EU Green Deal's critical raw materials act and forthcoming battery passport regulations from ECHA are mandating carbon footprint disclosure and recycled content minimums. Battery producers and automotive OEMs must monitor how CSRD sustainability reporting obligations cascade into anode procurement specifications before the next cell platform design cycles finalize.
Market Dynamics
Automotive OEMs in Germany and Scandinavia are forcing silicon-dominant anode formulations into cell qualification cycles faster than coating capacity can expand, compressing supplier margins while accelerating substitution away from graphite.
Growth Catalysts
- EU Green Deal battery mandates:Carbon footprint disclosure requirements and recycled content minimums are pulling high-capacity silicon composites into European EV supply chains ahead of 2030 platform deadlines.
- Silicon-composite architectures:These formulations achieve energy density thresholds that extend driving range, satisfying Stuttgart-to-Munich automotive corridor procurement specifications.
- Germany's automotive corridor:Cell producers stretching from Stuttgart to Munich are scaling silicon-dominant procurement volumes, concentrating demand pull in this manufacturing belt.
Market Restraints
- Silicon feedstock cost volatility:Metallurgical-grade silicon prices fluctuate with solar panel demand, squeezing anode producer margins when photovoltaic deployment accelerates.
- Coating capacity concentration:Active material coating facilities cluster in Germany and Poland, creating single-source vulnerability for automotive programs requiring localized supply.
- REACH chemical registration friction:ECHA's evolving purity thresholds for imported active materials extend supplier qualification timelines by 12-18 months.
Strategic Opportunities
- Nordic mining integration:Sweden's graphite deposits offer captive feedstock control for anode producers seeking to bypass Asian refined material dependence.
- Solid-state convergence:Silicon anode compatibility with lithium metal cathodes opens premium automotive segments where energy density commands price premiums.
- CSRD procurement cascades:Sustainability reporting obligations are rewriting anode specifications before next-generation cell platforms finalize, favoring early certified suppliers.
Industry Challenges
- Cell qualification bottlenecks:EMA safety protocols and OEM-specific validation cycles compress the window between material innovation and platform integration.
- Coating equipment capex intensity:CVD and ALD machinery for silicon-carbon interfaces requires capital deployment at scale before volume commitments materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Next Generation Anode Materials Market |
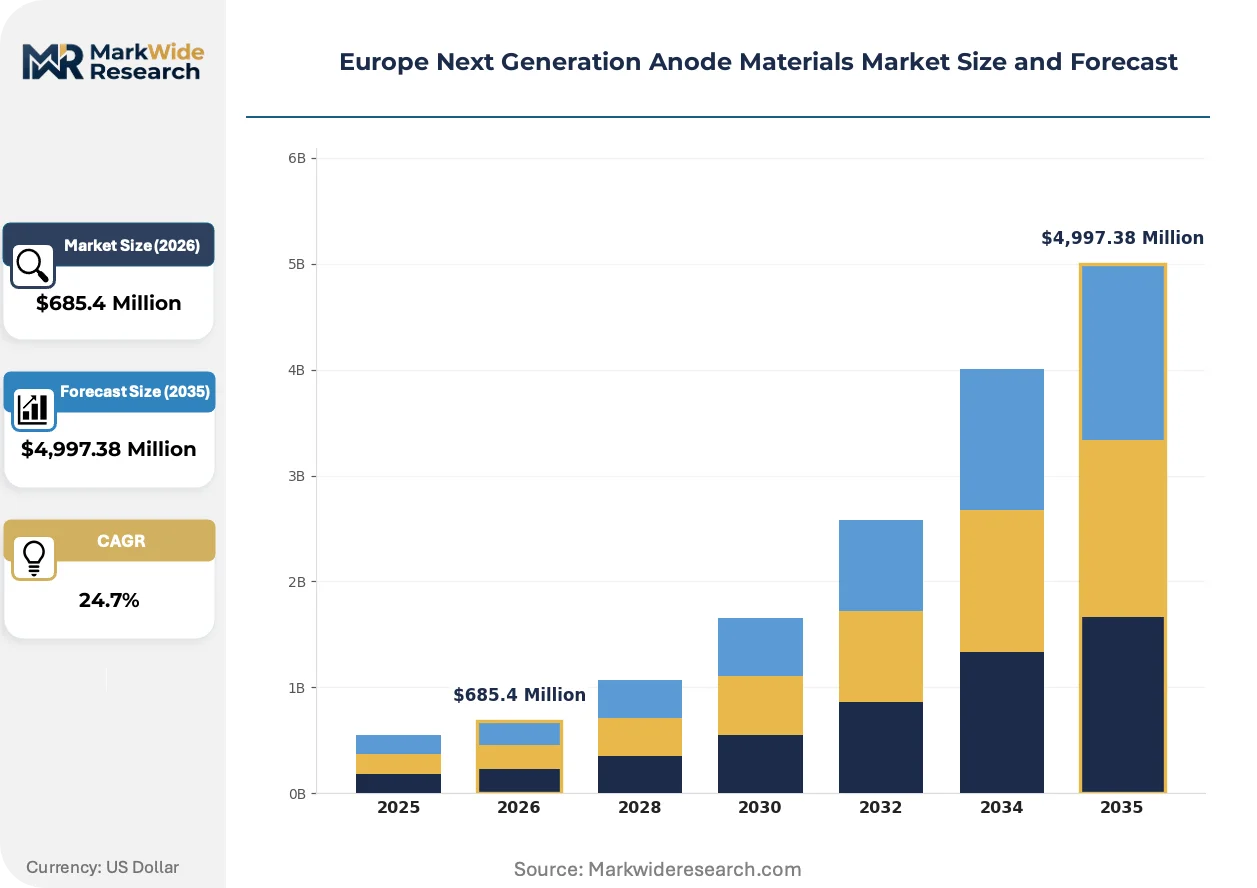
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,997.38 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium Titanate, Carbon Nanotubes Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Mobile Devices Technology: Li-Ion, Solid-State, Lithium Polymer, Na-Ion End User: Aerospace, Automotive OEMs, Electronics Manufacturers, Battery Producers |
| Companies Covered | SCT Europe Ltd, Resonac Holdings Corporation, Talga Technologies Limited, Vianode, Albemarle Corporation, Nexeon Limited, Novacium SAS, Leydenjar Technologies, JSR Micro NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Next Generation Anode Materials Market Shifts & Advancements
Silicon-dominant formulations are compressing the performance gap between laboratory demonstrations and automotive-grade cycling stability, forcing rapid adaptation across coating and cell assembly tiers.
Pre-lithiated silicon oxide composites are consolidating their position as the bridge technology between graphite baselines and pure silicon targets. Tier 1 cell producers in Germany's automotive corridor are adopting these materials at pilot scale ahead of 2027 platform locks. This consolidation is compressing the qualification timeline for next-generation architectures.
REACH chemical registration requirements are tightening purity thresholds for imported active materials, forcing suppliers to relocate refining steps inside European customs territory. ECHA's forthcoming battery passport regulations are mandating carbon footprint disclosure at the batch level. Automotive OEMs are responding by embedding sustainability auditors into supplier qualification teams.
Long-term offtake contracts are displacing spot market purchasing for silicon-dominant anodes. Cell producers are locking in volume commitments with coating specialists to secure allocation ahead of automotive platform ramp-ups. This shift is most visible in Germany, where Volkswagen and BMW cell ventures are negotiating five-year supply agreements with active material producers.
Europe Next Generation Anode Materials Market Segmentation
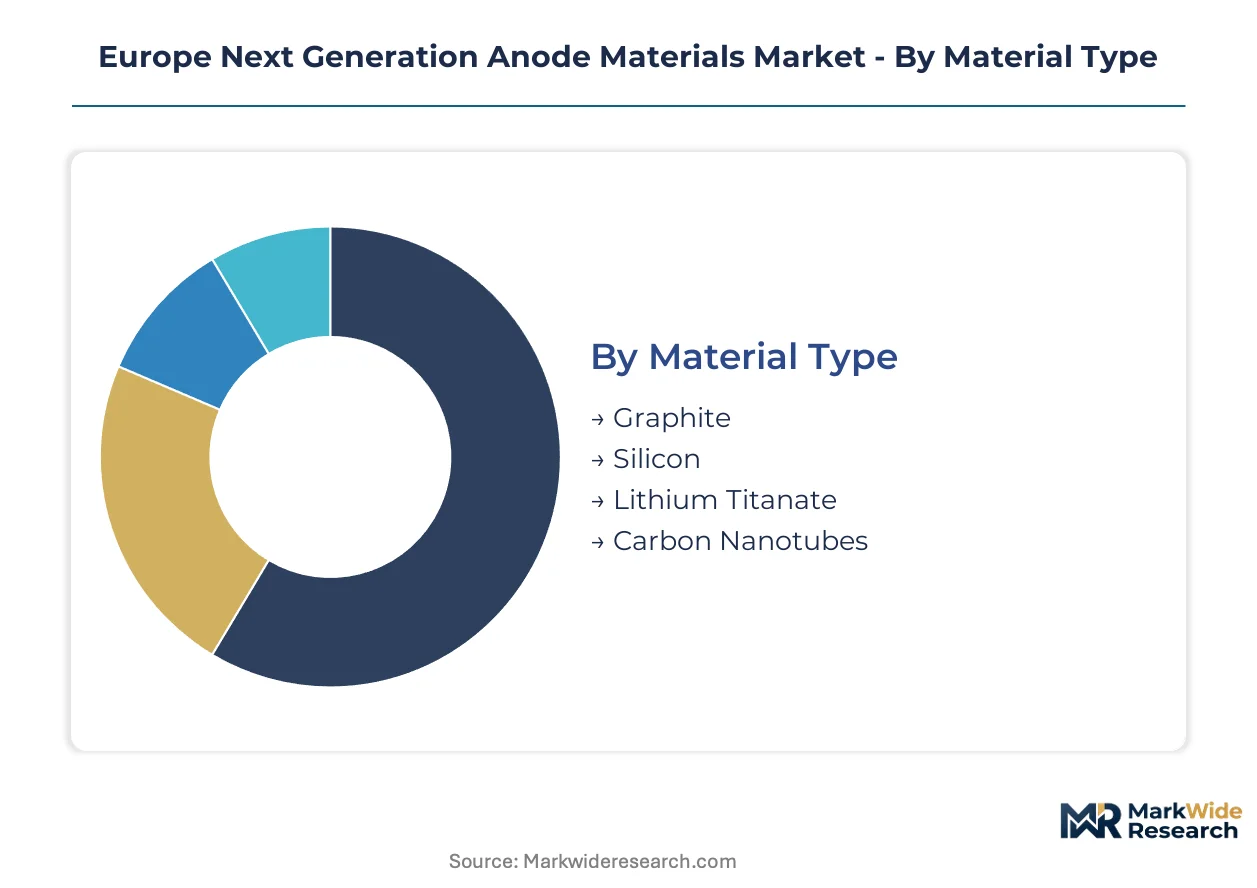
Europe's next generation anode materials market fragments across material chemistry, application intensity, and battery technology maturity. Procurement patterns diverge sharply between embedded automotive systems and standalone energy storage installations, reshaping supplier qualification requirements.
Material Type:
Silicon-dominant formulations operate as embedded performance layers within composite architectures, while graphite retains standalone baseline status in cost-sensitive applications.
- Silicon:Composite architectures achieve theoretical capacities near 4,200 mAh/g through engineered particle geometries. Cell producers across Germany's Stuttgart-to-Munich corridor are scaling procurement volumes for 2027 platform integrations, tolerating higher material costs for energy density gains that extend electric vehicle range.
- Graphite:Synthetic and natural variants remain the cost-optimized baseline for mid-range electric vehicle packs. Demand concentrates in Polish coating facilities serving budget automotive segments where cycle stability requirements moderate.
- Lithium Titanate:High-rate capability suits grid-scale frequency regulation applications requiring 10,000+ cycle lifespans.
- Carbon Nanotubes:Conductive additives for silicon-carbon interface stabilization in premium automotive cells.
Volume placements concentrate in Graphite; the faster expansion belongs to Silicon.
Application:
Automotive integration demands embedded material systems with decade-long validation cycles, whereas consumer electronics tolerates shorter-lived standalone configurations.
- Electric Vehicles:Pack-level energy density targets above 300 Wh/kg are forcing silicon-dominant anode adoption across German and Scandinavian automotive programs. EU Green Deal battery passport mandates are accelerating qualification timelines for high-capacity alternatives ahead of 2030 platform deadlines.
- Energy Storage Systems:Grid-scale installations prioritize cycle stability over energy density, favoring lithium titanate and graphite blends. Nordic utility procurement is concentrating demand in Sweden and Norway where renewable integration requires long-duration storage.
- Consumer Electronics:Smartphone and laptop producers specify moderate-capacity silicon oxide composites.
- Mobile Devices:Wearable applications drive demand for ultra-thin anode coatings with minimal swelling.
Procurement volume clusters in Electric Vehicles; Energy Storage Systems are climbing the fastest.
Technology:
Established liquid electrolyte systems accommodate incremental material upgrades, while solid-state architectures demand entirely reconstituted anode interfaces.
- Solid-State:Lithium metal anode compatibility positions silicon-carbon composites for premium automotive segments where energy density commands price premiums. Resonac Holdings Corporation and European coating specialists are allocating disproportionate R&D to sulfide and oxide electrolyte interfaces despite manufacturing immaturity.
- Li-Ion:Conventional liquid electrolyte cells dominate current production volumes across German cell ventures. Pre-lithiated silicon oxide composites are consolidating as the bridge technology between graphite baselines and pure silicon targets.
- Lithium Polymer:Pouch cell formats occupy established consumer electronics niches with moderate cycle life requirements.
- Na-Ion:Sodium-ion chemistry is gaining traction in stationary storage applications with silicon-doped hard carbon anodes.
Manufacturing scale favors Li-Ion; Solid-State exhibits the steepest expansion trajectory.
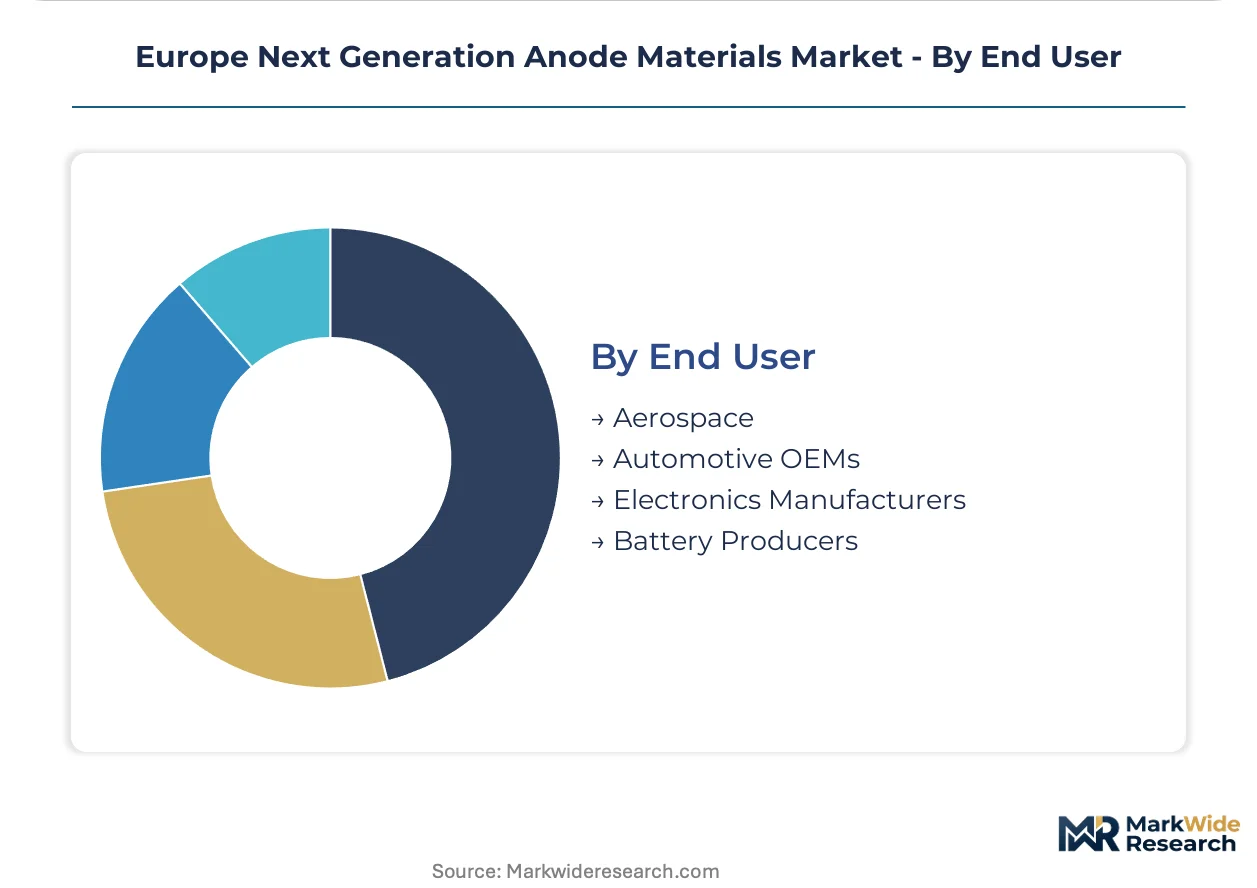
End User:
Battery producers and automotive OEMs impose distinct qualification regimes, with the former optimizing for coating throughput and the latter for pack-level integration.
- Automotive OEMs:Volkswagen, BMW, and Mercedes-Benz cell ventures are negotiating five-year offtake agreements with active material producers. Long-term contracts are displacing spot market purchasing as platform ramp-ups approach.
- Battery Producers:Northvolt and ACC are scaling silicon-dominant procurement faster than coating capacity can expand, compressing supplier margins while securing allocation.
- Electronics Manufacturers:Tier 1 consumer electronics brands specify moderate-performance silicon composites with shortened qualification cycles.
- Aerospace:Satellite and urban air mobility applications drive demand for ultra-high-energy density cells with minimal mass penalties.
Contract volume concentrates with Battery Producers; Aerospace is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's next generation anode materials production clusters in Germany and Scandinavia, while consumption spreads across the continent's automotive manufacturing belt. This geographic split creates supply chain tensions as coating capacity lags behind cell qualification demands.
Germany
Volkswagen and BMW cell ventures are locking in five-year offtake agreements with active material producers ahead of 2027 platform deadlines. KBA vehicle certification protocols are accelerating silicon-dominant anode qualification cycles for domestic EV production. The Stuttgart-to-Munich corridor concentrates coating facility investments, with Northvolt and ACC scaling procurement faster than local capacity expands.
Sweden
Northvolt's gigafactory program is pulling silicon-composite anode volumes into Nordic supply chains at unprecedented scale. EU Green Deal battery passport mandates are forcing carbon footprint disclosure at the batch level for all imported active materials. Västerbotten's graphite deposits offer captive feedstock control through Talga Technologies' vertical integration from mine to coated materials.
France
Automotive OEMs in the Paris-Saclay cluster are embedding sustainability auditors into supplier qualification teams under CSRD reporting obligations. ECHA's REACH chemical registration requirements are extending qualification timelines for imported anode materials by 12-18 months. The Hauts-de-France region hosts ACC's cell manufacturing, concentrating demand for high-capacity silicon formulations.
Poland
Budget automotive segments are sustaining graphite anode demand through coating facilities serving mid-range EV producers. EU critical raw materials act provisions are mandating recycled content minimums that reshape procurement specifications for imported materials. The Silesian industrial zone anchors synthetic graphite processing, though silicon-dominant alternatives are displacing volumes in premium segments.
Netherlands
Leydenjar Technologies and specialized coating ventures are attracting R&D investment for solid-state electrolyte interfaces despite manufacturing immaturity. EMA battery material safety protocols are tightening purity thresholds for active materials entering European customs territory. The Eindhoven-Brabant tech corridor concentrates pilot-scale silicon anode production for aerospace and urban air mobility applications.
Europe Next Generation Anode Materials Market Competitive Landscape
Top-tier vendors anchor automotive qualification programs, while mid-tier specialists compete on coating throughput and material certification speed. The vendor base stratifies across integrated miners, coating specialists, and composite architects. Three archetypes dominate: captive feedstock controllers, interface engineering specialists, and scale-driven chemical conglomerates. M&A activity targets coating capacity consolidation, while strategic partnerships lock in long-term offtake ahead of platform ramp-ups.
Within the captive feedstock tier, Talga Technologies Limited exemplifies backward integration from Swedish graphite deposits through coated active materials. Resonac Holdings Corporation anchors manufacturing scale across European coating facilities, securing supply security for automotive programs. Nexeon Limited occupies the composite architecture specialization, representing silicon-dominant formulation expertise for high-energy cell applications.
| Leading Market Players |
|---|
| SCT Europe Ltd |
| Resonac Holdings Corporation |
| Talga Technologies Limited |
| Vianode |
| Albemarle Corporation |
| Nexeon Limited |
| Novacium SAS |
| Leydenjar Technologies |
| JSR Micro NV |
| Others |
Supply & Pricing Matrix
Coating equipment specialists concentrated in Germany's Baden-Württemberg region command wage premiums that widen spreads between automotive-grade silicon anode pricing and commodity graphite baselines. Labor-cost differentials between Nordic mining-integrated producers and Asian-refined material importers stratify procurement tiers across the Stuttgart-to-Munich corridor.
Pricing Analysis
Margin tightening in silicon-dominant formulations reflects metallurgical-grade silicon feedstock volatility tied to solar panel demand cycles. Long-term offtake contracts are displacing spot market purchasing as cell producers lock in volume commitments ahead of automotive platform ramp-ups. Price differentiation hinges on carbon footprint certification tier under EU Green Deal battery passport mandates and coating throughput scale. Budget automotive segments in Poland exhibit highest price sensitivity, while German OEM cell ventures tolerate material cost premiums for energy density gains.
Supply Chain Analysis
Metallurgical-grade silicon feedstock rests on Norwegian and Chinese smelter output, with Swedish graphite deposits offering captive alternative for integrated producers. Active material coating capacity clusters in Germany and Poland, while precursor chemical synthesis concentrates in Belgium and the Netherlands. Single-source vulnerability pervades automotive programs dependent on localized CVD and ALD equipment operators. Distribution runs through Tier 1 cell ventures and OEM-backed joint ventures rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating capacity expansion timelines lag cell qualification demands by 18-24 months, propping material pricing power for qualified suppliers. This supply-constrained structure favors early movers with certified production assets.
For Market Incumbents: Deepen backward integration into Swedish graphite deposits or Nordic silicon feedstock streams to offset Asian refined material dependence. Expand coating throughput in Germany's automotive corridor ahead of 2027 platform locks. ECHA REACH registration friction and silicon feedstock cost volatility represent primary margin threats requiring captive supply hedging. For New Entrants and Emerging Players: Begin with solid-state electrolyte interface development for premium automotive segments where energy density commands price premiums. Target aerospace and urban air mobility applications in the Netherlands' Eindhoven-Brabant corridor with ultra-high-energy density specifications. Qualify through pilot-scale production partnerships with established cell ventures rather than direct OEM engagement. For Investors and Strategic Acquirers: The window for entry favors coating specialists with certified automotive qualification and scalable CVD/ALD equipment deployment. Long-term viability centers on five-to-ten-year offtake contract backlogs with Volkswagen, BMW, or Northvolt ventures. Watch for EMA safety protocol revisions as inflection indicators for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Feedstock | Talga Technologies' mine-to-coating model bypasses Asian refined material dependence under EU critical raw materials act. |
| Long-term Supply Agreement with OEM Cell Ventures | Five-year offtake contracts with Volkswagen and BMW ventures secure allocation ahead of platform ramp-ups. |
| Solid-State Electrolyte Interface R&D | Resonac Holdings and Leydenjar Technologies target premium automotive segments with lithium metal cathode compatibility. |
| Carbon Footprint Certification Investment | CSRD reporting obligations and ECHA battery passport mandates favor early certified suppliers in procurement specifications. |
| Coating Capacity Expansion in Germany | Northvolt and ACC procurement scaling outpaces local CVD and ALD equipment installation, compressing supplier margins. |
Research Methodology
Multi-period observation of cell qualification timelines, coating capacity utilization rates, and automotive platform lock dates anchored the trend analysis, supplemented by interviews with active material procurement directors at German cell ventures, coating equipment engineers in Baden-Württemberg, ECHA regulatory affairs specialists, and Nordic mining operations managers. Secondary validation drew from EU Green Deal implementation documents, EMA battery material safety protocols, REACH chemical registration databases, and customs trade data for graphite and silicon feedstock flows. Bottom-up volume estimates from individual coating facility outputs triangulated against top-down automotive production forecasts.
Segment-weighting across material type, application intensity, battery technology maturity, and end-user procurement regime structured the analytical framework. Silicon-dominant versus graphite baseline splits, electric vehicle pack energy density thresholds, and solid-state versus liquid electrolyte technology readiness levels defined the segmentation dimensions. CAGRs derived from fitted growth curves applied to qualified capacity expansion schedules and automotive platform adoption timelines. Industry-specific inputs included metallurgical-grade silicon price indices and ECHA regulatory friction estimates.
Feedstock cost volatility, coating equipment delivery delays, and EMA safety protocol revisions are the dominant revision risks to forecast outputs. Forecasts reflect documented assumptions about cell qualification cycle durations and automotive OEM platform lock schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Core Materials Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Graphene Market
Advanced Materials
Corundum Market
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
High-Purity Amorphous Boron Market