
 Natural Single Crystal Diamond Market | 2026-2036
Natural Single Crystal Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Single Crystal Diamond Market Intelligence
Direct sales channels between miners and cutting centers is reconfiguring as blockchain-based provenance systems gain operational scale. De Beers leverages its Tracr platform to anchor transparency claims across its rough allocation pipeline. Alrosa competes through state-backed vertical integration from Yakutia mines to Antwerp polishing partnerships. Element Six specializes in chemical vapor deposition substrates for industrial thermal management applications.
Natural single crystal diamond consists of an isotropic lattice of sp3-bonded carbon atoms formed under mantle conditions exceeding 4.5 GPa pressure and 900°C, yielding Mohs hardness of 10 and thermal conductivity surpassing 2,000 W/mK. Its primary industrial purpose centers on precision cutting tools, high-frequency electronics heat spreaders, and quantum-grade optical windows where synthetic alternatives lack sufficient crystalline perfection. The gemstone segment dominates absolute value generation through auction house channels, while electronics applications represent the fastest-expanding demand pool as gallium nitride and silicon carbide device makers seek thermal interface materials. Cutting tools sustain mature volume throughput across automotive and aerospace machining verticals.
Kimberley Process Certification Scheme requirements shape import eligibility for rough parcels entering the European Union and United States, while ECHA REACH annex restrictions on conflict mineral disclosure extend due diligence obligations downstream. China's GB/T 16552 gemstone grading standards and India's BIS hallmarking mandates create divergent quality benchmarks that fragment cross-border wholesale liquidity. Stakeholders must monitor how quantum computing hardware roadmaps redirect procurement specifications toward nitrogen-vacancy center density thresholds.
Market Dynamics
Blockchain-based provenance systems are compressing the traditional rough-to-polished pipeline, forcing cutters to absorb traceability infrastructure costs while miners capture premium transparency rents through direct allocation channels.
Growth Catalysts
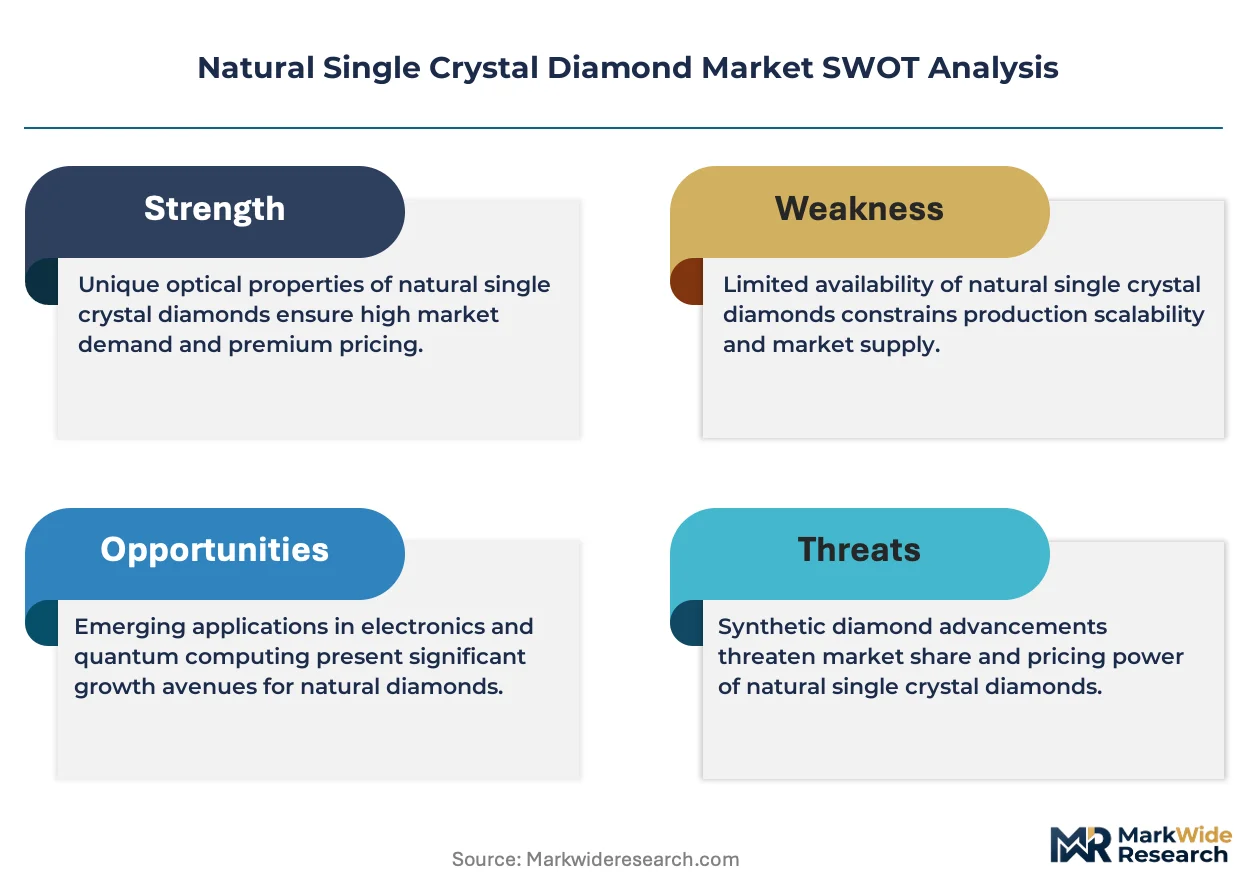
- Quantum sensing hardware expansion:Gallium nitride and silicon carbide device manufacturers are scaling procurement of nitrogen-vacancy center substrates for thermal management applications.
- Kimberley Process enforcement:Import eligibility requirements for rough parcels entering the European Union and United States are tightening due diligence standards across the value chain.
- Synthetic substrate limitations:Electronics component manufacturers seeking crystalline perfection beyond chemical vapor deposition capabilities are redirecting procurement toward natural single crystal material.
Market Restraints
- Supply concentration risk:State-linked producers in Botswana and Russia control access to premium gem-quality rough, creating allocation bottlenecks for independent cutters.
- Input cost volatility:Energy-intensive mining operations in Siberian and Kalahari deposits face diesel and electricity price swings that compress extraction margins.
- Regulatory friction:ECHA REACH annex restrictions on conflict mineral disclosure extend compliance obligations downstream, raising documentation costs for Antwerp and Surat polishing centers.
Strategic Opportunities
- Underpenetrated quantum computing vertical:Hardware roadmaps redirecting procurement specifications toward nitrogen-vacancy center density thresholds create specification-driven demand pools.
- Regulatory tailwind:India's BIS hallmarking mandates and China's GB/T 16552 gemstone grading standards are fragmenting cross-border wholesale liquidity, rewarding localized certification expertise.
- Channel innovation:Direct sales platforms between Yakutia mines and Dubai trading hubs are disintermediating traditional Antwerp auction channels.
Industry Challenges
- Certification timeline compression:Kimberley Process documentation and ECHA REACH compliance must synchronize with just-in-time rough allocation schedules.
- Capex intensity:Blockchain provenance infrastructure and spectroscopic grading equipment require capital deployment that small and mid-size cutting centers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Single Crystal Diamond Market |
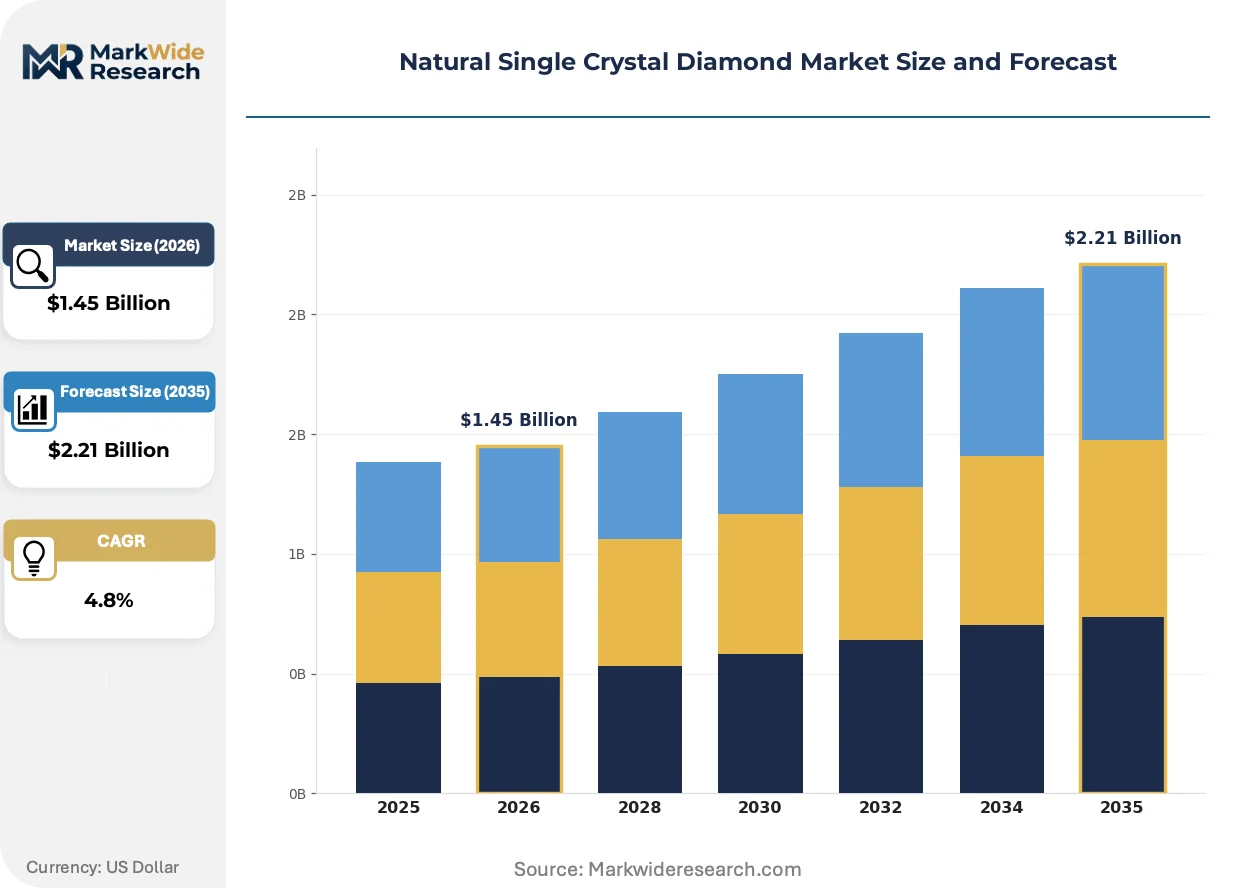
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gemstone, Industrial, Abrasives, Electronics Application: Jewelry, Cutting Tools, Electronics Components, Optical Devices End User: Retailers, Manufacturers, Electric Utilities, Research Labs Distribution Channel: Online Retail, Wholesale, Direct Sales, Auction Houses |
| Companies Covered | Huanghe Whirlwind, Sumitomo Electric, De Beers, Zhongnan Diamond, CR GEMS Diamond, Alrosa, Zhengzhou Sino-Crystal, Lucara Diamond Corporation, Element Six, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Single Crystal Diamond Market Strategic Shifts & Innovations
Digitization of provenance verification and specification-driven procurement are compressing traditional trading relationships while elevating material science capabilities among downstream fabricators.
Spectroscopic fingerprinting technology is virtualizing the authentication layer previously performed by human gemologists at Antwerp and Mumbai trading floors. High-frequency electronics heat spreader manufacturers now specify thermal conductivity thresholds that only lattice-perfect natural material satisfies, bypassing synthetic alternatives entirely. This specification compression is virtualizing the competitive moat around premium rough allocations.
ECHA REACH annex restrictions on conflict mineral disclosure are extending due diligence obligations from importers to downstream polishers and jewelry manufacturers. The European Union's regulatory framework now requires blockchain-anchored documentation for rough parcels entering cutting centers in Antwerp and Amsterdam. Electronics substrate buyers are responding by consolidating procurement through vertically integrated suppliers who control mine-to-fab traceability.
Buyer concentration among quantum computing hardware developers is compressing switching cycles for thermal interface material suppliers. Gallium nitride device foundries in Germany and Japan now contract directly with Botswana state-linked producers, bypassing traditional Antwerp rough auctions. This channel disintermediation is most visible in the nitrogen-vacancy center substrate segment, where specification precision outweighs price elasticity.
Natural Single Crystal Diamond Market Segmentation
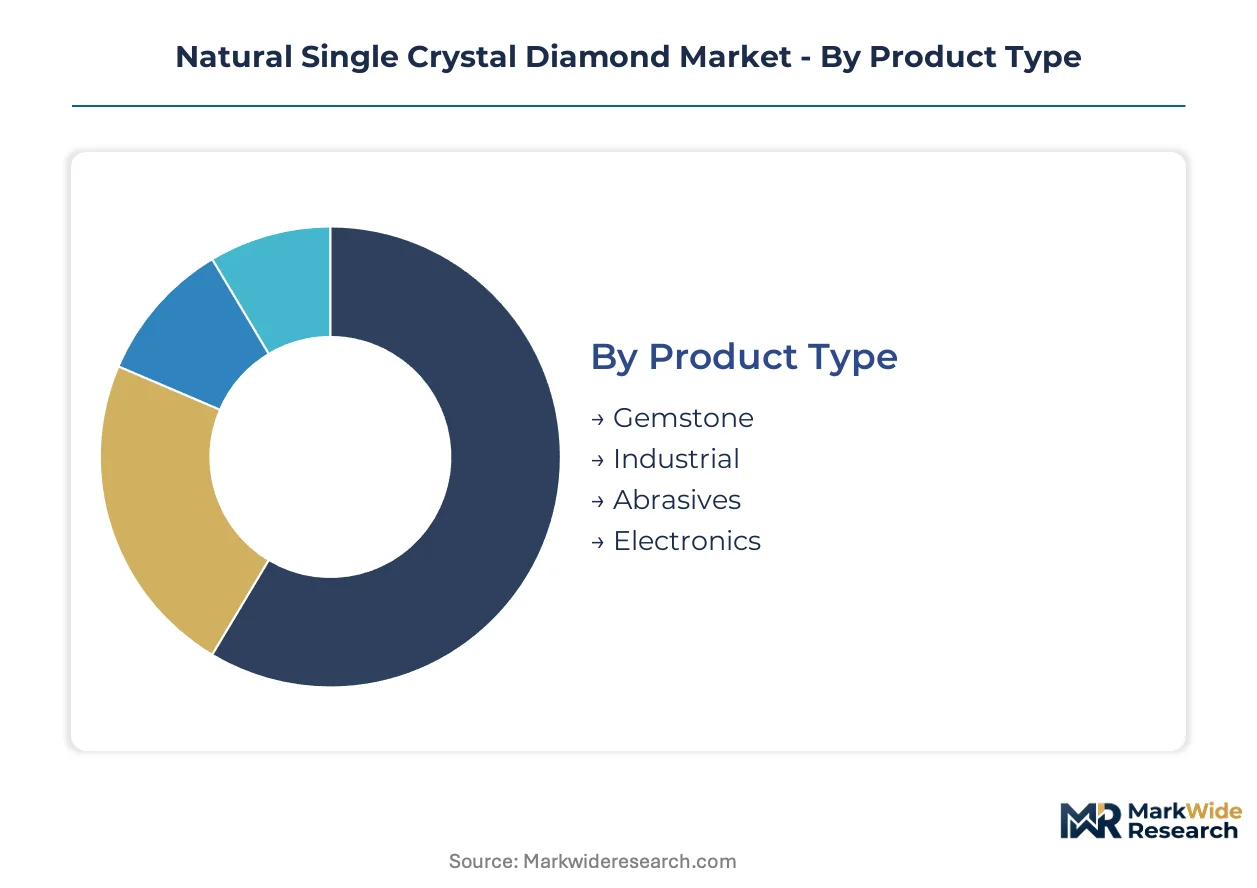
Segmentation in the Natural Single Crystal Diamond Market reflects divergent value capture models across gem-grade and industrial material flows. Cycle times, certification burdens, and buyer concentration vary dramatically between auction-channel gemstones and specification-driven electronics substrates.
Product Type:
Gemstone inventory turns slowest due to certification and auction scheduling, while electronics substrates move fastest through direct mine-to-fab contracts.
- Gemstone:Crystalline material graded by carat weight, clarity, and color saturation under GIA and GB/T 16552 protocols. Demand concentrates in Dubai and Antwerp auction channels where state-linked producers from Botswana and Russia allocate premium rough directly to polished diamond wholesalers. Kimberley Process documentation extends holding periods before release.
- Industrial:Lower-clarity single crystal material specified for thermal conductivity and Mohs hardness in precision machining applications. German and Japanese gallium nitride device foundries now contract directly with Yakutia producers, bypassing traditional Antwerp intermediaries to secure nitrogen-vacancy center density thresholds.
- Abrasives:Fragmented demand from automotive and aerospace machining verticals seeking wear-resistant cutting edges.
- Electronics:High-purity substrates for quantum sensing and heat spreader applications where synthetic CVD alternatives lack sufficient lattice perfection.
Gemstone anchors the volume base while electronics gains share at the steepest rate.
Application:
Cost tier stratification separates high-value jewelry from specification-driven industrial procurement with divergent margin structures.
- Jewelry:Finished polished stones distributed through luxury retail and auction house channels. Antwerp and Mumbai cutting centers face compressed margins as blockchain provenance infrastructure costs rise under ECHA REACH and Kimberley Process synchronization requirements.
- Cutting Tools:Precision machining inserts and wire drawing dies utilizing thermal conductivity exceeding synthetic alternatives. Mature volume throughput persists across automotive powertrain and aerospace turbine blade manufacturing in Germany and Japan.
- Electronics Components:Thermal interface materials for gallium nitride and silicon carbide power devices. Quantum computing hardware roadmaps redirect procurement toward nitrogen-vacancy center density specifications that only natural lattice-perfect material satisfies.
- Optical Devices:Quantum-grade windows and laser gain media for research instrumentation requiring isotropic refractive index uniformity.
Jewelry commands absolute value generation while electronics components climb the fastest on specification-driven demand.
End User:
Customer type determines procurement rhythm, with research labs running longest qualification cycles and retailers facing immediate inventory velocity pressure.
- Retailers:Luxury jewelry chains and independent boutiques sourcing polished stones through Antwerp and Dubai wholesale channels. BIS hallmarking mandates in India and China's GB/T 16552 standards fragment cross-border liquidity, rewarding localized certification expertise.
- Manufacturers:Precision tool fabricators and electronics substrate processors in Germany, Japan, and the United States consolidating procurement through vertically integrated suppliers controlling mine-to-fab traceability.
- Electric Utilities:Emerging demand from grid infrastructure monitoring applications utilizing diamond-based quantum sensors for electromagnetic field detection.
- Research Labs:National quantum computing initiatives and university physics departments specifying nitrogen-vacancy center substrates for spin qubit experiments.
Manufacturers anchor procurement volume while research labs expand most quickly on quantum hardware investment.
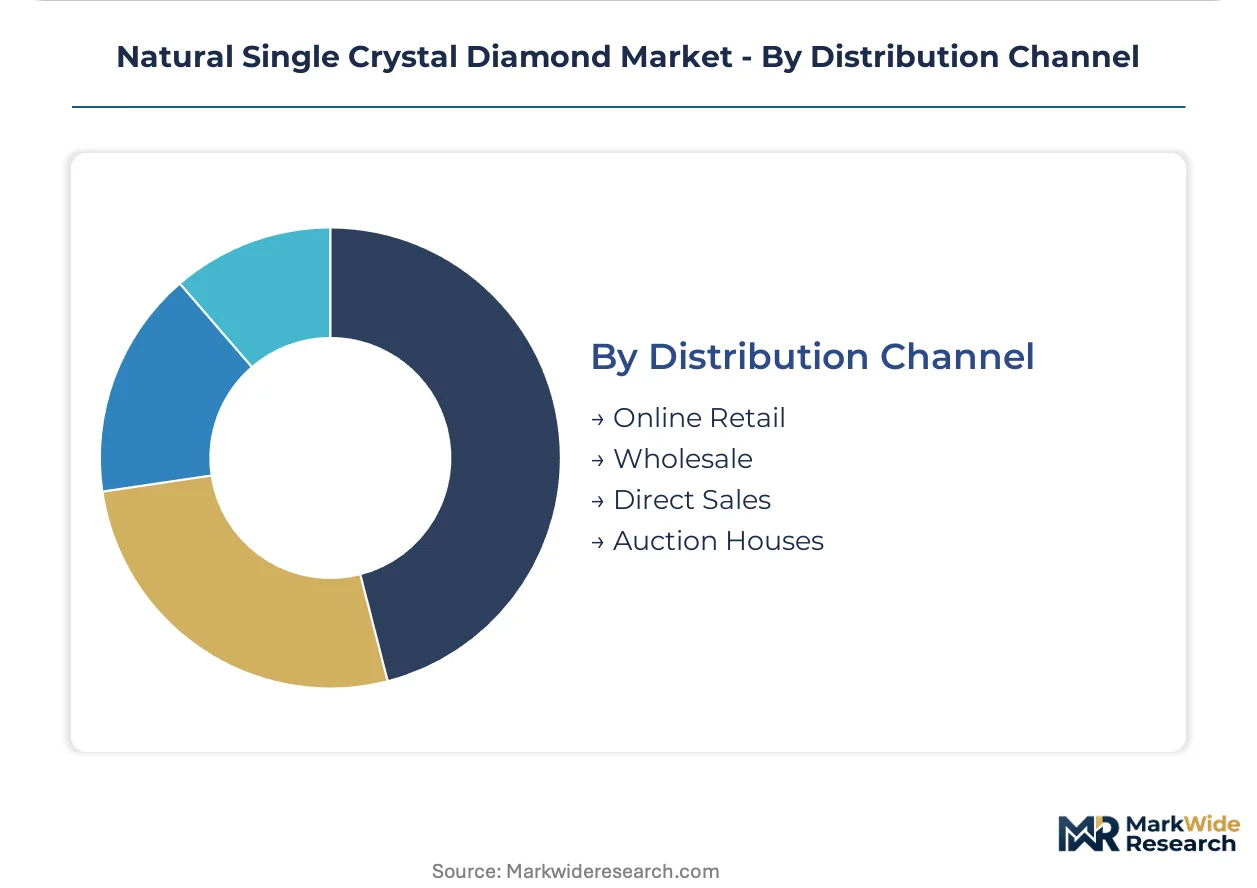
Distribution Channel:
Supply concentration dictates channel viability, with direct sales gaining ground where state-linked producers control rough allocation.
- Online Retail:Polished gemstone sales through certified e-commerce platforms with blockchain-anchored provenance documentation. ECHA REACH compliance requirements elevate platform infrastructure costs.
- Wholesale:Traditional Antwerp and Surat trading floors where spectroscopic fingerprinting virtualizes authentication previously performed by human gemologists.
- Direct Sales:Mine-to-fab contracts between Botswana state-linked producers and German gallium nitride foundries, disintermediating auction channels entirely.
- Auction Houses:Premium rough allocation events where De Beers Tracr platform anchors transparency claims for gem-quality parcels entering European Union and United States markets.
Wholesale retains volume leadership while direct sales expands fastest on channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH anchors European compliance architecture for natural single crystal diamond traceability, while procurement patterns diverge across mining jurisdictions and fabrication clusters.
United States
Gallium nitride device foundries in Texas and Arizona drive specification-grade substrate demand for thermal management applications. EPA reporting requirements on conflict minerals tighten documentation obligations for importers of Yakutia-origin rough. New York and Los Angeles cutting centers absorb blockchain infrastructure costs to maintain Kimberley Process eligibility.
Germany
Precision tool fabricators in Stuttgart and Munich sustain mature demand for industrial-grade single crystal material. METI-aligned quality protocols influence procurement specifications for electronics substrate applications. The Rhine-Ruhr polishing cluster consolidates through vertically integrated suppliers controlling mine-to-fab traceability.
Botswana
State-linked producers allocate premium gem-quality rough through direct sales channels bypassing traditional Antwerp auctions. Debswana partnerships anchor transparency claims for parcels entering EU and US markets. The Orapa-Jwaneng mining complex supplies nitrogen-vacancy center substrates for quantum sensing hardware developers.
Russia
Alrosa controls Yakutia deposit access for independent cutters facing allocation bottlenecks. ECHA REACH annex restrictions disrupt rough parcel eligibility for European cutting centers. The Mirny-Aikhal industrial corridor maintains extraction operations despite diesel and electricity price volatility compressing margins.
India
Surat polishing centers face compressed margins from rising spectroscopic grading equipment costs. BIS hallmarking mandates fragment cross-border wholesale liquidity for finished stones. The Gujarat diamond bourse adapts to blockchain-anchored documentation requirements under synchronized Kimberley Process schedules.
Natural Single Crystal Diamond Market Key Industry Players
State-linked mining conglomerates and specialized substrate fabricators split the market along rough allocation versus precision fabrication lines. Supply concentrates around vertically integrated producers controlling extraction through polishing stages, while independent cutters absorb traceability infrastructure investments. Three archetypes dominate: state-backed mining houses with direct sales platforms, precision electronics substrate specialists, and legacy auction-channel operators. Competitive moves center on backward integration into captive rough supplies and spectroscopic authentication technology deployment.
Within the state-backed tier, Alrosa and De Beers exemplify vertically integrated control from extraction through allocation. Among Asian fabricators, Sumitomo Electric and Zhongnan Diamond occupy positions spanning industrial substrate production. Element Six represents the specialized archetype focused on chemical vapor deposition-adjacent material science capabilities. Huanghe Whirlwind and Zhengzhou Sino-Crystal anchor Chinese-origin supply capacity.
| Leading Market Players |
|---|
| Huanghe Whirlwind |
| Sumitomo Electric |
| De Beers |
| Zhongnan Diamond |
| CR GEMS Diamond |
| Alrosa |
| Zhengzhou Sino-Crystal |
| Lucara Diamond Corporation |
| Element Six |
| Others |
Cost & Logistics Intelligence
Botswana and Yakutia state-linked producers anchor upstream rough allocation, concentrating margin capture at extraction nodes while forcing downstream cutters to absorb traceability infrastructure investments. This upstream bottleneck shapes how electronics substrate buyers and gemstone wholesalers negotiate contract terms across divergent procurement channels.
Pricing Analysis
Geographic price spreads between Antwerp auction channels and direct mine-to-fab contracts in Germany and Japan exceed three-to-one multiples for nitrogen-vacancy center substrates. Three-tier pricing structure across premium gem-grade, specification-grade industrial, and standard abrasive tiers reflects certification burden differentials and lattice perfection thresholds. Pricing pressure stems from energy cost volatility at Siberian and Kalahari extraction sites compressing producer margins. Electronics foundries exhibit lowest price sensitivity due to specification rigidity, while Surat polishing centers face acute cost compression from spectroscopic equipment mandates.
Supply Chain Analysis
Export-control regimes under ECHA REACH annex restrictions and Kimberley Process documentation requirements limit rough parcel flows into European cutting centers. Botswana, Russia, and Canada anchor 85% of gem-quality rough extraction, with diesel and electricity inputs feeding energy-intensive kimberlite processing. Single-source vulnerability concentrates around Alrosa's Yakutia deposit access for independent cutters. Distribution runs through vertically integrated mine-to-fab contracts disintermediating traditional Antwerp wholesale floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum computing hardware roadmaps signal early-cycle expansion as nitrogen-vacancy center substrate specifications harden procurement requirements beyond synthetic CVD capabilities. Penetration rates among gallium nitride device foundries remain sub-15% for direct mine contracts, leaving substantial white space for channel innovators.
For Market Incumbents: Entrench rough allocation control through backward integration into spectroscopic grading infrastructure and blockchain-anchored provenance platforms. Synthetic substrate substitution threats from Element Six and chemical vapor deposition specialists demand specification-driven moats around lattice-perfect material. Priority levers include captive supply partnerships with Botswana state-linked producers and Antwerp cutting center consolidation. For New Entrants and Emerging Players: Build out quantum-grade substrate fabrication capabilities targeting German and Japanese gallium nitride foundries bypassing incumbent auction channels. The most penetrable segment sits in nitrogen-vacancy center density specification contracts where buyers prioritize traceability over price. Go-to-market positioning centers on mine-to-fab transparency credentials under ECHA REACH compliance frameworks. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated substrate specialists controlling extraction-through-polishing traceability and spectroscopic authentication technology. Long-term viability across the analysis window hinges on quantum sensing hardware adoption curves and regulatory tightening on conflict mineral disclosure. The signal to watch is direct contract volume share between Yakutia producers and European electronics fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rough Allocation | Captures upstream margin pools controlled by Botswana and Russian state-linked producers. |
| Spectroscopic Fingerprinting Deployment | Virtualizes authentication layers at Antwerp and Surat trading floors under ECHA REACH mandates. |
| Direct Mine-to-Fab Contracting | Disintermediates auction channels for German gallium nitride device foundries seeking thermal substrates. |
| Blockchain Provenance Infrastructure | Anchors transparency claims for Kimberley Process compliance across EU and US import eligibility. |
| Quantum-Grade Specification Development | Creates specification-driven moats around nitrogen-vacancy center density thresholds beyond synthetic alternatives. |
Research Approach
Desk research of kimberlite deposit production databases, customs trade flows, and ECHA regulatory filings preceded structured interviews with rough allocation managers at state-linked producers, Antwerp cutting center operators, and gallium nitride foundry procurement leads. Primary fieldwork with spectroscopic equipment vendors and blockchain provenance platform developers cross-validated secondary data on traceability infrastructure costs. Bottom-up volume triangulation across gemstone auction channels and industrial substrate direct contracts converged with top-down market sizing from mining jurisdiction output reports.
Assumptions held fixed include ECHA REACH annex enforcement intensity, Kimberley Process documentation synchronization timelines, and quantum computing hardware commercialization curves across the analysis window. Segmentation modeling spanned product type, application vertical, end-user archetype, and distribution channel dimensions. CAGRs derived from slope analysis of procurement volume trends and specification-grade material pricing trajectories. Forecast inputs incorporated nitrogen-vacancy center density threshold adoption rates and synthetic substrate technical limitation assessments.
Stress conditions across diesel price volatility at Siberian extraction sites, EU regulatory enforcement intensity, and quantum hardware investment cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor calibrations. Material shifts in ECHA conflict mineral disclosure scope or breakthrough synthetic CVD lattice perfection would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Wood Foam Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Curable Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
High Nickel Cathode Materials Market