
 Global Viral Inactivation Market | 2026-2036
Global Viral Inactivation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Viral Inactivation Market Foresight
Multi-source procurement for viral inactivation services is consolidating as large biopharmaceutical sponsors reduce supplier audits and qualification burdens. Merck KGaA leverages its chromatography and filtration portfolio to anchor downstream bioprocessing contracts across North American and European manufacturing sites. Charles River Laboratories competes through integrated testing-to-clearance workflows that combine bioanalytical assays with dedicated viral clearance studies. Sartorius AG specializes in single-use viral inactivation systems that reduce cross-contamination risk in multi-product facilities.
Viral inactivation encompasses physicochemical and biological methods designed to eliminate or neutralize infectious viral particles in therapeutic products, raw materials, and process intermediates, typically achieving log reduction values exceeding four orders of magnitude through heat, ultraviolet irradiation, solvent-detergent treatment, or nanofiltration. The primary industrial purpose is to ensure patient safety in biologics manufacturing while satisfying regulatory requirements for demonstrating adequate clearance of known and adventitious agents. Chemical disinfectants and ultraviolet radiation represent mature, high-volume technology segments where standardization has compressed margins, whereas pulsed electric field systems occupy an emerging niche with premium pricing in food safety and water treatment applications. Vaccine manufacturing and biopharmaceuticals command the largest application revenue pools due to mandatory viral clearance validation for licensure, while blood products remain a stable, regulation-intensive segment with long-term contract structures.
The FDA and EMA enforce viral safety guidelines through ICH Q5A and region-specific guidance documents that mandate validated clearance studies for biologics license applications, directly shaping R&D spending and facility design requirements. WHO prequalification standards for vaccines exported to low-income countries add a second compliance layer that influences technology selection and documentation intensity. Stakeholders must monitor evolving regulatory expectations for continuous processing validation as biomanufacturing shifts from batch to integrated continuous bioprocessing platforms.
Market Dynamics
Orthogonal viral clearance validation has become the binding constraint on biologics facility design, as sponsors must demonstrate redundant inactivation pathways to satisfy FDA and EMA licensure requirements for cell and gene therapy products.
Growth Catalysts
- ICH Q5A Harmonization:The FDA and EMA's aligned viral safety guidelines eliminate redundant validation studies, accelerating multi-region biologics submissions and expanding contract manufacturing demand.
- Cell Therapy Manufacturing Scale-Up:Autologous and allogeneic cell therapy producers require dedicated viral clearance suites, creating specialized equipment and service demand in Boston, Basel, and Singapore manufacturing clusters.
- Continuous Bioprocessing Adoption:Integrated continuous manufacturing platforms demand real-time viral inactivation monitoring, pulling investment into inline ultraviolet and nanofiltration systems.
Market Restraints
- Specialized Stainless Steel Fabrication Bottlenecks:Vessel and piping fabricators for heat inactivation systems concentrate in northern Italy and southern Germany, creating 12-18 month equipment delivery timelines.
- High-Purity Solvent-Detergent Input Dependence:Triton X-100 and sodium cholate supply chains originate from three chemical manufacturers, exposing biopharmaceutical sponsors to raw material qualification delays.
- Facility Retrofit Capital Intensity:Existing multi-product biologics plants require segregated viral clearance zones with dedicated HVAC and waste handling, consuming 25-35% of facility expansion budgets.
Strategic Opportunities
- India Biologics Manufacturing Emergence:CDSCO's streamlined biosimilar approval pathway and government production-linked incentives attract viral clearance service providers to Hyderabad and Bengaluru.
- Pulsed Electric Field Food Safety Extension:Cold plasma and pulsed electric field systems validated for beverage and prepared food viral inactivation command premium pricing in Japanese and Australian export markets.
- Single-Use Technology Convergence:Integration of disposable bioreactors with gamma-irradiated viral inactivation assemblies eliminates cleaning validation burdens in clinical-stage manufacturing.
Industry Challenges
- Viral Clearance Study Design Expertise Scarcity:Bioanalytical scientists capable of designing valid spiking studies with model viruses remain concentrated at Charles River, Merck, and academic centers, constraining sponsor capacity expansion.
- Legacy Batch System Integration Complexity:Retrofitting continuous viral inactivation skids into validated batch downstream trains requires extensive process analytical technology implementation and regulatory resubmission.
- Adventitious Agent Testing Backlogs:Next-generation sequencing for novel viral detection creates 8-12 week analytical delays, compressing manufacturing campaign schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Viral Inactivation Market |
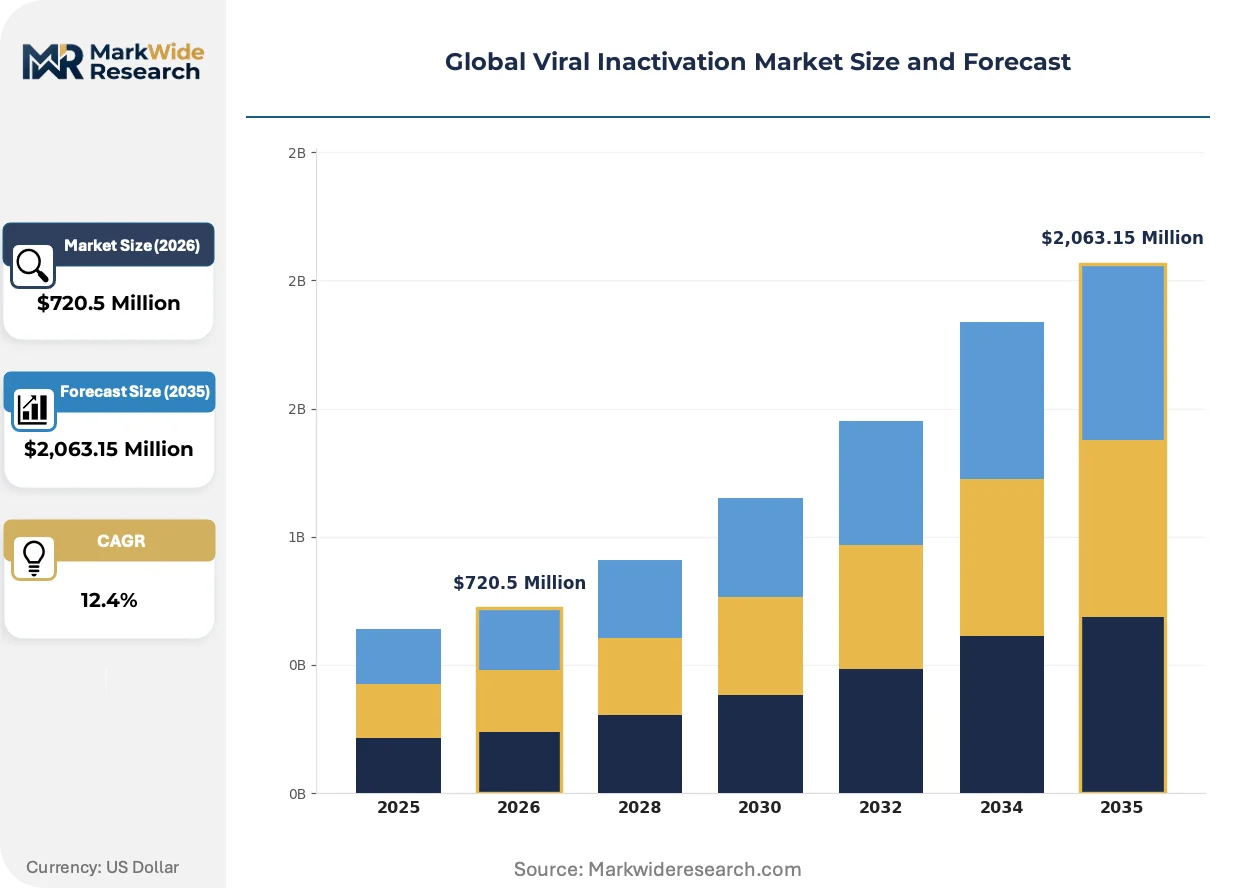
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $2,063.15 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Heat Treatment, Ultraviolet Radiation, Chemical Disinfectants, Pulsed Electric Field, High Pressure Processing Application: Blood Products, Biopharmaceuticals, Water Treatment, Food Safety, Vaccine Manufacturing End User: Diagnostic Laboratories, Biotech Firms, Pharmaceutical Manufacturers, Water Utilities, Food Processing Plants Deployment: Batch Processing, Continuous Flow, In-Process Integration, Standalone Systems, Embedded Solutions |
| Companies Covered | Merck KGaA, Rad Source Technologies, Charles River Laboratories, Texcell, Sartorius AG, Clean Cells, Parker Hannifin Corp, SGS SA, Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Viral Inactivation Market Shifts & Advancements
Process analytical technology and disposable manufacturing architectures are compressing viral clearance validation timelines from months to weeks, enabling just-in-release biologics manufacturing.
Single-use nanofiltration assemblies with pre-validated viral retention ratings are consolidating downstream bioprocessing workflows. Gene therapy manufacturers in North Carolina and Massachusetts have adopted these systems to eliminate steam-in-place validation cycles. The technology is consolidating equipment vendor margins while accelerating facility changeover between product campaigns.
The EMA's updated guideline on virus safety evaluation for biotechnological products now mandates next-generation sequencing for adventitious agent detection in addition to traditional in vitro and in vivo assays. European biologics sponsors must redesign viral clearance study protocols to incorporate orthogonal nucleic acid testing. Cell therapy developers in Basel and Leiden face 6-9 month protocol amendment timelines to satisfy the expanded documentation requirements.
Biopharmaceutical sponsors are unbundling viral clearance studies from full-service contract manufacturing agreements, establishing direct relationships with specialized testing laboratories. Large molecule developers in South San Francisco and Cambridge now contract viral validation separately from drug substance production, compressing overall program timelines by 4-6 months. This disintermediation is most pronounced among mid-cap biotechs with internal downstream processing capabilities but limited bioanalytical infrastructure.
Global Viral Inactivation Market Segmentation
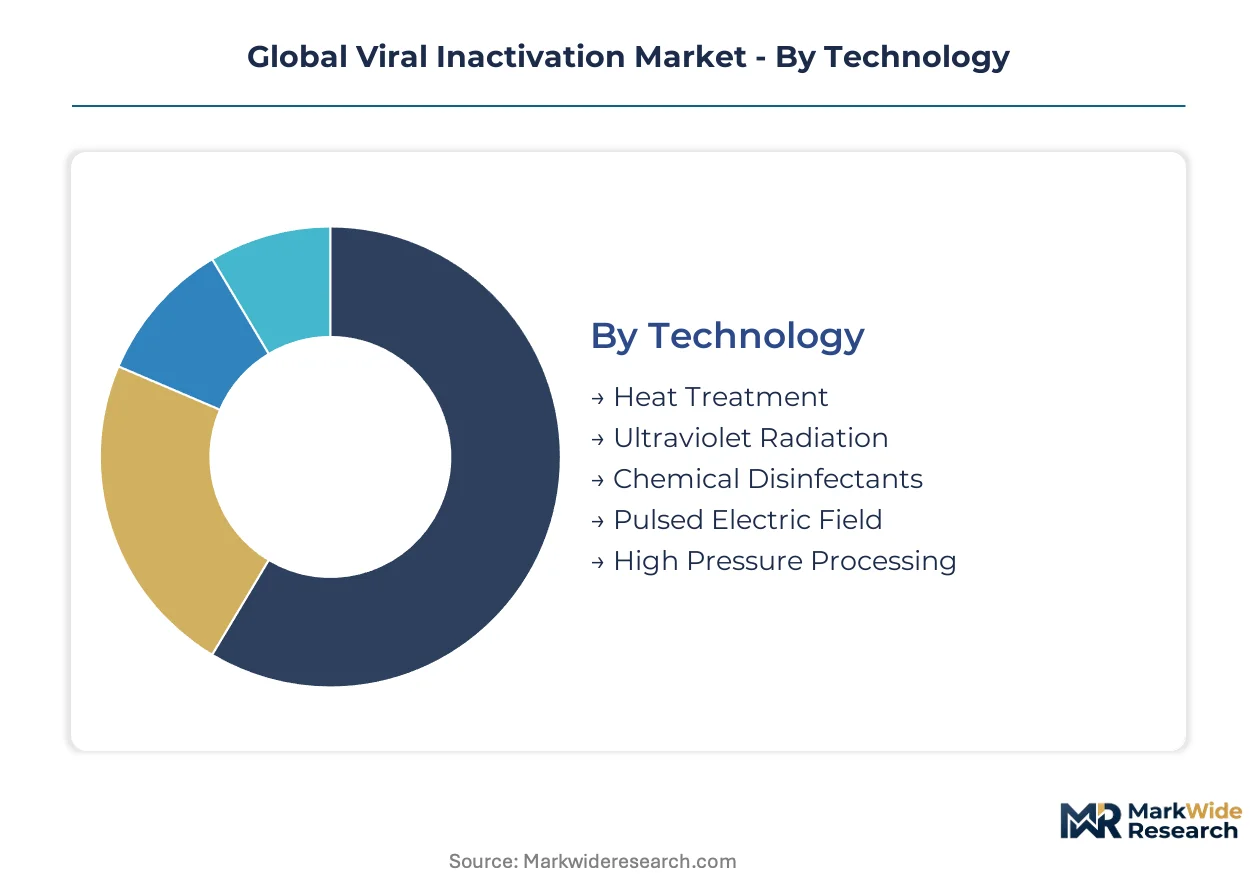
Viral inactivation technologies serve divergent compliance regimes and manufacturing architectures across biopharmaceutical, food safety, and water treatment verticals. Segmentation reveals how equipment specifications, validation protocols, and procurement patterns cluster around end-use risk tolerance and regulatory scrutiny intensity.
Technology:
Biopharmaceutical sponsors select thermal, chemical, or physical modalities based on product stability constraints and orthogonal clearance requirements mandated by FDA and EMA.
- Heat Treatment:Thermal inactivation systems operate at 60°C for extended hold periods to denature viral envelope proteins without compromising protein therapeutic integrity. Vaccine manufacturers in the United States and Germany deploy validated heat treatment skids as primary clearance steps for live-attenuated and subunit products. Volume sits with Heat Treatment; growth tilts toward Pulsed Electric Field.
- Ultraviolet Radiation:UV-C systems at 254 nm wavelength disrupt viral nucleic acid replication through pyrimidine dimer formation, achieving four-log reduction in continuous flow configurations. Water utilities in Australia and Singapore specify medium-pressure UV reactors for municipal drinking water viral safety compliance under WHO guidelines. Ultraviolet Radiation commands installed base across municipal infrastructure; Pulsed Electric Field climbs the fastest in premium food safety applications.
- Chemical Disinfectants:Solvent-detergent protocols using Triton X-100 and sodium cholate dissolve lipid envelopes in enveloped viruses across blood plasma derivatives.
- Pulsed Electric Field:High-voltage electric pulses permeabilize viral membranes in cold-processed beverages and prepared foods without thermal degradation.
- High Pressure Processing:Isostatic pressures above 300 MPa disrupt viral capsid assembly in high-value packaged foods and juices.
Heat Treatment and Ultraviolet Radiation dominate current procurement volumes; Pulsed Electric Field gains share fastest among clean-label food processors.
Application:
Regulatory filing requirements and patient exposure risk determine validation depth and technology selection across therapeutic and non-therapeutic domains.
- Biopharmaceuticals:Recombinant protein and monoclonal antibody manufacturing demands dual orthogonal viral clearance steps per ICH Q5A, typically combining nanofiltration with solvent-detergent or heat treatment. Sponsors in Massachusetts and Basel maintain dedicated viral clearance suites with segregated HVAC and waste handling infrastructure. Biopharmaceuticals concentrate revenue; Food Safety expands most quickly in Asia-Pacific export markets.
- Vaccine Manufacturing:Viral seed stock and cell substrate clearance requires validated inactivation of adventitious agents prior to release for clinical use. CDSCO in India and TGA in Australia enforce equivalent viral safety standards for domestic and export vaccine licensure. Vaccine Manufacturing anchors regulatory-driven demand; Water Treatment shows steepest volume acceleration in Middle East desalination projects.
- Blood Products:Plasma fractionation facilities apply solvent-detergent treatment to pooled human serum albumin and immunoglobulin products.
- Water Treatment:Municipal and industrial water systems deploy UV and chemical disinfection for enteric virus control in potable and wastewater streams.
- Food Safety:Beverage and prepared food manufacturers adopt non-thermal inactivation to meet Japanese and Australian export microbiological standards.
Biopharmaceuticals and Vaccine Manufacturing concentrate current spending; Food Safety applications gain share fastest in premium export segments.
End User:
Facility scale and in-house analytical capability determine whether viral clearance is performed captive or outsourced to contract service providers.
- Pharmaceutical Manufacturers:Large molecule developers in North Carolina and Leiden integrate viral clearance into downstream purification trains with dedicated process analytical technology for real-time release. These facilities command the highest equipment specification and validation documentation intensity. Pharmaceutical Manufacturers represent the largest equipment procurement segment; Biotech Firms show the fastest outsourcing growth.
- Biotech Firms:Clinical-stage developers in South San Francisco and Cambridge lack dedicated viral clearance infrastructure, driving demand for single-use disposable systems and specialized contract testing laboratories. Biotech Firms concentrate single-use demand; Diagnostic Laboratories expand fastest in emerging market reference lab networks.
- Diagnostic Laboratories:Clinical and research labs apply viral inactivation to patient samples and reagents prior to molecular testing workflows.
- Water Utilities:Municipal treatment authorities specify UV and chemical systems for enteric virus compliance in drinking water standards.
- Food Processing Plants:Juice, dairy, and ready-to-eat manufacturers deploy non-thermal systems for pathogen control without sensory degradation.
Pharmaceutical Manufacturers dominate capital equipment procurement; Biotech Firms drive fastest growth in disposable and service-based viral clearance.
Deployment:
Manufacturing architecture choices between batch fidelity and continuous throughput reshape equipment configuration and validation protocols.
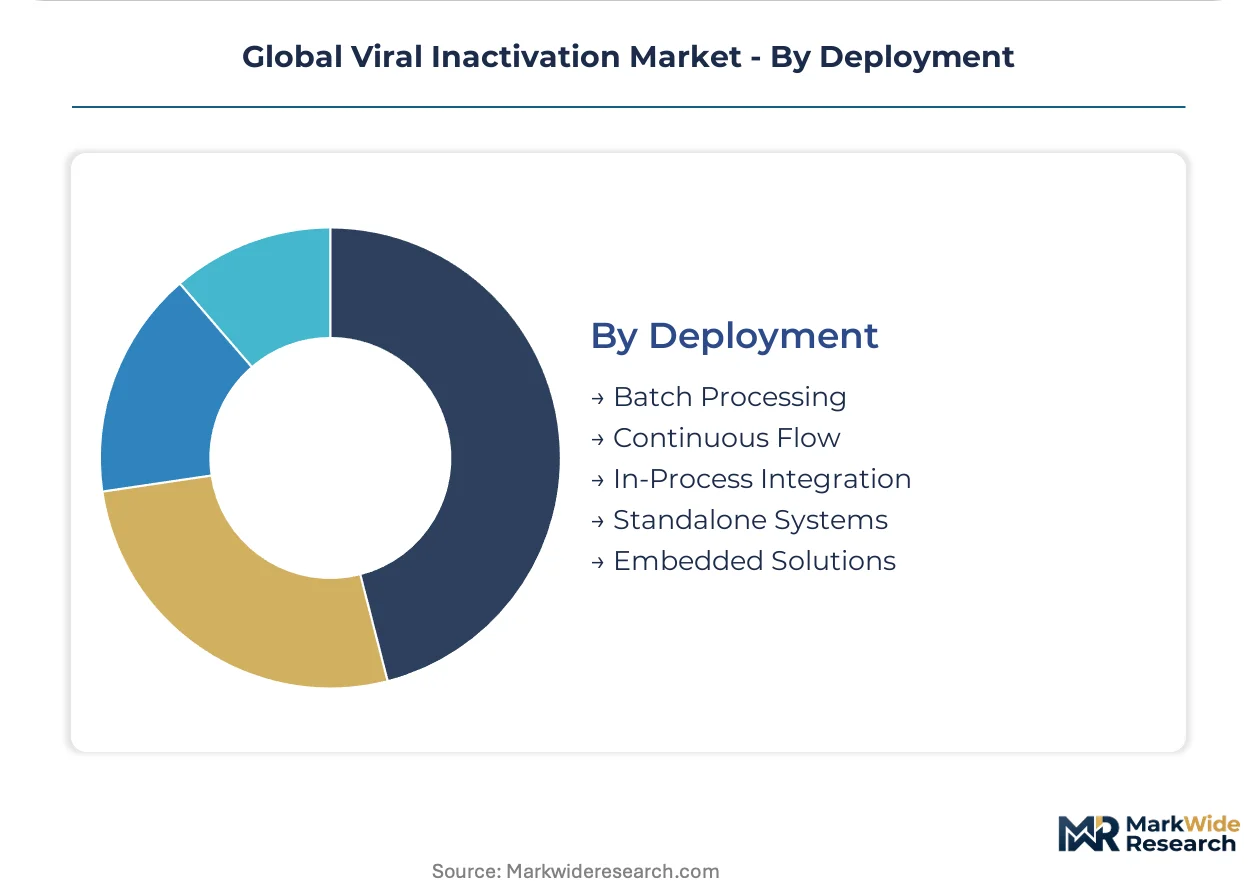
- Batch Processing:Traditional hold-tank configurations with validated time-temperature profiles remain standard for plasma derivatives and vaccine bulk manufacturing. These systems support extensive sampling and hold-release protocols required by FDA and EMA for biological license applications. Batch Processing retains installed base dominance; Continuous Flow gains fastest adoption in integrated bioprocessing platforms.
- Continuous Flow:Inline UV and nanofiltration skids enable real-time viral clearance without intermediate hold tanks, supporting continuous bioprocessing initiatives in Singapore and Swiss manufacturing clusters. Continuous Flow leads technology transition; In-Process Integration shows fastest specification growth in gene therapy vector production.
- In-Process Integration:Viral inactivation units embedded within purification trains eliminate discrete validation boundaries.
- Standalone Systems:Modular skids support multi-product facilities with rapid changeover between campaigns.
- Embedded Solutions:OEM-integrated components in bioreactor and chromatography platforms reduce footprint in distributed manufacturing.
Batch Processing retains volume leadership; Continuous Flow and In-Process Integration gain share fastest as biomanufacturing shifts toward integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stainless steel fabrication for heat inactivation vessels concentrates in northern Italy and southern Germany, creating 12-18 month equipment delivery timelines that constrain facility expansion across major biologics manufacturing clusters.
United States
FDA enforcement of ICH Q5A guidelines drives orthogonal viral clearance validation for recombinant protein and cell therapy submissions. The agency mandates redundant inactivation pathways for biologics license applications. Massachusetts and North Carolina manufacturing clusters attract dedicated viral clearance service providers and single-use equipment vendors.
Germany
EMA virus safety guidelines for biotechnological products now require next-generation sequencing for adventitious agent detection alongside traditional assays. Basel and Leiden developers face 6-9 month protocol amendments to satisfy expanded documentation requirements. Southern German fabricators supply validated heat treatment skids to European plasma fractionation facilities.
China
NMPA alignment with international viral safety standards accelerates multi-region biologics submissions from domestic manufacturers. Government production-linked incentives attract contract manufacturing investment to biologics clusters. Shanghai and Suzhou facilities expand dedicated viral clearance capacity for cell and gene therapy pipelines.
India
CDSCO streamlined biosimilar approval pathways reduce regulatory friction for viral clearance service providers. Government production-linked incentives draw equipment vendors and testing laboratories to Hyderabad and Bengaluru. Domestic plasma fractionators adopt solvent-detergent protocols to meet export market standards.
Switzerland
Swissmedic coordinates with EMA on viral safety evaluation standards for biotechnological products manufactured in Basel and Geneva corridors. Continuous bioprocessing initiatives in Swiss manufacturing clusters pull investment into inline ultraviolet and nanofiltration systems. Specialized bioanalytical capacity concentrates around academic and contract research institutions.
Global Viral Inactivation Market Competitive Landscape
Capacity expansion dominates the current landscape as biopharmaceutical contract manufacturers build dedicated viral clearance suites to capture cell and gene therapy demand. The vendor base separates into three tiers: integrated life science conglomerates with chromatography and filtration portfolios, specialized contract testing laboratories with bioanalytical capabilities, and single-use equipment fabricators focused on disposable manufacturing architectures. Strategic archetypes include full-service downstream bioprocessing integrators, viral clearance study specialists, and modular skid suppliers. M&A activity and geographic expansion into emerging biologics clusters represent the dominant competitive moves.
Among German-based diversified life science groups, Merck KGaA represents the integrated downstream bioprocessing archetype. Charles River Laboratories exemplifies the North American contract testing specialist model. Sartorius AG occupies a position within the single-use equipment tier. These three anchors illustrate how competitive positioning fragments across equipment supply, testing services, and integrated manufacturing workflows rather than concentrating in unified platform providers.
| Leading Market Players |
|---|
| Merck KGaA |
| Rad Source Technologies |
| Charles River Laboratories |
| Texcell |
| Sartorius AG |
| Clean Cells |
| Parker Hannifin Corp |
| SGS SA |
| Cytiva |
| Others |
Supply & Pricing Matrix
Performance tier divergence between validated single-use systems and commodity chemical disinfectants manifests in both procurement economics and supplier geography. Premium nanofiltration skids with pre-validated viral retention ratings command substantial service-bundling premiums from biopharmaceutical sponsors in Massachusetts and Basel, while standardized solvent-detergent protocols face margin compression from concentrated chemical feedstock suppliers.
Pricing Analysis
Equipment-versus-consumables bundling separates pricing models across the market. Project-based contracting dominates viral clearance study services, with Charles River Laboratories and Merck KGaA unbundling validation from manufacturing to capture 4-6 month timeline compression premiums. Price differentiation rests on FDA and EMA certification tier and real-time process analytical technology integration. Cost compression in chemical disinfectant tiers is intensifying because Triton X-100 and sodium cholate supply concentrates among three manufacturers. Clinical-stage biotech firms in South San Francisco exhibit highest price sensitivity, while plasma fractionators in Germany and the United States accept premium pricing for orthogonal validation redundancy.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical manufacturer demand for integrated downstream bioprocessing contracts. Fabrication of validated heat treatment vessels concentrates in northern Italy and southern Germany, with stainless steel piping and vessel assembly drawing from specialized metallurgical suppliers in Austria and Switzerland. Raw material dependencies include gamma-irradiated polymer resins for single-use assemblies, high-purity solvents for detergent protocols, and precision nanofiltration membranes. Single-source vulnerability in solvent-detergent chemical feedstocks exposes sponsors to raw material qualification delays. Distribution runs through authorized equipment distributors for mid-scale biotech firms and direct service contracts for large molecule developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
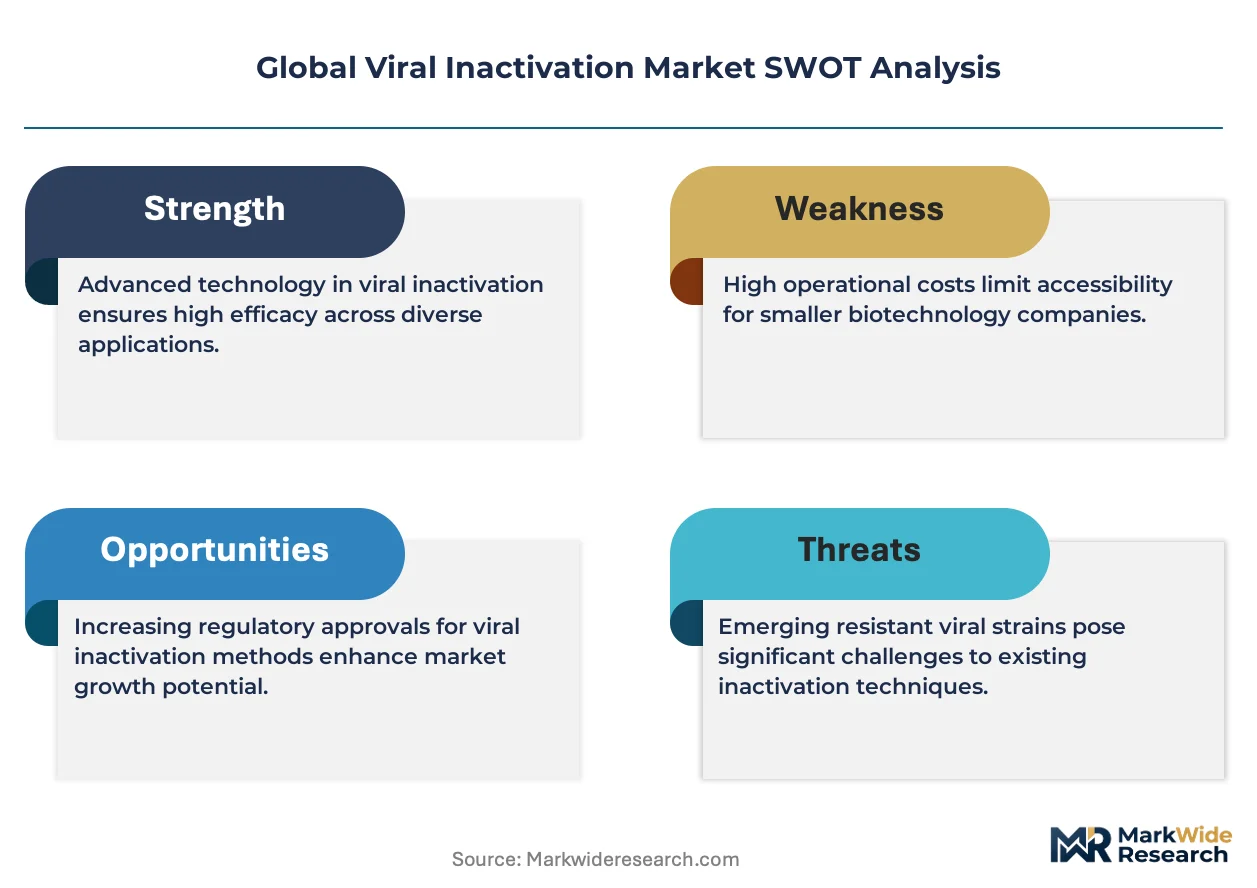
This market is consolidating as multi-source procurement burdens force smaller contract testing laboratories into acquisition or exit. Regulatory documentation intensity under EMA next-generation sequencing mandates is accelerating this consolidation pressure.
For Market Incumbents: Hedge against disintermediation by deepening bioanalytical service integration beyond viral clearance into full downstream bioprocessing workflows. Sartorius AG and Merck KGaA should expand single-use viral inactivation assembly capacity in Singapore and Swiss manufacturing clusters to capture continuous bioprocessing demand. Anchor position through captive supply of gamma-irradiated disposable components. For New Entrants and Emerging Players: Begin with specialized viral clearance study design for autologous cell therapy developers in Boston and Leiden, where bioanalytical scientist scarcity constrains sponsor capacity expansion. Target CDSCO-aligned biosimilar manufacturers in Hyderabad and Bengaluru with streamlined validation protocols. Lead with rapid-turnaround next-generation sequencing adventitious agent testing to compress 8-12 week analytical backlogs. For Investors and Strategic Acquirers: Re-rating potential sits with contract testing specialists given EMA documentation expansion and unbundling trends among mid-cap biotechs. Long-term viability favors platforms with integrated testing-to-clearance workflows and geographic presence across United States, Germany, and China regulatory clusters. Monitor CDSCO production-linked incentive disbursement velocity as inflection indicator for India biologics manufacturing emergence.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Production-Linked Incentive Capture | Indian biosimilar approval pathway acceleration draws viral clearance providers to Hyderabad and Bengaluru clusters. |
| Single-Use Technology Convergence | Gamma-irradiated viral inactivation assemblies eliminate cleaning validation burdens in clinical-stage manufacturing. |
| Next-Generation Sequencing Integration | EMA adventitious agent detection mandates force 6-9 month protocol redesigns for European biologics sponsors. |
| Continuous Bioprocessing Validation | Inline UV and nanofiltration systems require real-time viral clearance monitoring in Singapore and Swiss facilities. |
| Orthogonal Clearance Study Unbundling | Direct sponsor relationships with specialized testing laboratories compress overall program timelines by 4-6 months. |
Research Methodology
Document review covered FDA guidance documents, EMA virus safety evaluations, ICH Q5A harmonization texts, and WHO prequalification standards, complemented by interviews with viral clearance study directors, bioprocess engineering leads at contract manufacturers, regulatory affairs specialists, and procurement managers at plasma fractionation facilities. Secondary validation drew from SEC 10-K filings of diversified life science conglomerates, CDSCO biosimilar approval databases, and trade customs data for solvent-detergent chemical imports. Bottom-up equipment procurement estimates triangulated against top-down biologics manufacturing capacity expansion announcements.
Cross-reference between historical viral clearance validation timelines and expert panel input on continuous bioprocessing adoption shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology modality, application vertical, end-user facility scale, and deployment architecture. CAGRs were derived from weighted capacity expansion announcements and regulatory filing velocity. Forecast inputs incorporated cell and gene therapy pipeline progression rates and single-use technology penetration curves in multi-product facilities.
Underlying measurement precision varies by segment; biopharmaceutical and vaccine manufacturing applications carry tighter precision than food safety and water treatment verticals due to mandatory regulatory documentation intensity. Forecasts reflect assumptions regarding ICH Q5A harmonization maintenance, solvent-detergent chemical supply stability, and stainless steel fabrication capacity expansion in European supplier bases. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Suture Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Infection Prevention Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Denture Disinfectants Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Air Sanitizer Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Point of Care Infection Control Market
Infection Control
Antiseptic Bathing Market
Infection Control
Australia Hand Sanitizer Market