
 Internet of Things (IoT) Managed Services Market | 2026-2036
Internet of Things (IoT) Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) Managed Services Market Insights
Market Context with Strategic Players
Asset-light subscription and consumption-based financing is narrowing the competitive gap between hyperscale platforms and mid-tier systems integrators. Microsoft Azure leverages its captive cloud infrastructure to bundle compute with managed device lifecycle services. Tata Consultancy Services anchors its position through deep vertical specialization in manufacturing predictive maintenance. AWS competes by extending its IoT Core stack into fully managed security operations for multi-cloud estates.
Technical Definition and Structural Segments
Internet of Things (IoT) managed services denotes the outsourced provisioning, monitoring, security hardening, and optimization of connected device fleets, edge networks, and sensor data pipelines, typically delivered through SLAs governing uptime, latency, and incident response thresholds. These services eliminate the need for in-house platform engineering while ensuring industrial-grade reliability across distributed hardware ecosystems. Security management and data analytics command disproportionate margin pools as regulatory complexity and AI-driven inference workloads expand. Hybrid cloud deployment is displacing pure public cloud configurations in regulated manufacturing and healthcare end-user segments. Device management remains the most mature service type, with pricing pressure concentrated in standardized monitoring and firmware update delivery.
Regulatory Frame and Forward-Looking Close
The EU AI Act, GDPR, and NIS2 directive collectively mandate algorithmic transparency, data residency, and incident reporting for IoT systems processing personal or operational data across European member states. The US FDA and HIPAA frameworks impose comparable validation burdens on connected healthcare devices and their managed service backbones. Stakeholders must monitor how divergent cross-border compliance requirements reshape vendor consolidation logic and customer procurement criteria.
Market Dynamics
Hybrid cloud deployment architectures are fragmenting procurement authority between central IT and operational technology teams, forcing managed service vendors to engineer dual-interface governance models that satisfy both constituencies simultaneously.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for IoT systems processing personal data are compelling European manufacturers to outsource security operations and model validation to certified managed service providers.
- Predictive maintenance in discrete manufacturing:German automotive and machine tool producers are contracting device lifecycle management to reduce unplanned downtime across distributed production networks.
- Edge computing hardware proliferation:NVIDIA Jetson and ARM-based industrial controllers are expanding the addressable fleet base requiring remote monitoring and firmware orchestration services.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints for industrial-grade microcontrollers create delivery volatility for device management platforms dependent on hardware refresh cycles.
- GDPR data residency friction:Cross-border data transfer restrictions complicate centralized analytics delivery for multinational customers operating pan-European sensor networks.
- Legacy protocol persistence:Modbus and PROFIBUS installations in brownfield industrial sites resist seamless cloud-native integration without costly gateway infrastructure.
Strategic Opportunities
- Healthcare IoT in Japan:METI incentives for connected medical device deployments are opening service contracts for remote patient monitoring and FDA-equivalent PMDA compliance management.
- Digital twin convergence:Unity and Unreal Engine visualization layers are merging with real-time sensor streams to create immersive operational dashboards for facility management buyers.
- India smart city mandates:Ministry of Housing and Urban Affairs directives for 100 smart cities are generating municipal procurement of integrated traffic, utility, and environmental monitoring platforms.
Industry Challenges
- Embedded systems security expertise scarcity:Firmware vulnerability assessment and secure boot implementation skills command premium compensation, constraining service provider scaling.
- Multi-cloud orchestration complexity:Customers demanding workload portability across Azure, AWS, and private infrastructure require vendor investment in abstraction layer engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) Managed Services Market |
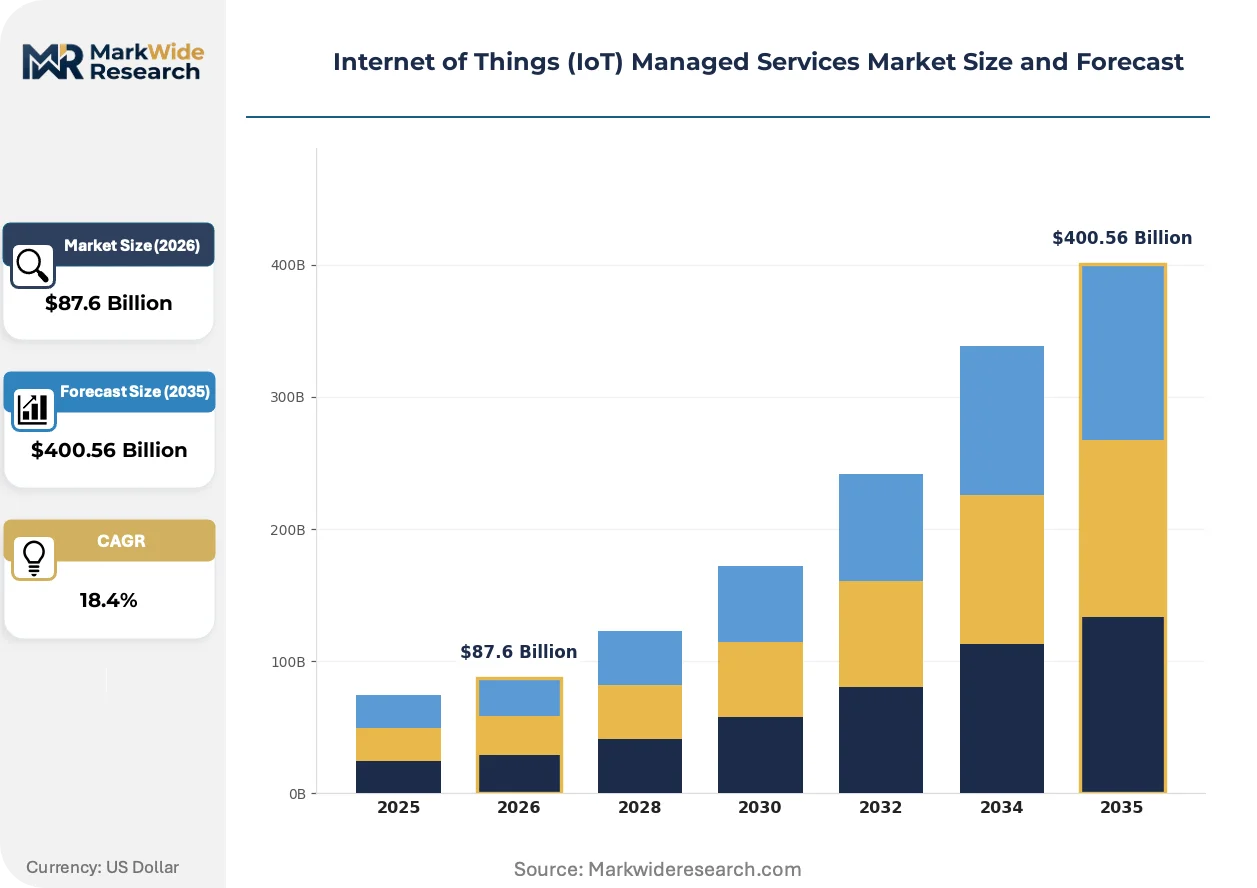
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Device Management, Network Management, Security Management, Data Analytics End User: Healthcare, Manufacturing, Smart Cities, Agriculture Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Application: Remote Monitoring, Asset Tracking, Predictive Maintenance, Smart Metering |
| Companies Covered | Infosys, EPAM Systems, Tata Consultancy Services, Microsoft Azure, AWS, Wipro, Capgemini Engineering, Cisco, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) Managed Services Market Trends and Innovations
Software-defined architectures are dissolving the boundary between device management and network operations, enabling service providers to monetize integrated stacks rather than discrete functional modules.
Digital twin platforms are virtualizing physical asset behavior for predictive simulation and scenario testing. German chemical producers and Dutch port operators are deploying these systems at scale to optimize maintenance scheduling. This capability is virtualizing traditional reliability engineering functions previously performed by in-house mechanical teams.
The EU AI Act's risk-based classification system is mandating conformity assessments for IoT systems deploying machine learning inference at the edge. Medical device and critical infrastructure operators must now document algorithmic decision trails and human oversight protocols. French and German healthcare networks are restructuring procurement specifications to prioritize vendors with notified body certifications.
Subscription-based consumption models are displacing perpetual licensing for device management platforms. Industrial buyers in Bavaria and Baden-Württemberg are negotiating outcome-indexed contracts tying fees to uptime guarantees rather than seat counts. This shift compresses vendor cash conversion cycles while aligning incentives around operational performance metrics.
Internet of Things (IoT) Managed Services Market Segmentation
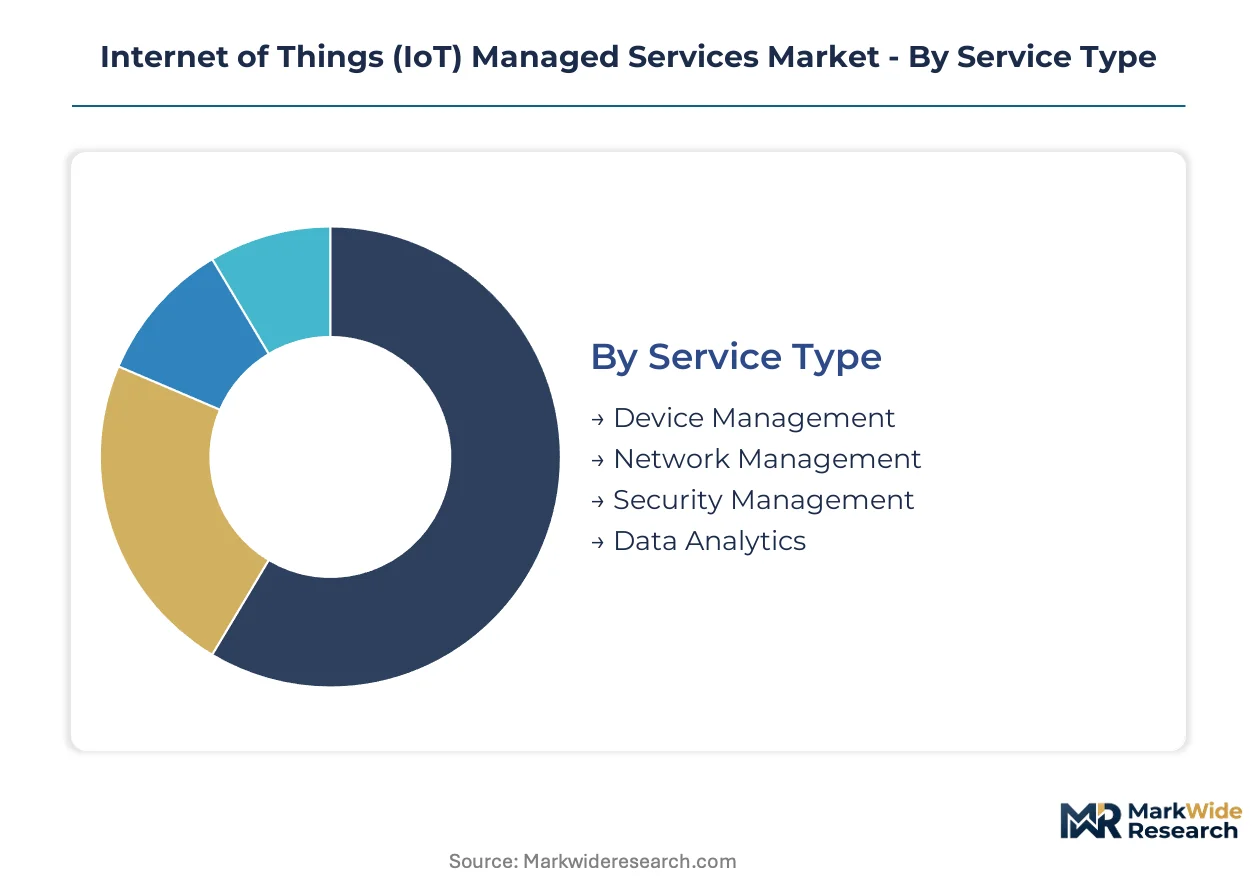
Service architecture choices in IoT managed services determine margin capture, compliance exposure, and customer lock-in duration. Segmentation reveals where vendor specialization creates defendable positions versus commoditized throughput.
Service Type:
Mature provisioning functions coexist with emerging intelligence layers, creating divergent margin profiles across the service stack.
- Device Management:Firmware orchestration, remote diagnostics, and lifecycle provisioning for distributed sensor fleets. German automotive suppliers in Bavaria dominate procurement volume, driven by unplanned downtime reduction mandates across just-in-time production networks.
- Security Management:Edge hardening, certificate lifecycle management, and threat detection for connected industrial controllers. EU AI Act and GDPR compliance requirements in France and Germany are accelerating outsourcing of algorithmic transparency validation and incident response.
- Network Management:Connectivity orchestration across cellular, LoRaWAN, and private 5G deployments.
- Data Analytics:Real-time inference pipelines and predictive model operations for sensor-derived insights.
Device Management handles the majority of throughput; Security Management is expanding most quickly on share.
End User:
Vertical specialization requirements fragment procurement authority between operational technology and central IT functions.
- Manufacturing:Predictive maintenance and production line optimization across discrete and process industries. Baden-Württemberg machine tool clusters anchor European demand, with contract structures shifting toward outcome-indexed uptime guarantees.
- Smart Cities:Integrated traffic, utility, and environmental monitoring platforms deployed at municipal scale. Southeast Asian urban deployments in Singapore and Vietnam are accelerating adoption of remote monitoring infrastructure.
- Healthcare:Connected medical device lifecycle management and FDA-equivalent PMDA compliance in Japan.
- Agriculture:Precision irrigation and livestock monitoring through distributed sensor networks.
Manufacturing contributes the largest revenue base; Smart Cities is climbing the fastest on deployment velocity.
Deployment Model:
Cost tier stratification separates standardized public offerings from engineered hybrid configurations.
- Hybrid Cloud:Workload portability across Azure, AWS, and private infrastructure with unified governance interfaces. Regulated manufacturing and healthcare segments in Germany concentrate demand, compelled by GDPR data residency requirements and NIS2 incident reporting mandates.
- Public Cloud:Consumption-based compute and storage with shared security responsibilities. Mid-tier systems integrators compete through vertical specialization rather than infrastructure ownership.
- Private Cloud:Dedicated infrastructure for classified or critical operational environments.
- On-Premises:Fully air-gapped deployments for legacy protocol integration and sovereignty requirements.
Hybrid Cloud commands premium pricing; Public Cloud maintains volume leadership.
Application:
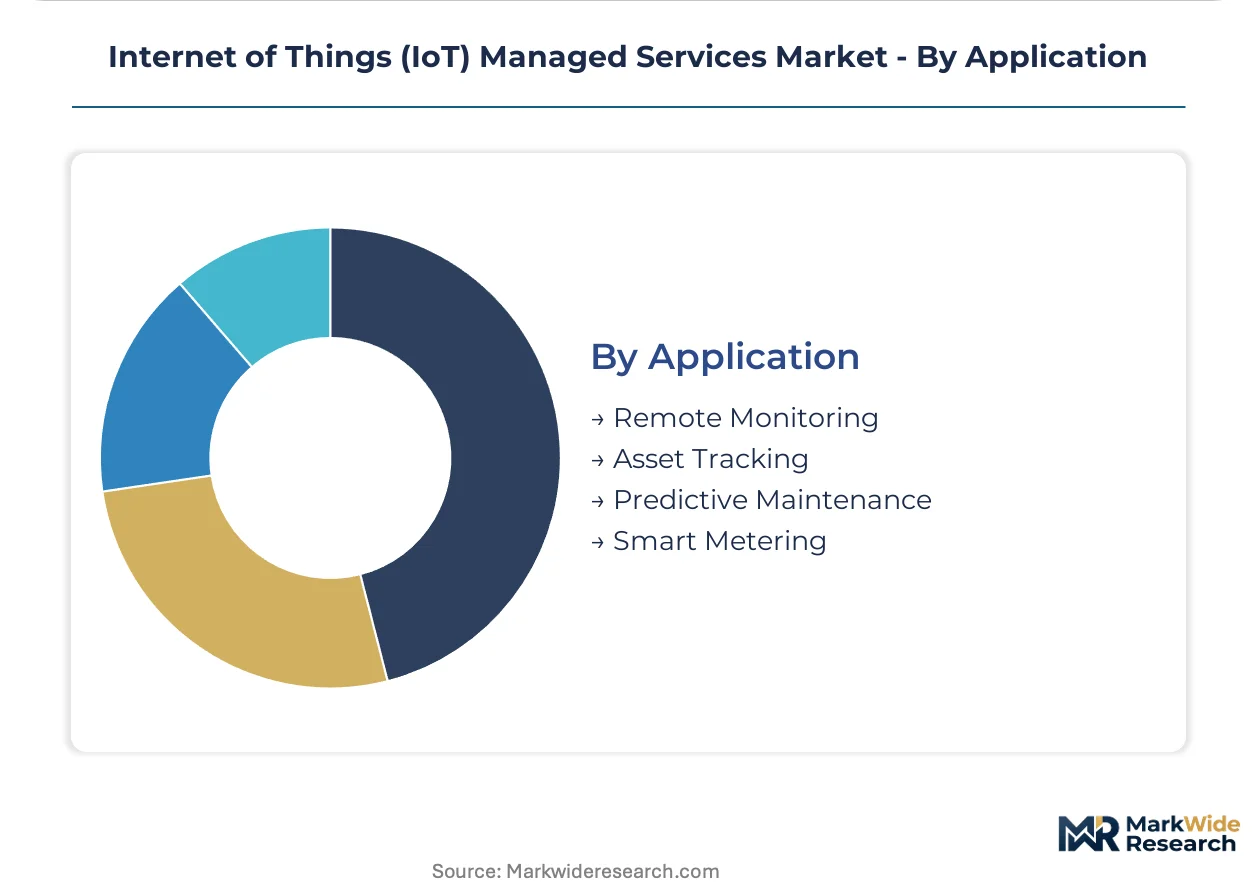
Use case maturity determines whether vendors monetize discrete modules or integrated operational stacks.
- Predictive Maintenance:Machine learning inference on vibration, thermal, and acoustic sensor streams to forecast equipment failure. Dutch port operators and German chemical producers deploy these systems at scale, virtualizing traditional reliability engineering functions.
- Remote Monitoring:Real-time telemetry visualization and threshold alerting for distributed asset fleets. Indian municipal procurement under Ministry of Housing and Urban Affairs directives is generating integrated platform demand across 100 smart city deployments.
- Asset Tracking:Location and condition monitoring for mobile equipment and inventory.
- Smart Metering:Automated utility consumption measurement and demand response orchestration.
Remote Monitoring processes the highest transaction volumes; Predictive Maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in IoT managed services favor net-importing industrial economies over hardware-exporting manufacturing hubs. Germany and Japan run structural deficits in platform engineering talent while exporting precision machinery requiring managed connectivity. The United States and India generate surplus service capacity through hyperscale cloud infrastructure and offshore delivery centers respectively.
United States
FDA and HIPAA frameworks impose validation burdens on connected healthcare devices, driving outsourcing of compliance management to certified providers. The IRA's domestic manufacturing incentives are expanding sensor deployments across reshoring factory networks. Greater Boston's medical device cluster anchors demand for FDA-validated remote monitoring platforms.
Germany
EU AI Act algorithmic transparency mandates and NIS2 incident reporting requirements are compelling industrial manufacturers to outsource security operations. Bavaria's automotive suppliers and Baden-Württemberg's machine tool producers contract predictive maintenance services to reduce unplanned downtime across just-in-time production networks.
Japan
METI incentives for connected medical device deployments are opening service contracts for remote patient monitoring and PMDA compliance management. Kanto region healthcare networks restructure procurement specifications to prioritize vendors with notified body certifications. Tokyo-based medical device manufacturers anchor regional demand for lifecycle management services.
India
Ministry of Housing and Urban Affairs directives for 100 smart cities generate municipal procurement of integrated traffic, utility, and environmental monitoring platforms. Karnataka's technology corridor and Maharashtra's industrial zones concentrate delivery center capacity for offshore managed services. Bangalore-based systems integrators capture contracts for remote monitoring infrastructure deployment.
Singapore
Southeast Asian smart city deployments accelerate adoption of remote monitoring platforms through government-backed urban digitalization programs. The city-state's position as regional headquarters for industrial automation vendors concentrates procurement authority for cross-border device fleet management. Maritime and logistics operators deploy predictive maintenance across port infrastructure and container tracking networks.
Internet of Things (IoT) Managed Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper vertical expertise. The vendor base organizes into three tiers: hyperscale cloud providers with captive infrastructure, global systems integrators with offshore delivery scale, and boutique specialists with sector-specific certifications. Consolidation pressure intensifies as EU AI Act compliance requirements favor providers with notified body relationships and cross-border data governance capabilities.
Within the hyperscale tier, Microsoft Azure and AWS exemplify platform-centric strategies bundling compute with managed device lifecycle services. Tata Consultancy Services anchors the global systems integrator segment through manufacturing vertical specialization. These three occupy positions reflecting divergent asset intensity: infrastructure ownership versus human capital leverage versus vertical depth.
| Leading Market Players |
|---|
| Infosys |
| EPAM Systems |
| Tata Consultancy Services |
| Microsoft Azure |
| AWS |
| Wipro |
| Capgemini Engineering |
| Cisco |
| Cognizant |
| Others |
Pricing and Supply Chain Analysis
Semiconductor supply concentration in Taiwan-based foundries exposes IoT managed service vendors to simultaneous cost volatility and delivery uncertainty, compressing margins in standardized device management tiers while forcing premium pricing for security-hardened offerings with alternative sourcing pathways.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture ISO 27001 and EU AI Act compliance certifications alongside dedicated incident response SLAs. Standard tiers compete on per-device subscription rates with shared security operations. Cost compression in economy tiers stems from hyperscale cloud providers bundling compute with baseline monitoring. Discrete manufacturers in Baden-Württemberg exhibit lowest price sensitivity due to unplanned downtime costs, while municipal smart city procurement in India shows highest sensitivity to unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for industrial-grade microcontroller sourcing. Taiwan, South Korea, and Germany concentrate fabrication capacity for edge computing hardware including NVIDIA Jetson modules and ARM-based controllers. The ecosystem draws from silicon wafers, cellular modem chipsets, and LoRaWAN gateway components. Distribution runs through hyperscale cloud marketplaces, systems integrator channel partners, and direct OEM contracting for large manufacturing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
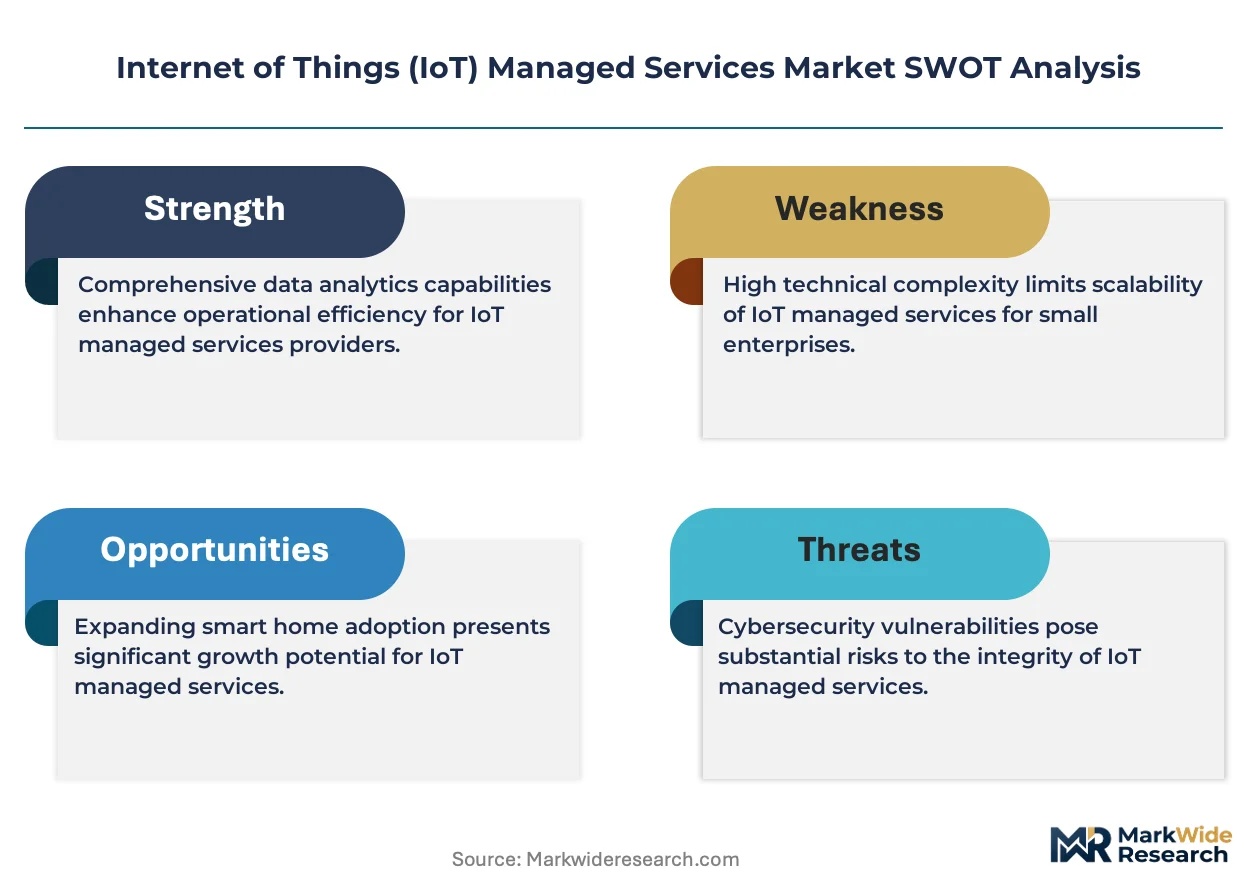
IoT managed services function as a high-attach recurring revenue layer expanding faster than underlying sensor hardware deployment, with security operations and predictive analytics subscriptions outpacing device provisioning growth across industrial end-user segments.
For Market Incumbents: Harden defensive positions through backward integration into edge hardware certification pipelines and captive firmware vulnerability assessment capabilities. The EU AI Act's conformity assessment requirements favor providers with notified body relationships, creating consolidation pressure on mid-tier competitors lacking vertical depth in algorithmic transparency validation. Prioritize capacity expansion in Germany's industrial automation clusters to secure outcome-indexed contract structures. For New Entrants and Emerging Players: Build out specialized capabilities in healthcare IoT compliance management for Japan's METI-incentivized connected medical device deployments. The PMDA validation pathway remains underpenetrated relative to FDA-equivalent demand density. Target municipal procurement in India's 100 smart city program through Bangalore-based systems integrator partnerships, offering integrated traffic and environmental monitoring platforms with localized data residency architecture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with EU AI Act certification assets and cross-border data governance infrastructure. Long-term viability centers on recurring revenue durability rather than project-based systems integration. Acquisition target archetypes include boutique security operations providers with embedded systems firmware expertise and regional healthcare compliance specialists. Monitor notified body certification backlogs as an inflection signal for vendor qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies device management, security operations, and analytics layers into single SLAs for manufacturing buyers. |
| Acquisition of Specialist Firm | Captures embedded systems security expertise and EU AI Act notified body relationships. |
| Geographic Expansion | Establishes delivery center capacity in Karnataka and Maharashtra for India's smart city procurement. |
| Strategic Partnership | Links Unity visualization engines with real-time sensor streams for Dutch port operator digital twin deployments. |
| Product Launch | Introduces outcome-indexed pricing tying fees to uptime guarantees across Bavarian automotive supplier networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with IoT platform engineers, OT security directors at German automotive suppliers, procurement leads for smart city infrastructure, managed service delivery heads, and regulatory compliance officers. Secondary validation drew from hyperscaler capex disclosures, EU AI Act implementation guidance, FDA device registration databases, and customs data on industrial controller imports. Bottom-up service revenue estimates were triangulated against top-down addressable fleet calculations.
Calibration against historical deployment velocity and regulatory milestone timing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type maturity, vertical specialization depth, deployment architecture complexity, and regional regulatory cluster intensity. CAGRs were derived from install base expansion rates multiplied by average revenue per device trajectories, with edge hardware proliferation and compliance outsourcing intensity as primary forecast inputs.
Stress conditions across semiconductor supply availability, cross-border data transfer restriction enforcement, and legacy protocol integration cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Employee Engagement Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Shared Services Center Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Managed Services Market
Enterprise Services
Supplier Management Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Outsourced Customer Care Services Market