
 Asia-Pacific Enterprise Asset Management Market | 2026-2036
Asia-Pacific Enterprise Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Enterprise Asset Management Market Insights
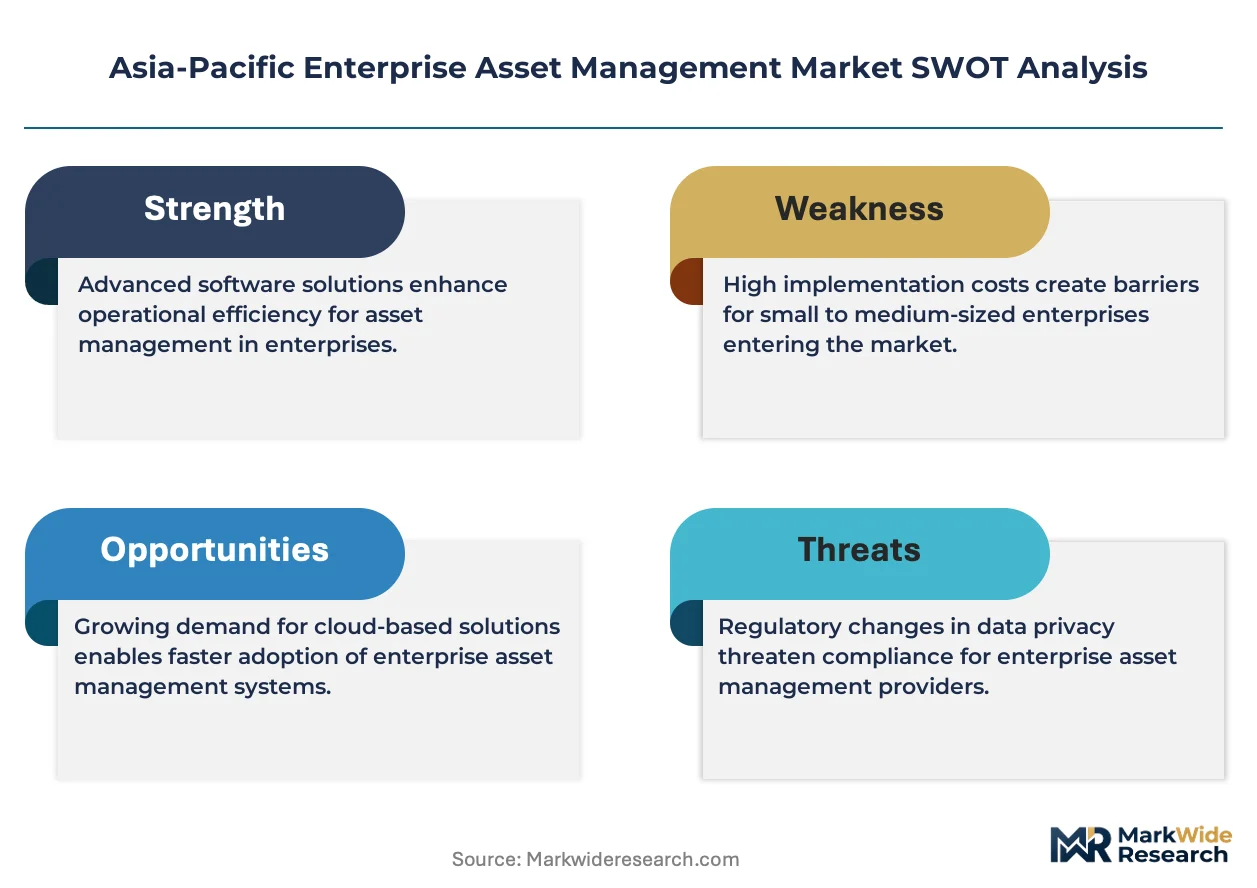
Buyer fragmentation across mid-sized manufacturers is repositioning procurement patterns throughout the Asia-Pacific Enterprise Asset Management landscape. IBM leverages its Watson IoT platform to anchor predictive maintenance capabilities for energy utilities across Australia and Japan. SAP competes through deep ERP integration, sustaining cross-functional asset visibility for large industrial conglomerates. Oracle differentiates via autonomous database architectures, extending real-time analytics to transportation fleet operators seeking lifecycle cost reduction.
Enterprise Asset Management encompasses the systematic governance of physical assets across their complete lifecycle, integrating condition monitoring, work order management, and spare parts inventory optimization through centralized digital platforms. Cloud-based Solutions lead deployment preferences as manufacturers seek scalable infrastructure without capital-intensive server investments, while On-premise Solutions retain traction among defense and critical infrastructure operators with stringent data sovereignty requirements. Support & Maintenance services capture recurring revenue streams as installed bases expand, and the Energy end user segment demonstrates accelerated uptake driven by grid modernization mandates across multiple Asia-Pacific jurisdictions.
Japan's METI operational technology cybersecurity guidelines, India's CEA grid connectivity standards, and China's MIIT cloud service security assessments collectively shape product certification pathways and vendor market access across the region. Compliance with these frameworks determines eligibility for public sector contracts and critical infrastructure deployments in their respective jurisdictions. Stakeholders must evaluate regulatory divergence between national frameworks when architecting multi-country rollout strategies for asset management platforms.
Market Dynamics
China's MIIT cloud computing standards are forcing vendors to re-architect compliance layers, compressing product development cycles and redistributing competitive advantage toward domestic software houses with pre-certified infrastructure stacks.
Growth Catalysts
- Grid Modernization Mandates:India's CEA connectivity standards for renewable integration are accelerating EAM adoption across thermal and solar hybrid installations in Gujarat and Rajasthan.
- Operational Technology Convergence:Japan's METI cybersecurity guidelines are mandating unified asset visibility across IT and OT environments for critical infrastructure operators.
- Industrial Corridor Concentration:Manufacturing clusters around Mumbai, Pune, and Chennai are consolidating procurement for digital asset platforms through shared service centers.
Market Restraints
- Data Sovereignty Compliance:Divergent national cloud security assessments across China, India, and Australia fragment vendor certification pathways and inflate compliance overhead.
- Legacy System Entrenchment:Decades-old CMMS installations in Japanese heavy industry create technical debt that resists API-based integration with modern predictive analytics layers.
- Specialized Talent Scarcity:Shortages of condition monitoring engineers and reliability-centered maintenance specialists constrain deployment velocity across Southeast Asian manufacturing.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics assembly and textile producers in Bac Ninh and Dong Nai provinces represent underpenetrated demand for cloud-native asset tracking.
- Digital Twin Convergence:Integration of IoT sensor streams with 3D facility modeling is opening lifecycle simulation contracts for process industries in South Korea and Singapore.
- PLI Scheme Tailwinds:India's production-linked incentive schemes for semiconductor and pharmaceutical manufacturing are embedding EAM requirements into greenfield facility specifications.
Industry Challenges
- Interoperability Certification Delays:ISO 55000 alignment with national asset management frameworks in Indonesia and Thailand extends sales cycles by 8-14 months for multinational vendors.
- OT Security Skill Gaps:Plant-level engineers lack training in IEC 62443 implementation, forcing vendors to bundle implementation services and compress software margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Enterprise Asset Management Market |
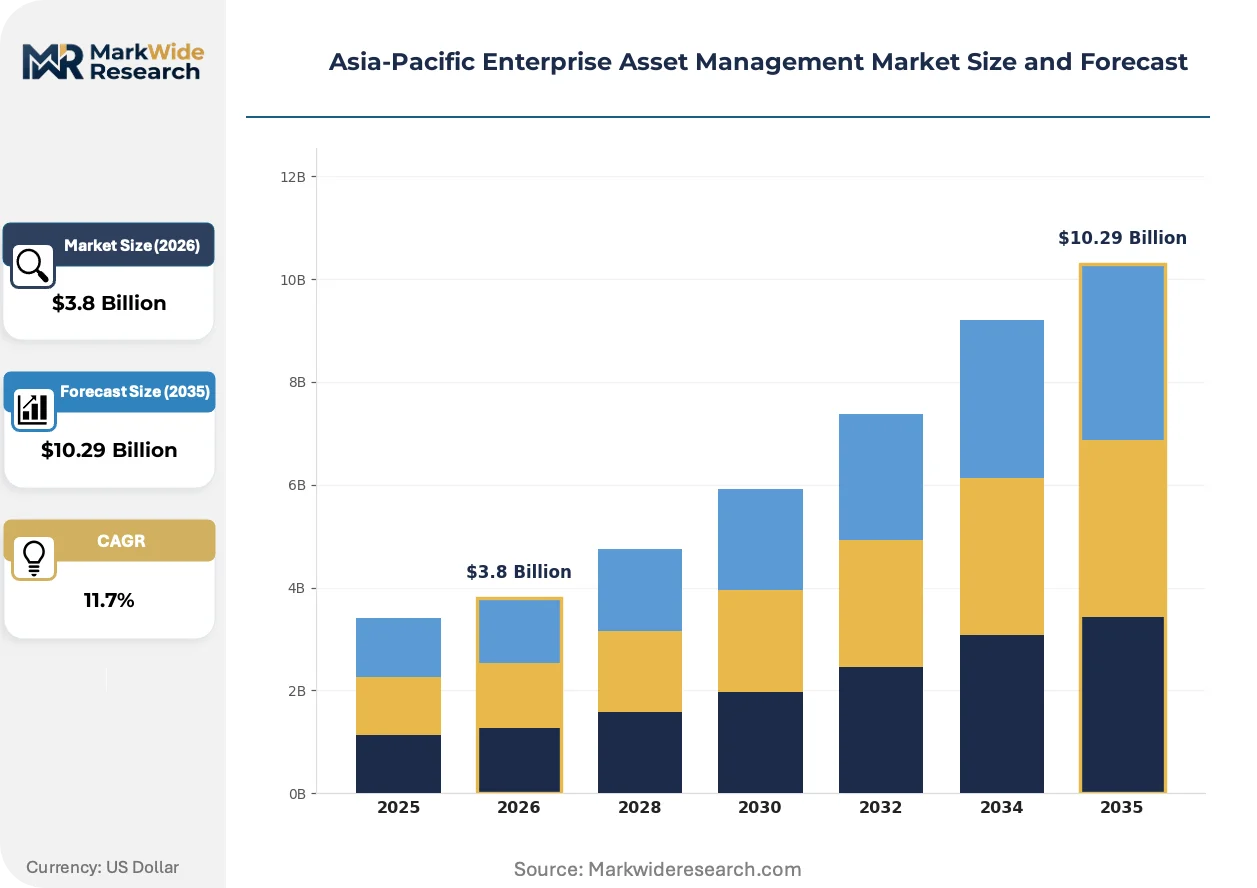
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Mobile Solutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: Manufacturing, Healthcare, Energy, Transportation Service Type: Consulting, Implementation, Support & Maintenance, Training |
| Companies Covered | IBM, SAP, Oracle, IFS, Hexagon, Siemens, Infor, ABB, Microsoft, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Enterprise Asset Management Market Trends and Innovations
Edge computing architectures are redistributing processing loads from centralized cloud nodes to plant-floor gateways, enabling millisecond-latency anomaly detection that reshapes maintenance scheduling economics.
Digital twin technology is electrifying asset lifecycle management by creating persistent virtual replicas of physical equipment. Energy utilities across Australia and Japan are deploying these models for scenario simulation of grid stress events. The technology is compressing mean time to repair by pre-positioning spare components before actual failures trigger downtime.
China's MIIT cloud service security assessments are mandating domestic data residency and encryption standards for critical infrastructure deployments. Foreign vendors must establish local cloud regions or partner with licensed domestic operators to maintain eligibility. Transportation and energy operators in Shanghai and Guangdong are prioritizing pre-certified platforms to accelerate procurement timelines.
Mid-sized manufacturers are consolidating vendor relationships through multi-year platform subscriptions rather than perpetual license purchases. Equipment OEMs in South Korea are responding with bundled EAM modules attached to new machinery sales. This pattern is most visible in automotive component supply chains around Chennai and Pune, where tier-two suppliers face pressure from upstream buyers to demonstrate predictive maintenance capabilities.
Asia-Pacific Enterprise Asset Management Market Segmentation
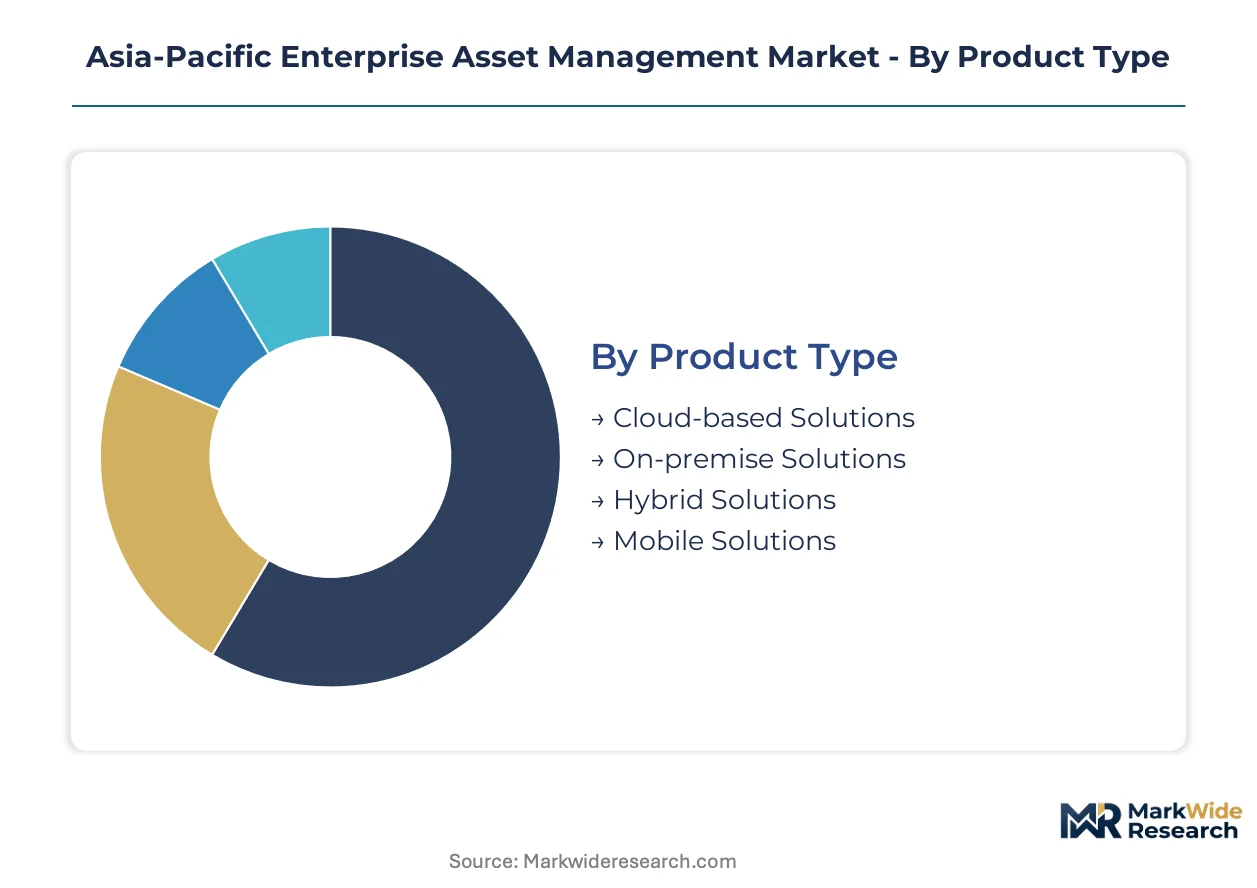
Segmentation in Asia-Pacific Enterprise Asset Management reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and operational technology integration depth. Buyers select deployment modes and service bundles based on data sovereignty requirements, legacy system entrenchment, and workforce digital readiness.
Product Type:
Standardization dominates cloud-native offerings while customization intensity rises with on-premise and hybrid configurations that must accommodate legacy OT protocols.
- Cloud-based Solutions:Multi-tenant SaaS architectures deliver scalable asset tracking without capital-intensive infrastructure. Demand concentrates in Vietnam's electronics assembly corridors around Bac Ninh and Dong Nai, where greenfield facilities prioritize rapid deployment over customization.
- On-premise Solutions:Dedicated server installations with localized data processing serve defense and critical infrastructure operators. Japanese heavy industry maintains these deployments due to METI cybersecurity guidelines mandating air-gapped operational technology environments.
- Hybrid Solutions:Split architectures process sensitive workloads locally while leveraging cloud analytics for non-critical functions. India's CEA grid connectivity standards are accelerating adoption across thermal-solar hybrid installations in Gujarat and Rajasthan.
- Mobile Solutions:Field technician applications with offline synchronization capabilities extend asset visibility to remote maintenance crews. Southeast Asian manufacturing clusters deploy these for condition monitoring in facilities with intermittent connectivity.
Most installed capacity flows through Cloud-based Solutions. Expansion is steepest in Hybrid Solutions.
Deployment:
Cost tier stratification separates hyperscale public deployments from premium private infrastructure serving regulated industries.
- Public Cloud:Shared infrastructure with pay-as-you-scale economics attracts mid-sized manufacturers consolidating procurement through shared service centers. Mumbai and Pune industrial corridors demonstrate concentrated uptake among tier-two automotive suppliers.
- Private Cloud:Single-tenant environments with dedicated resource pools address data residency mandates. China's MIIT cloud service security assessments are forcing foreign vendors to establish local regions or partner with licensed domestic operators.
- Hybrid Cloud:Orchestrated workloads spanning public and private domains balance cost efficiency with compliance. South Korean process industries favor this model for digital twin integration requiring low-latency edge processing alongside cloud-scale simulation.
- On-premises:Fully captive infrastructure retains traction where network reliability cannot be guaranteed. Australian energy utilities maintain these deployments for remote generation assets beyond reliable telecommunications coverage.
Public Cloud carries the largest installed base. Private Cloud is climbing the fastest as regulatory frameworks harden.
End User:
Application criticality determines solution sophistication, with continuous-process industries demanding predictive capabilities that discrete manufacturers often defer.
- Manufacturing:Discrete and process production facilities track equipment availability, quality parameters, and maintenance histories. Electronics OEMs in South Korea bundle EAM modules with new machinery sales to tier-two suppliers in Chennai and Pune.
- Energy:Generation, transmission, and distribution operators manage asset health across geographically dispersed infrastructure. Australia's grid modernization mandates and Japan's METI cybersecurity guidelines are accelerating unified IT-OT visibility investments.
- Healthcare:Medical device fleet management and facility infrastructure tracking ensure regulatory compliance and patient safety continuity. Singapore's hospital clusters deploy these systems for predictive maintenance of imaging equipment.
- Transportation:Fleet operators and logistics hubs optimize vehicle lifecycle costs and maintenance scheduling. Transportation operators in Shanghai and Guangdong prioritize pre-certified platforms to compress procurement timelines.
Manufacturing holds the dominant installed base. Energy is expanding most quickly on grid modernization tailwinds.
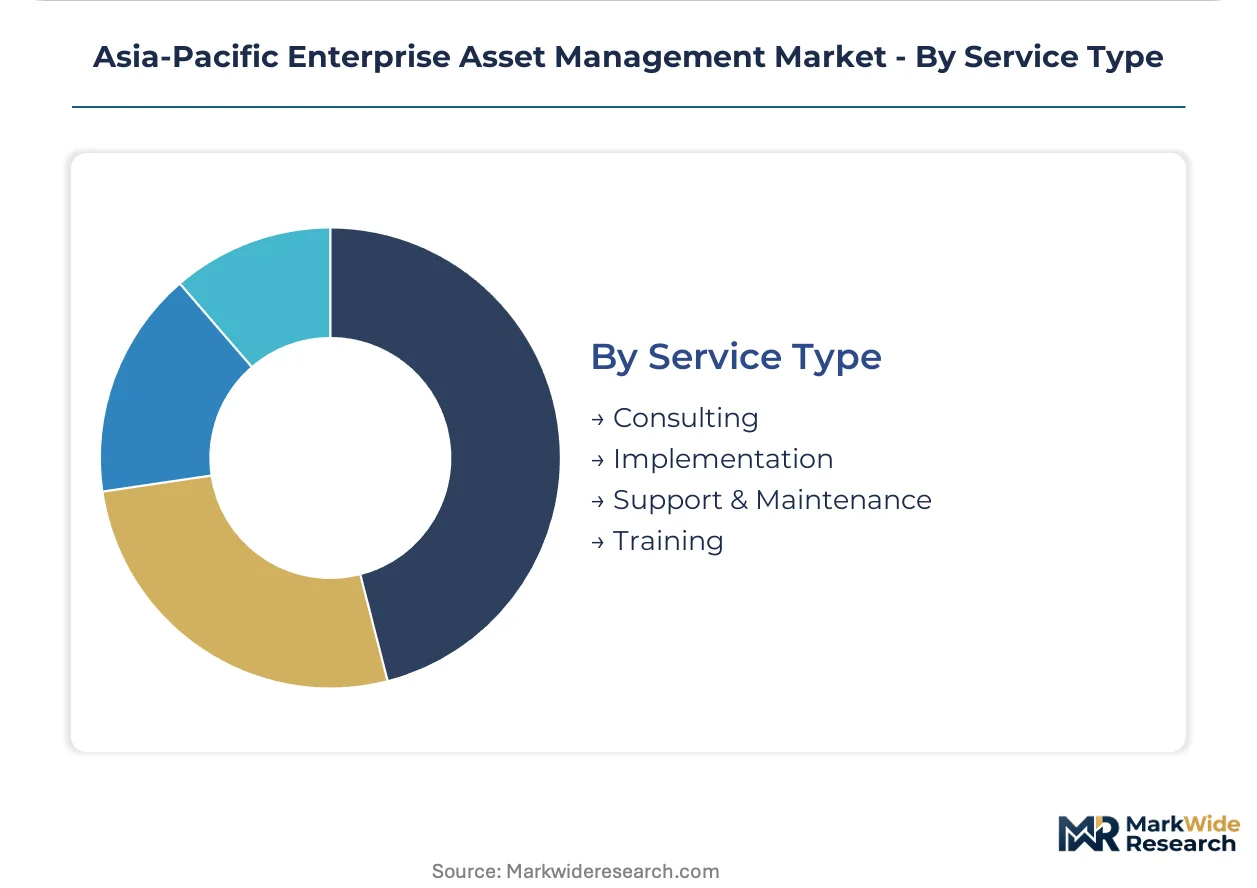
Service Type:
Customer maturity shapes service mix, with early-stage buyers requiring implementation support while established users shift spending toward optimization consulting.
- Consulting:Asset management strategy, process redesign, and organizational change management services align technology investments with operational objectives. Indian industrial corridors engage consultants to navigate ISO 55000 alignment with national frameworks.
- Implementation:System configuration, data migration, and integration with existing ERP or SCADA environments. Vendors bundle these services in Southeast Asia to compensate for OT security skill gaps among plant-level engineers.
- Support & Maintenance:Recurring technical assistance, version upgrades, and uptime guarantees capture expanding revenue as installed bases mature. This segment sustains vendor margins through multi-year platform subscriptions replacing perpetual licenses.
- Training:Workforce development programs address specialized talent scarcity in condition monitoring and reliability-centered maintenance. Japanese heavy industry invests here to overcome decades-old CMMS technical debt resisting API-based integration.
Support & Maintenance commands the largest revenue share. Consulting is gaining share fastest as buyers seek outcome-based partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT cloud computing standards are compressing product development cycles more aggressively than Japan's METI cybersecurity guidelines, creating divergent compliance pathways across the region.
China
MIIT cloud service security assessments mandate domestic data residency and encryption standards for critical infrastructure deployments. Foreign vendors must establish local cloud regions or partner with licensed domestic operators to maintain eligibility. Transportation and energy operators in Shanghai and Guangdong prioritize pre-certified platforms to accelerate procurement timelines.
Japan
METI operational technology cybersecurity guidelines mandate unified asset visibility across IT and OT environments for critical infrastructure operators. Decades-old CMMS installations in heavy industry create technical debt that resists API-based integration with modern predictive analytics layers. Kanto manufacturing clusters invest in workforce training to overcome legacy system entrenchment.
India
CEA grid connectivity standards for renewable integration are accelerating EAM adoption across thermal and solar hybrid installations. Production-linked incentive schemes for semiconductor and pharmaceutical manufacturing embed EAM requirements into greenfield facility specifications. Industrial corridors around Mumbai, Pune, and Chennai consolidate procurement through shared service centers.
Australia
Grid modernization mandates are accelerating unified IT-OT visibility investments across generation, transmission, and distribution operators. Energy utilities maintain on-premises deployments for remote generation assets beyond reliable telecommunications coverage. Western Australian mining operations deploy edge computing architectures for millisecond-latency anomaly detection.
South Korea
Process industries favor hybrid cloud models for digital twin integration requiring low-latency edge processing alongside cloud-scale simulation. Electronics OEMs bundle EAM modules with new machinery sales to tier-two suppliers. Automotive component supply chains demonstrate concentrated uptake of predictive maintenance capabilities.
Asia-Pacific Enterprise Asset Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and service bundles. The vendor base stratifies into three tiers: global technology conglomerates with integrated IoT platforms, ERP-native providers leveraging cross-functional data visibility, and industrial automation specialists with deep OT protocol expertise. Dominant competitive moves include strategic partnerships with licensed domestic cloud operators and portfolio diversification into edge computing architectures.
Among global technology conglomerates, IBM and Microsoft exemplify the platform-centric archetype, anchoring predictive maintenance capabilities through cloud-native infrastructure stacks. SAP and Oracle occupy positions within the ERP-native tier, leveraging existing enterprise data relationships to extend asset visibility. Siemens and ABB represent the industrial automation specialists, sitting within the OT-IT convergence segment with embedded hardware-software integration.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Oracle |
| IFS |
| Hexagon |
| Siemens |
| Infor |
| ABB |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Condition monitoring engineer shortages across Southeast Asian manufacturing clusters widen labor-cost differentials between premium-certified and economy-tier EAM deployments. India's CEA grid connectivity standards and China's MIIT cloud assessments compress procurement timelines for pre-certified platforms while inflating compliance premiums.
Pricing Analysis
Capacity additions in Vietnam's electronics corridors are reshaping price floors for cloud-native asset tracking solutions. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in ISO 55000 certification status and edge computing integration depth. Cost compression in economy tiers intensifies because domestic software houses leverage pre-certified infrastructure stacks. Mid-sized manufacturers in Mumbai and Pune industrial corridors exhibit highest price sensitivity; defense operators with METI air-gap requirements demonstrate lowest.
Supply Chain Analysis
China's MIIT domestic-content mandates for critical infrastructure are reshaping sourcing patterns for encryption modules and cloud processing nodes. Component supply concentrates in China, South Korea, and Japan for IoT sensors, edge gateways, and predictive analytics engines. Raw material dependencies span semiconductor-grade silicon, lithium-ion battery cells for mobile field units, and specialized alloys for industrial-grade enclosures. Single-source vulnerability in domestic cloud operator licensing creates procurement bottlenecks for foreign vendors. Distribution runs through systems integrators with OT protocol expertise and direct OEM channels for bundled machinery sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where China's MIIT cloud service security assessments and Japan's METI cybersecurity guidelines continuously expand compliance-driven replacement cycles.
For Market Incumbents: Extend predictive maintenance capabilities into digital twin convergence for South Korean process industries before specialized OT-IT integrators capture lifecycle simulation contracts. Deepen backward integration into edge computing hardware to defend margin position against bundled EAM modules from South Korean electronics OEMs. Prioritize local cloud region establishment or licensed domestic operator partnerships in China to preserve eligibility for transportation and energy procurement. For New Entrants and Emerging Players: The price-point gap between SAP-Oracle premium tiers and economy SaaS offerings opens white-space in Vietnam's Bac Ninh and Dong Nai electronics assembly corridors. Target tier-two automotive suppliers around Chennai facing upstream pressure to demonstrate predictive maintenance capabilities. Pursue PLI-linked greenfield facility specifications in India's semiconductor and pharmaceutical manufacturing as the fastest-penetrable entry channel. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial automation specialists with deep OT protocol expertise but limited cloud-native platform scale. Long-term viability favors acquisition targets with embedded hardware-software integration and existing METI or CEA certification pathways. Watch for inflection when ISO 55000 alignment delays in Indonesia and Thailand begin compressing multinational vendor sales cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified IT-OT visibility investments accelerate across Australia's grid modernization mandates. |
| Strategic Partnership | Licensed domestic cloud operator alliances preserve China market access under MIIT assessments. |
| Acquisition of Specialist Firm | Edge computing hardware targets address latency requirements for Western Australian mining operations. |
| Geographic Expansion | Vietnam manufacturing corridors represent underpenetrated demand for cloud-native asset tracking. |
| Product Launch | Digital twin modules capture lifecycle simulation contracts in South Korean process industries. |
Research Methodology
Bottom-up energy and manufacturing modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combine with secondary validation from MIIT certification databases, CEA grid connectivity filings, METI cybersecurity guideline releases, and hyperscaler regional capex disclosures. This dual-layer approach triangulates demand-side adoption patterns against supply-side capacity commitments.
Input-output matrices map deployment mode, end-user vertical, and integration complexity dimensions across the projection horizon. CAGRs derive from segment-level adoption curves weighted by regulatory enforcement timelines and industrial corridor concentration patterns. Forecast inputs incorporate cloud service security assessment completion rates and ISO 55000 alignment progress across Indonesia and Thailand.
The model assumes a particular technology adoption path; alternative pathways for edge computing architectures would alter the outlook if millisecond-latency requirements shift faster than telecommunications infrastructure expansion. Forecasts reflect assumptions about regulatory enforcement consistency and workforce training program scale. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Bring Your Own Device Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Managed Services Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Supplier Management Market
Enterprise Services
North America Contingent Workforce Management Market