
 Contingent Staffing Solutions Market | 2026-2036
Contingent Staffing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Contingent Staffing Solutions Market Insights
AI-powered talent matching and automated compliance verification is rewriting how contingent workforces are sourced, onboarded, and managed across distributed enterprises. Deel leverages its global payroll infrastructure to anchor cross-border contractor engagement in over 150 countries. Upwork sustains a marketplace model that competes on transaction velocity and skill-category breadth for knowledge-work assignments. Magnit specializes in contingent workforce analytics that differentiate its managed service provider offerings through real-time labor cost benchmarking.
Contingent staffing solutions encompass the systems, platforms, and services that connect organizations with non-permanent workers across defined durations, project scopes, or seasonal demand cycles, typically incorporating automated time tracking, regulatory compliance checks, and payment orchestration as core functional modules. The primary commercial purpose centers on enabling workforce elasticity while transferring employment liability and administrative burden to specialized intermediaries. Temporary staffing and contract staffing dominate service type revenue pools due to their entrenched use in manufacturing and financial services, where predictable cycle-based labor adjustments justify ongoing vendor relationships. Project-based staffing captures faster expansion within information technology, where agile delivery models and statement-of-work contracting align talent acquisition directly to software release timelines.
The US Department of Labor enforces Fair Labor Standards Act classification standards that shape how platforms structure contractor-versus-employee determinations, while the EU's Platform Work Directive establishes presumption-of-employment thresholds affecting cross-border gig arrangements. ISO 30414 human capital reporting standards increasingly influence how large corporations disclose contingent labor metrics to investors and regulators. Stakeholders must monitor how algorithmic management transparency requirements and portable benefits pilots in multiple jurisdictions reshape platform economics and client risk profiles.
Market Dynamics
AI-powered talent matching engines are compressing sourcing cycles from weeks to hours, while the US Department of Labor's evolving independent contractor classification rules under the Fair Labor Standards Act force platforms to restructure compliance architectures and liability frameworks.
Growth Catalysts
- Healthcare Surge Demand:Hospital systems facing patient volume spikes are embedding temporary clinical staffing into core workforce planning, with seasonal flu cycles and elective procedure backlogs creating predictable procurement rhythms.
- Fair Labor Standards Act Compliance Automation:Platforms investing in real-time classification algorithms reduce client misclassification exposure and accelerate enterprise sales cycles.
- Agile IT Delivery Models:Software release timelines measured in sprints rather than quarters drive statement-of-work contracting for specialized developers and cloud architects.
Market Restraints
- Benefit Cost Escalation:Portable benefits pilots in California and New York threaten to transfer insurance and retirement burdens back to staffing platforms, eroding the liability-transfer value proposition.
- Talent Pool Fragmentation:Skill scarcity in cybersecurity and data engineering concentrates viable candidate pools in Austin, Seattle, and San Francisco, inflating rate premiums and extending fill times.
- Platform Work Directive Friction:The EU's presumption-of-employment thresholds complicate cross-border contractor engagement for US-based platforms serving European enterprise clients.
Strategic Opportunities
- Germany's Skilled Immigration Act:Streamlined work visa pathways for non-EU IT professionals create arbitrage opportunities for platforms building localized compliance and payroll infrastructure.
- ISO 30414 Human Capital Reporting:Mandatory contingent labor disclosure requirements for large corporations elevate analytics capabilities from nice-to-have to procurement gatekeeping criteria.
- AI-Compliance Convergence:Natural language processing engines that parse jurisdiction-specific employment law variations in real time differentiate platform offerings for multi-national employers.
Industry Challenges
- Algorithmic Management Transparency Mandates:New York City's automated employment decision tools law requires audit trails for AI-driven candidate ranking, forcing engineering investment and slowing product roadmaps.
- Legacy HRIS Integration Complexity:Enterprise clients demand seamless data flow between contingent platforms and incumbent Workday or SAP implementations, stretching implementation timelines and professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contingent Staffing Solutions Market |
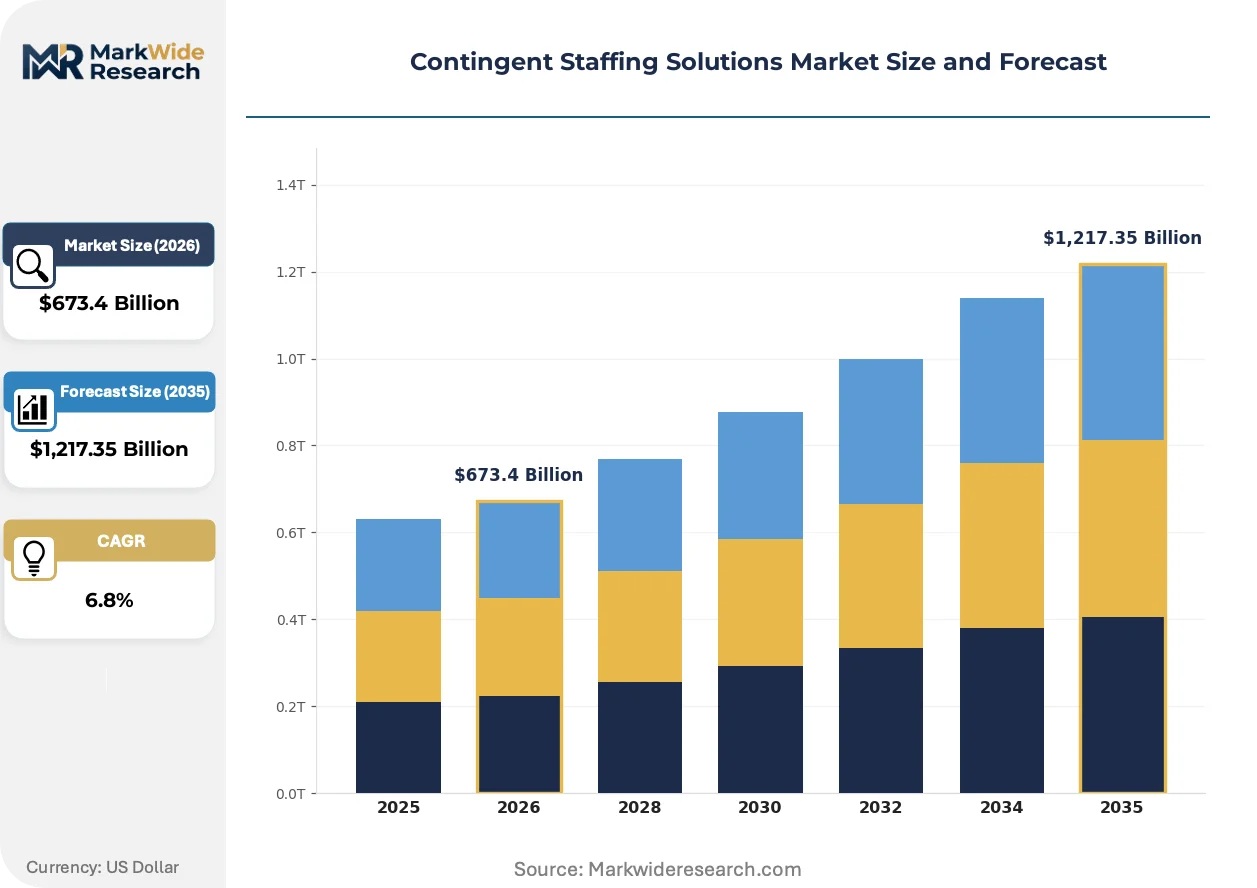
| Market Size in 2026 | $673.4 Billion |
| Market Size in 2035 | $1,217.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temporary Staffing, Contract Staffing, Project-Based Staffing, Freelance Staffing, Seasonal Staffing Industry: Information Technology, Manufacturing, Financial Services, Healthcare Providers, Education Services Client Type: Small Enterprises, Mid-Sized Companies, Large Corporations, Non-Profit Organizations, Government Agencies Engagement Model: Master Vendor, Neutral Vendor, Managed Service Provider, Recruitment Process Outsourcing, Statement of Work |
| Companies Covered | Deel, Upwork, ADP, SAP, Magnit, Allegis Global Solutions, Randstad Sourceright, Beeline, KellyOCG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contingent Staffing Solutions Market Trends and Innovations
Workforce management platforms are embedding predictive analytics and blockchain credential verification to compress trust-building timelines and reduce compliance overhead in distributed hiring scenarios.
Natural language processing engines are digitizing contract review and jurisdiction-specific compliance checks that previously required specialized legal teams. Large healthcare systems and financial services firms are deploying these tools at scale, cutting onboarding documentation processing from days to minutes. The structural compression is eliminating regional staffing brokers who historically intermediated compliance expertise.
The EU's Platform Work Directive establishes presumption-of-employment thresholds that reclassify gig workers as employees unless platforms prove otherwise. This regulatory architecture forces US-based staffing firms to restructure European operations or exit certain service categories. German and French enterprise clients now prioritize vendors with demonstrated compliance infrastructure over rate competitiveness.
Managed service provider consolidation is displacing fragmented vendor management office structures at Fortune 500 employers. Procurement teams are consolidating spend under single-platform umbrellas that aggregate time tracking, compliance verification, and payment orchestration. This concentration is most visible in US manufacturing and logistics, where seasonal volume swings demand rapid workforce elasticity without administrative multiplication.
Contingent Staffing Solutions Market Segmentation
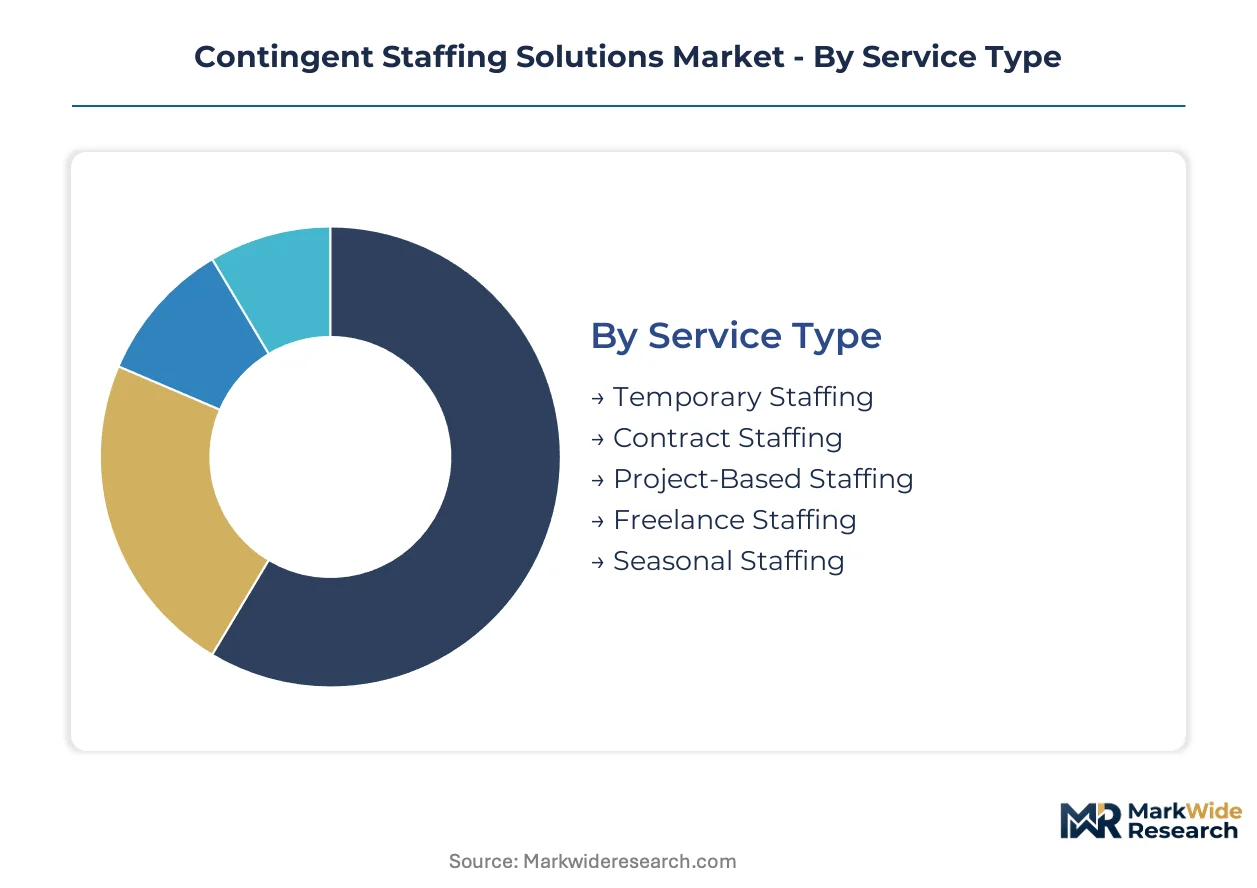
Contingent staffing solutions fragment across service delivery modes, client scale tiers, and procurement architectures. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape vendor selection criteria.
Service Type:
Temporary arrangements span single-day deployments to multi-year engagements, creating a use-case spectrum from crisis response to strategic workforce planning.
- Temporary Staffing:Short-duration placements typically covering absences, peak seasons, or emergency backfills. Manufacturing plants in the US Midwest and healthcare systems in Texas deploy these arrangements for predictable cycle-based labor adjustments.
- Contract Staffing:Fixed-term engagements with defined deliverables and embedded supervision. Financial services firms in New York and London concentrate demand here for regulatory project surges and system migration timelines.
- Project-Based Staffing:Outcome-oriented talent clusters assembled for discrete initiatives. IT departments favor this model for cloud migration and cybersecurity implementations where scope clarity supports statement-of-work contracting.
- Freelance Staffing:Individual contributor engagements brokered through marketplace platforms. Creative agencies and software startups tap this segment for specialized skills without employment overhead.
- Seasonal Staffing:Calendar-driven volume spikes in retail, agriculture, and logistics. Warehouse operators near Chicago and Atlanta scale headcount by 300-400% during holiday fulfillment windows.
The dominant share belongs to Temporary Staffing, while Project-Based Staffing is closing the gap fastest.
Industry:
Vertical specialization determines compliance complexity and rate benchmarking precision, with regulated sectors commanding premium vendor margins.
- Information Technology:Software development, infrastructure operations, and data engineering roles dominate. Agile delivery models in Seattle, Austin, and Bangalore drive statement-of-work proliferation for DevOps and AI/ML talent.
- Manufacturing:Assembly line coverage, quality inspection, and maintenance staffing. Automotive suppliers in Michigan and electronics contract manufacturers in Mexico rely on master vendor arrangements for volume flexibility.
- Financial Services:Risk management, compliance, and technology transformation staffing. Banks in New York, London, and Singapore embed contingent workers in regulatory remediation and digital banking builds.
- Healthcare Providers:Clinical and administrative temporary labor for patient surges. Hospital systems facing flu season spikes and elective procedure backlogs structure predictable procurement rhythms with specialty staffing firms.
- Education Services:Substitute teaching, administrative support, and curriculum development. School districts in California and Texas use managed service providers to consolidate fragmented substitute teacher sourcing.
Information Technology commands the largest revenue pool, though Healthcare Providers exhibit the steepest expansion trajectory.
Client Type:
Organizational scale dictates procurement sophistication, with enterprise buyers consolidating spend under single-platform umbrellas.
- Small Enterprises:Businesses with under 100 employees accessing contingent labor through self-serve marketplaces. Limited procurement staff drives preference for simple onboarding and transparent pricing.
- Mid-Sized Companies:Organizations with 100-999 employees building vendor management office capabilities. These buyers balance rate competitiveness with compliance infrastructure as they scale contingent spend.
- Large Corporations:Fortune 1000 employers with mature managed service provider relationships. Procurement teams demand real-time analytics, global payroll integration, and ISO 30414 human capital reporting alignment.
- Non-Profit Organizations:Mission-driven entities with constrained budgets and grant-funded staffing. These clients prioritize cost control over technology sophistication in vendor selection.
- Government Agencies:Federal, state, and municipal entities with strict classification and security clearance requirements. US Department of Labor compliance automation becomes table stakes for platform eligibility.
Large Corporations anchor vendor revenue, while Mid-Sized Companies are gaining share fastest as procurement maturation accelerates.
Engagement Model:
Procurement architecture determines liability allocation and administrative burden distribution between client and intermediary.
- Master Vendor:Single staffing firm assumes primary fulfillment responsibility with secondary supplier management. Manufacturing clients favor this model for speed and accountability in high-volume scenarios.
- Neutral Vendor:Third-party administrator coordinates multiple staffing suppliers without self-fulfillment. This structure appeals to healthcare systems seeking rate transparency and supplier diversity.
- Managed Service Provider:Comprehensive platform integrating sourcing, compliance, time tracking, and payment orchestration. Fortune 500 employers standardize on this model for global contingent workforce governance.
- Recruitment Process Outsourcing:Transfer of permanent hiring function to external provider, sometimes with contingent labor add-on. Financial services firms deploy RPO for talent pipeline building ahead of conversion.
- Statement of Work:Outcome-based contracting for discrete deliverables with minimal supervision. IT departments leverage SOW structures for agile project staffing with clear acceptance criteria.
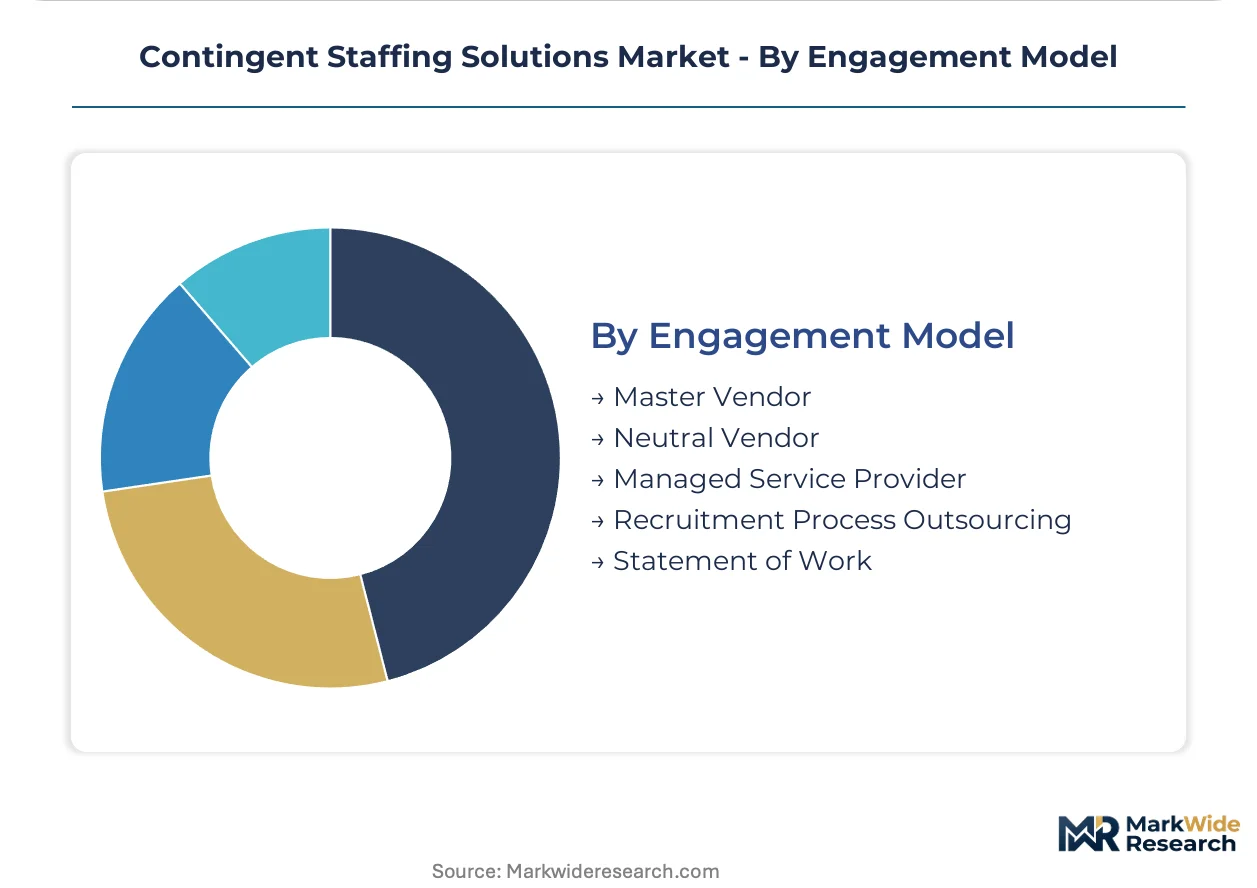
Managed Service Provider arrangements hold the dominant position, though Statement of Work contracting is climbing fastest as project-based IT staffing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 employers concentrate contingent staffing procurement in the United States, where managed service provider adoption has become standard practice. Mid-sized companies in Germany and the United Kingdom are accelerating procurement maturation. Healthcare systems in India and Brazil are embedding temporary clinical staffing into core workforce planning.
United States
Hospital systems facing patient volume spikes drive demand for temporary clinical staffing, with seasonal flu cycles creating predictable procurement rhythms. The US Department of Labor enforces Fair Labor Standards Act classification standards that reshape platform compliance architectures. Enterprise adoption concentrates in Chicago and Atlanta warehouse corridors, where seasonal fulfillment demand scales headcount by 300-400% during holiday windows.
Germany
Automotive suppliers and electronics contract manufacturers rely on master vendor arrangements for volume flexibility in assembly line coverage. The Skilled Immigration Act streamlines work visa pathways for non-EU IT professionals, creating arbitrage opportunities for platforms building localized infrastructure. Industrial demand clusters in Bavaria and Baden-Württemberg, where precision manufacturing maintains entrenched seasonal adjustment patterns.
United Kingdom
Financial services firms in London concentrate demand for regulatory project surges and system migration timelines through fixed-term contract staffing. The country's employment tribunal system shapes contractor-versus-employee determinations for cross-border platforms. Technology transformation staffing accelerates in the Southeast corridor, where digital banking builds require specialized compliance and risk management talent.
India
Software development and data engineering roles dominate contingent demand, with agile delivery models driving statement-of-work proliferation for DevOps and AI/ML talent. The country's central bank and securities regulator influence how staffing platforms structure payment orchestration and compliance verification. Bangalore and Hyderabad anchor the IT staffing expansion, where global capability centers embed contingent workers in sprint-based delivery models.
Brazil
São Paulo-based financial institutions and industrial conglomerates are consolidating fragmented vendor management office structures under single-platform umbrellas. The country's national labor regulator shapes classification standards that affect platform liability frameworks. Manufacturing and logistics operations in the Southeast region deploy seasonal staffing for agricultural and retail fulfillment cycles, compressing trust-building timelines through predictive analytics adoption.
Contingent Staffing Solutions Market Competitive Landscape
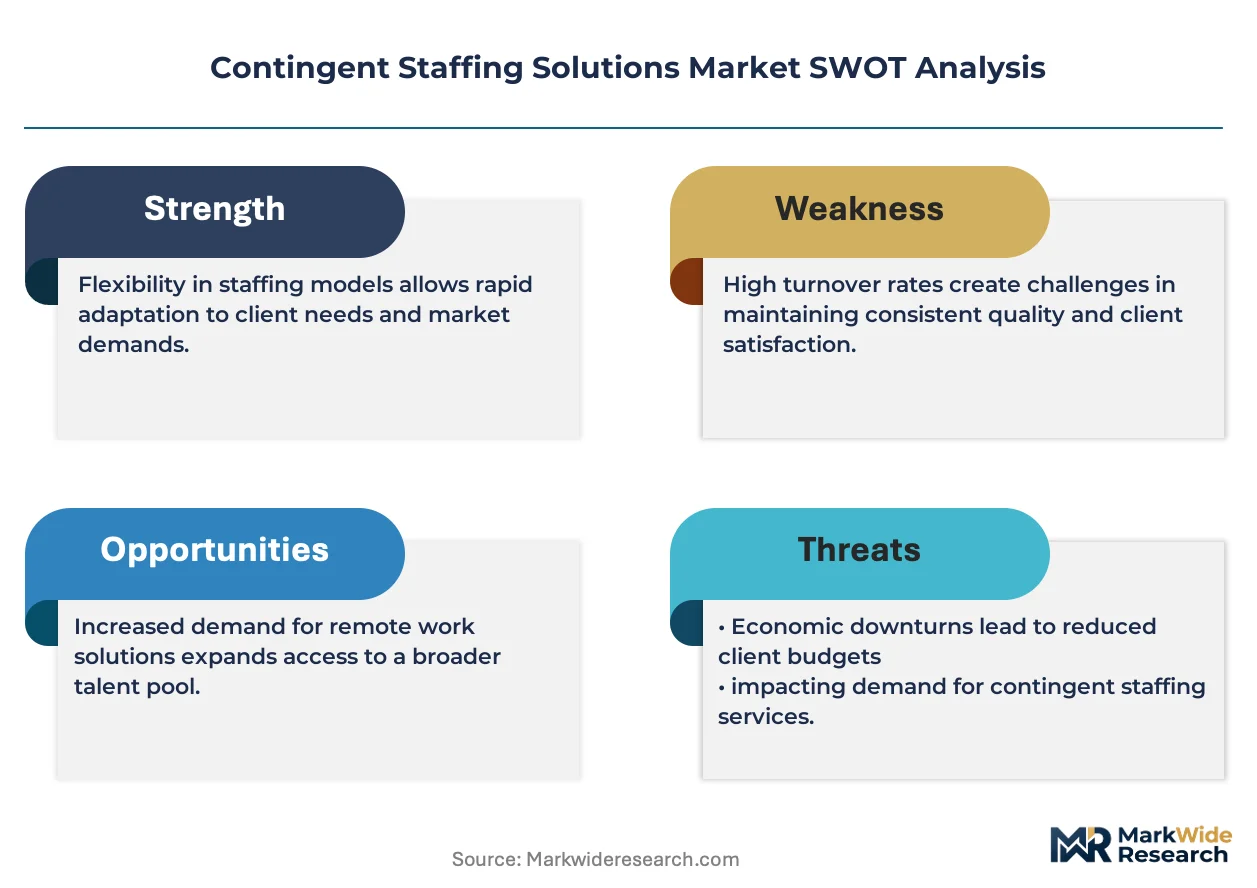
Channel-controlling players compete with product-specialist players across a market structure that concentrates revenue among Fortune 500-focused managed service providers while fragmenting among self-serve marketplaces serving small enterprises. The vendor base stratifies into three tiers: global payroll infrastructure operators, marketplace platforms competing on transaction velocity, and analytics-specialist managed service providers. Consolidation through single-platform umbrellas and AI-powered compliance automation represent the dominant competitive moves reshaping procurement relationships.
Within the global payroll infrastructure tier, Deel leverages cross-border contractor engagement capabilities spanning over 150 countries. Upwork exemplifies the marketplace archetype competing on skill-category breadth for knowledge-work assignments. Magnit occupies a position within the analytics-specialist tier, differentiating through real-time labor cost benchmarking for enterprise contingent workforce governance. These three anchors illustrate how platform economics diverge based on whether competitive positioning centers on geographic reach, transaction efficiency, or data-driven procurement intelligence.
| Leading Market Players |
|---|
| Deel |
| Upwork |
| ADP |
| SAP |
| Magnit |
| Allegis Global Solutions |
| Randstad Sourceright |
| Beeline |
| KellyOCG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in the US temporary staffing corridor compresses rate premiums and forces suppliers toward automation investments that reshape both margin structures and client procurement postures.
Pricing Analysis
Cost-plus contracts indexed to Bureau of Labor Statistics wage data dominate enterprise engagements, with markups scaling by certification tier and geographic labor market tightness. Price differentiation hinges on ISO 30414 human capital reporting compliance and real-time analytics integration, with premium tiers commanding substantial spreads over basic staffing arrangements. Pricing pressure stems from portable benefits pilots in California and New York threatening to transfer insurance burdens back to platforms. Small enterprises exhibit acute price sensitivity through self-serve marketplace selection, while Fortune 500 buyers prioritize compliance infrastructure over rate competitiveness.
Supply Chain Analysis
Tariff exposure between the United States and India dominates platform risk profiles as cross-border payment orchestration faces regulatory friction. Supply concentration clusters in the United States, India, and Germany, with talent pool fragmentation in cybersecurity and data engineering creating single-source vulnerability for specialized roles. Raw material dependencies center on AI-powered matching engines, blockchain credential verification infrastructure, and compliance automation software licenses. Distribution runs through managed service provider consolidations that displace fragmented vendor management office structures at large employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Fortune 500 procurement teams consolidating contingent spend under single-platform umbrellas, fragmenting vendor relationships that once sustained regional brokers.
For Market Incumbents: Pre-empt algorithmic management transparency mandates by embedding audit-ready AI decision trails before New York City enforcement deadlines erode competitive positioning. Invest in backward integration into compliance automation software to capture margin pools currently flowing to third-party legal tech vendors, while defending against marketplace platforms competing on transaction velocity through embedded analytics differentiation. For New Entrants and Emerging Players: Pursue white-space expansion in Germany's Skilled Immigration Act corridor, where streamlined visa pathways for non-EU IT professionals create arbitrage opportunities for platforms building localized payroll infrastructure. Target mid-sized companies in the United Kingdom accelerating procurement maturation, with a direct-to-procurement-officer go-to-market angle emphasizing rapid Workday integration and transparent rate benchmarking. For Investors and Strategic Acquirers: Capital is best deployed toward analytics-specialist managed service providers with demonstrated ISO 30414 alignment and real-time labor cost benchmarking capabilities that procurement gatekeepers now require. Watch for inflection signals in EU Platform Work Directive enforcement severity that would reclassify gig workers as employees and reshape platform economics across European operations.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Compliance Convergence Investment | Natural language processing engines parsing jurisdiction-specific employment law variations differentiate offerings for multi-national employers. |
| Managed Service Provider Consolidation | Single-platform umbrellas aggregating time tracking and payment orchestration displace fragmented vendor management office structures. |
| Portable Benefits Infrastructure Buildout | California and New York pilots threaten liability-transfer value propositions, forcing platform-side insurance and retirement fund integration. |
| Cross-Border Payroll Localization | Germany's Skilled Immigration Act creates arbitrage for platforms building compliant infrastructure across 150-country contractor networks. |
| Blockchain Credential Verification Deployment | Distributed trust-building compresses onboarding timelines from days to minutes, eliminating regional staffing broker intermediation. |
Research Methodology
Initial hypotheses were tested against primary input from chief procurement officers, vendor management office directors, staffing platform executives, and compliance automation engineers and refined through secondary validation against SEC filings, US Department of Labor enforcement data, EU Platform Work Directive regulatory texts, and ISO 30414 implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic labor market indicators anchored the value estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning service type, client scale tier, engagement model, and geographic regulatory cluster. CAGRs derived from trend extrapolation of historical procurement patterns and scenario-weighted regulatory outcome probabilities incorporated healthcare surge demand cyclicality and agile IT delivery model adoption curves as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global payroll infrastructure operators or analytics-specialist managed service providers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
IT Staffing Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Europe Warehouse Management Systems Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Shared Services Center Market