
 Enterprise Data Loss Prevention (DLP) Services Market | 2026-2036
Enterprise Data Loss Prevention (DLP) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Data Loss Prevention (DLP) Services Market Insights
Cybersecurity talent scarcity is rotating enterprise procurement toward managed DLP services that reduce in-house operational burden. Microsoft leverages its cloud infrastructure dominance to anchor hybrid DLP deployments across enterprise clients. Palo Alto Networks competes through integrated network-level and cloud application security positioning. Broadcom specializes in endpoint-level DLP with deep operating system hooks that sustain technical differentiation against platform-agnostic rivals.
Enterprise Data Loss Prevention (DLP) Services encompass policy-driven monitoring, classification, and blocking systems that inspect data in motion across network egress points, data at rest within storage repositories, and data in use on endpoint devices, typically employing content inspection engines that match against fingerprinted intellectual property, regulated data patterns, and behavioral anomaly baselines. These systems serve the primary commercial purpose of preventing unauthorized exfiltration of sensitive records while generating audit trails for regulatory examination. Cloud-based DLP now leads service type growth as remote work architectures displace perimeter-centric security models, while managed DLP captures expanding margin pools by converting capital expenditure into recurring operational contracts. Network-level deployment retains the largest installed base among deployment modes, though cloud applications security is accelerating fastest as SaaS adoption deepens.
FCC guidelines on telecommunications data protection, SEC cybersecurity disclosure rules, and HIPAA safeguards for healthcare records collectively shape product requirements and procurement urgency across the United States. The EU AI Act and GDPR enforcement in Europe impose parallel compliance architectures that vendors must engineer into multi-jurisdictional service offerings. Stakeholders must monitor how NIS2 implementation across EU member states reclassifies DLP investment from discretionary security spending to mandatory critical infrastructure obligation.
Market Dynamics
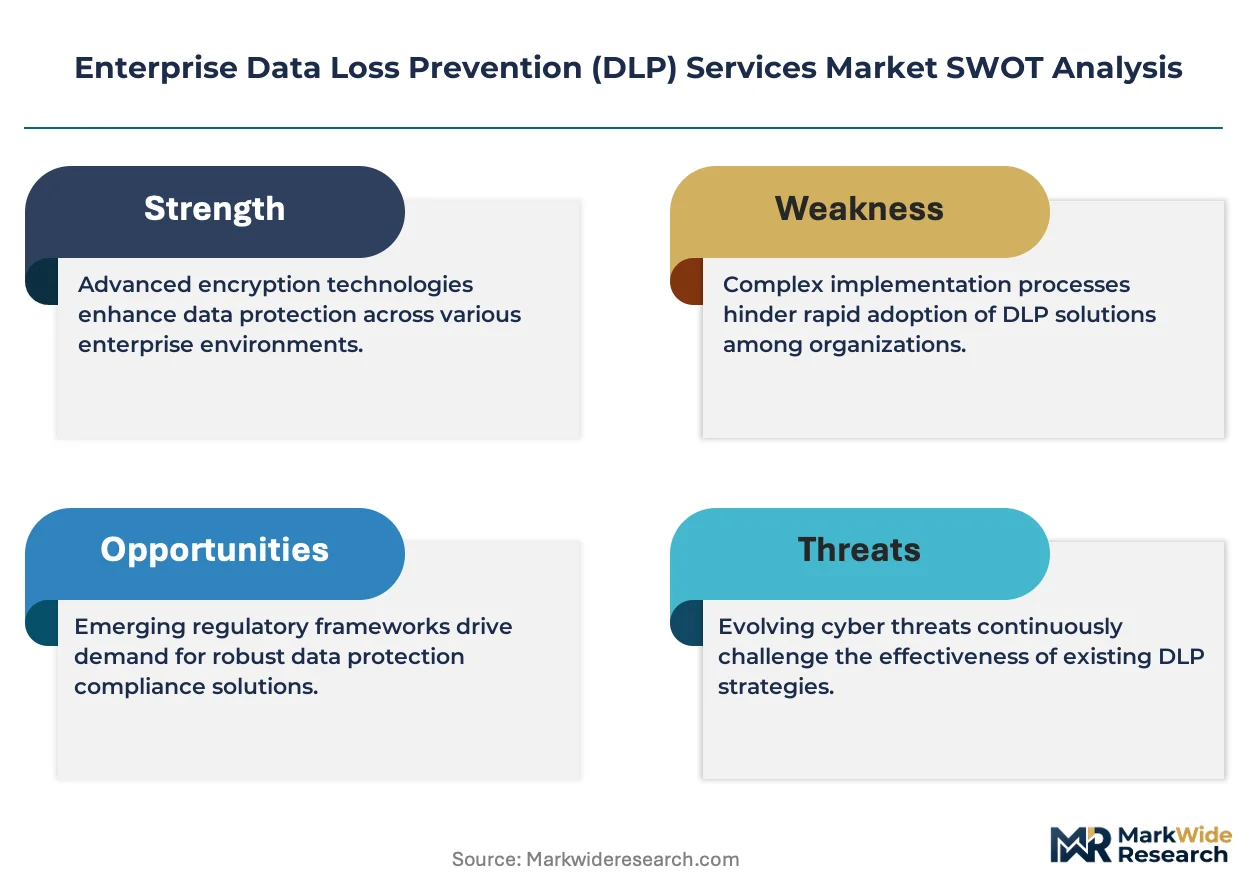
Cloud migration is fragmenting the traditional network-perimeter security model, forcing enterprises to reconstruct data protection architectures around distributed SaaS applications and remote endpoints rather than centralized gateways.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must implement automated data classification and audit trails for AI training datasets, accelerating managed DLP procurement.
- Healthcare records digitization:HIPAA safeguards enforcement is tightening across US hospital systems, requiring endpoint-level monitoring for patient data access.
- Insider threat sophistication:Financial services firms in Japan are deploying behavioral analytics overlays to detect anomalous data access patterns before exfiltration occurs.
Market Restraints
- Specialized engineering talent scarcity:DLP policy tuning and incident response require rare combinations of security operations and data governance expertise, inflating service delivery costs.
- Cloud infrastructure concentration:Three hyperscale providers dominate underlying compute for cloud-based DLP, creating vendor lock-in risks and pricing leverage asymmetries.
- Encryption protocol limitations:Homomorphic encryption remains computationally prohibitive for real-time content inspection at enterprise data volumes, constraining privacy-preserving detection methods.
Strategic Opportunities
- German Mittelstand underpenetration:Mid-sized industrial enterprises in Germany lack dedicated security operations centers, creating whitespace for fully managed DLP services with native German language support.
- Operational technology convergence:Manufacturing environments are merging IT and OT networks, opening demand for DLP solutions that inspect data flows between enterprise systems and industrial control platforms.
- SEC cybersecurity disclosure rules:US public companies must now report material data security incidents within four business days, converting DLP from discretionary security spend to board-level governance infrastructure.
Industry Challenges
- Multi-cloud policy orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud environments struggle to maintain consistent data classification schemas and blocking rules without configuration drift.
- False positive management burden:Overly sensitive content inspection engines generate excessive alert volumes that overwhelm security operations teams and erode trust in automated blocking decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Data Loss Prevention (DLP) Services Market |
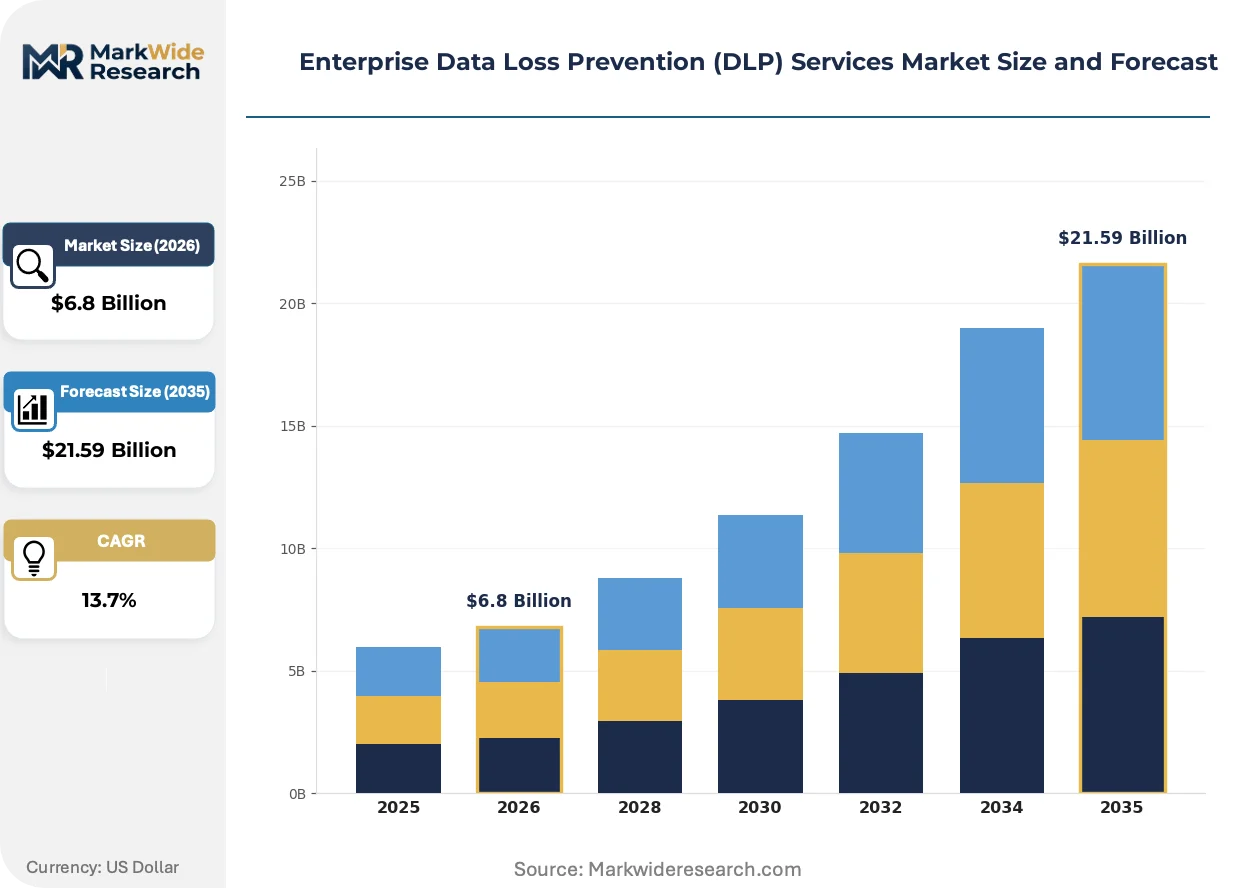
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed DLP, On-Premise DLP, Cloud-Based DLP, Hybrid DLP, Consulting Services Deployment Mode: Network Level, Endpoint Level, Cloud Applications, Email Security, Storage Security Application: Data Compliance, Insider Threat Protection, Intellectual Property Security, Privacy Management, Regulatory Reporting End User Industry: IT & Telecommunications, Banking, Insurance, Government Agencies, Education |
| Companies Covered | Broadcom, Microsoft, IBM, Forcepoint, Proofpoint, Trend Micro, Fortra, Palo Alto Networks, Digital Guardian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Data Loss Prevention (DLP) Services Market Trends and Innovations
Generative AI adoption is introducing novel data exfiltration vectors through prompt injection and model training data harvesting, compelling DLP vendors to develop entirely new detection heuristics and response playbooks.
Agentic AI security controls are fragmenting the traditional DLP architecture by embedding autonomous monitoring capabilities directly within business applications rather than relying on network interception points. Salesforce and ServiceNow are piloting native data protection modules that inspect content at the moment of user interaction. This architectural shift is compressing margins for standalone DLP vendors that lack deep application integrations.
The EU AI Act risk classification framework is mandating automated data lineage tracking for high-risk AI systems deployed across European member states. Enterprises must now demonstrate continuous monitoring of training data provenance and model output distribution. Financial services and healthcare verticals are responding by integrating DLP with MLOps pipelines to satisfy audit requirements.
Security service unbundling is accelerating as enterprises separate detection tooling from managed response functions. Large manufacturers in Japan are increasingly procuring cloud-native DLP software directly while outsourcing tier-1 alert triage to regional managed security providers. This bifurcation is most pronounced in automotive supply chains where original equipment manufacturers impose strict data handling clauses on component suppliers.
Enterprise Data Loss Prevention (DLP) Services Market Segmentation
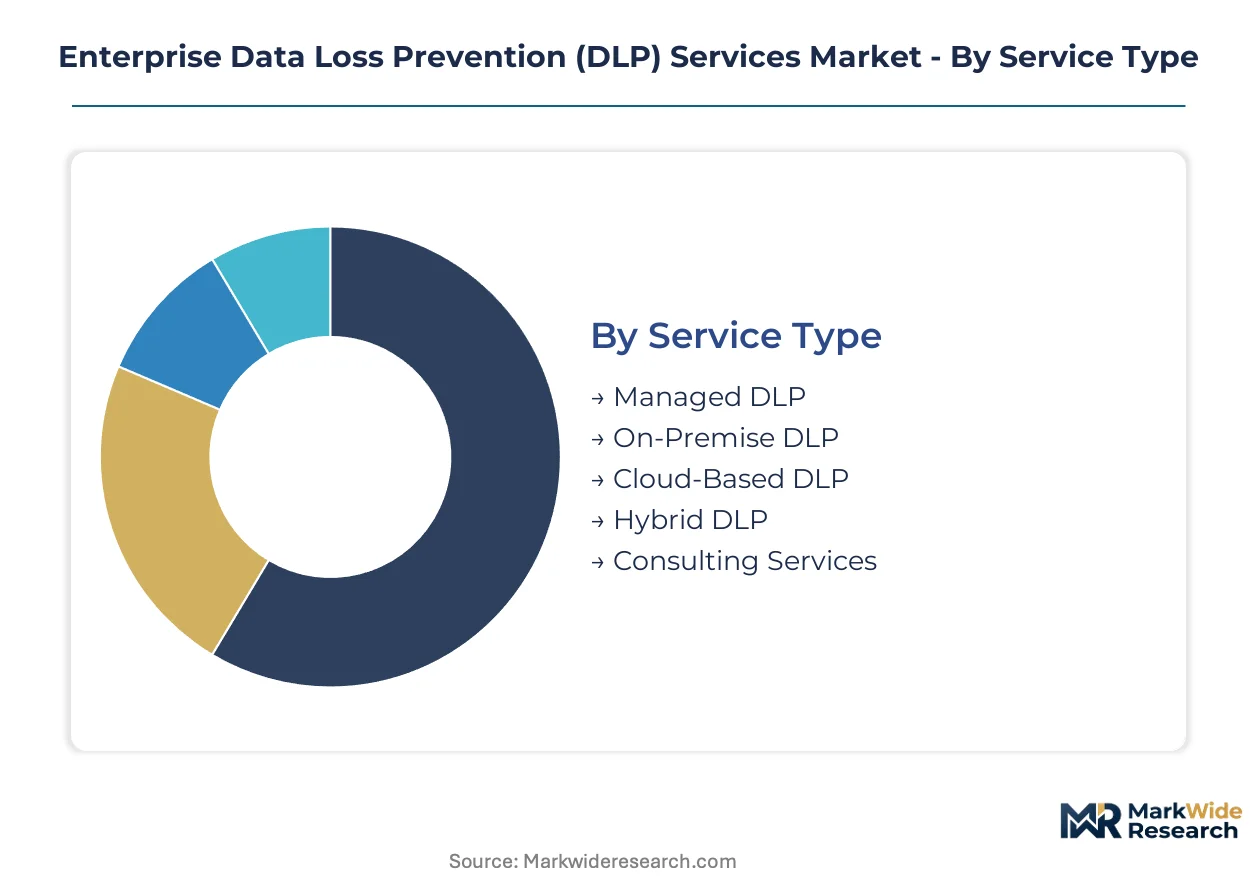
Enterprise DLP services fragment across four structural dimensions that determine procurement patterns and vendor positioning. Service type and deployment mode capture the largest margin pools, while application focus and end-user industry dictate compliance integration depth and contract duration.
Service Type:
Margin concentration sits with recurring operational models that convert capital expenditure into subscription revenue streams.
- Managed DLP:Fully outsourced security operations covering policy tuning, incident response, and compliance reporting. Demand concentrates among US financial services firms facing SEC cybersecurity disclosure deadlines and HIPAA-mandated healthcare systems requiring 24/7 monitoring capabilities without in-house SOC investment.
- Cloud-Based DLP:Native SaaS delivery inspecting data flows across distributed cloud applications and remote endpoints. German industrial enterprises and Japanese automotive suppliers are deploying these services fastest as perimeter-centric architectures collapse under hybrid work models.
- On-Premise DLP:Hardware and software deployed within customer data centers for air-gapped environments.
- Hybrid DLP:Integrated on-premise and cloud-native components orchestrated through unified policy management.
- Consulting Services:Advisory engagements for data classification schema design and regulatory gap assessments.
The dominant share belongs to Managed DLP, while Cloud-Based DLP is closing the gap fastest.
Deployment Mode:
Volume leadership reflects legacy infrastructure commitments, though architectural displacement is redirecting procurement toward inspection points embedded within business applications.
- Network Level:Gateway appliances inspecting data in motion at egress boundaries. Banking networks in Japan and telecommunications carriers in Germany retain substantial installed bases due to high-throughput requirements and established operational playbooks.
- Cloud Applications:API-native inspection of SaaS platforms including Salesforce, ServiceNow, and Microsoft 365. US healthcare systems and German Mittelstand manufacturers are prioritizing these deployments to satisfy GDPR and EU AI Act data lineage mandates without proxy latency.
- Endpoint Level:Agent-based monitoring of data in use on laptops and workstations.
- Email Security:Specialized inspection of message content and attachments at mail gateway or cloud email service layers.
- Storage Security:Scanning of data at rest within file shares, object stores, and database repositories.
Network Level retains the largest footprint, though Cloud Applications deployment is expanding most quickly.
Application:
Compliance urgency varies by regulatory enforcement intensity, with data governance mandates in Europe and the United States driving premium pricing for integrated audit capabilities.
- Data Compliance:Automated classification and retention policy enforcement aligned to GDPR, HIPAA, and SEC rules. German automotive suppliers and US hospital systems are procuring these capabilities under direct board oversight following enforcement actions.
- Insider Threat Protection:Behavioral analytics detecting anomalous data access and exfiltration patterns. Japanese financial institutions and US insurance carriers are deploying these systems to satisfy internal risk committees and external auditor requirements.
- Intellectual Property Security:Fingerprinting and monitoring of trade secrets, source code, and product designs.
- Privacy Management:Subject rights request fulfillment and consent tracking workflows.
- Regulatory Reporting:Automated generation of audit trails and incident documentation for examiner review.
Data Compliance commands the largest contract values, while Insider Threat Protection is gaining share fastest among regulated verticals.
End User Industry:
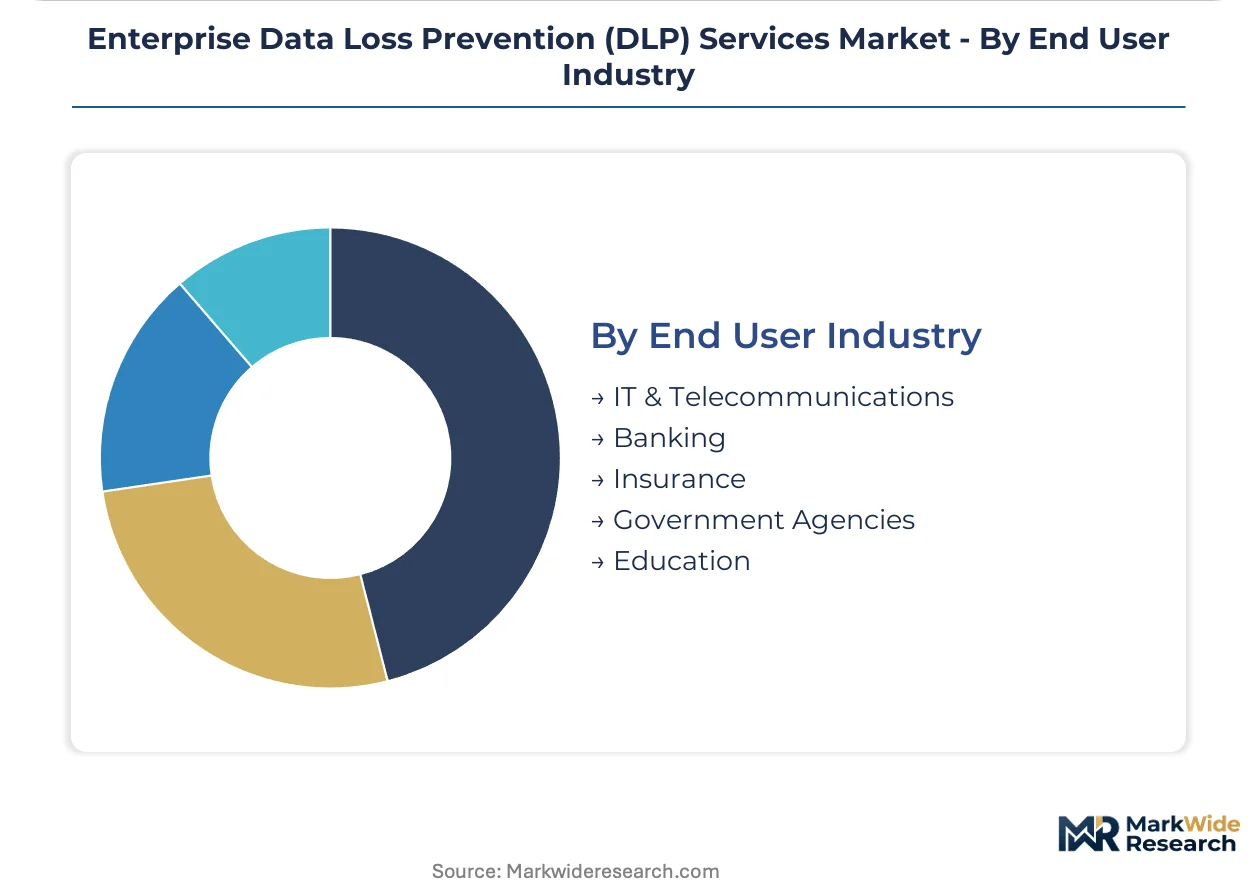
Customer concentration patterns reflect sector-specific data sensitivity and regulatory exposure, with financial services and government procurement cycles extending 18-36 months.
- Banking:Transaction monitoring, customer data protection, and anti-money laundering integration. Institutions in Japan and Germany are mandating DLP as a condition of correspondent banking relationships and ECB supervisory reviews.
- Government Agencies:Classified information handling and supply chain security compliance. US federal agencies and German state-level administrations are consolidating procurement through framework contracts that favor vendors with domestic data residency guarantees.
- IT & Telecommunications:Customer data management and infrastructure security for service providers.
- Insurance:Policyholder information protection and claims data governance.
- Education:Student records privacy and research data security for universities.
Banking maintains the deepest penetration, while Government Agencies are accelerating procurement most steeply under critical infrastructure designations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies, with United States enterprises prioritizing managed services for regulatory disclosure compliance while German manufacturers favor cloud-native deployments for EU AI Act alignment.
United States
Financial services firms and healthcare systems are accelerating procurement of managed DLP services to satisfy SEC cybersecurity disclosure rules and HIPAA safeguards enforcement. The FCC guidelines on telecommunications data protection shape product requirements for network-level deployments. New York and California host the densest concentrations of enterprise security operations centers.
Germany
Mid-sized industrial enterprises in the Mittelstand segment are driving demand for fully managed DLP services with native German language support and domestic data residency guarantees. The EU AI Act and GDPR enforcement impose automated data classification mandates. Bavaria and Baden-Württemberg industrial clusters are prioritizing cloud applications security for manufacturing supply chains.
Japan
Financial institutions and automotive suppliers are deploying behavioral analytics overlays for insider threat protection and correspondent banking compliance. METI industrial security guidelines influence procurement specifications for critical infrastructure operators. Tokyo and Osaka metropolitan areas concentrate the highest deployment volumes for endpoint-level monitoring.
United Kingdom
Enterprise procurement concentrates on hybrid DLP architectures bridging on-premise legacy systems with cloud-native inspection points. The UK Information Commissioner's Office enforcement actions are tightening data governance requirements for financial services and insurance verticals. London's financial district and Manchester's technology corridor show the steepest adoption curves.
South Korea
Electronics manufacturers and semiconductor fabricators are integrating DLP with operational technology networks to protect intellectual property across IT-OT convergence points. MFDS data protection standards for medical device manufacturers create specialized compliance requirements. Seoul Capital Area and Busan-Ulsan industrial zones lead deployment activity for supply chain security.
Enterprise Data Loss Prevention (DLP) Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform-agnostic vendors competing against cloud-native entrants. The market structure reflects consolidation around vendors offering unified policy management across hybrid environments. Two strategic archetypes dominate: infrastructure-anchored platforms leveraging existing cloud relationships, and endpoint specialists with deep operating system integration. Competitive moves center on M&A for behavioral analytics capabilities and strategic partnerships for multi-cloud orchestration.
Within the infrastructure-anchored tier, Microsoft exemplifies platform leverage through cloud infrastructure dominance, while Palo Alto Networks occupies a position integrating network-level and cloud application security. Broadcom represents the endpoint specialist archetype with technical differentiation through operating system-level deployment. These three companies anchor the competitive structure without exhausting the vendor ecosystem.
| Leading Market Players |
|---|
| Broadcom |
| Microsoft |
| IBM |
| Forcepoint |
| Proofpoint |
| Trend Micro |
| Fortra |
| Palo Alto Networks |
| Digital Guardian |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure utilization rates above 80% create steep economies of scale that compress unit economics for managed DLP providers while establishing price floors for mid-tier competitors lacking comparable compute leverage. This concentration dynamic shapes procurement negotiations across US financial services and German industrial verticals.
Pricing Analysis
Contract structures in enterprise DLP services favor multi-year managed service agreements with annual recurring revenue escalation clauses rather than spot procurement or project-based engagements. Three-tier pricing structure across premium, standard, and economy levels separates fully managed SOC capabilities from software-only SaaS tiers and basic consulting engagements. Pricing pressure stems from hyperscaler bundling of native DLP modules within existing cloud contracts, eroding standalone vendor margins. Mid-sized German Mittelstand manufacturers exhibit highest price sensitivity due to constrained security budgets, while US banking institutions demonstrate lowest sensitivity given regulatory disclosure mandates.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-based DLP delivery, though strategic stockpiling of specialized engineering talent occurs in India and Poland where security operations expertise concentrates. Software development and policy engineering draw from talent pools in the United States, Israel, and Ireland, while cloud compute infrastructure rests on hyperscaler data centers concentrated in Virginia, Frankfurt, and Tokyo. Single-source vulnerability sits with three dominant cloud providers controlling underlying infrastructure. Distribution runs through direct enterprise sales teams supplemented by regional managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals combining data governance expertise with security operations proficiency constrains service delivery capacity across all vendor tiers, creating durable competitive moats for firms with established training pipelines.
For Market Incumbents: Consolidate market position through targeted acquisition of behavioral analytics specialists to offset agentic AI displacement of traditional network inspection architectures. Deepen vertical integration into cloud-native policy orchestration layers to defend margin pools against hyperscaler bundling. Prioritize certification investment for EU AI Act compliance tooling to capture German automotive and financial services procurement cycles. For New Entrants and Emerging Players: Anchor in the German Mittelstand segment where fully managed DLP services with native German language support remain underpenetrated relative to large enterprise saturation. Target US healthcare systems requiring HIPAA-mandated endpoint monitoring without internal SOC investment. Pursue channel partnerships with regional managed security providers rather than direct enterprise sales to accelerate customer acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors endpoint specialists with deep operating system integration over platform-agnostic network gateway vendors as architectural gravity shifts toward application-embedded controls. Long-term viability hinges on MLOps pipeline integration capabilities for AI training data lineage tracking. The signal to watch is hyperscaler announcement of native behavioral analytics modules that would compress standalone vendor addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Behavioral Analytics Specialist | Fortifies detection capabilities against insider threat vectors in financial services. |
| EU AI Act Compliance Certification | Unlocks procurement from German automotive suppliers under direct board oversight. |
| Native Cloud Application Integration | Embeds monitoring within Salesforce and ServiceNow to counter agentic AI fragmentation. |
| Managed SOC Service Expansion | Captures recurring revenue from US healthcare systems lacking 24/7 internal operations. |
| MLOps Pipeline Partnership | Satisfies automated data lineage mandates for high-risk AI systems in European deployments. |
Research Methodology
Desk research of vendor financial disclosures, regulatory filing databases, and cloud infrastructure capex reports preceded structured interviews with CISOs at financial services institutions, healthcare system IT directors, and managed security service provider executives. Primary fieldwork captured procurement decision criteria and pricing sensitivity across US, German, and Japanese enterprise segments. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, and HIPAA enforcement action records. Bottom-up service revenue estimates triangulated against top-down market sizing from cloud infrastructure spend allocations.
Variance decomposition across service type, deployment mode, application focus, and end-user industry dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured managed versus cloud-native delivery, network versus endpoint versus cloud application inspection points, compliance versus insider threat versus intellectual property use cases, and banking versus healthcare versus government verticals. CAGRs were derived from elasticity modeling of security spend to regulatory enforcement intensity and cloud migration velocity. Forecast inputs incorporated hyperscaler DLP module bundling announcements and NIS2 implementation timelines across EU member states.
Material uncertainties — regulatory enforcement intensity variations, hyperscaler competitive bundling decisions, and encryption technology breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about sustained cloud migration trends and steady-state regulatory compliance mandates. Revision becomes warranted when hyperscaler native DLP capability announcements cross thresholds that materially alter standalone vendor competitive position.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Supplier Management Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Managed Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
IT Staffing Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Field Service Management Market
Enterprise Services
Middle East and Africa Enterprise Software Market