
 Artificial Intelligence in Supply Chain Management Market | 2026-2036
Artificial Intelligence in Supply Chain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Supply Chain Management Market Outlook
Third-party logistics providers is bifurcating demand away from traditional manufacturer-led procurement, as asset-light intermediaries seek predictive visibility tools that shippers historically bought directly. IBM leverages its Watson supply chain suite to anchor enterprise accounts in North America with deep ERP integration. SAP competes through native S/4HANA connectivity that reduces deployment friction for existing customers. o9 Solutions specializes in digital twin modeling for discrete manufacturing, occupying a narrow but defensible niche in demand-sensing accuracy.
Artificial intelligence in supply chain management encompasses machine learning algorithms, natural language processing engines, and optimization solvers deployed to automate planning, execution, and monitoring workflows across procurement, production, and distribution networks. These systems process multi-source telemetry from IoT sensors, EDI transactions, and external demand signals to generate prescriptive recommendations with latency targets under five minutes for critical path decisions. Software dominates current revenue as enterprises prioritize subscription-based demand forecasting and inventory optimization modules over capital-intensive hardware. Cloud-based deployment is expanding fastest among mid-market logistics providers that lack internal data center capacity. Edge computing remains nascent but carries concentrated margin pools in cold chain and autonomous fleet applications where millisecond response requirements disqualify centralized architectures.
The EU AI Act imposes risk-tiered conformity assessments on automated supply chain decision systems, compelling vendors to document algorithmic transparency and human oversight protocols before market access. The FDA and FAA maintain parallel requirements for AI-enabled pharmaceutical cold chain and drone logistics respectively, fragmenting compliance burdens across jurisdictions. Stakeholders must monitor how divergent algorithmic accountability standards reshape vendor qualification criteria and procurement specifications.
Market Dynamics
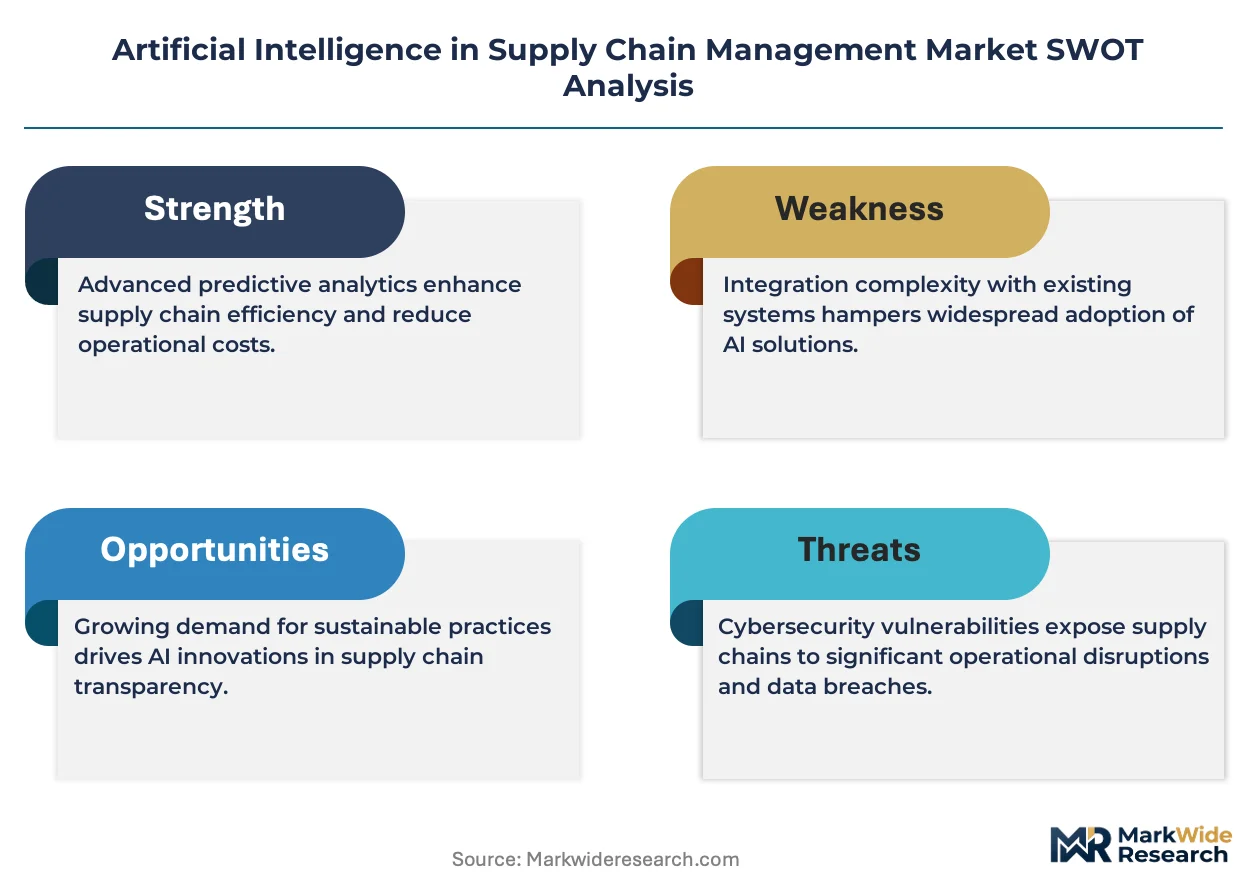
Third-party logistics providers are accelerating AI procurement faster than direct shippers, compressing deployment timelines and forcing vendors to rearchitect solutions for asset-light intermediaries rather than enterprise manufacturers.
Growth Catalysts
- EU AI Act compliance mandates:Automated supply chain decision systems face tiered conformity assessments in Brussels, compelling enterprises to upgrade legacy planning engines to meet algorithmic transparency requirements.
- Discrete manufacturing digital twins:Demand-sensing accuracy investments in automotive and electronics clusters around Munich and Stuttgart are piloting autonomous control towers with sub-five-minute latency targets.
- Cloud-native deployment elasticity:Mid-market logistics providers lacking internal data center capacity are expanding fastest in subscription-based demand forecasting modules.
Market Restraints
- Algorithmic accountability fragmentation:Divergent FDA pharmaceutical cold chain requirements and FAA drone logistics rules create multi-jurisdictional compliance burdens that disqualify standardized product architectures.
- Edge computing capex intensity:Millisecond response requirements in cold chain and autonomous fleet applications demand localized hardware investments that centralized cloud providers cannot subsidize.
- Human oversight protocol gaps:The EU AI Act's documentation requirements for automated decisions expose vendors to liability where audit trails for prescriptive recommendations remain incomplete.
Strategic Opportunities
- German industrial cluster concentration:Pilot programs around Munich and Stuttgart offer reference architectures that can replicate across Benelux and Nordic manufacturing corridors.
- IoT-EDI telemetry convergence:Multi-source sensor fusion combining EDI transactions with external demand signals creates predictive visibility tools previously captive to integrated ERP suites.
- CSRD supply chain disclosure rules:The EU Corporate Sustainability Reporting Directive mandates emissions traceability that AI-enabled procurement platforms can monetize as compliance-as-a-service offerings.
Industry Challenges
- Prescriptive recommendation latency engineering:Critical path decisions under five minutes require rearchitecting optimization solvers that historically tolerated batch processing windows.
- ERP integration complexity:Native S/4HANA connectivity and Watson suite anchoring create switching costs that fragment vendor qualification criteria across enterprise accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Supply Chain Management Market |
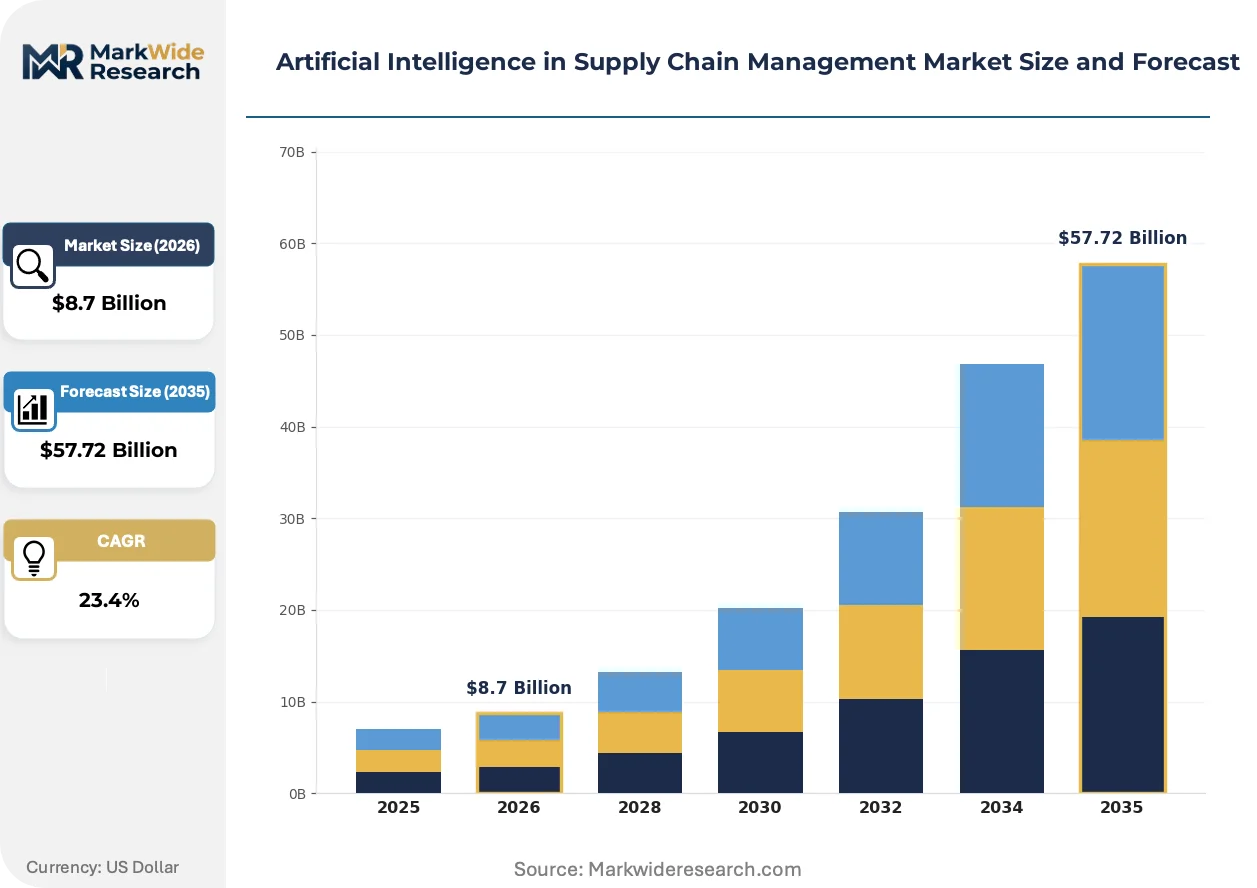
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Service, Hardware End User: Retailers, Manufacturers, Logistics Providers, Distributors Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Functionality: Demand Forecasting, Inventory Management, Route Optimization, Process Automation |
| Companies Covered | o9 Solutions, IBM, SAP, FourKites, Kinaxis, Oracle, Blue Yonder, GEP, Coupa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Supply Chain Management Market Strategic Shifts
Generative AI is compressing planning cycle times while regulatory pressure on algorithmic transparency forces architectural redesigns. Deployment patterns are splitting between cloud-native mid-market solutions and edge-intensive specialized applications.
Digital twin modeling is bifurcating demand forecasting architectures between discrete manufacturing verticals requiring physics-based simulation and process industries tolerating statistical extrapolation. Automotive and electronics clusters in Germany are adopting o9 Solutions-style demand-sensing platforms at 18-month replacement cycles for legacy statistical engines. This technology is bifurcating vendor roadmaps into separate product lines for asset-heavy manufacturers and asset-light logistics intermediaries.
The EU AI Act imposes risk-tiered conformity assessments on automated supply chain decision systems before market access. Industrial consequence includes mandatory documentation of algorithmic transparency and human oversight protocols that extend procurement timelines by 4-6 months. Pharmaceutical cold chain and drone logistics segments face the strictest scrutiny, with vendors pre-qualifying solutions through Brussels notified bodies rather than post-hoc compliance.
Shippers are unbundling predictive visibility procurement from integrated ERP suites, contracting directly with specialized AI vendors for demand forecasting modules. Third-party logistics providers displace traditional manufacturer-led buying committees as the primary decision-makers for supply chain software. This pattern concentrates in Germany and extends into Austrian and Swiss industrial corridors where 3PL market share in software procurement exceeds direct shipper spending.
Artificial Intelligence in Supply Chain Management Market Segmentation
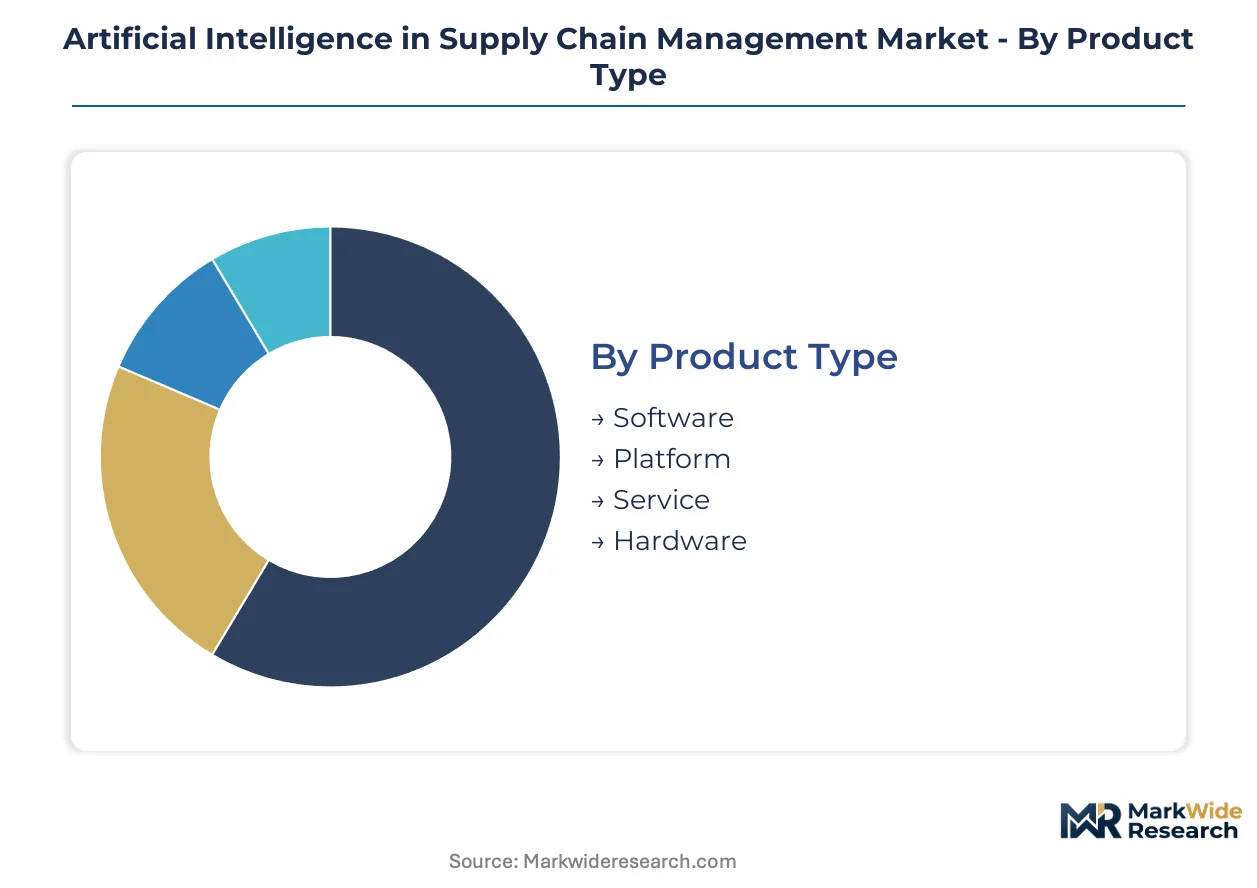
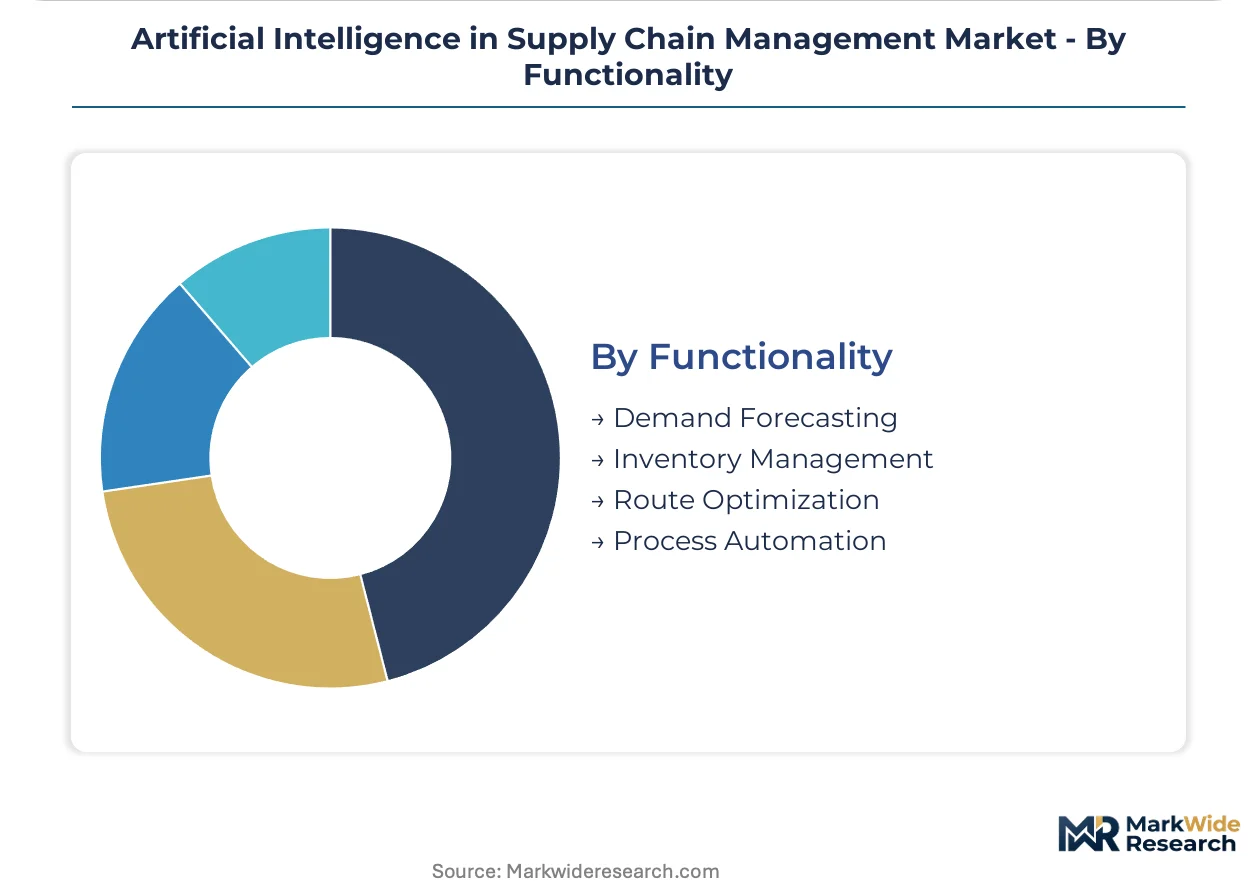
AI supply chain segmentation reveals how regulatory pressure and latency requirements split procurement patterns across buyer types. Vendors must architect separate compliance pathways and deployment architectures for each segment cluster.
Product Type:
The EU AI Act imposes tiered conformity assessments that fragment software certification timelines from hardware validation protocols.
- Software:Machine learning algorithms, natural language processing engines, and optimization solvers delivered via subscription models. Demand concentrates among mid-market logistics providers in Germany seeking predictive visibility tools without capital-intensive infrastructure commitments.
- Platform:Integrated suites combining multiple AI capabilities with native ERP connectivity. Automotive clusters around Stuttgart favor platforms with S/4HANA integration to reduce deployment friction in existing SAP environments.
- Service:Implementation consulting, algorithm tuning, and compliance documentation support. CDSCO and EMA documentation requirements in pharmaceutical cold chain drive specialized service procurement.
- Hardware:Edge computing devices, IoT sensors, and localized processing units. Millisecond response requirements in autonomous fleet applications disqualify centralized architectures.
Established volume favors Software; emerging adoption favors Hardware.
End User:
Procurement authority is shifting from asset-heavy manufacturers to asset-light intermediaries with compressed deployment timelines.
- Retailers:Demand forecasting and inventory optimization for omnichannel fulfillment. Electronics retailers in Munich pilot autonomous control towers with sub-five-minute latency targets.
- Manufacturers:Digital twin modeling and production planning automation. Discrete manufacturing verticals require physics-based simulation capabilities that statistical engines cannot deliver.
- Logistics Providers:Third-party logistics providers accelerate AI procurement faster than direct shippers. These asset-light intermediaries seek predictive visibility tools historically bought by integrated manufacturers.
- Distributors:Route optimization and multi-echelon inventory positioning. CSRD supply chain disclosure rules create compliance-as-a-service monetization opportunities.
Procurement concentration favors Logistics Providers; contract value favors Manufacturers.
Deployment:
Latency engineering requirements split architectures between centralized cloud elasticity and localized edge responsiveness.
- On-Premises:Dedicated infrastructure within enterprise data centers. Defense and pharmaceutical sectors maintain on-premises deployments for FDA and EMA audit trail requirements.
- Cloud-Based:Subscription-based modules hosted by hyperscale providers. Mid-market logistics providers lacking internal data center capacity expand fastest in this configuration.
- Hybrid:Split processing between cloud analytics and local execution. German industrial clusters pilot hybrid architectures balancing algorithmic transparency documentation with operational responsiveness.
- Edge Computing:Localized processing for millisecond-critical decisions. Cold chain and autonomous fleet applications demand edge hardware investments that centralized providers cannot subsidize.
Current revenue favors Cloud-Based; margin expansion favors Edge Computing.
Functionality:
Regulatory scrutiny intensity varies by decision consequence, with pharmaceutical and autonomous logistics facing strictest algorithmic accountability.
- Demand Forecasting:Statistical and machine learning models predicting consumption patterns. o9 Solutions-style platforms in automotive verticals achieve 18-month replacement cycles for legacy engines.
- Inventory Management:Multi-echelon optimization and safety stock positioning. Retailers unbundle this functionality from integrated ERP suites to contract directly with specialized AI vendors.
- Route Optimization:Real-time pathfinding incorporating traffic, weather, and capacity constraints. FAA drone logistics rules fragment compliance burdens for aerial delivery applications.
- Process Automation:Robotic process automation and autonomous decision execution. EU AI Act human oversight protocols expose vendors to liability where audit trails remain incomplete.
Deployment maturity favors Demand Forecasting; regulatory complexity favors Process Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics providers concentrate procurement authority in Germany, while discrete manufacturers in automotive and electronics verticals drive platform adoption across industrial clusters in North America and Asia-Pacific.
Germany
Industrial clusters around Munich and Stuttgart pilot autonomous supply chain control towers with sub-five-minute latency targets for automotive and electronics manufacturing. The EU AI Act imposes tiered conformity assessments on automated decision systems, compelling vendors to document algorithmic transparency before market access. Baden-Württemberg's manufacturing corridor represents the densest concentration of demand-sensing platform deployments in Europe.
United States
Enterprise manufacturers prioritize deep ERP integration for supply chain AI, with FDA and FAA maintaining parallel compliance requirements for pharmaceutical cold chain and drone logistics applications. The IRA's domestic manufacturing incentives accelerate reshoring investments that require predictive visibility tools for multi-tier supplier networks. Greater Boston and Pacific Northwest technology corridors host the highest density of cloud-native logistics AI startups serving mid-market 3PLs.
China
Dual carbon goals and MIIT smart manufacturing mandates drive AI procurement for emissions traceability and production optimization in Yangtze River Delta industrial zones. SAMR algorithmic governance rules create compliance complexity for automated procurement systems that vendors address through localized deployment architectures. Shenzhen and Shanghai electronics manufacturing clusters represent the fastest-growing demand for edge computing in autonomous fleet applications.
India
PLI scheme incentives for electronics and automotive manufacturing attract supply chain AI investments to meet export compliance requirements from EU and US buyers. CDSCO documentation standards for pharmaceutical cold chain create specialized service procurement from vendors with regulatory expertise. Maharashtra and Karnataka industrial corridors concentrate pilot programs for demand forecasting modules among contract manufacturers serving global OEMs.
Japan
METI's Society 5.0 initiative funds digital twin modeling for discrete manufacturing verticals requiring physics-based simulation capabilities. PMDA cold chain requirements for biologics distribution impose strict audit trail standards on automated decision systems. Kansai manufacturing belt around Osaka hosts the highest concentration of legacy ERP modernization projects integrating AI planning modules.
Artificial Intelligence in Supply Chain Management Market Competitive Environment
Player mix skews toward enterprise software vendors with native ERP connectivity, creating tiered competition between integrated suite providers and specialized demand-sensing platforms. Consolidation pressure intensifies as procurement authority shifts from asset-heavy manufacturers to asset-light logistics intermediaries with compressed deployment timelines. Three strategic archetypes dominate: ERP-native platforms leveraging existing customer relationships, best-of-breed AI specialists occupying narrow functional niches, and cloud-native challengers targeting mid-market 3PLs. Competitive moves center on M&A to acquire digital twin capabilities and strategic partnerships to accelerate EU AI Act compliance documentation.
Among enterprise suite providers, IBM anchors North American accounts through Watson supply chain integration, while SAP occupies the S/4HANA-native tier for European manufacturers seeking reduced deployment friction. o9 Solutions exemplifies the specialized demand-sensing archetype, with its digital twin modeling concentrated in German automotive and electronics clusters. These three companies represent distinct competitive vectors: ERP anchoring, native connectivity, and vertical specialization.
| Leading Market Players |
|---|
| o9 Solutions |
| IBM |
| SAP |
| FourKites |
| Kinaxis |
| Oracle |
| Blue Yonder |
| GEP |
| Coupa |
| Others |
Value Chain & Pricing Dynamics
Cloud-native deployment architectures displacing legacy on-premises infrastructure simultaneously concentrates vendor development resources in Germany and compresses subscription pricing for mid-market logistics providers lacking capital-intensive data center commitments. This substitution dynamic reshapes both supply geography toward Brussels-compliant development centers and pricing economics toward SaaS-tiered models with algorithmic transparency documentation bundled as standard.
Pricing Analysis
Generational pricing gaps separate legacy statistical engines from current-generation machine learning platforms and emerging edge-computing hardware tiers. SaaS-tiered subscription models dominate software revenue, with price differentiation anchored in EU AI Act certification grade and native ERP integration depth. Pricing pressure stems from mid-market 3PL procurement authority displacing enterprise manufacturer buying committees. Logistics providers exhibit highest price sensitivity due to asset-light balance sheets, while discrete manufacturers in automotive verticals tolerate premium tiers for physics-based digital twin capabilities.
Supply Chain Analysis
Brussels regulatory clearance chokepoints underwrite vendor qualification timelines, concentrating compliant solution development in Germany, the United States, and India. AI supply chains draw from Taiwan for edge computing semiconductors, Ireland for cloud infrastructure, and Germany for automotive sensor telemetry. Single-source vulnerability runs through hyperscale cloud providers unable to subsidize localized millisecond-response hardware. Distribution runs through direct enterprise sales for platform suites and channel partners for mid-market software modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial intelligence in supply chain management market sits in early-cycle recovery as EU AI Act compliance mandates force replacement demand for legacy planning engines. Industrial capital expenditure cyclicality in German automotive clusters provides the recovery justification.
For Market Incumbents: Compound defensive moats through native S/4HANA connectivity investments and Watson-style ERP anchoring that elevate switching costs against cloud-native challengers. Prioritize backward integration into algorithmic transparency documentation capabilities to preempt Brussels notified body pre-qualification requirements. Channel control through system integrator partnerships protects margin position as 3PL procurement compresses deployment timelines. For New Entrants and Emerging Players: EU AI Act compliance-as-a-service gaps where incumbents under-serve mid-market logistics providers lacking internal regulatory affairs capacity offer immediate white-space entry. Target German industrial clusters piloting autonomous control towers with sub-five-minute latency requirements. Go-to-market through vertical specialization in cold chain traceability or drone logistics segments facing strictest FDA and FAA algorithmic accountability scrutiny. For Investors and Strategic Acquirers: The market sits at a regulatory-mandated replacement phase that favors specialized demand-sensing platforms with defensible automotive vertical concentration. Long-term viability hinges on digital twin physics-based simulation capabilities that statistical extrapolation engines cannot replicate. Monitor CDSCO and EMA documentation standard convergence as the inflection signal for pharmaceutical cold chain service-layer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Pre-Qualification | Brussels notified body certification accelerates procurement timelines for automated decision systems. |
| Digital Twin Capability Acquisition | Physics-based simulation assets in German automotive clusters command strategic premiums. |
| Edge Computing Hardware Partnership | Millisecond-response cold chain applications require localized processing beyond cloud elasticity. |
| 3PL Channel Program Expansion | Asset-light logistics intermediaries now exceed direct shipper procurement authority. |
| CSRD Emissions Traceability Integration | Supply chain disclosure rules enable compliance-as-a-service monetization for procurement platforms. |
Study Parameters
A standing panel of supply chain planning directors, third-party logistics procurement officers, EU regulatory affairs specialists, and cloud platform engineers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, EMA submission databases, hyperscaler capex disclosures, and German industrial cluster investment reports. Bottom-up deployment counts and top-down software revenue estimates underwent iterative triangulation.
Consistency checks validated outputs against external benchmarks including EU AI Act implementation timelines and MIIT smart manufacturing mandate progress indicators. The analytical framework modeled segmentation dimensions spanning deployment architecture, buyer type concentration, functionality maturity, and regional regulatory cluster intensity across the projection horizon. CAGRs derived from replacement cycle analysis for legacy statistical engines and pilot-to-production scaling patterns for autonomous control towers.
Forecasts assume regulatory continuity in EU AI Act risk-tiered assessments and FDA pharmaceutical cold chain requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as SAMR algorithmic governance rules and FAA drone logistics standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Robotic Vision Market