
 Global Enterprise High-Productivity Application Platform As a Service Market | 2026-2036
Global Enterprise High-Productivity Application Platform As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise High-Productivity Application Platform As a Service Market Foresight
Healthcare and BFSI demand for rapid application delivery is hardening as enterprises replace legacy systems with cloud-native development environments. Microsoft leverages its Azure ecosystem to anchor enterprise accounts across hybrid cloud deployments. Salesforce sustains competitive pressure through deep CRM integration and workflow automation specialization. Amazon Web Services dominates infrastructure-scale consumption with extensive API management and serverless backend services.
Enterprise High-Productivity Application Platform As a Service denotes cloud-hosted environments enabling visual, model-driven, or low-code application development with pre-built connectors, automated DevOps pipelines, and elastic infrastructure provisioning. These platforms abstract underlying infrastructure complexity to accelerate software delivery cycles from months to days for business technologists and professional developers alike. Public cloud deployments lead volume consumption due to faster provisioning and lower capital requirements, though hybrid cloud configurations capture expanding margin pools from regulated industries requiring data residency controls. Low-code development represents the fastest-growing solution offering as business units gain direct authoring capabilities, while integration platform spending remains mature and concentrated among large enterprises with complex legacy system estates.
FDA 21 CFR Part 11 guidelines shape validation requirements for pharmaceutical and medical device companies deploying cloud-based quality management applications. The EU AI Act and GDPR impose algorithmic transparency and data localization mandates that platform vendors must architect into European deployments. ISO 27001 and SOC 2 Type II certifications function as baseline market access credentials for enterprise procurement evaluations. Stakeholders must monitor evolving sovereign cloud regulations across multiple jurisdictions to anticipate where platform residency requirements will fragment deployment architectures and inflate compliance costs.
Market Dynamics
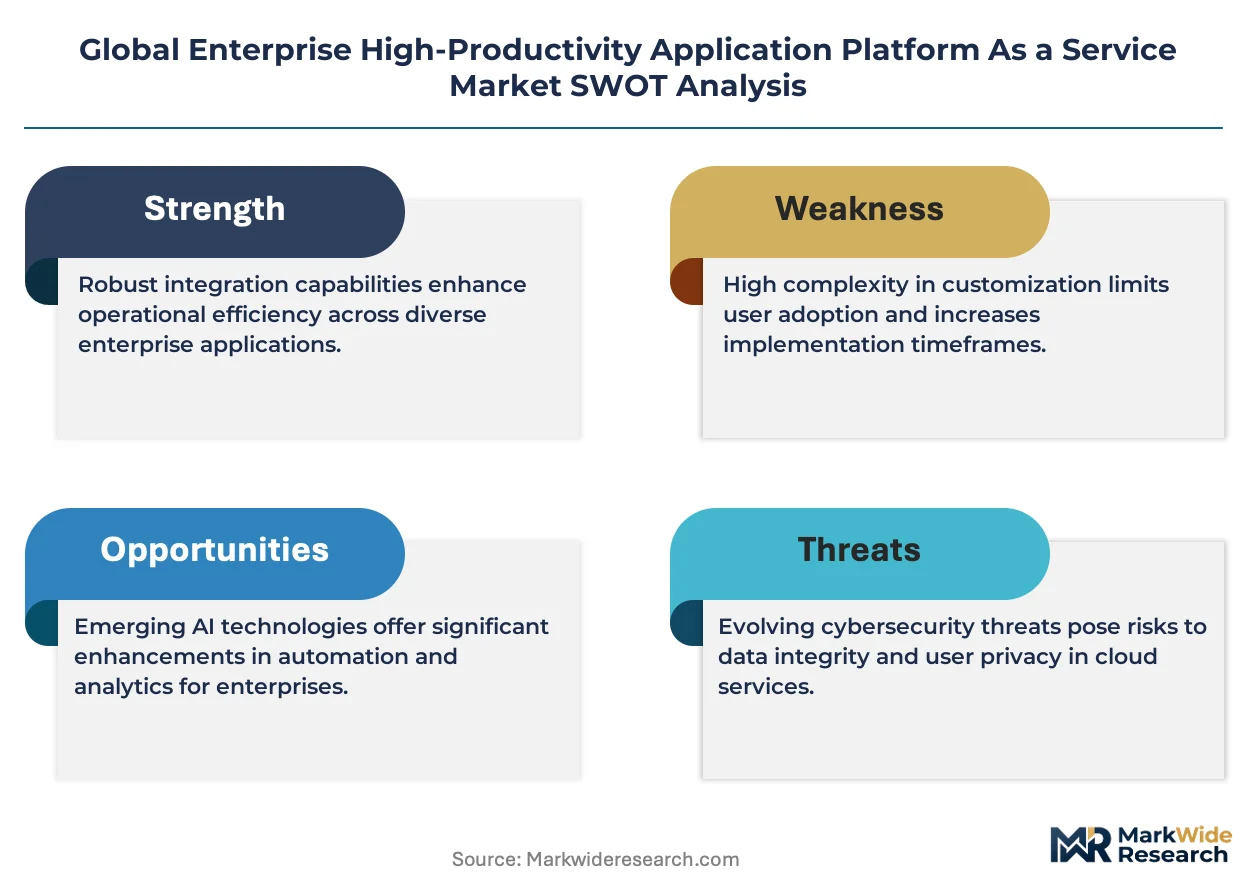
Enterprise demand for governed low-code environments is compressing procurement cycles as CIOs prioritize platforms that embed compliance automation directly into development workflows.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European financial services and healthcare enterprises are selecting platforms with built-in explainability features to preempt regulatory scrutiny.
- FDA 21 CFR Part 11 validation requirements:Pharmaceutical manufacturers are migrating quality management applications to cloud-native platforms that automate audit trails and electronic signature compliance.
- Sovereign cloud strategies in India, Germany, and the United States:National data residency policies are accelerating domestic platform deployment and local partnership ecosystems.
Market Restraints
- Specialized integration architecture costs:Enterprise legacy system estates require expensive custom connector development that erodes low-code cost advantages.
- Hyperscaler infrastructure concentration:Three cloud providers dominate underlying compute and storage, creating vendor lock-in risk and pricing power asymmetry.
- GDP data localization enforcement:Cross-border data transfer restrictions fragment platform architectures and inflate operational overhead for multinational deployments.
Strategic Opportunities
- Underpenetrated industrial manufacturing in India:Domestic PLI scheme incentives are driving factory digitization where low-code MES and inventory platforms remain nascent.
- Convergence of generative AI with visual development interfaces:Natural language code generation is collapsing the gap between business analyst intent and executable application logic.
- Outcome-based platform pricing through channel partners:Systems integrators are piloting consumption models tied to deployed application business value rather than seat licenses.
Industry Challenges
- Citizen developer governance gaps:Business-unit-authored applications lack standardized security review, creating shadow IT exposure and compliance audit failures.
- ISO 27001 and SOC 2 Type II certification timelines:Six-to-twelve month attestation cycles delay enterprise sales cycles and strain vendor cash flow.
- Multi-cloud deployment complexity:Enterprise architects struggle to maintain consistent policy enforcement across hybrid configurations spanning public, private, and edge infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise High-Productivity Application Platform As a Service Market |
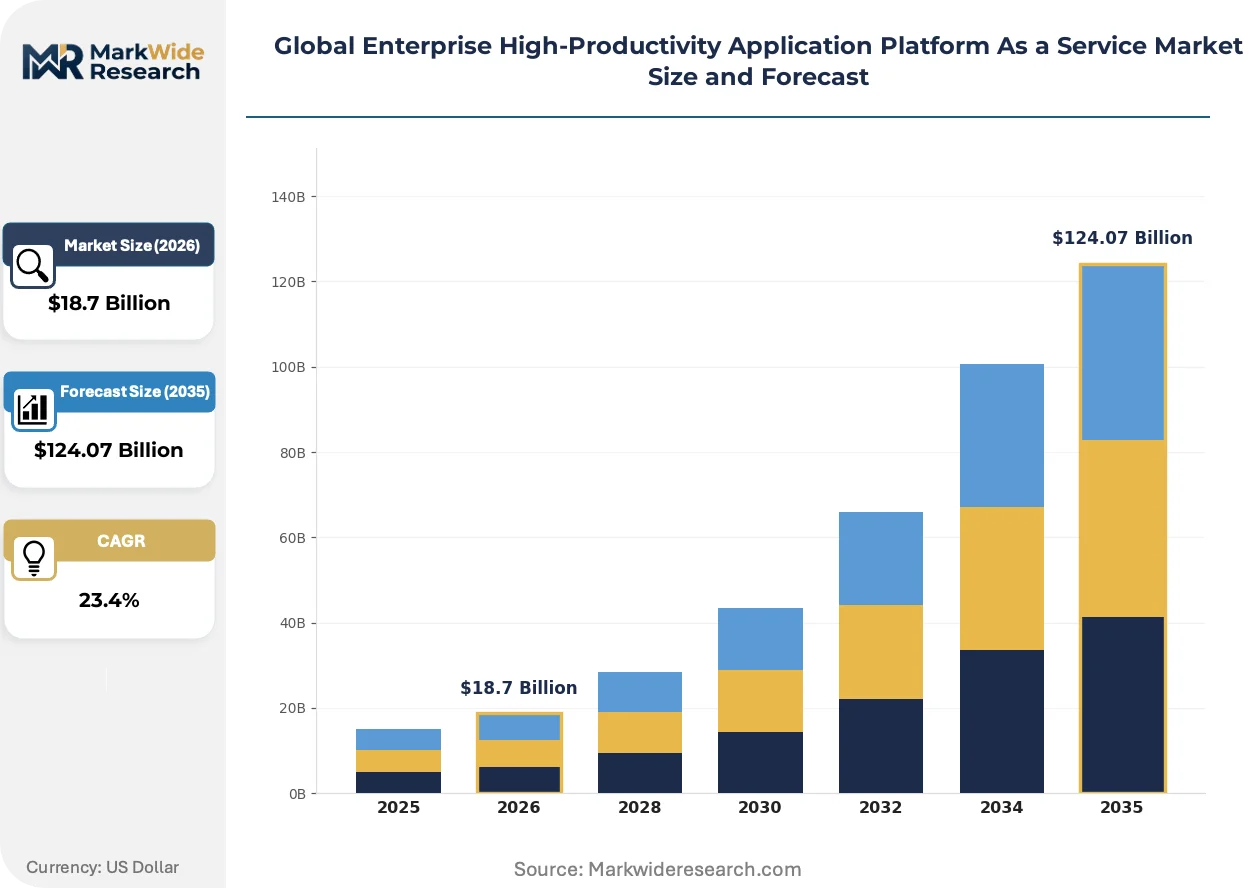
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Low-Code Development, Integration Platform, Workflow Automation, API Management, Mobile Backend Application Use Case: Financial Reporting, Customer Relationship Management, Supply Chain Optimization, HR Management, Data Analytics End User Industry: BFSI, Telecommunications, Manufacturing, Government, Education |
| Companies Covered | Microsoft, Salesforce, SAP SE, Amazon Web Services, IBM Corporation, Google, ServiceNow, OutSystems, Tencent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise High-Productivity Application Platform As a Service Market Shifts & Advancements
Platform architectures are converging around embedded governance layers that automate compliance verification during the development lifecycle rather than as a post-deployment checkpoint.
Unified low-code and integration platform suites are unifying previously separate visual development and API management capabilities into single vendor contracts. Healthcare providers and insurers are consolidating procurement around these integrated stacks to reduce vendor management overhead. This consolidation is compressing standalone integration platform vendors into niche legacy modernization roles.
CSRD sustainability reporting mandates in Europe are forcing platform vendors to embed carbon footprint tracking and supply chain disclosure workflows into standard application templates. Industrial enterprises deploying these pre-built modules can accelerate compliance without custom development. German automotive and chemical manufacturers represent the most advanced adopters, using these tools to automate Scope 3 emissions data collection from tiered suppliers.
Business technologists are displacing traditional IT gatekeepers as primary platform buyers within enterprise accounts. Procurement authority is migrating to operations and line-of-business leaders who prioritize speed over architectural purity. This shift is most pronounced in United States financial services, where product managers now directly contract workflow automation platforms without central IT review.
Global Enterprise High-Productivity Application Platform As a Service Market Segmentation
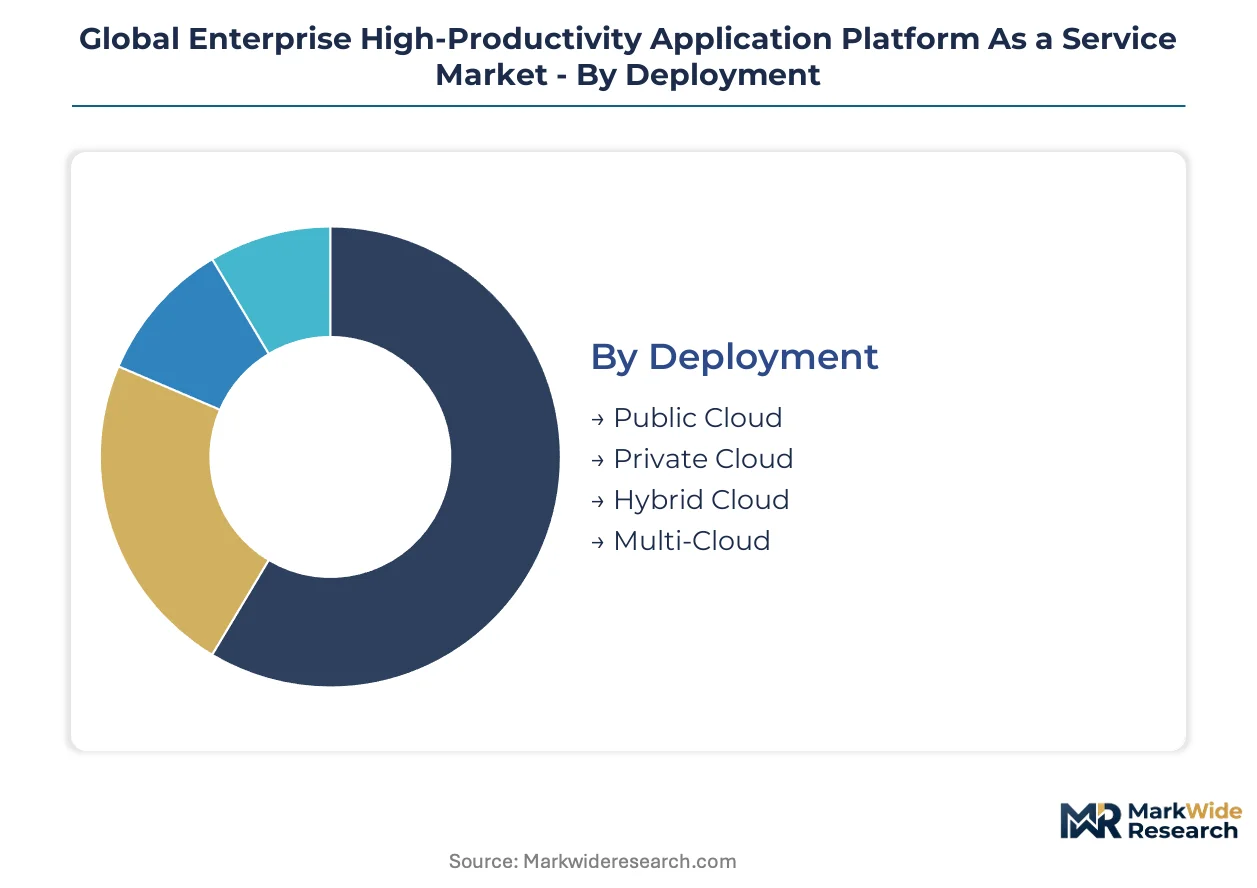
Segmentation reveals how procurement authority fragments across infrastructure choices, solution types, and compliance requirements. Platform vendors must align pricing and partnership strategies to where buying power concentrates within each dimension.
Deployment:
Upgrade cycles for legacy on-premises systems are accelerating cloud migration decisions as enterprises confront end-of-support deadlines for aging infrastructure.
- Public Cloud:Shared infrastructure pools deliver elastic compute with zero capital deployment. Financial services firms in the United States and Germany dominate consumption as they rebuild core banking platforms without data center construction.
- Hybrid Cloud:Split architectures separate sensitive workloads from burst capacity, satisfying RBI data localization mandates for Indian insurers while preserving AWS connectivity for analytics. European manufacturers under GDPR jurisdiction increasingly specify hybrid configurations to maintain sovereignty controls.
- Private Cloud:Dedicated tenant environments serve defense contractors and government agencies with air-gapped security requirements.
- Multi-Cloud:Redundancy across Azure, AWS, and Google Cloud mitigates vendor concentration risk for multinational enterprises.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest.
Solution Offering:
Application maturity determines where procurement budgets flow, with early-stage digitization favoring rapid development tools and established enterprises prioritizing integration complexity.
- Low-Code Development:Visual drag-and-drop interfaces collapse months of traditional coding into weeks. German automotive suppliers deploy these tools to build supplier portal applications without expanding professional developer headcount.
- Workflow Automation:Process orchestration engines connect disparate systems through conditional logic and human task routing. Indian BFSI institutions under SEBI operational risk guidelines adopt these platforms to automate loan approval pipelines with embedded audit trails.
- Integration Platform:Middleware suites bridge ERP, CRM, and legacy mainframe estates through pre-built connectors.
- API Management:Gateway services throttle, secure, and monetize programmatic interfaces exposed to external developers.
- Mobile Backend:Serverless infrastructure provisions authentication, push notifications, and data synchronization for consumer-facing applications.
Low-Code Development commands the largest revenue share, though Workflow Automation is gaining share fastest among regulated industries.
Application Use Case:
Functional replacement priorities shift procurement toward systems delivering immediate compliance or revenue impact rather than back-office efficiency gains.
- Customer Relationship Management:Unified customer data platforms consolidate sales, service, and marketing touchpoints. United States healthcare insurers rebuild member engagement portals to satisfy CMS interoperability rules while reducing call center volume.
- Supply Chain Optimization:Demand forecasting and inventory positioning applications integrate IoT sensor feeds with ERP order data. Indian electronics manufacturers under PLI scheme incentives deploy these tools to track component traceability for DGFT export documentation.
- Financial Reporting:Consolidation engines automate multi-entity close processes and regulatory filing preparation.
- HR Management:Talent acquisition and workforce planning modules replace fragmented point solutions.
- Data Analytics:Embedded visualization and machine learning pipelines transform operational data into predictive insights.
Customer Relationship Management leads deployment counts, while Supply Chain Optimization shows the steepest expansion trajectory as reshoring initiatives multiply data integration requirements.
End User Industry:
Industry-specific regulatory pressure determines platform selection criteria, with governed environments commanding premium pricing over generic configurations.
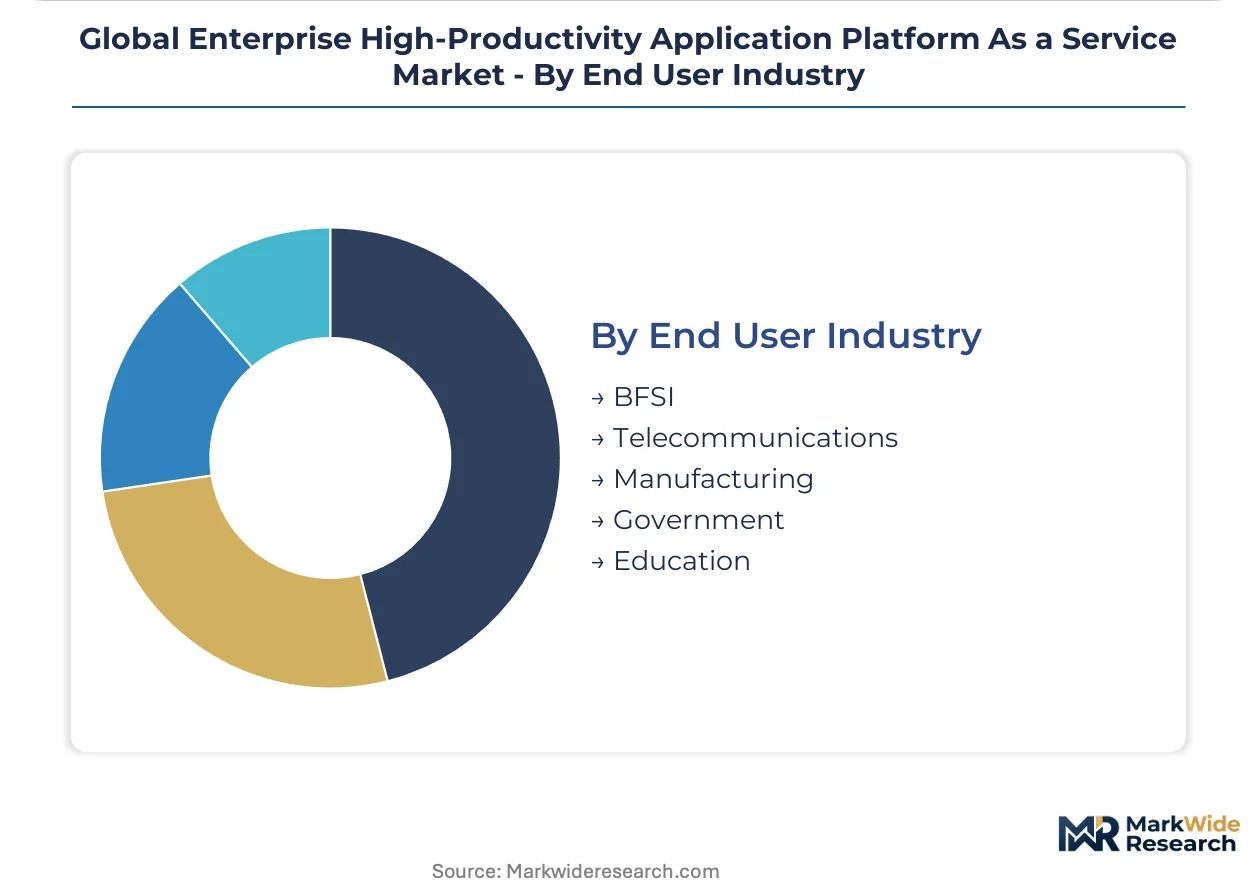
- BFSI:Core banking transformation and open banking API deployment dominate platform consumption. European institutions under EU AI Act algorithmic transparency mandates select platforms with built-in explainability dashboards for credit decisioning models.
- Government:Citizen service portals and inter-agency data exchanges require FedRAMP or equivalent national certification. Indian state governments deploy low-code platforms under Digital India initiatives to build property registration and social benefit distribution systems without lengthy procurement cycles.
- Telecommunications:OSS/BSS modernization and 5G service orchestration drive integration platform spending.
- Manufacturing:MES connectivity and predictive maintenance applications bridge operational technology with enterprise IT.
- Education:Student information systems and learning management platforms consolidate administrative workflows.
BFSI captures the highest absolute spending, with Government expanding most quickly as sovereign cloud mandates proliferate across national jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform deployment patterns as enterprises migrate workloads toward jurisdictions offering clearer compliance frameworks and sovereign cloud incentives. Cost-of-compliance gaps between the United States, Germany, and India are accelerating cross-border data center investments and local partnership formations.
United States
Financial services institutions dominate platform consumption as they rebuild core banking infrastructure under SEC operational resilience guidelines. FDA 21 CFR Part 11 requirements drive pharmaceutical manufacturers toward cloud-native quality management systems with automated audit trails. The Boston-Cambridge biotech corridor and New York financial district anchor the highest concentration of governed platform deployments.
Germany
Automotive suppliers and chemical manufacturers deploy low-code platforms to automate CSRD sustainability reporting and Scope 3 emissions tracking. EU AI Act algorithmic transparency mandates push credit institutions toward explainable AI-integrated development environments. The Rhine-Ruhr industrial belt and Baden-Württemberg manufacturing clusters lead adoption of compliance-embedded platform architectures.
India
Domestic BFSI institutions under RBI data localization rules adopt hybrid cloud configurations separating sensitive workloads from burst analytics capacity. PLI scheme incentives accelerate factory digitization in electronics and automotive component manufacturing. Bengaluru's SaaS startup ecosystem and Mumbai's financial services corridor drive the fastest-growing regional demand for visual development tools.
United Kingdom
Insurance technology firms and open banking API providers consolidate procurement around unified low-code and integration suites. Financial Conduct Authority operational resilience requirements compress vendor evaluation cycles toward pre-certified platforms. London's fintech concentration and Manchester's emerging digital services hub represent primary demand centers for workflow automation.
Japan
Manufacturing enterprises deploy predictive maintenance applications bridging operational technology with enterprise IT systems. METI digital transformation subsidies accelerate SME migration from legacy mainframe environments to cloud-native platforms. The Tokyo-Osaka industrial corridor anchors platform consumption for supply chain optimization and quality management use cases.
Global Enterprise High-Productivity Application Platform As a Service Market Competitive Landscape
Strategic partnership formation dominates the current landscape as hyperscalers anchor enterprise accounts through integrated cloud ecosystems. The vendor base concentrates around three structural tiers: infrastructure-scale providers with native platform services, independent software vendors with deep vertical specialization, and emerging challengers with generative AI-native interfaces. Consolidation pressures intensify as procurement authority migrates from central IT to line-of-business buyers seeking speed over architectural purity. Portfolio diversification and sovereign cloud localization represent the two most active competitive vectors.
Within the hyperscaler tier, Microsoft, Amazon Web Services, and Salesforce exemplify distinct ecosystem anchoring strategies. Microsoft leverages Azure hybrid cloud deployments to capture enterprise accounts navigating complex regulatory jurisdictions. Amazon Web Services dominates infrastructure-scale consumption through extensive API management and serverless backend services. Salesforce occupies a position defined by deep CRM integration and workflow automation specialization for customer-facing applications.
| Leading Market Players |
|---|
| Microsoft |
| Salesforce |
| SAP SE |
| Amazon Web Services |
| IBM Corporation |
| ServiceNow |
| OutSystems |
| Tencent |
| Others |
Supply & Pricing Matrix
Hyperscaler concentration versus independent software vendor specialization creates a bifurcation where platform pricing power clusters around cloud-native ecosystem bundling while supply chain leverage fragments across regional data center footprints and compliance certification pipelines. This divergence manifests in divergent margin structures: anchored accounts absorb premium pricing for integrated Azure or AWS stacks, while procurement officers at mid-market enterprises exploit vendor competition among best-of-breed low-code specialists.
Pricing Analysis
Distributor margin compression in the indirect channel has pushed platform vendors toward direct enterprise contracting with volume-discount schedules tied to committed consumption thresholds. SaaS-tiered subscription models dominate, with price differentiation across ISO 27001 certification tier, data residency zone, and embedded AI inference volume. Pricing pressure stems from hyperscaler infrastructure concentration as AWS, Azure, and Google Cloud leverage compute-storage bundling to undercut standalone platform margins. Mid-market manufacturers in India exhibit highest price sensitivity, while FDA-regulated pharmaceutical enterprises in the United States accept premium tiers for validated GxP environments.
Supply Chain Analysis
Compute infrastructure supply rests on concentrated hyperscaler data center investments across the United States, Germany, and India, with specialized AI accelerator chip dependencies tethering platform performance to NVIDIA and AMD foundry output. Raw material inputs span silicon wafers, rare earth elements for server manufacturing, and lithium-ion battery systems for edge deployment resilience. Supply chain risk concentrates in single-source vulnerability for advanced GPU allocation, where cloud providers ration capacity among platform tenants. Distribution runs through direct hyperscaler marketplaces and systems integrator channel partners, with Indian domestic cloud providers emerging as alternative supply anchors under RBI localization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Enterprise High-Productivity Application Platform As a Service Market compounds steadily as sovereign cloud mandates and algorithmic transparency regulations institutionalize platform spending across regulated industries.
For Market Incumbents: Acquire compliance automation assets and generative AI-native development interfaces to neutralize emerging challengers with embedded governance layers. Defensive consolidation must address citizen developer governance gaps through centralized policy enforcement engines, while capacity expansion in Indian and German sovereign cloud zones secures data residency positioning against domestic platform rivals. For New Entrants and Emerging Players: Capture underpenetrated industrial manufacturing workflows in India's PLI scheme corridors, where low-code MES and inventory platforms remain nascent against legacy ERP extensions. White-space concentration favors outcome-based pricing pilots through Mumbai and Bengaluru systems integrators, with go-to-market positioning anchored to DGFT traceability automation for electronics exporters. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone integration platform vendors face compression from unified low-code suite consolidation in healthcare and BFSI procurement. Long-term viability favors vertical specialists with embedded EU AI Act explainability tooling and FDA 21 CFR Part 11 validation frameworks. The signal to watch is sovereign cloud tender awards in Germany and India as inflection indicators for regional platform leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies low-code development with API management to reduce vendor management overhead for healthcare insurers. |
| Strategic Partnership | Localizes deployment architectures through German automotive supplier networks for CSRD sustainability reporting automation. |
| Acquisition of Specialist Firm | Absorbs generative AI-native interfaces that collapse business analyst intent to executable application logic. |
| Geographic Expansion | Establishes sovereign cloud presence in India under RBI data localization rules for domestic BFSI institutions. |
| Product Launch | Introduces embedded governance layers that automate EU AI Act compliance verification during development lifecycles. |
Research Methodology
Multiple input streams — structured interviews with enterprise CIOs and platform engineering directors, procurement data from hyperscaler marketplace disclosures, and regulatory filing analysis across FDA, EMA, and RBI jurisdictions — were reconciled through bottom-up deployment sizing and top-down vendor revenue triangulation. Secondary validation incorporated SEC 10-K filings, cloud infrastructure capex reports, and EU AI Act implementation guidance documents.
Historical consumption patterns were cross-referenced against expert panel inputs covering deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from segment-level growth rate reconciliation across the modeling period, with specific weighting applied to sovereign cloud policy acceleration and generative AI interface adoption curves.
Regulatory enforcement delays, hyperscaler capacity rationing, and sovereign cloud tender award timelines are the dominant revision risks that could compress or extend platform adoption trajectories. Forecasts embed assumptions regarding compliance timeline adherence and infrastructure investment continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Helpdesk Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market