
 Africa Managed Services Market | 2026-2036
Africa Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Managed Services Market Outlook
Market Context with Strategic Players
Channel partnerships between global technology vendors and local systems integrators is reshaping how managed services reach African enterprises. Cisco Systems leverages its extensive certified partner network to extend network management capabilities into mid-market accounts across the continent. IBM Corporation anchors its position through hybrid cloud management offerings tailored to regulated industries. Dimension Data competes aggressively on security management, drawing on its Johannesburg headquarters to serve pan-African financial services clients.
Technical Definition and Structural Segments
Africa Managed Services encompasses the ongoing remote monitoring, administration, and optimization of enterprise IT infrastructure, applications, and security environments under multi-year contractual arrangements with defined service level agreements. These services integrate automated ticketing systems, predictive analytics engines, and 24/7 network operations centers to maintain uptime commitments while transferring operational risk from client to provider. Cloud Management commands the largest share of current contract value as enterprises migrate from aging data centers. Security Management generates the fastest expansion, driven by escalating cyber threats against banking and telecommunications infrastructure. Hybrid Cloud deployment models capture disproportionate margin pools by combining public cloud elasticity with private infrastructure compliance for healthcare and financial services end users.
Regulatory Frame and Forward-Looking Close
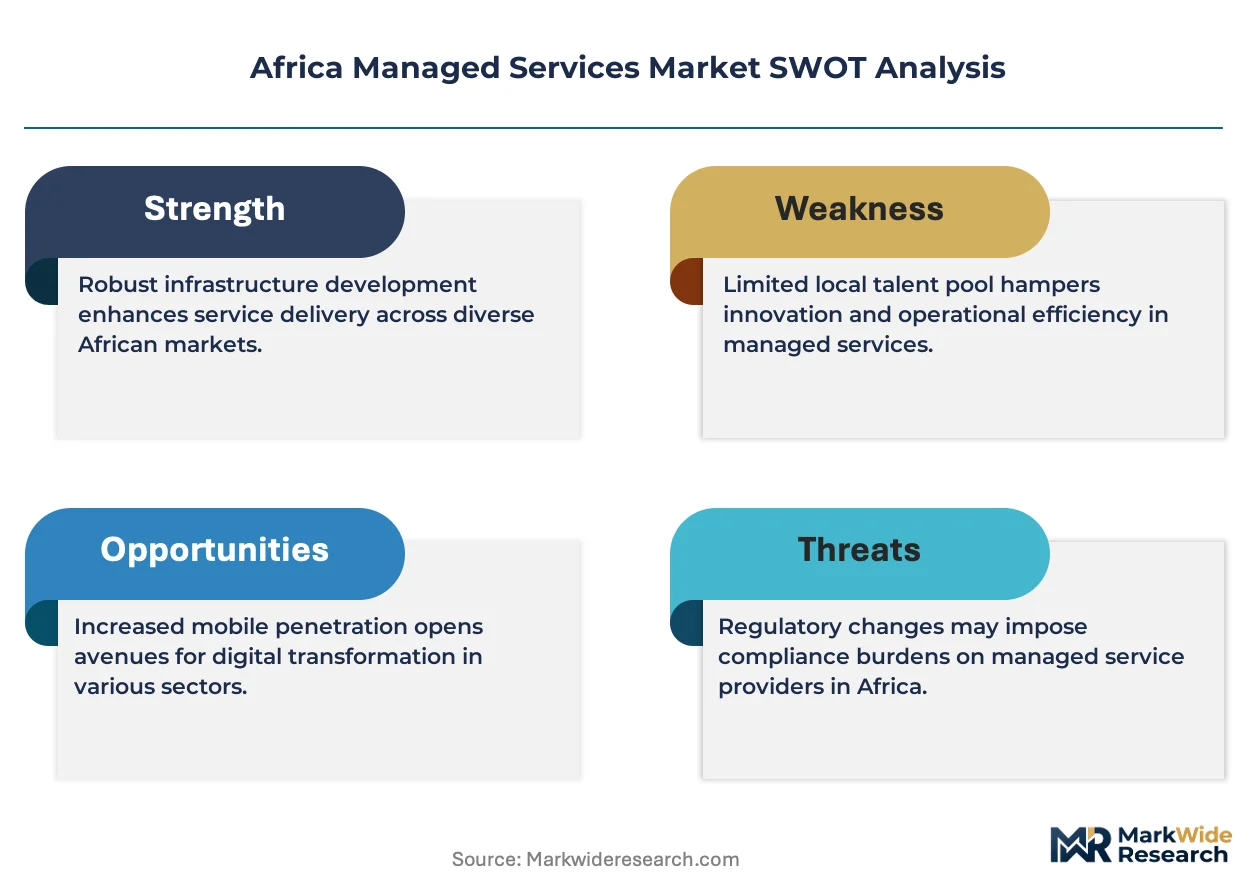
South Africa's Protection of Personal Information Act and Kenya's Data Protection Act impose strict data residency and cross-border transfer rules that managed service providers must architect around. Nigeria's Central Bank cybersecurity framework and the African Union's Malabo Convention on Cybersecurity collectively elevate compliance costs while creating barriers to unqualified entrants. Stakeholders must monitor how rapidly evolving national data sovereignty laws fragment service delivery architectures and force localization investments that alter provider economics.
Market Dynamics
Legacy system modernization across Nigeria's banking sector is forcing rapid outsourcing of infrastructure operations to providers capable of bridging on-premise data centers with cloud-native architectures under strict uptime guarantees.
Growth Catalysts
- Kenya's Data Protection Act:Compliance mandates for cross-border data transfers are expanding the addressable market for localized managed security operations centers serving East African enterprises.
- Telecommunications infrastructure:5G network rollouts in South Africa and Egypt are generating sustained demand for network operations center outsourcing among mobile operators lacking in-house scale.
- Hybrid cloud orchestration:Financial services institutions in Lagos and Nairobi require unified management platforms spanning AWS, Azure, and private VMware environments.
Market Restraints
- Power infrastructure instability:Grid reliability deficits in Nigeria and Kenya force providers to absorb diesel generator and battery backup capital costs that compress margins.
- Specialized cybersecurity talent scarcity:Certified security architects and SOC analysts command premium compensation that inflates service delivery costs across the continent.
- Data localization hardware requirements:South Africa's POPIA and Nigeria's NDPR mandate in-country server deployment, blocking pure offshore delivery models.
Strategic Opportunities
- Ethiopia's banking liberalization:New private bank licenses are creating greenfield demand for fully outsourced core banking infrastructure without legacy migration burdens.
- Healthcare digitization:Hospital information system rollouts in Ghana and Kenya present untapped demand for HIPAA-aligned managed hosting services.
- AI-powered predictive maintenance:Convergence of machine learning with network monitoring is enabling premium-tier service contracts with guaranteed mean-time-to-repair reductions.
Industry Challenges
- Multi-cloud certification timelines:Engineers require 6-12 month credentialing cycles across AWS, Azure, and Google Cloud platforms before client-facing deployment.
- Legacy mainframe integration complexity:Nigerian banks running IBM z Systems require specialized COBOL expertise that conflicts with cloud-native skill development priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Managed Services Market |
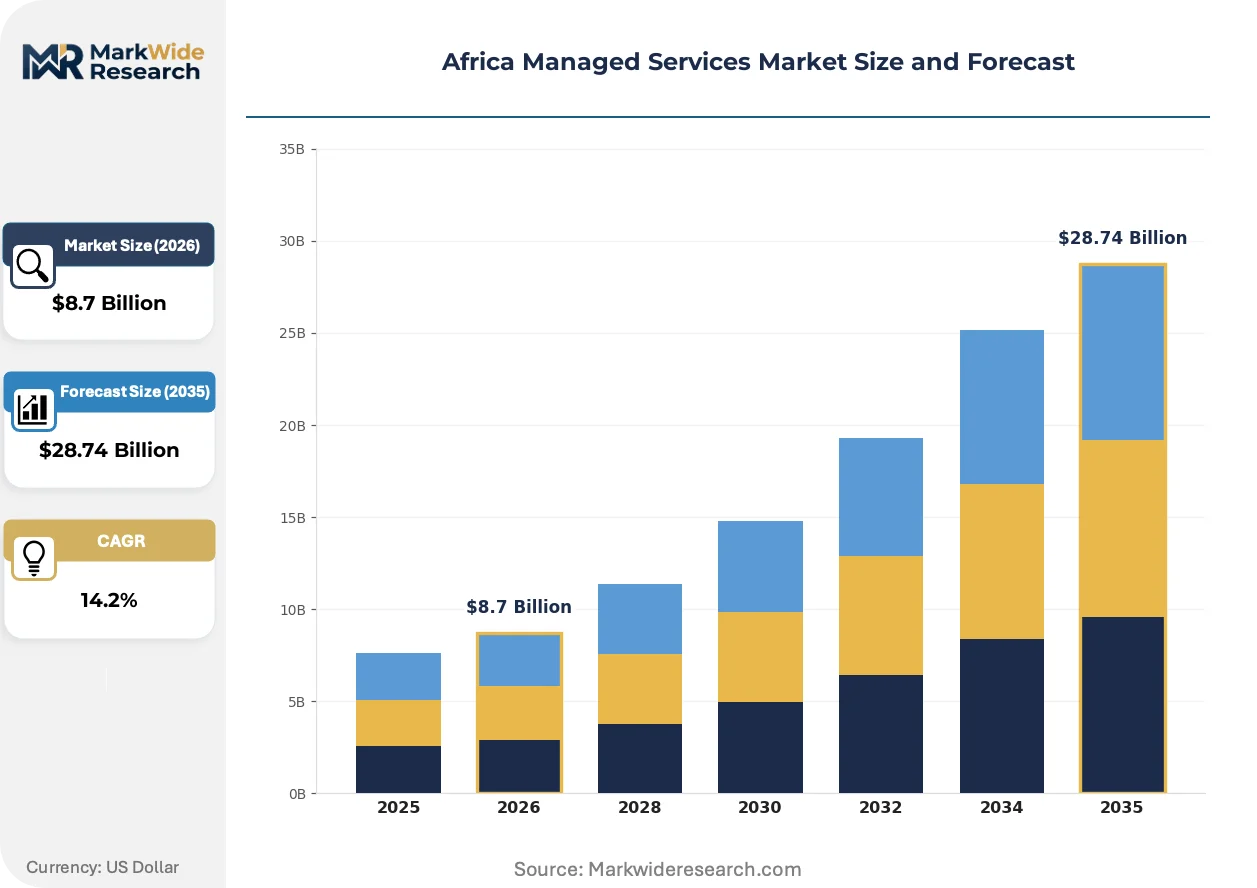
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Management, Network Management, Security Management, IT Asset Management End User: Healthcare, Retail, Financial Services, Telecommunications Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: AI, IoT, Virtualization, Automation |
| Companies Covered | Cisco Systems, IBM Corporation, Accenture PLC, Dimension Data, Fujitsu Ltd., Orange Business Services, Liquid Telecom, HP Development Company LP, NEC Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Managed Services Market Strategic Shifts
Service delivery architectures are fragmenting across national data sovereignty boundaries while automation layers compress human-in-the-loop dependencies for routine infrastructure tasks.
Container orchestration platforms are hybridizing workload portability between public cloud hyperscalers and sovereign private clouds. South African financial institutions are adopting Kubernetes-based management stacks at the fastest regional pace. This hybridizing capability is collapsing the traditional distinction between managed hosting and cloud-native operations, forcing providers to reprice contracts around outcome metrics rather than resource allocation.
South Africa's Protection of Personal Information Act enforcement is tightening audit requirements for external service providers processing personal information. The regulator's penalty framework now exposes managed service providers to direct liability for client data breaches. Healthcare and insurance verticals in Johannesburg and Cape Town are responding by demanding dedicated single-tenant infrastructure with documented data residency chain-of-custody.
Enterprise buyers are unbundling security operations from general infrastructure management contracts. Nigerian banking procurement teams are separating SOC-as-a-service from network management to access specialized threat intelligence capabilities. This disaggregation is most visible in Lagos, where tier-one institutions maintain relationships with three distinct providers for endpoint, network, and cloud security monitoring.
Africa Managed Services Market Segmentation
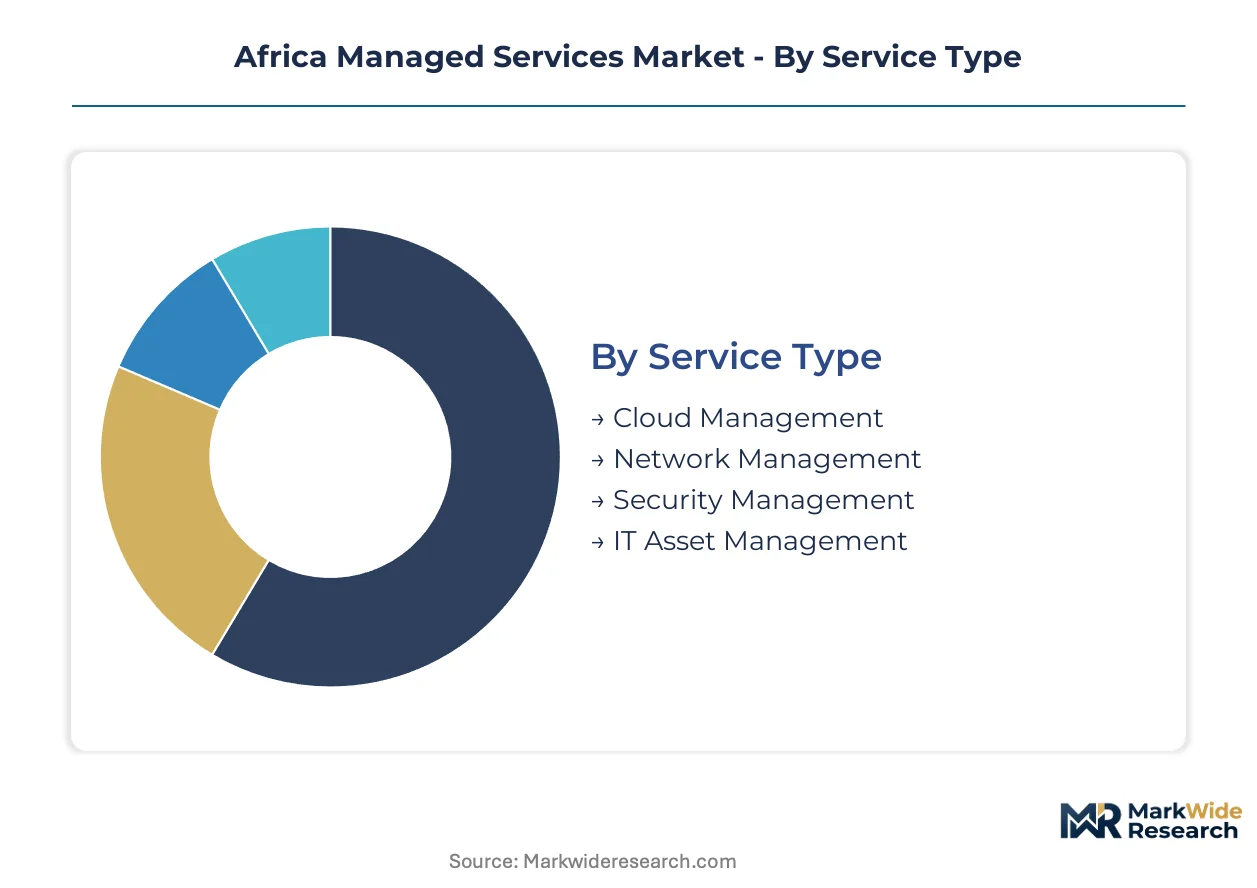
Managed services delivery across Africa fragments along operational maturity, regulatory exposure, and infrastructure legacy. Service providers architect differentiated offerings around data sovereignty mandates, uptime requirements, and hybrid cloud readiness.
Service Type:
Cloud Management commands the largest share of current contract value as enterprises migrate from aging data centers. Security Management generates the fastest expansion, driven by escalating cyber threats against banking and telecommunications infrastructure.
- Cloud Management:Unified orchestration across AWS, Azure, and private VMware environments with automated provisioning and cost optimization. Nigerian banks in Lagos and Nairobi's financial district drive demand for hybrid workload portability under strict uptime guarantees.
- Security Management:24/7 security operations center monitoring, threat intelligence integration, and incident response under defined mean-time-to-detect contracts. Kenya's Data Protection Act compliance mandates are expanding localized SOC demand among East African enterprises.
- Network Management:WAN optimization, SD-WAN deployment, and carrier-agnostic connectivity management for distributed branch operations.
- IT Asset Management:Hardware lifecycle tracking, software license compliance, and disposal certification for regulated industries.
Established volume favors Cloud Management; emerging adoption favors Security Management.
End User:
Financial services institutions concentrate procurement spend around compliance-heavy infrastructure outsourcing. Healthcare digitization creates greenfield demand for HIPAA-aligned managed hosting without legacy migration burdens.
- Financial Services:Core banking infrastructure outsourcing, payment system uptime guarantees, and regulatory audit support. Lagos-based institutions drive Nigeria's banking sector modernization through legacy system transitions to cloud-native architectures.
- Healthcare:Hospital information system hosting, electronic medical record management, and clinical device integration. Ghana and Kenya present untapped demand for managed services aligned with patient data protection requirements.
- Telecommunications:5G network operations center outsourcing and subscriber data management for mobile operators lacking in-house scale.
- Retail:Point-of-sale system monitoring, e-commerce platform management, and supply chain application hosting.
Procurement sophistication peaks in Financial Services; contract growth rates climb fastest in Healthcare.
Deployment Model:
Hybrid configurations capture disproportionate margin pools by combining public cloud elasticity with private infrastructure compliance. Pure public deployments face headwinds from data localization mandates.
- Hybrid Cloud:Workload portability between hyperscaler resources and sovereign private clouds with unified management stacks. South African financial institutions adopt Kubernetes-based orchestration at the fastest regional pace.
- Private Cloud:Single-tenant infrastructure with documented data residency chain-of-custody for POPIA and NDPR compliance.
- Public Cloud:Shared infrastructure resources with consumption-based pricing for non-regulated workloads.
- On-Premises:Managed services delivered to client-owned data centers with remote monitoring and field engineering support.
Margin concentration sits with Hybrid Cloud; compliance constraints restrict Public Cloud expansion in regulated verticals.
Technology:
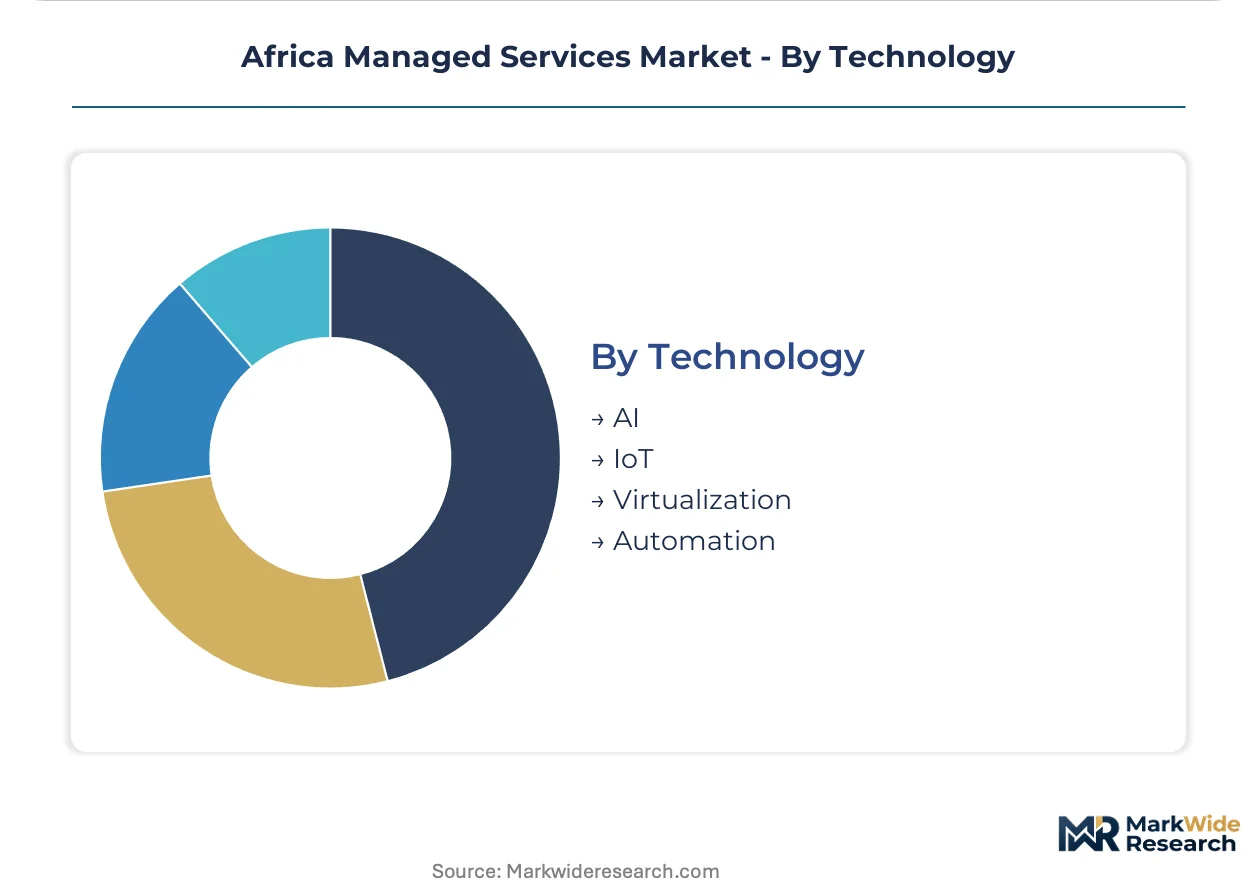
Predictive capabilities and autonomous remediation are compressing human-in-the-loop dependencies for routine infrastructure tasks. Certification timelines across multiple platforms constrain deployment velocity.
- AI:Machine learning-driven anomaly detection, predictive maintenance, and automated ticket routing with guaranteed mean-time-to-repair reductions.
- Automation:Infrastructure-as-code deployment, self-healing systems, and scripted remediation workflows.
- IoT:Connected device monitoring, edge computing management, and sensor data pipeline optimization.
- Virtualization:VMware and Hyper-V environment management with legacy workload containerization.
AI-powered offerings command premium pricing tiers; Virtualization retains the largest installed base requiring ongoing management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The West Africa Cable System landing in Lagos anchors Nigeria's position as the continent's primary data transit hub, channeling submarine bandwidth that underwrites managed services delivery across West African financial centers.
South Africa
Johannesburg's concentration of banking headquarters drives demand for POPIA-compliant hybrid cloud management, with Cape Town emerging as a secondary node for healthcare digitization projects requiring HIPAA-aligned hosting infrastructure.
Nigeria
Lagos-based institutions dominate procurement for legacy core banking modernization, while the Central Bank's cybersecurity framework mandates localized security operations centers that exclude pure offshore delivery models.
Kenya
Nairobi's financial district generates concentrated demand for cross-border data transfer compliance under the Data Protection Act, with Mombasa serving as the coastal failover site for East African enterprise disaster recovery architectures.
Egypt
Cairo anchors North African managed services demand through government-led smart city initiatives, while the Suez Canal Economic Zone attracts hyperscaler investment that expands local cloud infrastructure capacity.
Ethiopia
Addis Ababa's banking liberalization creates greenfield demand without legacy migration burdens, as newly licensed private banks seek fully outsourced core infrastructure under the National Bank of Ethiopia's evolving regulatory guidance.
Africa Managed Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in security and network optimization subsystems. The market exhibits moderate concentration with global technology vendors anchoring high-value contracts while regional systems integrators capture mid-market share through localized compliance expertise. Three archetypes dominate: hyperscaler-aligned platform vendors, Johannesburg-headquartered pan-African specialists, and telecom-carrier-affiliated service divisions. Competitive intensity centers on strategic partnerships with local integrators and certification investments for multi-cloud orchestration capabilities.
Among global platform vendors, Cisco Systems and IBM Corporation exemplify the hyperscaler-aligned archetype, leveraging extensive partner networks to extend managed service reach into regulated African enterprises. Dimension Data occupies a distinct position as a Johannesburg-based pan-African specialist, drawing geographic proximity advantages for financial services clients across multiple jurisdictions. These three anchors illustrate how competitive positioning stratifies between global scale and regional compliance depth.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM Corporation |
| Accenture PLC |
| Dimension Data |
| Fujitsu Ltd. |
| Orange Business Services |
| Liquid Telecom |
| HP Development Company LP |
| NEC Corporation |
| Others |
Value Chain & Pricing Dynamics
The West Africa Cable System landing in Lagos channels submarine bandwidth costs that concentrate supply leverage among Johannesburg and Nairobi data center operators, compressing margin pools for mid-tier providers while enabling premium pricing for POPIA-certified hybrid cloud delivery.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with premium tiers anchored by ISO 27001 certification and dedicated single-tenant infrastructure. Price differentiation hinges on data residency chain-of-custody documentation and guaranteed mean-time-to-repair commitments. Cost compression in standard tiers is intensifying because diesel generator capital requirements in Lagos and Nairobi erode provider economics. Nigerian banking procurement teams exhibit highest price sensitivity, while South African healthcare institutions absorb premium rates for HIPAA-aligned hosting.
Supply Chain Analysis
Single-source vulnerability in specialized cybersecurity talent pools dominates supply risk, as certified SOC analysts command compensation premiums that inflate service delivery costs across the continent. Hardware concentration rests on South Africa, Nigeria, and Kenya for in-country server deployment mandated by POPIA and NDPR. Critical dependencies include VMware licensing, Cisco networking equipment, and AWS/Azure hyperscaler credits. Distribution runs through Johannesburg-headquartered pan-African specialists with certified partner networks extending into Lagos and Nairobi financial districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as data sovereignty mandates splinter service delivery architectures, creating specialized niches for compliance-first providers around Kenya's Data Protection Act and South Africa's POPIA enforcement.
For Market Incumbents: Build certification moats around multi-cloud orchestration credentials across AWS, Azure, and Google Cloud platforms. Invest in localized security operations centers in Lagos and Nairobi to preempt regulatory exclusion. Absorb diesel generator capital costs in Nigeria and Kenya to defend market share against leaner entrants.
For New Entrants and Emerging Players: Pursue greenfield banking infrastructure contracts in Addis Ababa as Ethiopia's banking liberalization creates demand without legacy migration burdens. Target healthcare digitization projects in Ghana and Kenya for HIPAA-aligned managed hosting. Lead with AI-powered predictive maintenance capabilities to differentiate against established volume players.
For Investors and Strategic Acquirers: Carve-out targets emerge from telecom-carrier-affiliated service divisions seeking to monetize non-core IT infrastructure assets. Long-term viability favors providers with sovereign private cloud capacity and documented data residency compliance. Monitor enforcement actions by South Africa's Information Regulator as inflection indicator for compliance-cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Certification Investment | AWS, Azure, and Google Cloud credentials enable premium-tier contract capture in Lagos banking sector. |
| Localized SOC Buildout | Nairobi and Lagos security operations centers satisfy Kenya's Data Protection Act cross-border transfer mandates. |
| AI-Powered Predictive Maintenance | Machine learning anomaly detection commands guaranteed mean-time-to-repair reductions in telecommunications. |
| Healthcare Compliance Specialization | HIPAA-aligned hosting infrastructure captures Ghana and Kenya hospital digitization procurement. |
| Strategic Partnership with Local Integrators | Certified partner networks extend Cisco and IBM reach into mid-market accounts across the continent. |
Study Parameters
Cross-validation between primary interviews with CTOs, IT procurement officers, and platform engineers and secondary validation through hyperscaler capex disclosures, SEC filings, and national data protection regulator enforcement records anchors the qualitative findings. Bottom-up contract analysis across Lagos, Nairobi, and Johannesburg financial districts triangulates with top-down market sizing from service provider revenue disclosures.
Calibration against historical adoption curves for hybrid cloud orchestration and security management services shapes the analytical framework across the analysis window. Segmentation dimensions modeled include service type, deployment model, end-user vertical, and technology layer. CAGRs derive from regression against infrastructure outsourcing penetration rates and regulatory compliance cost trajectories. Forecast inputs incorporate 5G network rollout timelines and banking sector modernization project pipelines.
Macroeconomic conditions sit as an overlay; deviation in currency volatility across Nigerian naira and Kenyan shilling or escalation in power infrastructure instability would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement intensity and talent pool expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Shared Services Market
Enterprise Services
Mobile Enterprise Application Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Proactive Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Shared Services Center Market