
 Shared Services Center Market | 2026-2036
Shared Services Center Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Services Center Market Outlook
Market Context
GDPR is expanding the cost-of-entry calculus for shared services operators serving European enterprise clients. Accenture leverages its compliance infrastructure to sustain multi-jurisdictional delivery capabilities. IBM anchors its position through proprietary automation platforms that reduce regulatory overhead. Wipro competes by specializing in sector-specific process architectures for healthcare and manufacturing clients.
Technical Definition and Structural Segments
A shared services center consolidates business functions—finance, human resources, information technology, and customer support—into a single operational unit delivering standardized processes at scale through enterprise resource planning integration and workflow automation. By delivery model, cloud-based configurations are capturing the fastest expansion as enterprises prioritize remote accessibility and elastic capacity scaling over fixed on-premise infrastructure. By client type, large enterprises dominate current revenue pools while SMEs represent the underpenetrated expansion frontier where modular service packaging is displacing traditional full-function outsourcing.
Regulatory Frame and Outlook
The EU AI Act and HIPAA impose divergent compliance architectures on shared services centers processing automated decision-making or protected health information across jurisdictions. ISO standards for information security management and service delivery quality function as de facto market access prerequisites for vendor selection by risk-sensitive clients. Stakeholders must monitor how emerging algorithmic accountability requirements reshape automation investment priorities and geographic service distribution.
Market Dynamics
Enterprise migration from fixed-cost on-premise infrastructure to consumption-based cloud delivery is compressing traditional shared services economics and forcing operators to restructure talent deployment across distributed delivery nodes.
Growth Catalysts
- EU AI Act:Mandates for human oversight in automated decision-making are creating specialized compliance service lines that command premium pricing from European enterprise clients.
- Healthcare digitization:HIPAA-covered entities are consolidating fragmented administrative functions into centralized platforms, expanding addressable volume for specialized healthcare shared services operators.
- India:Concentration of finance and IT talent pools in Bangalore and Hyderabad continues to attract captive center investments from multinational enterprises seeking process standardization.
Market Restraints
- GDPR cross-border friction:Data localization requirements and adequacy ruling uncertainties are elevating legal engineering costs for shared services centers serving European clients from non-adequate jurisdictions.
- Specialized automation talent scarcity:Shortage of process architects capable of configuring robotic process automation at scale is constraining throughput expansion for mid-tier operators.
- Cloud infrastructure concentration:Dependency on three dominant hyperscale providers creates vendor lock-in risk and limits negotiation leverage for shared services centers managing elastic capacity contracts.
Strategic Opportunities
- SME modular penetration:Mid-market enterprises previously excluded from full-function outsourcing represent expansion terrain where standardized process modules displace bespoke consulting engagements.
- ISO 27001 certification arbitrage:Information security management certification is becoming a de facto procurement filter, creating differentiation leverage for early-adopter operators against uncertified competitors.
- Process mining convergence:Integration of task capture analytics with legacy ERP systems enables predictive workflow optimization that reduces client-specific customization overhead.
Industry Challenges
- Multi-jurisdictional compliance orchestration:Simultaneous adherence to HIPAA, GDPR, and emerging algorithmic accountability frameworks requires dedicated legal-technical liaison functions that strain organizational bandwidth.
- Technical debt in ERP integration:Heterogeneous client technology stacks demand costly middleware development to achieve promised workflow automation outcomes.
Report Scope
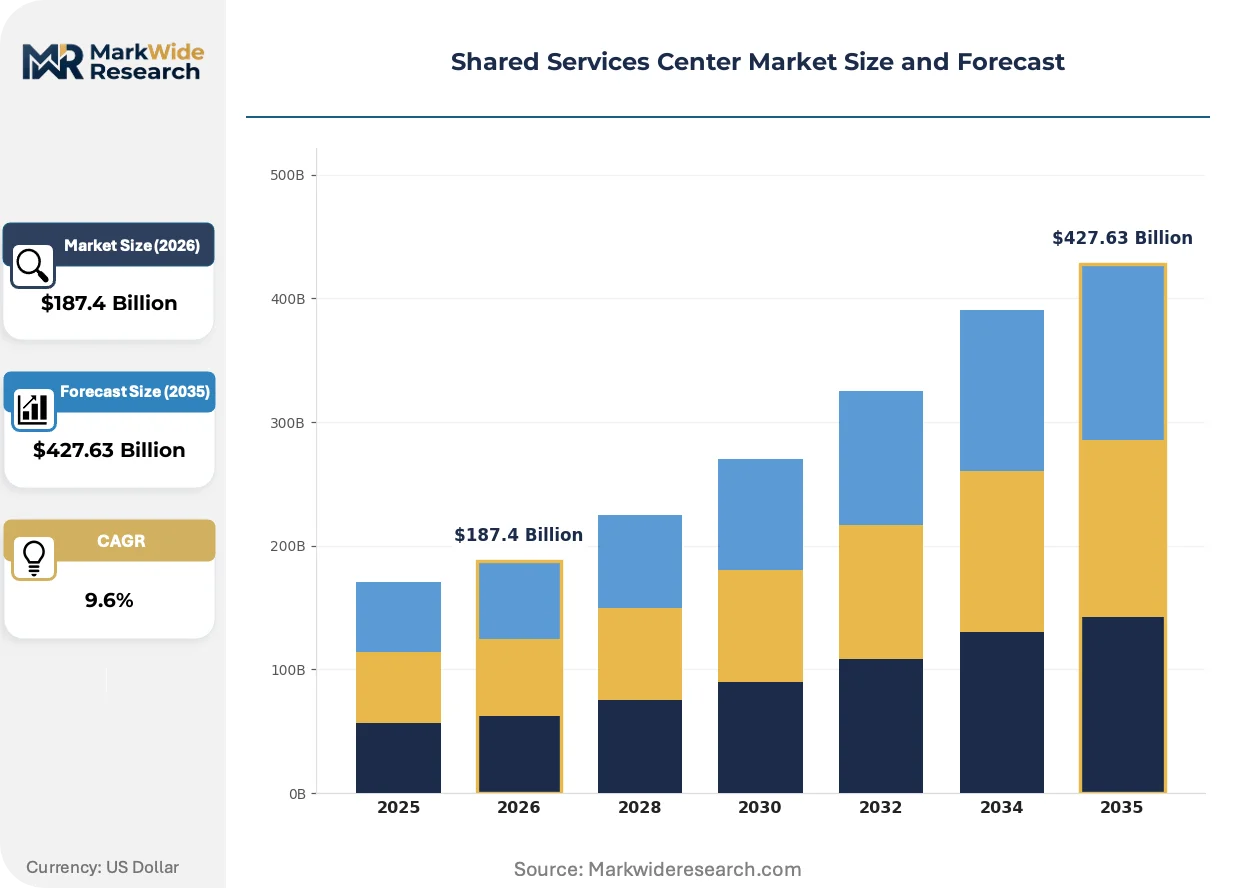
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Services Center Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $427.63 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Finance, HR, IT, Customer Support Industry Vertical: Healthcare, Manufacturing, Retail, Telecom Delivery Model: On-premise, Cloud-based, Hybrid, Outsourced Client Type: SMEs, Enterprises, Public Sector, Non-profits |
| Companies Covered | DXC Technology, Capgemini, Accenture, NTT DATA, HCL Technologies, IBM, Wipro, Infosys, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Services Center Market Strategic Shifts
Operational technology in shared services is pivoting from labor arbitrage toward intelligence arbitrage, where competitive differentiation derives from algorithmic process discovery rather than wage differential alone.
Intelligent document processing is integrating computer vision with natural language understanding to extract unstructured data from invoices, contracts, and medical records without template-dependent configuration. Healthcare payers and property-and-casualty insurers are deploying these systems at scale to eliminate manual transcription queues. The technology is integrating previously siloed capture workflows into unified ingestion pipelines that compress end-to-end cycle times.
CSRD disclosure requirements are mandating granular sustainability reporting from shared services operators serving EU-listed enterprise clients. Scope 3 emissions tracking and supply chain due diligence documentation are becoming standard contractual appendices. Finance and accounting shared services centers with carbon accounting capabilities are capturing preference in RFP evaluations from European manufacturing conglomerates.
Enterprise buyers are unbundling monolithic outsourcing contracts into discrete process-specific engagements with shorter renewal cycles and performance-based fee structures. Large pharmaceutical and industrial clients are disaggregating finance operations into separate procure-to-pay, order-to-cash, and record-to-report contracts. North American healthcare systems are driving this fragmentation most aggressively, using competitive pressure across modular providers to extract service-level improvements.
Shared Services Center Market Segmentation
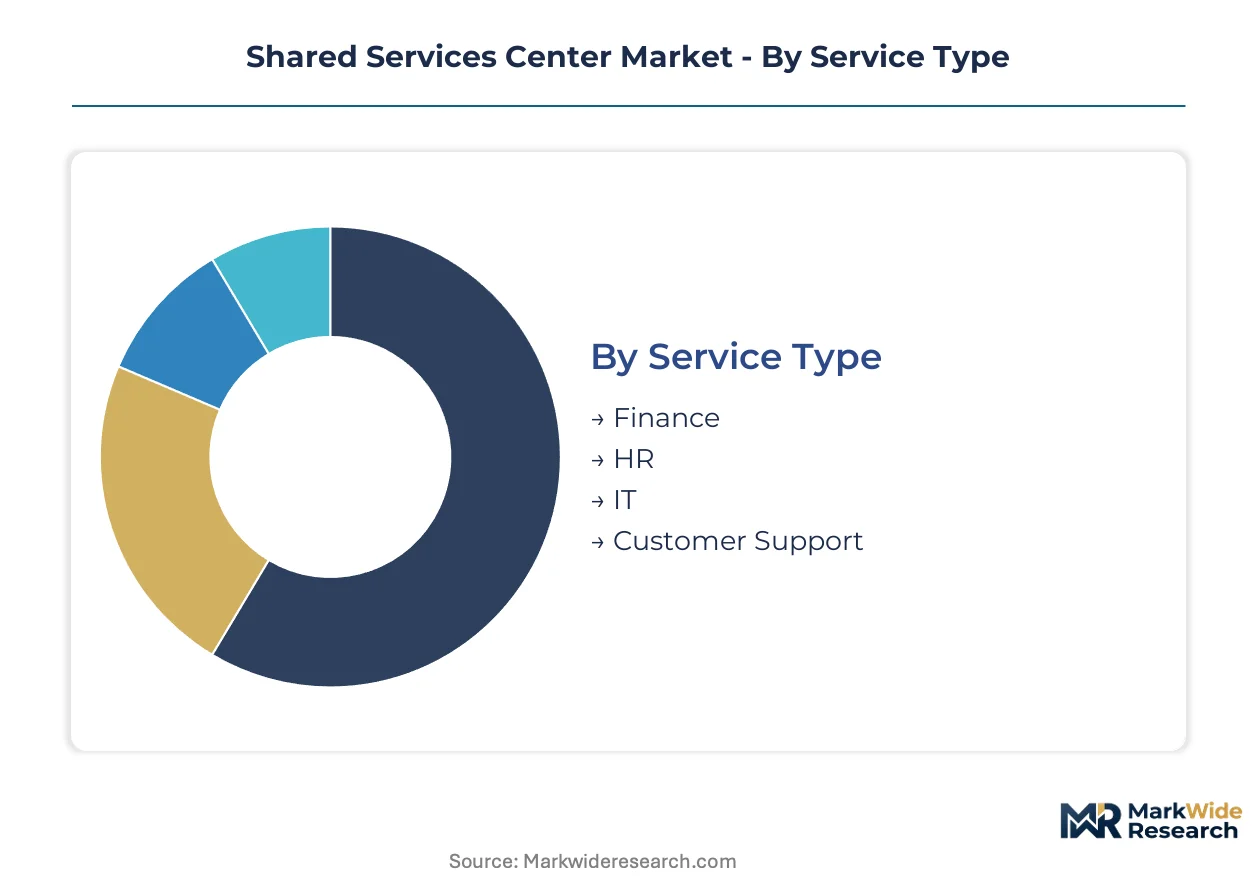
Shared services center configurations vary dramatically by operational mandate and client sophistication. Standardization levels determine whether providers deploy template-driven platforms or bespoke process architectures. Segmentation reveals where margin concentrates and which service lines demand specialized compliance infrastructure.
Service Type:
Customization intensity spans from rigid regulatory-bound functions to adaptive knowledge services across this category.
- Finance:Encompasses procure-to-pay, order-to-cash, and record-to-report processes governed by SOX and IFRS requirements. Demand clusters in India and Poland where chartered accountant density supports multi-entity consolidation for manufacturing conglomerates navigating CSRD disclosure mandates.
- HR:Payroll administration, benefits management, and talent acquisition workflows. German automotive and industrial clients drive specialization here, requiring Works Council consultation protocols and collective bargaining compliance that resist full automation.
- IT:Service desk operations, infrastructure management, and application support. Cloud migration projects and cybersecurity monitoring dominate current engagement scopes.
- Customer Support:Multi-channel inquiry resolution and technical assistance. Healthcare payers and telecom operators represent primary demand sources.
Most installed capacity flows through Finance. Expansion is steepest in IT.
Industry Vertical:
Regulatory density and process complexity create divergent margin profiles across vertical applications.
- Healthcare:HIPAA-covered revenue cycle management, claims adjudication, and patient access services. US hospital systems consolidate fragmented administrative functions here, with HIPAA audit readiness commanding premium pricing from specialized operators.
- Manufacturing:Supply chain finance, vendor master data management, and plant maintenance administration. German and Japanese automotive OEMs anchor demand through captive center investments in Eastern Europe and Mexico.
- Retail:Omnichannel order management, returns processing, and supplier collaboration platforms. Seasonal volume volatility drives preference for elastic cloud delivery configurations.
- Telecom:Subscriber lifecycle management, billing inquiry resolution, and network operations support. High transaction volumes favor robotic process automation deployment at scale.
Healthcare commands the highest compliance premiums. Retail is gaining share fastest through SME modular adoption.
Delivery Model:
Capital commitment and operational control trade off across deployment architectures.
- Cloud-based:Consumption-priced infrastructure with API-native ERP integration and elastic capacity scaling. GDPR adequacy uncertainties are redirecting some European enterprise demand toward EU-sovereign cloud instances operated by regional providers.
- Hybrid:Sensitive data remains on-premise while compute-intensive processing shifts to cloud. Financial services clients favor this architecture for fraud detection workloads.
- On-premise:Fixed infrastructure with dedicated hardware and localized disaster recovery. Defense and government clients maintain this preference for classified processing.
- Outsourced:Third-party operator assumes full operational responsibility under outcome-based contracts. Mid-market enterprises access enterprise-grade capabilities without captive center investment.
Cloud-based configurations carry the majority of new deployments. Hybrid architectures are climbing the fastest as regulated industries seek middle-ground compliance postures.
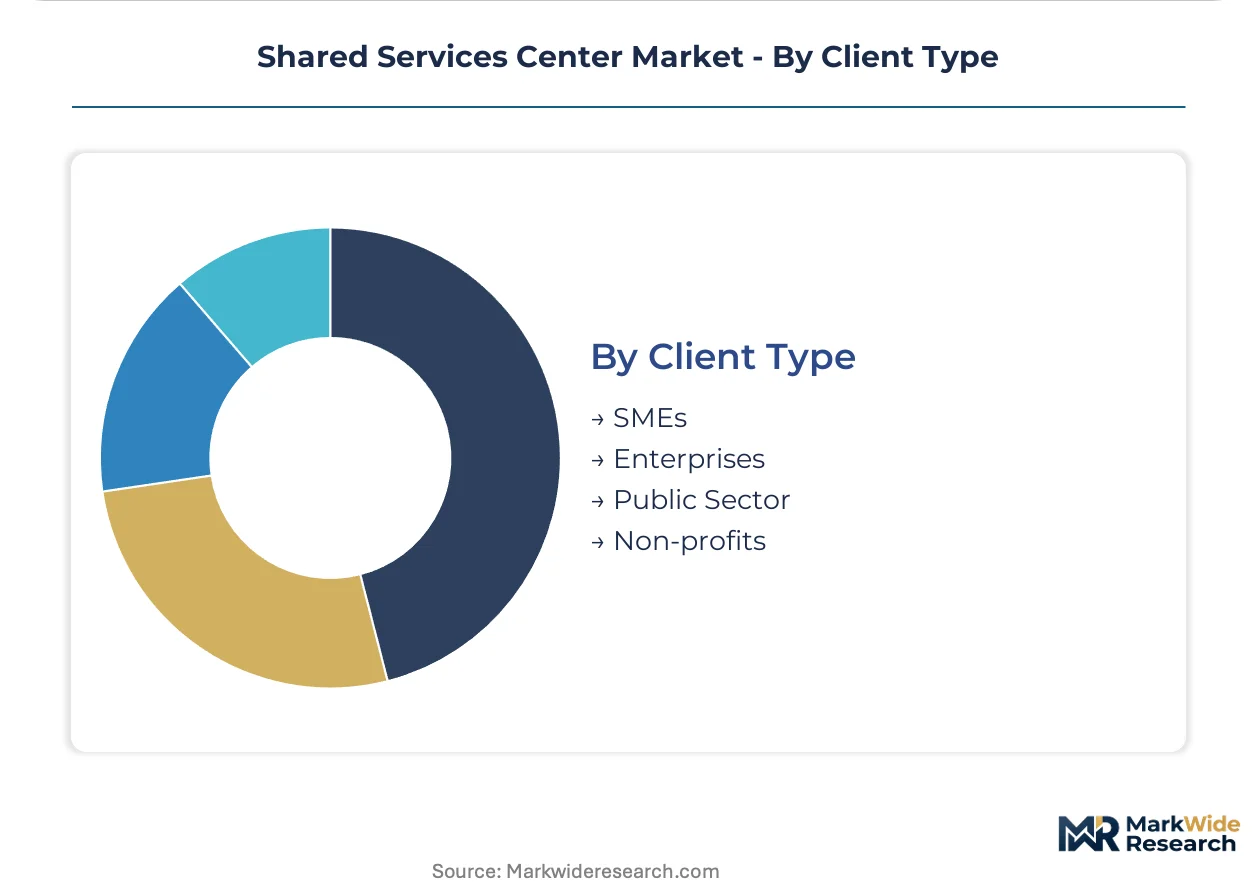
Client Type:
Scale economics and procurement sophistication determine service packaging approaches.
- Enterprises:Multi-national corporations operating captive centers or demanding bespoke SLAs. These clients drive process mining and predictive analytics adoption through dedicated innovation budgets.
- SMEs:Mid-market enterprises previously excluded from full-function outsourcing. Modular service packaging—procure-to-pay as standalone engagement rather than integrated finance transformation—opens this segment.
- Public Sector:Government agencies and state-owned enterprises with mandatory domestic delivery requirements. India's NeGP and similar digitization programs expand addressable volume.
- Non-profits:NGOs and charitable organizations with donor transparency mandates. Grant compliance reporting and restricted fund accounting create specialized service requirements.
Enterprises retain the deepest installed base. SME penetration is expanding most quickly as standardized modules displace consulting-led engagements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance and IT talent pools in Bangalore, Hyderabad, and Manila anchor the primary delivery infrastructure for multinational shared services operations. GDPR adequacy rulings and data localization mandates are redirecting European enterprise demand toward EU-sovereign cloud instances and regional captive centers.
India
Chartered accountant density in Bangalore and Hyderabad supports multi-entity consolidation for manufacturing conglomerates navigating CSRD disclosure mandates. The RBI's data localization guidelines for financial services processing reinforce domestic delivery preferences. Pune and Chennai host expanding captive centers for US healthcare payers seeking HIPAA-compliant revenue cycle management.
United States
Hospital systems in Texas and Florida consolidate fragmented administrative functions into centralized platforms, expanding demand for specialized healthcare shared services. HIPAA audit readiness commands premium pricing from operators serving covered entities. Phoenix and Dallas-Fort Worth attract cloud-native delivery investments from enterprise clients prioritizing domestic data residency.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg anchor demand through captive center investments requiring Works Council consultation protocols. The EU AI Act mandates for human oversight in automated decision-making create specialized compliance service lines. Frankfurt and Berlin host expanding finance shared services operations serving CSRD-mandated sustainability reporting requirements.
Poland
Multi-lingual finance talent in Kraków and Warsaw supports procure-to-pay and order-to-cash processes for Western European enterprise clients. GDPR adequacy status reduces legal engineering costs for cross-border service delivery from EU member states. Wrocław and Łódź attract IT shared services investments seeking EU-sovereign cloud infrastructure alternatives.
Philippines
English-language customer support talent in Metro Manila and Cebu anchors voice and non-voice BPO operations for North American healthcare payers and telecom operators. The country's national data privacy act imposes compliance frameworks modeled on GDPR principles. Clark and Davao host expanding delivery centers for mid-market enterprises accessing modular service packaging.
Shared Services Center Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with proprietary automation platforms and compliance infrastructure. Tier-one operators sustain multi-jurisdictional delivery capabilities through dedicated legal-technical liaison functions. Three archetypes dominate: India-headquartered IT services conglomerates, US-based consulting-technology hybrids, and European-origin business services specialists. M&A activity concentrates on process mining and intelligent document processing capabilities, while strategic partnerships with hyperscale cloud providers secure elastic capacity commitments.
Within the diversified technology services tier, Accenture and IBM occupy positions anchored by compliance infrastructure and proprietary automation platforms respectively. India-headquartered operators Wipro and Infosys exemplify the scale-driven archetype competing through sector-specific process architectures and finance-IT talent concentration. These entities represent the competitive core where GDPR complexity and healthcare digitization demands filter market access.
| Leading Market Players |
|---|
| DXC Technology |
| Capgemini |
| Accenture |
| NTT DATA |
| HCL Technologies |
| IBM |
| Wipro |
| Infosys |
| Cognizant |
| Others |
Value Chain & Pricing Dynamics
Finance and IT talent concentration in Bangalore and Hyderabad drives labor-cost differentials that translate into pricing-tier spreads between premium compliance-certified operators and uncertified mid-tier competitors.
Pricing Analysis
Bundled full-function outsourcing contracts are fragmenting into unbundled process-specific engagements with shorter renewal cycles. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified operators with multi-jurisdictional compliance infrastructure from uncertified regional providers and commodity transactional processors. Cost compression in the economy tier is intensifying because hyperscale cloud vendor lock-in limits negotiation leverage for mid-tier operators. SME buyers exhibit highest price sensitivity, while healthcare payers prioritize HIPAA audit readiness over unit cost.
Supply Chain Analysis
Freight costs for cross-border service delivery are negligible compared to talent mobility and data residency compliance expenses. Supply concentration centers on India, Poland, and the Philippines for finance and IT talent pools, with Germany and the United States anchoring specialized healthcare and automotive captive centers. Raw material dependencies rest on chartered accountant density, multi-lingual workforce availability, and hyperscale cloud infrastructure capacity. Single-source vulnerability runs through AWS, Azure, and Google Cloud concentration. Distribution runs through direct enterprise sales, channel partners, and modular service marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Shared Services Center Market functions as a stable compounder where enterprise digitization mandates and regulatory complexity generate recurring demand for compliance-anchored service delivery.
For Market Incumbents: Lock in multi-jurisdictional compliance infrastructure as a defensive moat against specialized automation talent scarcity that constrains mid-tier competitor expansion. Deepen vertical integration into proprietary process mining and intelligent document processing capabilities to reduce client-specific customization overhead. Prioritize ISO 27001 certification maintenance and EU-sovereign cloud partnerships to defend margin position against GDPR adequacy uncertainties. For New Entrants and Emerging Players: Cloud-native ERP integrators represent the most accessible channel partner type for penetrating SME modular service packaging without captive center investment. White-space targets include mid-market healthcare systems in the United States and German automotive suppliers requiring Works Council-compliant HR shared services. A process-mining-as-a-service go-to-market angle bypasses incumbent scale advantages in full-function outsourcing. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking service delivery partners with established enterprise relationships and compliance certifications. Long-term viability frames this market as a beneficiary of structural enterprise cost reduction imperatives and regulatory complexity expansion. Acquisition targets should display sector-specific process architectures in healthcare or manufacturing alongside ISO-certified delivery infrastructure. Watch for EU AI Act enforcement patterns as an inflection indicator for compliance service line premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | Information security certification functions as a de facto procurement filter for risk-sensitive enterprise clients. |
| EU-Sovereign Cloud Partnership | Regional cloud infrastructure addresses GDPR adequacy uncertainties redirecting European enterprise demand. |
| Process Mining Capability Acquisition | Predictive workflow optimization reduces client-specific customization overhead and accelerates margin expansion. |
| Healthcare Vertical Specialization | HIPAA audit readiness commands premium pricing from US hospital systems consolidating administrative functions. |
| Intelligent Document Processing Deployment | Computer vision and natural language understanding eliminate manual transcription queues for insurance and healthcare payers. |
Study Parameters
Coverage spans India, the United States, Germany, Poland, and the Philippines, with primary inputs from each market cluster through structured interviews with shared services center directors, enterprise procurement officers, compliance officers, and cloud infrastructure architects. Secondary validation draws from RBI data localization guidelines, HIPAA enforcement actions, EU AI Act implementation guidance, SEC filings of publicly traded operators, and ISO certification registries. Bottom-up service line sizing triangulates against top-down enterprise spending estimates across the projection horizon.
Rate-of-change decomposition separates volume expansion from pricing evolution across service type, delivery model, industry vertical, and client size tier. Segmentation dimensions modeled include finance, HR, IT, and customer support functions; cloud-based, hybrid, on-premise, and outsourced deployment architectures; and enterprise, SME, public sector, and non-profit buyer categories. CAGRs derive from regression analysis against enterprise cloud migration velocity, regulatory implementation timelines, and talent pool growth trajectories. Industry-specific forecast inputs incorporate chartered accountant graduation rates in India and GDPR adequacy ruling patterns affecting cross-border delivery economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement stringency, hyperscale cloud pricing power, and India talent pool saturation. Forecasts reflect documented assumptions about enterprise digitization continuity and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Supplier Management Market
Enterprise Services
Enterprise Internet Reputation Management Market