
 Global Sunflower Seed (Seed for Sowing) Market | 2026-2036
Global Sunflower Seed (Seed for Sowing) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sunflower Seed (Seed for Sowing) Market Foresight
Competitive Landscape
A capital-intensity divergence between integrated seed-chemical platforms and specialized breeders is reorganizing competitive tiers in sunflower seed supply. Bayer Crop Science leverages its trait-stacked hybrid pipeline and crop protection bundling to dominate high-value acreage in Eastern Europe. KWS SAAT SE anchors its position through deep in-house production of proprietary inbred lines and regional adaptation programs. Sakata Seed Corporation differentiates via confectionery-type specialization and quality-focused breeding for premium snack food channels.
Product Structure and Segment Dynamics
Sunflower seed for sowing comprises genetically stabilized propagules bred for specific oil profiles, disease resistance packages, and agronomic traits, with hybrid seed requiring controlled pollination between distinct male and female inbred lines to produce first-generation commercial grain. Oilseed-type hybrids command the largest volume share due to integrated crush facility demand and food oil processor contracting, while Clearfield varieties with imidazolinone tolerance represent the fastest-expanding margin pool as herbicide-resistant weed pressure intensifies across the Black Sea basin. Confectionery seed for sowing occupies a narrower but higher-margin niche tied to shelling-grade specifications and direct retail snack supply chains.
Regulatory Environment and Strategic Outlook
The EU Green Deal and F-Gas Regulation shape breeding priorities by penalizing carbon-intensive production systems and rewarding climate-adapted germplasm, while USDA-APHIS phytosanitary protocols govern cross-border seed movement into the United States and FDA food-contact regulations influence oil composition targets for edible end uses. Ukraine's State Service on Food Safety and Consumer Protection and Russia's Federal Service for Veterinary and Phytosanitary Surveillance enforce distinct national variety registration and seed certification requirements that fragment market access protocols. Stakeholders must monitor accelerating divergence between EU sustainability disclosure mandates and Black Sea basin regulatory enforcement capacity as seed trade policy becomes entangled with broader agricultural commodity geopolitics.
Market Dynamics
Commercial oilseed farming operations are expanding acreage under high-oleic hybrid varieties while EU F-Gas Regulation and broader EU Green Deal sustainability mandates redirect breeding investment toward nitrogen-use-efficient genetics, compressing time-to-market for climate-adapted germplasm.
Growth Catalysts
- EU Green Deal nitrogen-efficiency mandates:The EU F-Gas Regulation penalizes carbon-intensive production systems, rewarding breeders who develop climate-adapted germplasm with faster variety registration pathways.
- Black Sea export-oriented crush expansion:Ukraine, Russia, and Argentina are expanding sunflower cultivation for edible oil and confectionery supply chains, concentrating demand in these origin markets.
- Herbicide-resistant weed pressure:Imidazolinone-tolerant Clearfield varieties are capturing expanded margin pools as resistant weed populations intensify across the Black Sea basin.
Market Restraints
- Input cost volatility in controlled pollination:Labor-intensive hybrid seed production requires precise male-female inbred line management, with labor and isolation distance costs subject to agricultural wage inflation.
- Supply concentration in Eastern European germplasm:Proprietary inbred line production concentrates in Ukraine and Russia, exposing global supply chains to geopolitical disruption and phytosanitary blockades.
- Regulatory fragmentation in variety registration:Ukraine's State Service on Food Safety and Russia's Federal Service for Veterinary and Phytosanitary Surveillance enforce divergent national certification requirements that fragment market access protocols.
Strategic Opportunities
- Underpenetrated confectionery-type specialization:Premium snack food channels in North America and Western Europe offer higher-margin positioning for shelling-grade specifications with limited current breeder focus.
- Technology convergence in marker-assisted selection:Genomic selection tools combined with rapid generation advancement are compressing breeding cycles for disease resistance packages.
- Distribution innovation through processor contracting:Direct contracting between seed suppliers and integrated crush facilities is bypassing traditional distributor channels in Argentina and Russia.
Industry Challenges
- Phytosanitary certification timeline compression:USDA-APHIS protocols governing cross-border seed movement into the United States impose multi-season quarantine and testing requirements that delay commercial launch.
- Skill scarcity in hybrid seed production:Controlled pollination between distinct male and female inbred lines requires specialized technicians with declining agricultural workforce pipeline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sunflower Seed (Seed for Sowing) Market |
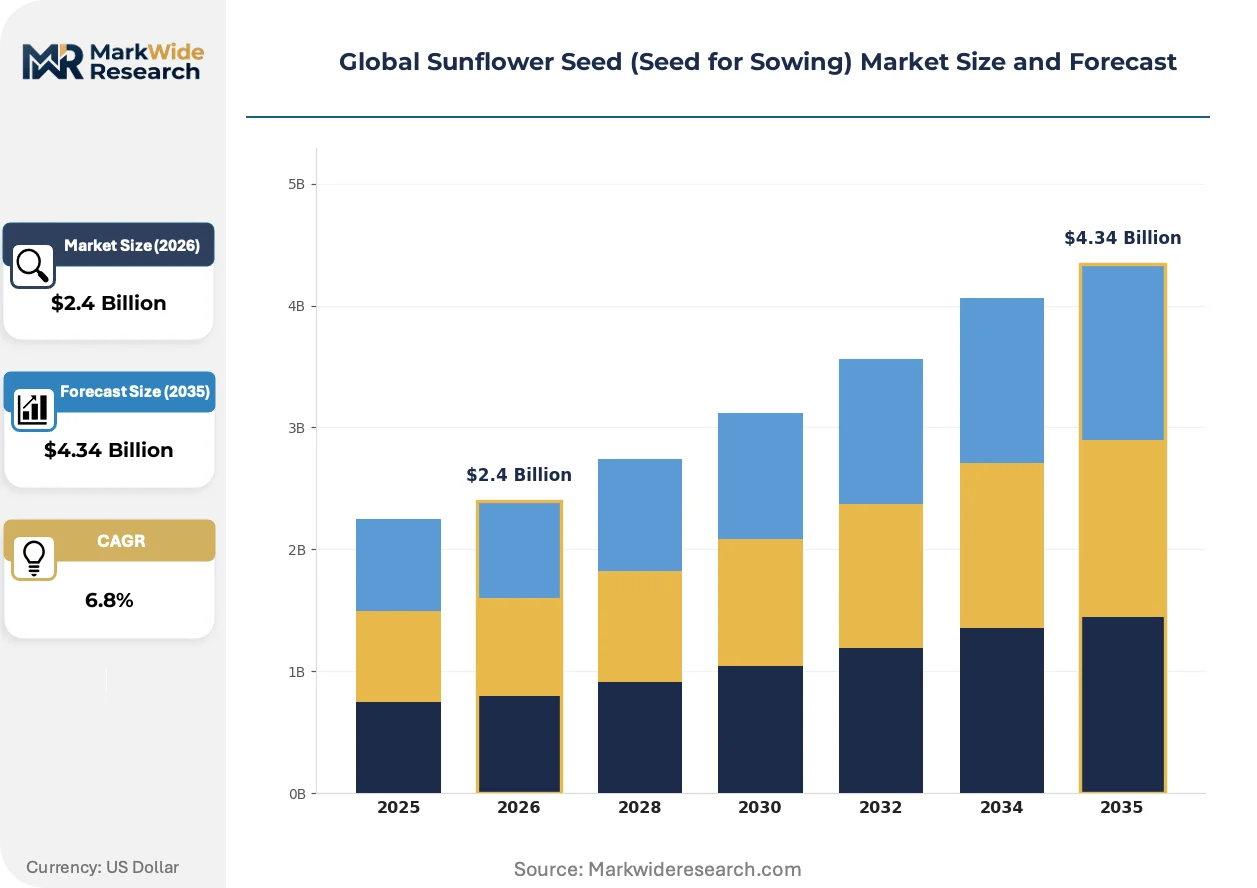
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Open-Pollinated, Clearfield, Organic, Conventional Crop Variety: Oilseed, Confectionery, Industrial, Non-GMO Planting Method: Direct Seeding, Transplanting, Raised Bed, Strip Cropping End Use Industry: Edible Oil Production, Snack Food Manufacturing, Cosmetics, Animal Feed |
| Companies Covered | Bayer Crop Science AG, Corteva Agriscience, Syngenta AG, BASF SE, Groupe Limagrain Holding SA, KWS SAAT SE & Co KGaA, Sakata Seed Corporation, Nufarm Limited, Land O'Lakes, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sunflower Seed (Seed for Sowing) Market Shifts & Advancements
Genomic tools and sustainability-linked breeding priorities are compressing development timelines while reshaping competitive advantage around climate adaptation and input efficiency rather than yield alone.
Marker-assisted selection platforms leveraging high-density single nucleotide polymorphism arrays are accelerating stacking of disease resistance loci and oil profile genes. Commercial breeders in Eastern Europe and Argentina are adopting these platforms at scale for hybrid line development. Conventional phenotypic selection is supplanting as the dominant breeding paradigm, compressing variety release cycles from eight years to four.
The EU F-Gas Regulation and associated EU Green Deal sustainability disclosure mandates are penalizing carbon-intensive nitrogen fertilizer regimes. Industrial consequence forces breeders to prioritize nitrogen-use-efficient genetics with documented greenhouse gas reduction credentials. Oilseed-type hybrids destined for EU crush facilities face the most stringent documentation requirements, with breeders investing in lifecycle assessment capabilities.
Processor-led procurement consolidation is displacing distributor-mediated seed purchasing in major producing regions. Large integrated crush facilities in Ukraine and Argentina now contract directly with breeders for volume commitments and identity-preserved oil profiles. This channel shift is most visible in the Black Sea basin where vertical integration between crushing and farming operations concentrates buying power.
Global Sunflower Seed (Seed for Sowing) Market Segmentation
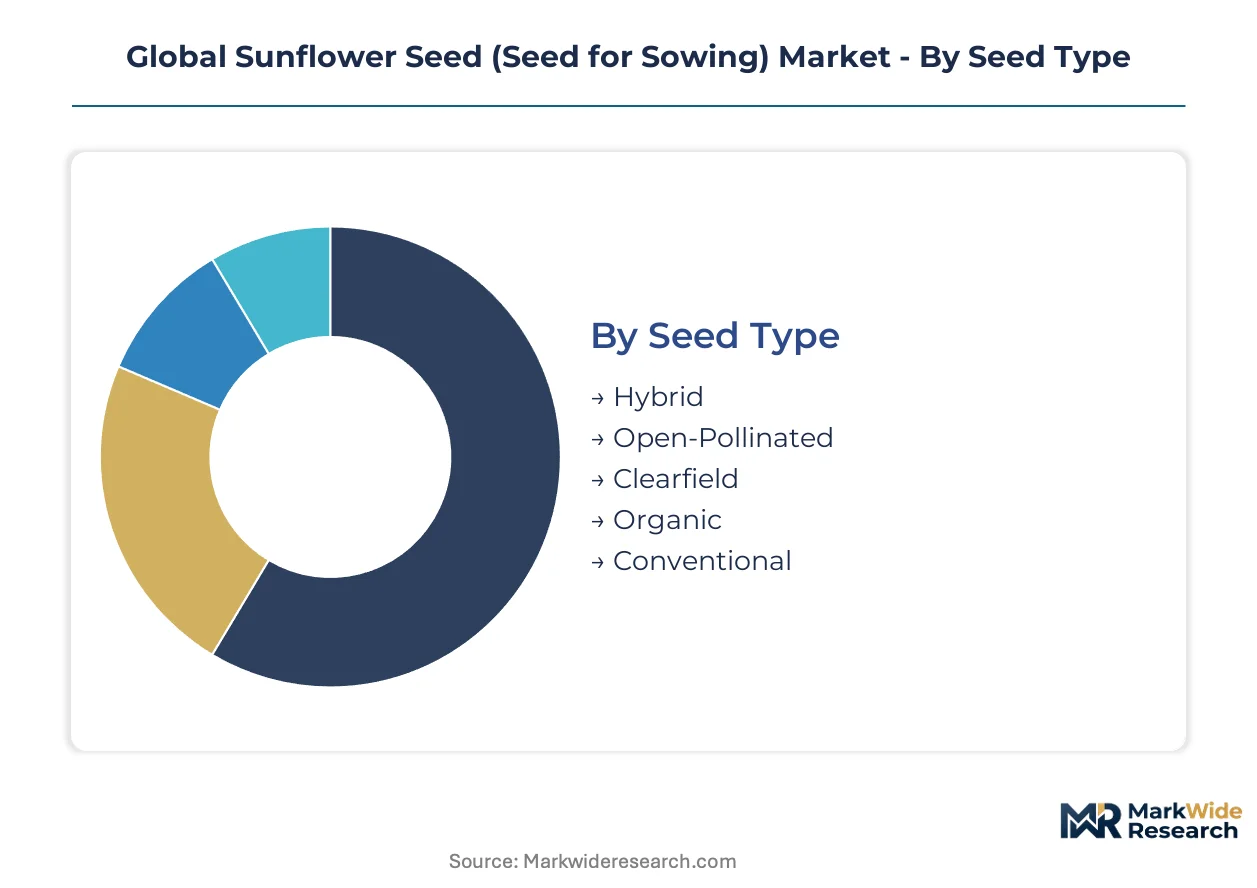
Sunflower seed for sowing segments diverge sharply by genetic system and end-use specification, with hybrid and Clearfield varieties commanding premium positioning against commoditized open-pollinated alternatives. Breeders configure product portfolios around crush facility contracting requirements and snack food processor quality protocols.
Seed Type:
Substitution pressure from herbicide-tolerant genetics and organic certification standards is fragmenting demand across proprietary and public-domain germplasm pools.
- Hybrid:First-generation crosses between distinct male and female inbred lines deliver heterosis for yield stability and oil concentration. Demand concentrates in Ukraine and Russia where integrated crush facilities contract directly for high-oleic hybrid volumes under identity-preserved protocols. Labor-intensive controlled pollination constrains supply elasticity.
- Clearfield:Imidazolinone-tolerant varieties carry proprietary herbicide resistance traits licensed through BASF's Clearfield production system. Black Sea basin farmers facing resistant weed pressure in continuous sunflower rotations drive adoption, with seed premiums reflecting trait licensing fees and reduced herbicide application costs.
- Open-Pollinated:Genetically stabilized populations maintained through mass selection serve smallholder operations and organic certification pathways in Argentina and Eastern Europe.
- Organic:Certified organic seed production requires multi-year isolation distances and prohibited-synthetic protocols, limiting supply to dedicated organic crush facilities in Germany and France.
- Conventional:Non-traited, non-certified seed serves price-sensitive acreage in developing markets with limited herbicide resistance pressure.
Hybrid retains volume leadership; Clearfield holds the steepest expansion curve.
Crop Variety:
Margin structure separates commodity oilseed crush from premium confectionery specifications, with industrial and non-GMO niches capturing divergent value pools.
- Oilseed:Thin-hull, high-oil-content hybrids bred for solvent extraction efficiency dominate acreage in Ukraine, Russia, and Argentina. EU F-Gas Regulation nitrogen-efficiency mandates redirect breeding investment toward climate-adapted germplasm with documented greenhouse gas reduction credentials for crush facilities serving European edible oil markets.
- Confectionery:Large-seed, low-oil varieties with striped hulls meet shelling-grade specifications for snack food processors in North America and Western Europe. Premium positioning reflects limited breeder focus and direct contracting with retail-ready supply chains.
- Industrial:High-linoleic or specific fatty acid profiles serve non-food applications including bio-based lubricants and surfactants.
- Non-GMO:Identity-preserved production systems exclude genetically modified traits to access EU and Japanese food-labeling premiums.
Oilseed dominates planted area; confectionery commands the widest margin premiums.
Planting Method:
Mechanization intensity and soil conservation priorities reshape equipment-seed bundling across major producing regions.
- Direct Seeding:No-till or minimum-till drilling into residue-covered soils reduces erosion and fuel consumption. Adoption accelerates in Argentina's Pampas and Ukraine's steppe zones where drought risk favors moisture retention.
- Transplanting:Nursery-raised seedlings enable precise stand establishment in high-value confectionery production and regions with compressed growing seasons.
- Raised Bed:Elevated planting surfaces improve drainage in poorly drained Black Sea basin soils prone to waterlogging.
- Strip Cropping:Alternating sunflower with companion crops reduces wind erosion and pest pressure in semi-arid steppe environments.
Direct seeding leads adoption rates; strip cropping gains traction in erosion-prone districts.
End Use Industry:
Processor consolidation and sustainability disclosure mandates concentrate demand from integrated crush facilities and branded snack manufacturers.
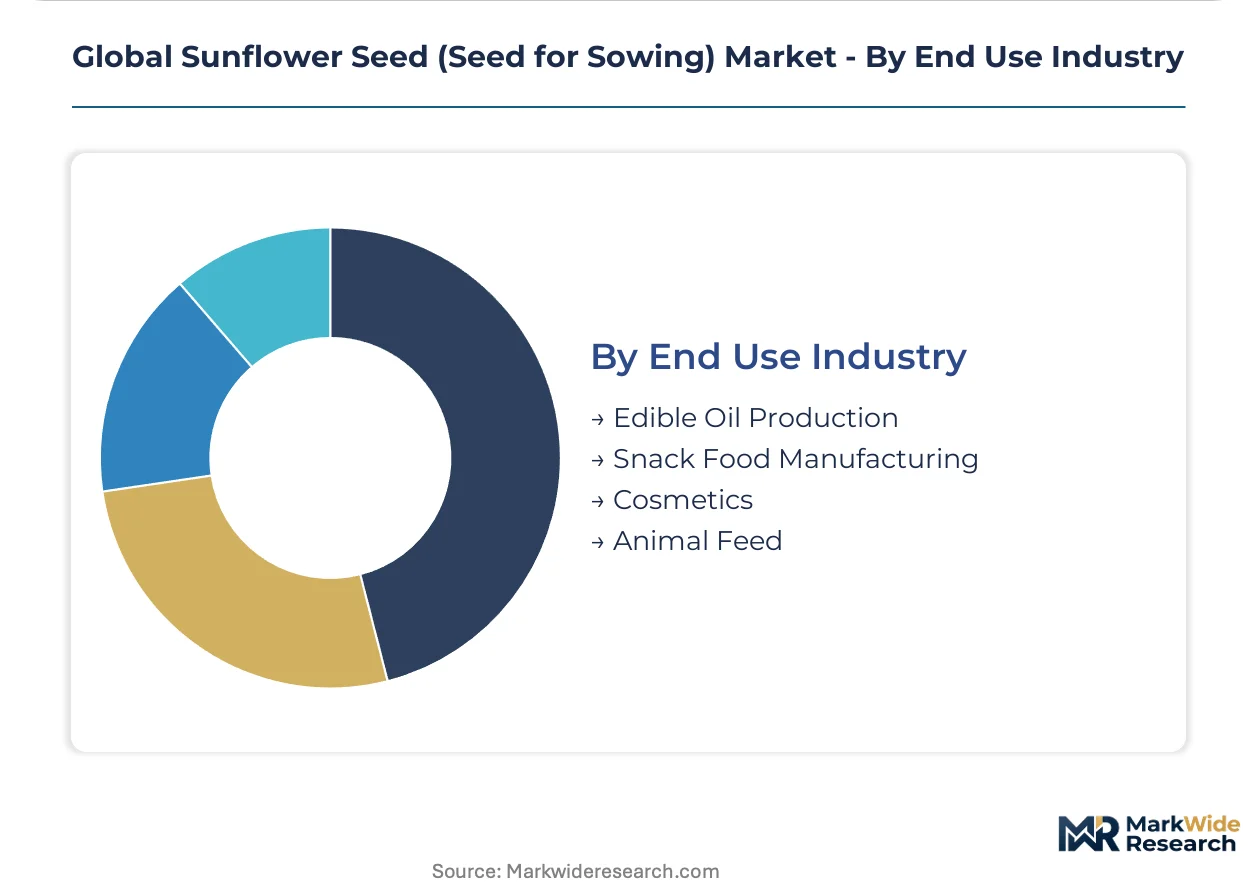
- Edible Oil Production:Refining and bottling operations in Ukraine, Russia, and Argentina contract for high-oleic and mid-oleic hybrid volumes with specified fatty acid profiles. EU Green Deal sustainability mandates require lifecycle documentation for oil destined for European retail channels.
- Snack Food Manufacturing:Shelling and roasting operations in the United States and Western Europe source confectionery-type seed through identity-preserved contracts with quality premiums for kernel size and color uniformity.
- Cosmetics:Cold-pressed oil extraction for skincare formulations demands specific tocopherol profiles and organic certification.
- Animal Feed:Meal and hull byproducts from crush operations serve ruminant and poultry ration formulation.
Edible oil production anchors volume demand; snack food manufacturing offers the most concentrated premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium seed pricing power concentrates in Western European breeding centers while crush facility demand anchors volume procurement in the Black Sea basin. Argentina's export-oriented farms negotiate contract terms that diverge sharply from Ukrainian spot market dynamics. Regulatory fragmentation across these zones reshapes cross-border germplasm flows.
Ukraine
Integrated crush facilities in Dnipropetrovsk and Odesa oblasts contract directly for high-oleic hybrid volumes under identity-preserved protocols. The State Service on Food Safety and Consumer Protection enforces national variety registration requirements that delay foreign germplasm market entry. Kherson and Zaporizhzhia clusters concentrate controlled pollination production for export-oriented seed supply.
Russia
Rostov Oblast and Krasnodar Krai farming operations expand acreage under proprietary domestic hybrids bred for regional disease pressure profiles. The Federal Service for Veterinary and Phytosanitary Surveillance maintains distinct phytosanitary certification protocols that fragment trade access with EU and North American markets. Voronezh and Belgorod regions anchor commercial multiplication of inbred lines for Black Sea basin distribution.
Argentina
Pampas region direct-seeding adoption accelerates demand for drought-tolerant hybrids with stable stand establishment under no-till residue management. The National Seed Institute enforces distinct certification timelines for imported versus domestically bred varieties. Buenos Aires and Córdoba provinces concentrate processor-led contracting that bypasses traditional distributor channels.
France
Toulouse and Montpellier breeding clusters develop nitrogen-use-efficient genetics for EU Green Deal compliance documentation. The EFSA and national variety registration authorities prioritize climate-adapted germplasm with lifecycle-assessed greenhouse gas credentials. Picardy and Champagne-Ardenne production zones supply organic-certified seed for German and Benelux crush facilities.
United States
North Dakota and Minnesota confectionery-type acreage contracts through identity-preserved channels for snack food processors demanding shelling-grade kernel specifications. USDA-APHIS phytosanitary protocols impose multi-season quarantine requirements on Black Sea basin germplasm imports that compress commercial launch windows. California's specialty oilseed sector experiments with high-oleic varieties for cosmetic-grade cold-press extraction.
Global Sunflower Seed (Seed for Sowing) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sunflower seed supply structure. Integrated seed-chemical platforms dominate trait-stacked hybrid development while specialized breeders capture premium positioning through proprietary inbred line control. The competitive field organizes around three strategic archetypes: multinational agrochemical conglomerates with bundled crop protection offerings, regional specialists with deep germplasm libraries, and confectionery-focused quality breeders. Consolidation pressure manifests through direct processor contracting displacement of distributor channels and accelerated breeding cycle investment in marker-assisted selection platforms.
Within the integrated platform tier, Bayer Crop Science AG and Corteva Agriscience exemplify multinational scale advantages through trait-stacked pipeline depth and crop protection bundling. KWS SAAT SE & Co KGaA anchors the European specialist position with captive inbred line production and regional adaptation programming. Sakata Seed Corporation occupies the premium quality tier through confectionery-type specialization for snack food channel contracting.
| Leading Market Players |
|---|
| Bayer Crop Science AG |
| Corteva Agriscience |
| Syngenta AG |
| BASF SE |
| Groupe Limagrain Holding SA |
| KWS SAAT SE & Co KGaA |
| Sakata Seed Corporation |
| Nufarm Limited |
| Land O'Lakes, Inc. |
| Others |
Supply & Pricing Matrix
Controlled pollination scale economies in Ukraine and Russia concentrate proprietary inbred line production among breeders with captive multiplication facilities, creating price floors that reflect labor-intensive isolation protocols rather than commodity grain economics. These scale advantages compress margins for smaller programs lacking vertical integration into hybrid seed production while rewarding integrated platforms with bundling leverage across crop protection portfolios.
Pricing Analysis
Configured-to-order pricing for identity-preserved high-oleic hybrids commands substantial premiums over standard non-traited seed through direct processor contracting in the Black Sea basin. Price differentiation separates Clearfield trait-licensed varieties with imidazolinone tolerance from conventional open-pollinated alternatives, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from labor cost inflation in controlled pollination operations. Smallholder operations in Argentina exhibit highest price sensitivity; integrated crush facilities in Ukraine demonstrate lowest sensitivity due to identity-preserved premium capture.
Supply Chain Analysis
Ukraine and Russia anchor commercial inbred line multiplication and hybrid seed production for Black Sea basin distribution, with Argentina's Pampas region serving as the secondary southern hemisphere supply node. Germplasm development draws from proprietary male-female line libraries, synthetic nitrogen fertilizers, and specialized pollination labor pools concentrated in Eastern European breeding centers. Single-source vulnerability concentrates in Kherson and Zaporizhzhia production clusters exposed to geopolitical disruption. Distribution runs through processor-led direct contracting that displaces traditional distributor channels in major producing regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity in controlled pollination operations and proprietary inbred line concentration among established breeding programs create defendable moats that reshape competitive entry calculus across the sunflower seed supply structure.
For Market Incumbents: Consolidate germplasm libraries through targeted acquisition of regional adaptation programs in Argentina and Eastern Europe to preempt emerging platform competition. Prioritize captive inbred line production capacity in Ukraine and Russia to defend margin position against supply disruption risks from phytosanitary blockades and labor cost inflation in hybrid seed multiplication. For New Entrants and Emerging Players: Lead with confectionery-type specialization for North American and Western European snack food processors, where shelling-grade specifications command premium positioning with limited incumbent breeder focus. Target organic certification pathways in Germany and France through multi-year isolation distance protocols that established oilseed-centric programs cannot rapidly replicate. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized breeders with deep proprietary inbred line libraries and regional adaptation capabilities over diversified agrochemical platforms facing crop protection bundling pressure. Long-term viability rests on genomic selection infrastructure deployment and nitrogen-use-efficient germplasm pipelines aligned with EU Green Deal compliance documentation. Watch accelerated processor-led procurement consolidation in the Black Sea basin as inflection signal for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Marker-Assisted Selection Platform Deployment | Genomic tools compress breeding cycles from eight years to four for disease resistance stacking. |
| Processor Direct Contracting Expansion | Bypassing distributor channels in Argentina and Russia concentrates volume commitments with crush facilities. |
| Nitrogen-Use-Efficient Germplasm Investment | EU F-Gas Regulation compliance documentation accelerates variety registration pathways for climate-adapted lines. |
| Confectionery-Type Breeding Program Launch | Premium snack food channels in North America offer higher-margin positioning with limited competition. |
| Captive Inbred Line Production Scale-Up | Proprietary male-female line control insulates supply chains from geopolitical disruption in Eastern Europe. |
Research Methodology
Desk research of proprietary breeder variety registration databases, national seed certification authority filings, and EU regulatory disclosure frameworks preceded structured interviews with hybrid seed production managers, crush facility procurement directors, and confectionery processor quality assurance leads. Secondary validation drew from customs trade data, national agricultural statistics, and phytosanitary inspection records across Ukraine, Russia, Argentina, and France. Bottom-up acreage and variety adoption estimates were triangulated against top-down crush capacity and seed production volume assessments.
Variance decomposition across seed type, crop variety, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value modeling that incorporated nitrogen-efficiency trait adoption curves, Clearfield licensing expansion rates, and processor contracting penetration by geography. Forecast inputs included EU Green Deal compliance timeline assumptions and Black Sea basin crush facility capacity expansion pipelines.
The analysis sits within stated boundaries; outcomes outside sustained EU sustainability mandate enforcement or stable Eastern European germplasm flows would require recalibration. Forecasts reflect assumptions regarding labor availability in controlled pollination and phytosanitary certification timeline stability. Recalibration cycles align with material shifts in EU F-Gas Regulation implementation intensity and Black Sea basin trade policy configuration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Psyllium Market
Seeds
Global Wheat Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Asia-Pacific Seed Market
Seeds
Global Onion Seed Market
Seeds
Nepal Seeds Market
Seeds
Vietnam Seed Market
Seeds
Seed Cracker Market
Seeds
Global Vegetable Seed Market
Seeds
South America Chia Seeds Market
Seeds
North America Forage Seed Market
Seeds
Garden Seeds Market
Seeds
Apple Seed Oil Market
Seeds
India Vegetable Seed Market