
 Apple Seed Oil Market | 2026-2036
Apple Seed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Apple Seed Oil Market Analysis
Cold-press extraction technology is tilting quality benchmarks across the apple seed oil value chain. Seatons leverages proprietary low-temperature pressing protocols to preserve linoleic acid profiles in cosmetic-grade output. The Kerfoot Group anchors European supply through integrated seed sourcing from English orchard cooperatives. Herboil Chem competes on volume scale in refined oil segments for Asian nutraceutical buyers.
Apple seed oil is a fixed oil extracted from Malus domestica seeds, containing approximately 60% linoleic acid, 30% oleic acid, and vitamin E homologues, produced through mechanical pressing or solvent extraction for emollient and oxidative-stability applications. Cold-pressed oil commands premium positioning in cosmetic formulations where tocopherol retention justifies higher input costs. Refined oil dominates food industry volumes where neutral flavor and extended shelf life are non-negotiable specifications. Organic oil segments extract margin premiums through certified supply chains, though conventional oil retains volume leadership in pharmaceutical excipient applications.
REACH in Europe mandates full substance registration and toxicity dossiers for cosmetic-grade botanical oils entering commercial distribution. FDA oversight in the United States governs GRAS self-affirmation pathways for food-grade apple seed oil, while USDA organic certification shapes premium segment access. EMA pharmacopoeial standards influence pharmaceutical adoption where seed oil fatty acid profiles must meet monograph specifications. Stakeholders must monitor evolving purity thresholds across these regulatory frameworks to preserve market access and premium positioning.
Market Dynamics
Cold-press extraction protocols are compressing quality thresholds across cosmetic-grade supply chains, forcing solvent-extraction incumbents to retool or retreat into commodity food-oil segments. REACH purity mandates in Europe are accelerating this bifurcation.
Growth Catalysts
- REACH compliance thresholds:Tightening ECHA purity requirements for cosmetic-grade botanical oils are locking out unrefined competitors and consolidating premium supply around certified cold-press producers.
- Nutraceutical formulation demand:Asian health-product manufacturers are expanding apple seed oil inclusion for oxidative-stability applications in softgel encapsulation.
- Hamburg-Berlin manufacturing corridor:Germany's natural cosmetics cluster is concentrating procurement volumes, creating captive demand for traceable organic supply chains.
Market Restraints
- Apple seed input volatility:Orchard waste streams fluctuate with annual harvest yields, compressing raw material availability for mechanical pressing operations.
- English cooperative sourcing concentration:Integrated orchard partnerships in the UK control a disproportionate share of cosmetic-grade seed stock, creating single-geography supply risk.
- Grape seed oil substitution:Established cosmetic formulators retain existing supplier relationships for linoleic-acid alternatives with equivalent emollient properties.
Strategic Opportunities
- USDA organic certification expansion:Certified supply chains command margin premiums in North American natural retail channels where label transparency drives shelf placement.
- Pharmaceutical excipient adoption:EMA pharmacopoeial monograph alignment opens formulation opportunities in European tablet-coating and lipid-based drug delivery systems.
- Direct-to-formulator digital platforms:B2B marketplace procurement is disintermediating traditional distributor networks for mid-volume cosmetic compounders seeking batch traceability.
Industry Challenges
- Linoleic acid retention expertise:Cold-press operators face acute talent scarcity in low-temperature process engineering and tocopherol preservation protocols.
- Multi-jurisdiction dossier compilation:REACH registration, FDA GRAS self-affirmation, and EMA pharmacopoeial alignment demand simultaneous compliance investment across divergent documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Seed Oil Market |
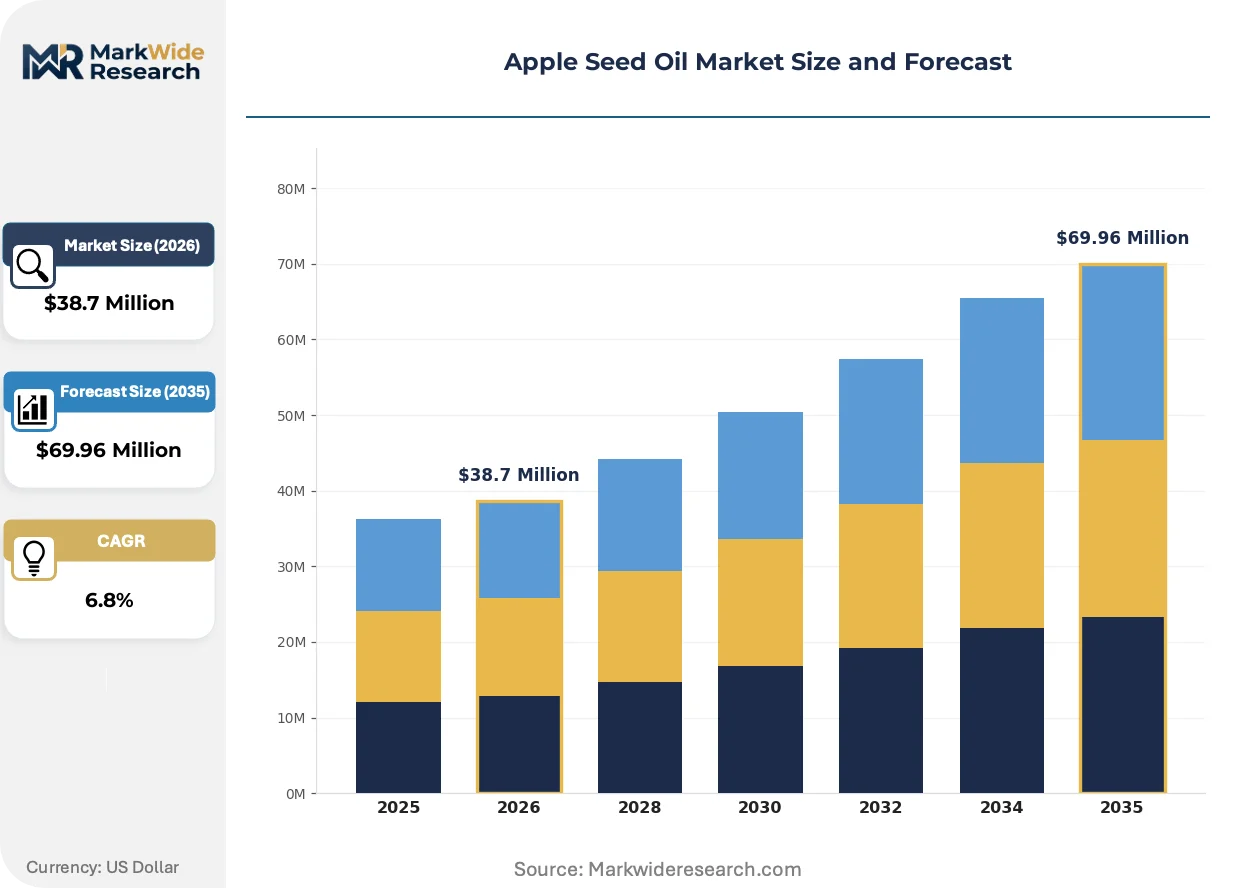
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-pressed Oil, Refined Oil, Organic Oil, Conventional Oil End Use: Cosmetics, Food Industry, Nutraceuticals, Pharmaceuticals Packaging Type: Glass Bottles, Plastic Containers, Bulk Packaging, Sachets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Retailers |
| Companies Covered | Seatons, MORRE-TEC Industries Inc., Cyrus Enterprises, Herboil Chem, The Kerfoot Group, LHASA HERBS PRIVATE LIMITED, Parchem Fine & Specialty Chemicals, Organic Pure Oil Inc, GREEN LEAF INDUSTRIES, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Seed Oil Market Emerging Trajectories
Extraction technology convergence and regulatory data requirements are redrawing competitive boundaries between artisanal cold-press specialists and scaled solvent-extraction refiners.
Supercritical CO2 extraction is collapsing the traditional trade-off between yield efficiency and heat-sensitive compound preservation. Premium cosmetic formulators in France are adopting this technology to capture phytosterol fractions previously lost to mechanical pressing. The capital intensity of CO2 systems is compressing viable participant pools to well-capitalized integrated producers.
REACH extended safety data requirements are forcing substance registration for every botanical oil variant entering European commercial distribution. Cosmetic-grade apple seed oil now requires full toxicity dossiers under ECHA oversight, elevating compliance costs that disadvantage small-batch importers. German manufacturers are responding by consolidating procurement around pre-registered domestic suppliers.
Clean-label procurement mandates are rotating buyer preference toward certified organic and cold-pressed grades across European natural cosmetics. Formulators in Hamburg are unbundling long-term distributor contracts to source directly from orchard-integrated pressers with batch-level traceability. This channel shift is most visible in premium skincare lines targeting dermatological positioning.
Apple Seed Oil Market Segmentation
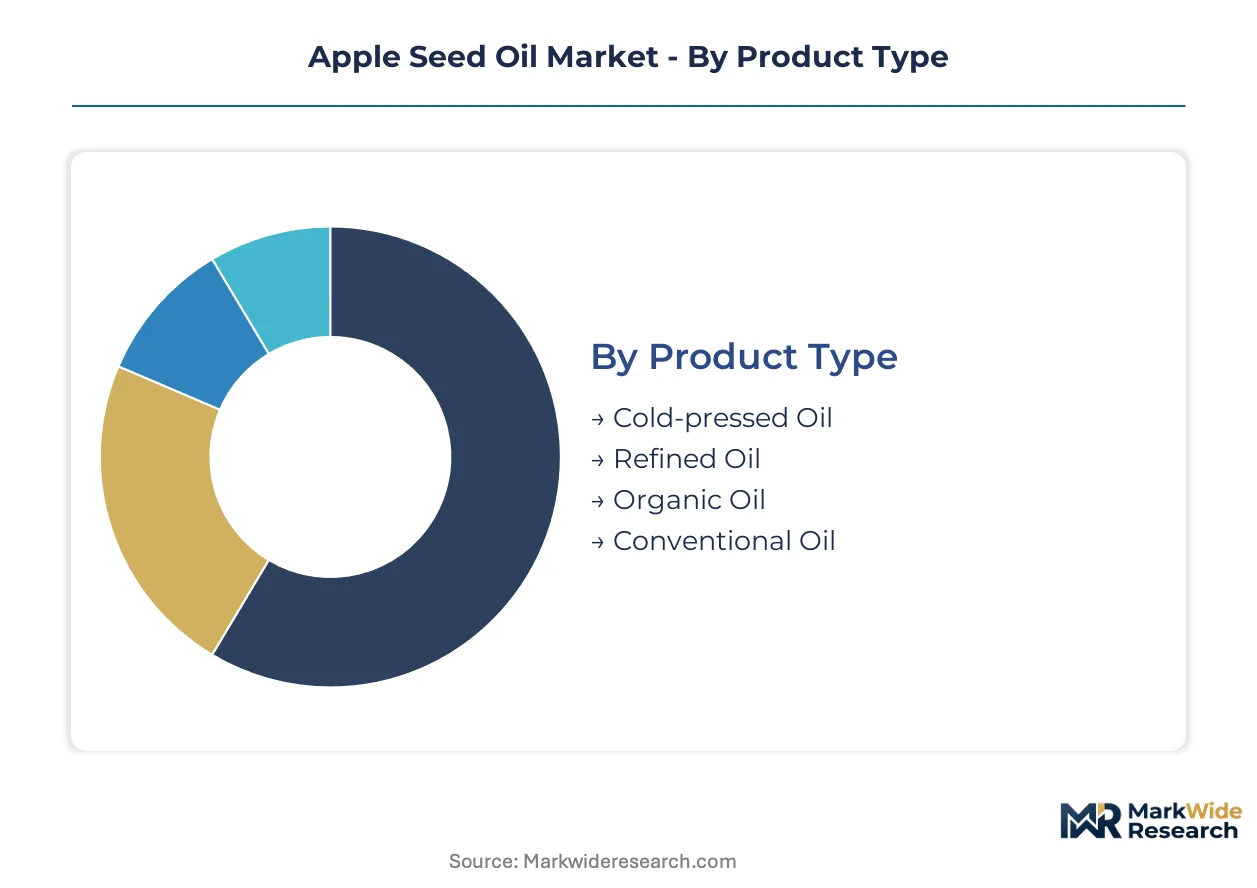
Segmentation in apple seed oil separates extraction-method purity tiers from end-use performance requirements. Formulators select grades based on tocopherol retention needs, oxidative stability thresholds, and regulatory compliance burdens across cosmetic, food, and pharmaceutical applications.
Product Type:
Use-case spectrum spans dermatological-grade emollients requiring heat-sensitive compound preservation to shelf-stable food ingredients demanding neutral flavor profiles.
- Cold-pressed Oil:Mechanical extraction below 40°C preserves approximately 60% linoleic acid and vitamin E homologues for premium cosmetic formulations. French skincare manufacturers in the Provence-Alpes-Côte d'Azur region specify this grade for anti-aging serum lines where tocopherol content justifies input cost premiums.
- Refined Oil:Solvent extraction followed by deodorization and bleaching yields extended shelf life with neutral sensory characteristics. Asian food manufacturers source this grade for cooking oil blends where oxidative stability and flavor neutrality override nutritional retention priorities.
- Organic Oil:Certified supply chains from orchard-integrated producers command margin premiums in North American natural retail channels.
- Conventional Oil:Non-certified grades retain volume leadership in pharmaceutical excipient applications where fatty acid profile compliance matters more than organic certification.
Established volume favors Refined Oil; emerging adoption favors Cold-pressed Oil.
End Use:
Application maturity varies from established cosmetic emollient deployment to nascent pharmaceutical excipient standardization.
- Cosmetics:Emollient and barrier-function applications in premium skincare drive the steepest expansion trajectory, particularly in German natural cosmetics manufacturing around Hamburg and Berlin where REACH-registered cold-pressed supply is consolidating procurement.
- Pharmaceuticals:Lipid-based drug delivery and tablet-coating applications require EMA pharmacopoeial monograph alignment for fatty acid specifications. European formulators are validating apple seed oil as a replacement for synthetic excipients in dermatological preparations.
- Food Industry:Salad dressing and culinary oil applications favor refined grades with extended fry stability.
- Nutraceuticals:Softgel encapsulation demand concentrates in Asian health-product manufacturing for oxidative-stability applications.
Cosmetics generate the highest margin per liter; Pharmaceuticals present the longest validation timelines.
Packaging Type:
Packaging selection tracks customer scale and oxidation sensitivity from artisanal glass to industrial bulk.
- Bulk Packaging:Intermediate bulk containers and drum shipments serve mid-volume cosmetic compounders and food manufacturers with captive filling operations, reducing per-unit packaging cost by eliminating retail-ready materials.
- Glass Bottles:Amber and cobalt glass protects photosensitive tocopherols in premium cosmetic and nutraceutical distribution.
- Plastic Containers:HDPE and PET formats balance cost and barrier properties for conventional-grade food oil retail.
- Sachets:Single-use foil pouches target hospitality sampling and travel-size cosmetic distribution.
Bulk Packaging dominates procurement tonnage; Glass Bottles command the highest unit economics.
Distribution Channel:
Channel structure reflects customer sophistication and batch traceability requirements across direct procurement and intermediated retail.
- Specialty Retailers:Natural product stores and apothecary channels curate certified organic and cold-pressed grades for ingredient-conscious consumers in German and French urban markets.
- Online Retail:B2B marketplace platforms are disintermediating traditional distributor networks for mid-volume cosmetic compounders seeking documented batch traceability and direct orchard-producer relationships.
- Health Food Stores:Regional chains stock organic-grade oils for culinary and wellness applications.
- Supermarkets:Mass retail carries refined food-grade oils in conventional packaging tiers.
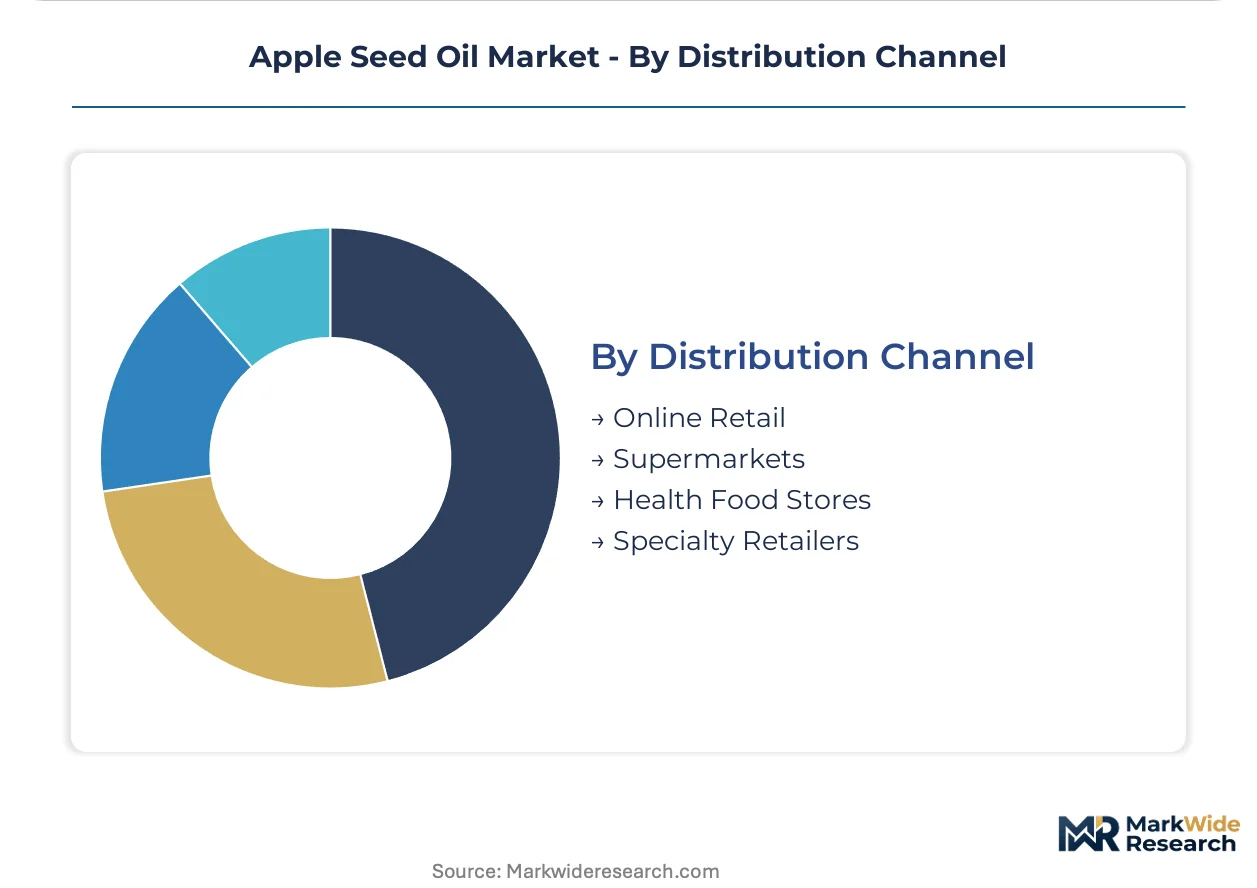
Specialty Retailers anchor premium positioning; Online Retail is gaining share fastest in B2B procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural cosmetics formulators in Germany and France anchor premium-grade procurement, while Asian nutraceutical manufacturers drive refined oil volumes. Cold-press specialists compete for REACH-registered supply access across these buyer clusters.
Germany
REACH compliance thresholds from ECHA lock out unrefined imports, consolidating procurement around certified domestic pressers. The Hamburg-Berlin manufacturing corridor concentrates natural cosmetics production, with formulators unbundling distributor contracts for direct orchard relationships. Seatons and The Kerfoot Group serve this demand through pre-registered supply chains.
France
Provence-Alpes-Côte d'Azur skincare manufacturers specify cold-pressed grades for anti-aging serum lines where tocopherol retention commands premium positioning. ANSM oversight of cosmetic safety dossiers aligns with ECHA substance registration requirements. Supercritical CO2 adoption in this cluster captures phytosterol fractions for dermatological positioning.
United States
USDA organic certification shapes premium segment access in North American natural retail channels where label transparency drives shelf placement. FDA GRAS self-affirmation governs food-grade pathways, though cosmetic applications dominate volume. Direct-to-formulator digital platforms disintermediate traditional distribution for mid-volume compounders seeking batch traceability.
United Kingdom
Integrated orchard cooperatives in England control disproportionate shares of cosmetic-grade seed stock, creating single-geography supply concentration. The Kerfoot Group anchors European supply through these partnerships. Brexit-related regulatory divergence from REACH complicates cross-border distribution for smaller pressers.
India
Asian nutraceutical manufacturers source refined grades for softgel encapsulation applications where oxidative stability overrides nutritional retention. FSSAI standards govern food-grade imports while CDSCO oversight applies to pharmaceutical excipient adoption. Herboil Chem competes on volume scale for this buyer segment.
Apple Seed Oil Market Vendor Landscape
Channel-controlling players compete with product-specialist players across extraction-method tiers. Cold-press specialists preserve linoleic acid profiles for cosmetic premiums while solvent-extraction refiners dominate food and nutraceutical volumes. Three archetypes define positioning: orchard-integrated pressers with captive raw material, technology-licensed CO2 operators, and volume-scaled refiners serving Asian manufacturing. Competitive moves concentrate on REACH registration completion and direct-formulator platform development.
Within the orchard-integrated tier, The Kerfoot Group anchors European supply through English cooperative partnerships. Seatons occupies the cold-press technology position with proprietary low-temperature protocols. Herboil Chem exemplifies the volume-scaled refiner archetype competing for Asian nutraceutical procurement.
| Leading Market Players |
|---|
| Seatons |
| MORRE-TEC Industries Inc. |
| Cyrus Enterprises |
| Herboil Chem |
| The Kerfoot Group |
| LHASA HERBS PRIVATE LIMITED |
| Parchem Fine & Specialty Chemicals |
| Organic Pure Oil Inc |
| GREEN LEAF INDUSTRIES |
| Others |
Supply Flow & Price Mechanics
Undercapacity in English orchard cooperatives is compressing raw material availability for mechanical pressing operations, forcing cold-press specialists to bid up seed stock while solvent-extraction refiners retreat toward lower-grade food oil segments. This utilization squeeze concentrates pricing power among integrated producers with captive supply relationships.
Pricing Analysis
Long-term offtake contracts with linoleic acid indexation dominate procurement between German natural cosmetics manufacturers and orchard-integrated pressers. Price differentiation rests on certification grade—REACH-registered cold-pressed oil commands substantial premiums over conventional refined grades—and volume scale, with bulk purchasers securing favorable terms. Cost compression in refined oil tiers is intensifying because grape seed oil substitution erodes commodity positioning. Small-batch cosmetic formulators exhibit lowest price sensitivity, prioritizing tocopherol retention and batch traceability over unit economics.
Supply Chain Analysis
Upstream apple seed feedstock draws from orchard waste streams concentrated in England, France, and Poland, with English cooperative partnerships controlling disproportionate shares of cosmetic-grade stock. Raw material dependencies rest on annual harvest yields, cold-press equipment availability, and phytosterol testing capacity. Single-source vulnerability runs through the Hamburg-Berlin manufacturing corridor, where REACH-registered supply consolidation creates captive buyer relationships. Distribution runs through direct-to-formulator digital platforms disintermediating traditional distributor networks for mid-volume compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apple seed oil demand is recovering from cyclical lows in orchard waste availability, with harvest yield normalization in English cooperatives driving input cost stabilization. Formulators and suppliers should position for tightened quality thresholds rather than volume expansion.
For Market Incumbents: Build regulatory moats by accelerating REACH registration completion for cold-pressed variants before ECHA extended safety data requirements take full effect. Seatons and The Kerfoot Group should deepen orchard cooperative exclusivity to lock out solvent-extraction refiners attempting cosmetic-grade repositioning. Supercritical CO2 technology licensing offers a second defensive lever against artisanal cold-press competitors.
For New Entrants and Emerging Players: Build out USDA organic certification infrastructure to access North American natural retail channels where label transparency drives shelf placement. The most penetrable white space sits in pharmaceutical excipient applications requiring EMA pharmacopoeial alignment, where validation timelines deter incumbent resource allocation. A direct-to-formulator digital platform with batch-level traceability documentation offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among orchard-integrated pressers with long-term offtake contracts to Hamburg-Berlin cosmetics manufacturers. Long-term viability over a five-to-ten-year window favors producers with backward integration into seed sourcing rather than toll-pressing operators exposed to raw material volatility. The signal to monitor is REACH registration completion rates among mid-tier competitors, which will indicate consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA compliance locks out unregistered imports, consolidating premium supply around certified domestic pressers. |
| Orchard Cooperative Exclusivity | Captive seed sourcing from English partnerships secures raw material access against harvest volatility. |
| Supercritical CO2 Technology Licensing | Phytosterol fraction capture justifies premium positioning in French dermatological formulations. |
| Direct-to-Formulator Platform Launch | Digital disintermediation serves mid-volume compounders seeking documented batch traceability. |
| USDA Organic Certification Expansion | Certified supply chains access North American natural retail channels with margin premiums. |
Methodological Framework
A standing panel of cold-press plant managers, natural cosmetics procurement leads at German formulators, distribution channel partners, and ECHA regulatory affairs specialists provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from REACH registration databases, EMA pharmacopoeial monographs, and customs trade records supported bottom-up and top-down triangulation across extraction-method tiers and end-use applications.
Scenario-bracketing around orchard yield volatility, regulatory timeline slippage, and substitution elasticity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include extraction method purity tier, end-use industry, certification grade, and regional manufacturing cluster. CAGRs were derived from volume-weighted growth rates across these segments, with specific inputs from REACH compliance cost trajectories and softgel encapsulation demand curves in Asian nutraceutical manufacturing.
Stress conditions across harvest yield compression, ECHA purity threshold escalation, and grape seed oil price erosion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cooperative partnership stability. Cross-checking against ECHA substance registration progress and orchard waste stream utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Quinoa Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
Global Sunflower Market
Seeds
Uganda Seeds Market
Seeds
Myanmar Seed Market
Seeds
India Seed Market
Seeds
Flower Seed Market
Seeds
China Forage Seed Market
Seeds
Melon Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Australia Forage Seed Market
Seeds
Perilla Seed Oil Market
Seeds
Myanmar Maize Seed Market
Seeds
E. Angustifolium Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Pumpkin Seeds Market