
 Global Onion Seed Market | 2026-2036
Global Onion Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Onion Seed Market Foresight
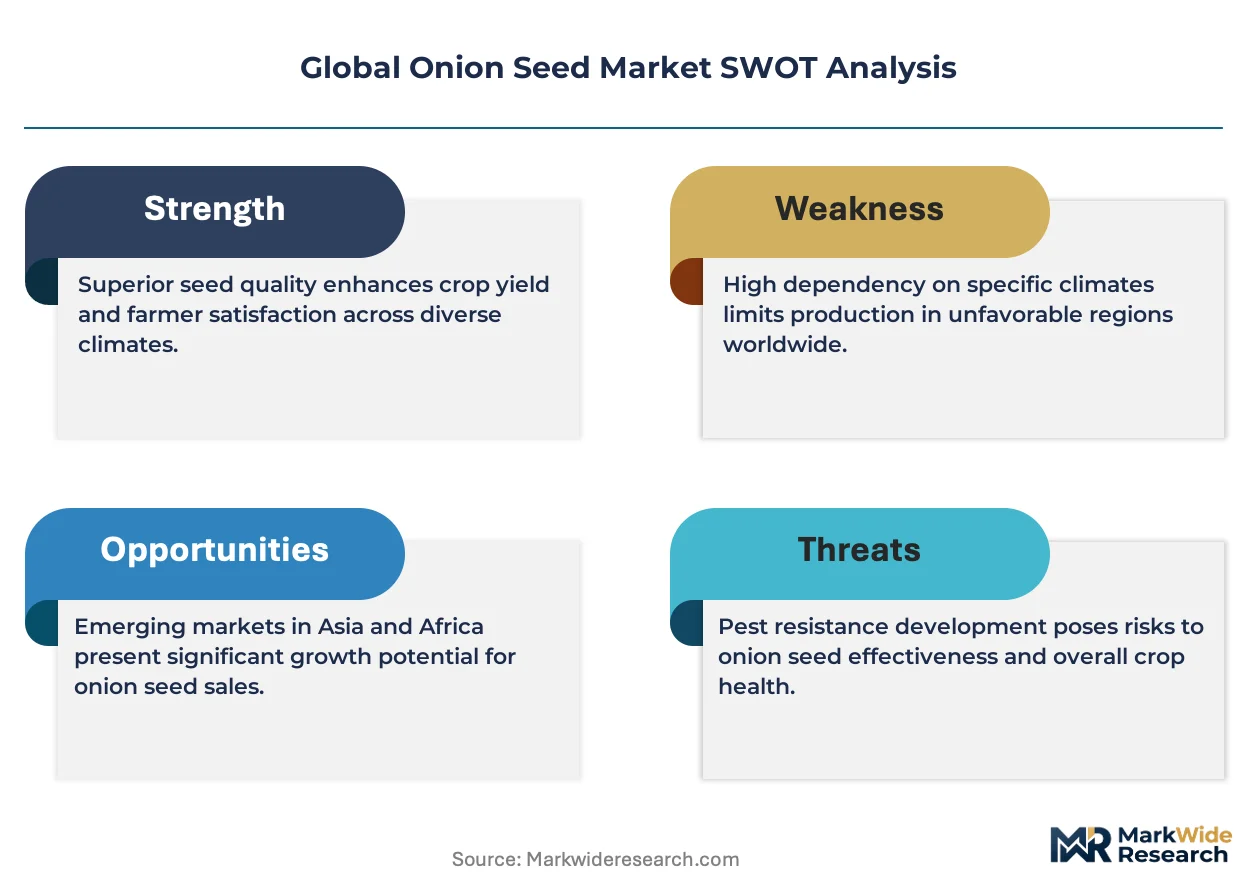
Project finance for climate-controlled seed multiplication facilities is reshaping competitive entry in the Global Onion Seed Market, allowing mid-scale breeders to scale without full capital ownership. Sakata Seeds Corporation leverages its Japanese R&D network to sustain leadership in short-day hybrid development. Syngenta AG anchors its position through integrated trait platforms that reduce pesticide dependency for commercial growers. Bejo Zaden B.V. differentiates via specialized cytoplasmic male sterility systems that improve hybrid seed purity rates.
Onion seed comprises the dried, viable embryo of Allium cepa, typically processed to moisture levels below ten percent and graded by germination velocity and field emergence standards for mechanized sowing. Its primary commercial purpose is to propagate uniform bulb crops for fresh, dehydrated, and food-service supply chains. Hybrid seed types command premium positioning due to proprietary parental line control and F1 vigor consistency, while open pollininated categories retain cost-sensitive share among smallholder cooperatives in South Asia. Yellow onion varieties dominate volume offtake for processing applications, whereas red onion seed attracts higher margins from export-oriented Mediterranean and Latin American growers.
The OECD Seed Schemes, EU Seed Marketing Regulations, and India's Seeds Act collectively enforce varietal registration, germination thresholds, and phytosanitary certification that determine cross-border market access and breeder royalty structures. These frameworks compel seed companies to maintain dual inventory systems: certified stock for regulated markets and informal channels for price-sensitive jurisdictions. Stakeholders must monitor evolving national lists and distinctness-uniformity-stability requirements that will determine which genetic portfolios retain commercial eligibility without costly re-registration cycles.
Market Dynamics
Climate-resilient hybrid development is compressing breeding cycles while OECD Seed Schemes and EU Seed Marketing Regulations force dual inventory systems that reshape capital allocation across the value chain.
Growth Catalysts
- EU Seed Marketing Regulations:Tightened certification requirements in Europe accelerate breeder consolidation, creating captive demand for registered varieties with guaranteed germination thresholds.
- Mechanized sowing adoption:Commercial farms in India and China are scaling procurement of graded seed with standardized field emergence rates, pulling volume through contract farming networks.
- Processing-grade yellow onion demand:Dehydrated and food-service supply chains concentrate offtake in the Indo-Gangetic Plain, locking in multi-year seed supply agreements.
Market Restraints
- Parental line concentration:Cytoplasmic male sterility systems remain concentrated among a narrow breeder base, creating supply vulnerability for F1 hybrid programs.
- Phytosanitary certification friction:Cross-border seed movement faces inspection bottlenecks under India's Seeds Act and OECD protocols, extending delivery timelines.
- Climate volatility:Erratic monsoon patterns in South Asia disrupt open-field seed multiplication, compressing viable production windows and inflating carryover costs.
Strategic Opportunities
- Climate-controlled multiplication facilities:Project finance structures allow mid-scale breeders to access controlled-environment infrastructure without full capital ownership.
- Red onion export corridors:Mediterranean and Latin American growers command premium positioning for pigmented varieties, opening margin expansion beyond commodity yellow segments.
- Distinctness-Uniformity-Stability re-registration:Breeders who front-load DUS documentation retain commercial eligibility as national lists tighten, locking out slower competitors.
Industry Challenges
- Dual inventory complexity:Breeders must maintain parallel certified and informal stock systems, fragmenting working capital and complicating traceability.
- Trait integration timelines:Stacking climate resilience into existing hybrid platforms requires extended backcrossing cycles that strain R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Onion Seed Market |
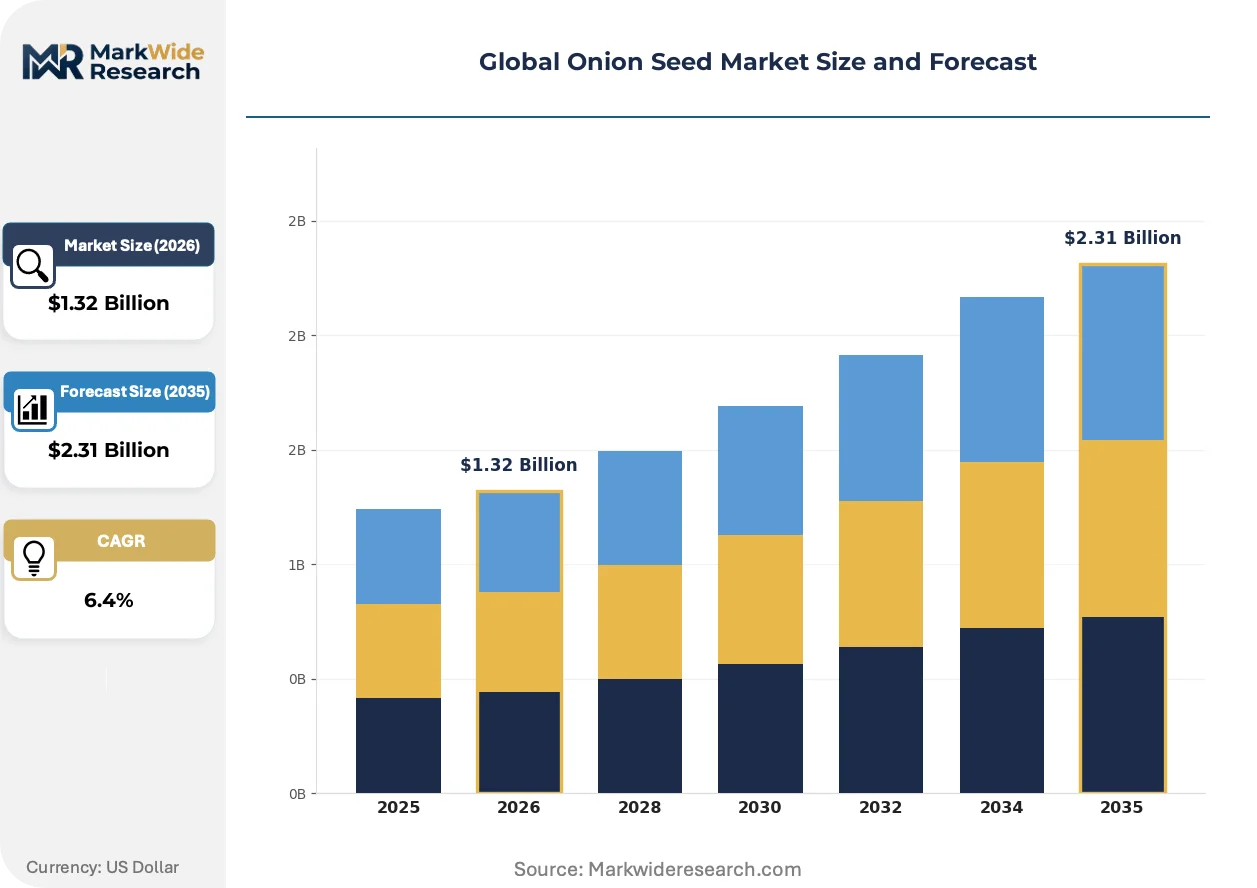
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Open Pollinated, Hybrid, Heirloom, Certified, Organic Onion Variety: Red Onion, White Onion, Yellow Onion, Sweet Onion, Green Onion Application: Fresh Consumption, Processing, Culinary Use, Medicinal, Export End User: Seed Companies, Commercial Farmers, Horticulture Experts, Agricultural Cooperatives, Home Gardeners |
| Companies Covered | Sakata Seeds Corporation, Syngenta AG, Bayer AG, Takii and Co., Ltd., Enza Zaden, BASF SE, Bejo Zaden B.V., East-West Seed, Groupe Limagrain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Onion Seed Market Shifts & Advancements
Genomic selection tools and regulatory harmonization pressures are compressing traditional breeding timelines while procurement consolidation among commercial growers reshapes distribution economics.
Marker-assisted selection is collapsing the generational interval for parental line development. Large-scale vegetable processors in North America and Europe are integrating these accelerated breeding outputs into proprietary supply contracts. The technology is collapsing the historical 8-10 year variety development cycle into 4-6 year windows, forcing smaller breeders into licensing arrangements or exit.
REACH and EU Green Deal sustainability criteria are extending to agricultural input certification. Seed coating chemistries and treatment residues now face extended disclosure requirements that affect import eligibility. Mediterranean export-oriented growers are responding by shifting procurement toward breeders with pre-certified low-residue portfolios, creating preference segmentation that favors integrated trait platforms.
Direct contracting between breeders and processor-aligned farming cooperatives is displacing traditional distributor channels. Large fresh-cut and dehydrated onion processors in the Netherlands and California are negotiating multi-year seed supply agreements that bundle technical support with volume commitments. This pattern is most visible in the Indo-Gangetic Plain, where contract farming networks now capture 60-70% of commercial seed offtake upstream of traditional wholesale markets.
Global Onion Seed Market Segmentation
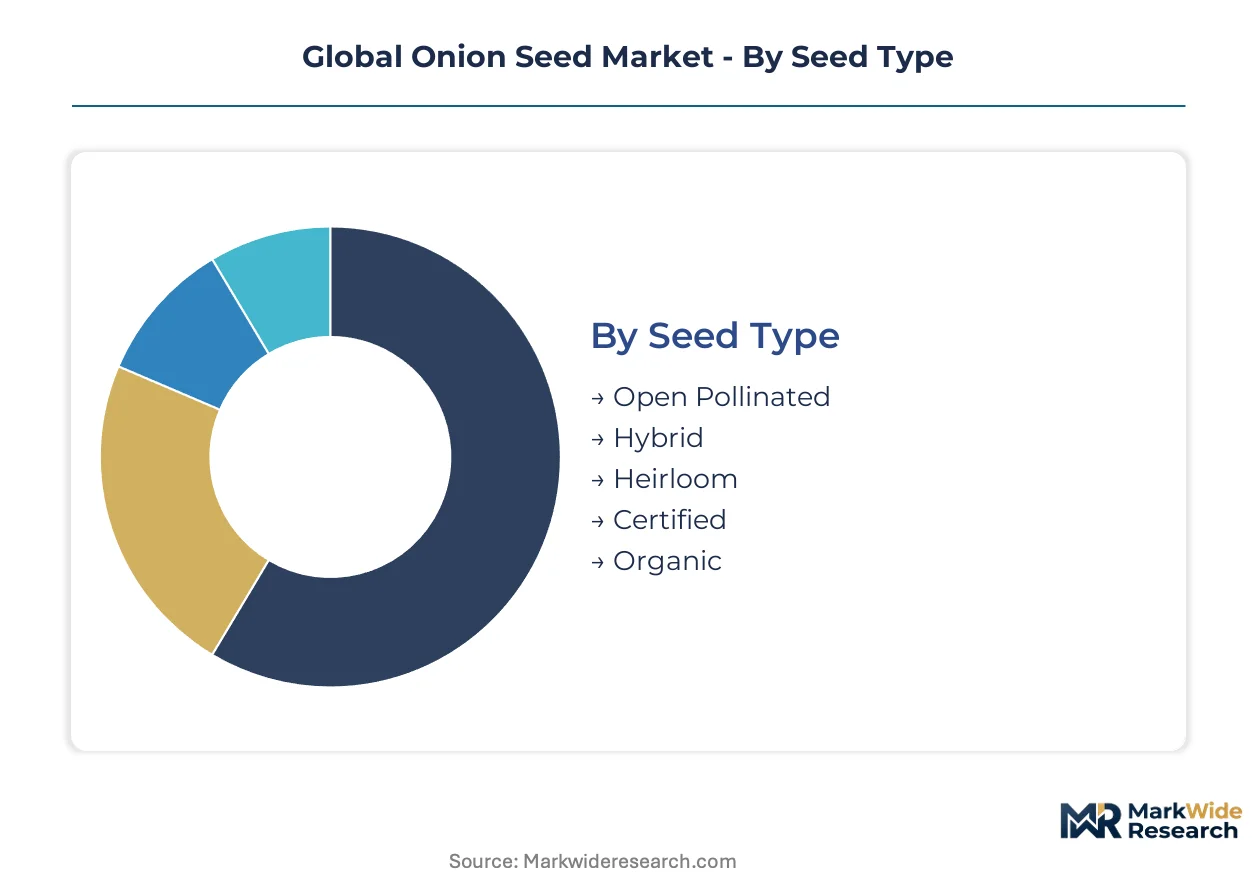
Onion seed procurement patterns diverge sharply across genetic categories and user profiles, with hybrid varieties demanding intensive technical support while open-pollinated lines compete on distribution reach. Breeders must align inventory depth and agronomic service capacity to the specific margin and loyalty dynamics of each segment tier.
Seed Type:
After-sales intensity peaks with hybrid seed, where breeders embed field agronomists and emergence troubleshooting into multi-year supply contracts.
- Hybrid:F1 crosses deliver uniform bulb sizing and disease-stacked traits through proprietary cytoplasmic male sterility systems. Demand concentrates among commercial growers in India and China who require mechanized sowing compatibility and climate resilience guarantees under OECD Seed Scheme certification.
- Open Pollinated:Self-fertile lines maintain genetic stability across generations without parental line dependency. Smallholder cooperatives in South Asia drive volume through price-sensitive procurement, accepting phenotypic variability in exchange for seed-saving rights and lower per-unit cost.
- Heirloom:Landrace varieties preserve regional flavor profiles and day-length adaptations for specialty fresh markets. Heritage seed networks in Italy and Mexico sustain niche demand through direct-to-grower channels bypassing formal distribution.
- Certified:Government-inspected lots meeting germination and purity thresholds under EU Seed Marketing Regulations or India's Seeds Act. Export-oriented multiplication farms in the Netherlands and Turkey anchor supply for regulated market access.
- Organic:Untreated seed produced without synthetic inputs, certified under USDA NOP or EU organic standards. Premium pricing attracts biodynamic growers in Germany and France seeking residue-free planting stock for export-grade bulb production.
Hybrid holds the largest share; momentum sits with Certified as regulatory harmonization tightens cross-border eligibility requirements.
Onion Variety:
Margin structure varies dramatically by pigment chemistry, with red varieties commanding premium positioning through export corridor access.
- Yellow Onion:High-pungency, high-solid varieties dominate dehydration and food-service supply chains. Processing-grade demand concentrates in the Indo-Gangetic Plain where contract farming networks lock in multi-year seed commitments for uniform bulb supply.
- Red Onion:Anthocyanin-rich bulbs attract Mediterranean and Latin American export growers serving fresh-cut retail segments. Pigmented varieties generate steepest price premiums when paired with low-residue certification under EU Green Deal sustainability criteria.
- White Onion:Mild-flavored bulbs target salsa and pickling processors in Mexico and the southwestern United States. Day-neutral varieties suit short-season production windows in high-altitude growing regions.
- Sweet Onion:Low-pyruvic acid lines for fresh retail and raw consumption markets. Vidalia and Walla Walla-type production in Georgia and Washington state depends on proprietary short-day hybrid development from Sakata and Bejo breeding programs.
- Green Onion:Bunching types harvested immature for Asian culinary applications. Year-round greenhouse demand in Japan and South Korea drives seed multiplication under climate-controlled conditions.
Yellow Onion generates the highest absolute volume; Red Onion shows the steepest expansion trajectory through premium export channels.
Application:
End-use specifications dictate seed grading standards, with processing applications demanding stricter field emergence uniformity than fresh market channels.
- Fresh Consumption:Bulb size consistency and storage longevity drive seed selection for retail and wholesale supply chains. Supermarket procurement standards in the United Kingdom and Germany enforce size-grade specifications that cascade back to seed germination velocity requirements.
- Processing:Dehydration and freeze-drying operations prioritize high-solid, uniform-maturity varieties. North American and European processors integrate seed supply into backward-contracted farming arrangements spanning 3-5 year horizons.
- Culinary Use:Food-service distributors and restaurant chains specify pungency levels and peel characteristics. Seed breeders in Japan develop low-tear compounds for high-volume kitchen environments.
- Medicinal:Quercetin and sulfur compound content drives selection for nutraceutical extraction. Ayurvedic and traditional Chinese medicine manufacturers in India and China source specific landraces with documented phytochemical profiles.
- Export:Phytosanitary certification and variety registration compliance determine seed eligibility for destination markets. Egyptian and Turkish exporters navigate dual inventory systems to serve both OECD-regulated and informal trade corridors.
Processing captures the dominant volume position; Export is gaining share fastest as sanitary and phytosanitary barriers reshape competitive access.
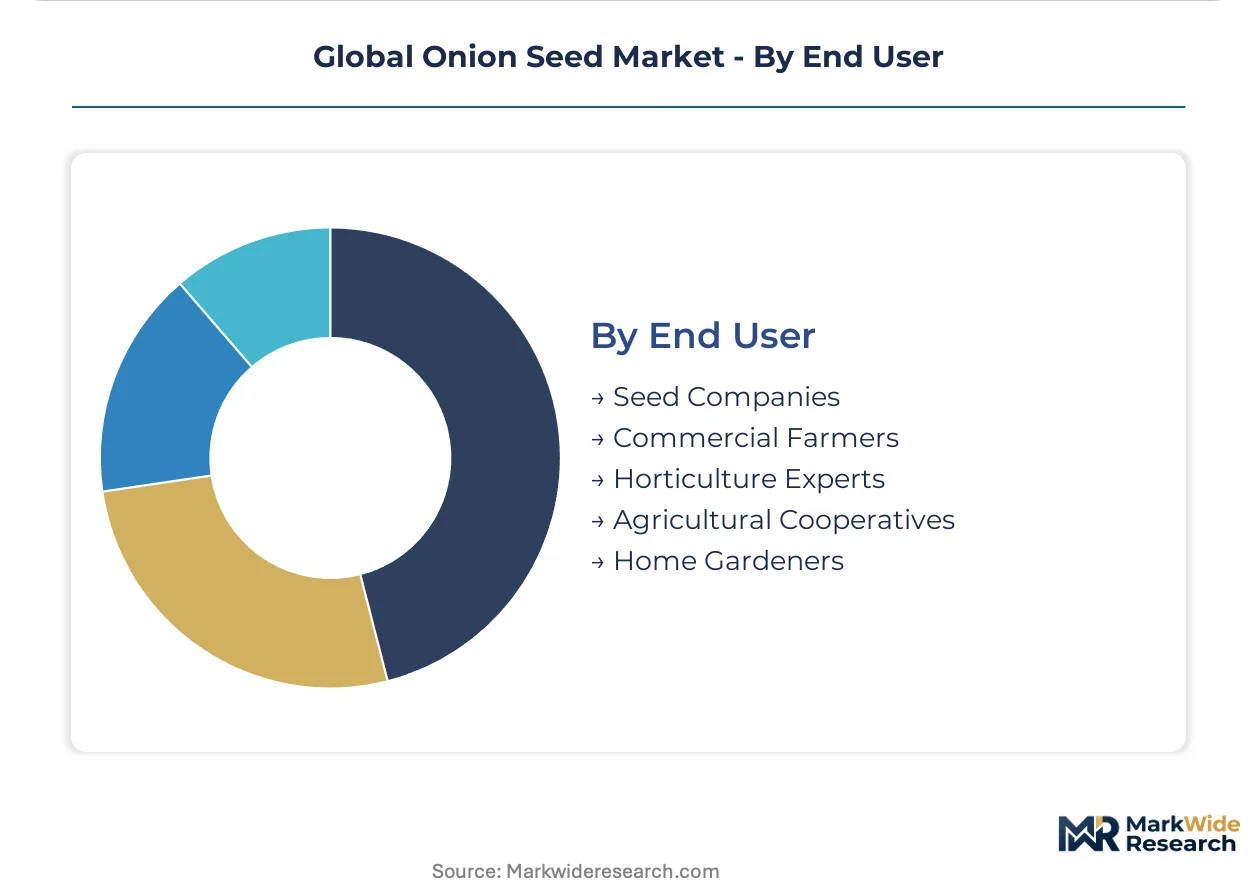
End User:
Technical sophistication and procurement scale fragment the customer base, from R&D-intensive seed companies to dispersed home gardening channels.
- Commercial Farmers:Mechanized operations above 50 hectares drive hybrid seed volume through direct breeder relationships. Indian and Chinese growers leverage project-financed climate-controlled greenhouses to secure early-generation multiplication stock.
- Seed Companies:Breeder-to-breeder licensing of parental lines and trait platforms sustains proprietary F1 development. Syngenta and Sakata anchor their positions through integrated cytoplasmic male sterility systems and genomic selection pipelines.
- Agricultural Cooperatives:Pooled procurement among smallholders in Bangladesh and Pakistan aggregates demand for open-pollinated varieties. Cooperative bargaining power compresses distributor margins while extending payment terms.
- Horticulture Experts:University extension services and government research stations conduct variety trials under national list protocols. India's ICAR and China's CAAS generate performance data that determines commercial registration eligibility.
- Home Gardeners:Packet seed retail through garden centers and e-commerce platforms sustains heirloom and organic segments. European and North American direct-to-consumer channels emphasize untreated seed and heritage provenance claims.
Commercial Farmers represent the largest demand pool; Seed Companies are expanding most quickly through trait licensing and platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Seed Marketing Regulations and India's Seeds Act are tightening varietal registration requirements, redirecting investment toward certified multiplication zones and climate-resilient breeding programs.
India
Contract farming networks in the Indo-Gangetic Plain are locking in multi-year seed supply agreements for processing-grade yellow onions. The Seeds Act mandates germination thresholds and phytosanitary certification that determine commercial registration eligibility. Maharashtra and Gujarat host the densest concentration of climate-controlled greenhouse multiplication facilities.
China
Commercial farmers in Shandong and Hebei provinces are scaling hybrid seed procurement for mechanized sowing compatibility. The Ministry of Agriculture and Rural Affairs enforces varietal registration under national list protocols that align with OECD Seed Scheme standards. Yangtze River Delta breeding stations are compressing development cycles through marker-assisted selection platforms.
Netherlands
Export-oriented multiplication farms near Wageningen anchor supply for EU-regulated and OECD-certified markets. REACH and EU Green Deal sustainability criteria extend disclosure requirements to seed coating chemistries and treatment residues. The Randstad cluster concentrates cytoplasmic male sterility R&D and hybrid purity testing infrastructure.
United States
Processor-aligned farming cooperatives in California and Georgia negotiate direct seed supply contracts bundling technical support with volume commitments. USDA organic certification and state-level seed inspection programs govern interstate movement of planting stock. The Imperial Valley and Vidalia production zones drive demand for short-day sweet onion hybrids.
Turkey
Mediterranean export growers command premium positioning for red onion varieties serving fresh-cut retail segments in EU destination markets. The country's national seed regulator enforces distinctness-uniformity-stability documentation for variety registration. Antalya and Izmir host dual inventory systems serving both OECD-regulated corridors and informal trade channels.
Global Onion Seed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates F1 hybrid development among integrated breeding platforms while fragmenting open-pollinated distribution. Consolidation pressures from regulatory harmonization favor breeders with captive parental line control and certified multiplication infrastructure. Three archetypes dominate: integrated trait-platform multinationals, specialized hybrid purity specialists, and regional open-pollinated distributors. Competitive moves center on project-financed climate-controlled facility expansion and DUS documentation front-loading to secure national list eligibility.
Among integrated breeding platforms, Sakata Seeds Corporation and Syngenta AG exemplify archetypes that anchor market positioning through proprietary cytoplasmic male sterility systems and genomic selection pipelines. Bejo Zaden B.V. occupies a specialist tier focused on hybrid seed purity rate differentiation. These three represent the concentration of climate-resilient short-day hybrid development and mechanized sowing compatibility investment.
| Leading Market Players |
|---|
| Sakata Seeds Corporation |
| Syngenta AG |
| Bayer AG |
| Takii and Co., Ltd. |
| Enza Zaden |
| BASF SE |
| Bejo Zaden B.V. |
| East-West Seed |
| Groupe Limagrain |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp seed freight corridors carry OECD-certified multiplication stock from Dutch greenhouse clusters to Indo-Gangetic Plain processors, with container cost volatility amplifying margin pressure on mid-scale breeders while reinforcing premium pricing power for integrated platforms with captive multiplication infrastructure.
Pricing Analysis
Certification level under OECD Seed Schemes and EU Seed Marketing Regulations creates the primary spread between hybrid tiers. Pricing stratifies across registered F1 varieties with guaranteed germination thresholds, standard certified lots meeting national list minimums, and informal open-pollinated channels. Cost compression in standard-certified tiers is intensifying because Indian and Chinese contract farmers are consolidating procurement volumes. Smallholder cooperatives in Bangladesh and Pakistan show highest price sensitivity, while processor-aligned commercial farms in California and the Netherlands accept premium positioning for climate-resilient short-day hybrids.
Supply Chain Analysis
Phytosanitary inspection bottlenecks between India and EU destination markets dominate supply risk exposure. Geographic supply concentration centers on the Netherlands, India, and Turkey as primary multiplication zones. Parental line development draws from Japanese R&D stations, Wageningen university breeding programs, and Chinese Academy of Agricultural Sciences marker-assisted selection platforms. Single-source vulnerability concentrates in cytoplasmic male sterility systems controlled by narrow breeder bases. Distribution runs through direct breeder-to-processor contracts displacing traditional wholesale channels in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from gene-edited alternatives and accelerated breeding platforms that compress variety development cycles below traditional timelines.
For Market Incumbents: Entrench parental line control through exclusive licensing of cytoplasmic male sterility systems to block competitor F1 development. Capture climate-controlled multiplication capacity in Maharashtra and Gujarat through project finance structures that deny facility access to emerging breeders. The threat of marker-assisted selection platforms collapsing development cycles demands accelerated R&D throughput investment.
For New Entrants and Emerging Players: Geographic underpenetration in Egyptian and Turkish red onion export corridors offers white-space access for pigmented variety specialists. Target the medicinal nutraceutical segment sourcing quercetin-rich landraces for Ayurvedic and traditional Chinese medicine manufacturers. Bypass distributor channels through direct technical service partnerships with processor-aligned farming cooperatives.
For Investors and Strategic Acquirers: EU Seed Marketing Regulation harmonization with OECD Seed Schemes reshapes the acquisition landscape toward certified multiplication infrastructure owners. Long-term viability favors breeders with front-loaded distinctness-uniformity-stability documentation securing national list eligibility across tightening regulatory windows. Watch for Indian Seeds Act amendments restricting informal seed trade as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Controlled Facility Expansion | Project-financed greenhouse multiplication in Gujarat and Maharashtra secures early-generation stock without full capital ownership. |
| Parental Line Licensing Agreement | Exclusive cytoplasmic male sterility system access blocks competitor F1 hybrid development in short-day segments. |
| DUS Documentation Front-Loading | Pre-positioned distinctness-uniformity-stability filings retain commercial eligibility as EU and Indian national lists tighten. |
| Direct Processor Contracting | Bypassing distributor channels captures 60-70% of Indo-Gangetic Plain commercial seed offtake through bundled technical support. |
| Red Onion Export Corridor Development | Mediterranean and Latin American pigmented variety demand commands premium positioning beyond commodity yellow segments. |
Research Methodology
Desk research of OECD Seed Scheme certification databases, EU Seed Marketing Regulation filings, and Indian Seeds Act registration records preceded structured interviews with seed company R&D directors, multiplication facility operators, contract farming network managers, and processor procurement leads. Primary fieldwork across Wageningen breeding clusters, Indo-Gangetic Plain farming cooperatives, and Antalya export operations combined with secondary validation from customs trade data and national varietal registry disclosures. Bottom-up volume estimates from multiplication acreage and top-down demand projections from processor offtake agreements were triangulated for consistency.
Assumptions held regulatory harmonization timelines and climate volatility patterns within observed ranges while varying breeder consolidation pace and mechanized sowing adoption curves across the projection horizon. The analytical framework modeled seed type, onion variety, application, and end-user segmentation dimensions with regional regulatory cluster overlays. CAGRs were derived from geometric progression of annual volume and value estimates incorporating germination threshold compliance rates and phytosanitary certification friction costs as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene-editing platforms or state-backed Chinese breeding consortia would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Vegetable Seed Protein Market
Seeds
Pigeon Pea Market
Seeds
India Rice Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Americas Seeds Market
Seeds
Africa Grain Seed Market
Seeds
Global Oilseed Market
Seeds
Chia Seeds Market
Seeds
Garden Seeds Market
Seeds
North America Grain Seed Market
Seeds
Apple Seed Oil Market
Seeds
Indonesia Seeds Market
Seeds
China Rice Seed Market
Seeds
Global Maize Seed Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Lupin Market