
 Asia-Pacific Seed Market | 2026-2036
Asia-Pacific Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Seed Market Outlook
Market Context with Strategic Players
Plant breeder shortages across Southeast Asia is reorganizing competitive dynamics as companies scramble for germplasm expertise. Yuan Longping High-Tech Agriculture Co. Ltd anchors China's hybrid rice sector through its captive research stations in Hunan and Hainan. Syngenta Group leverages its global trait pipeline to dominate vegetable seed distribution across Thailand and Vietnam. East-West Seed specializes in tropical vegetable genetics, sustaining deep farmer relationships through its decentralized breeding programs in Indonesia and the Philippines.
Technical Definition and Structural Segments
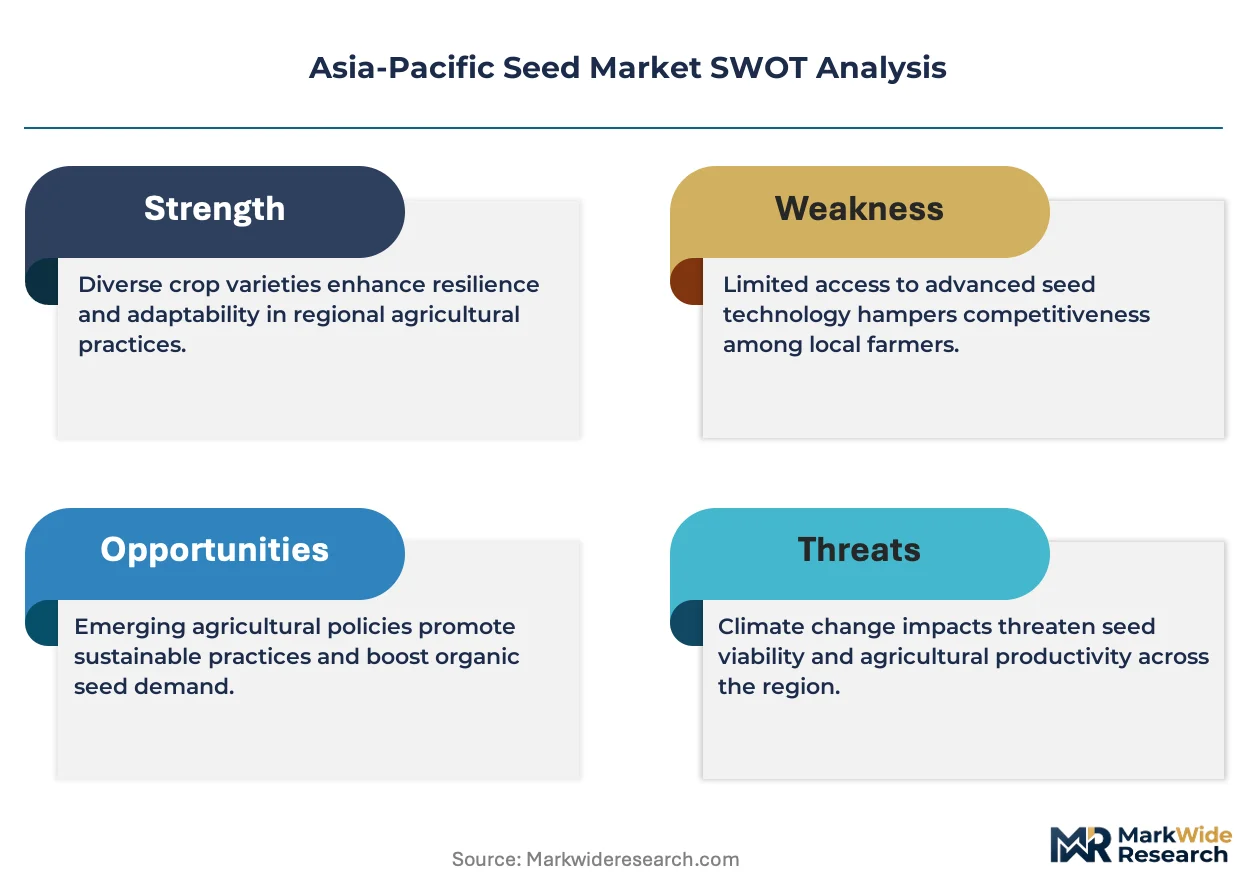
Asia-Pacific seed encompasses genetically stable propagules—certified for germination rate, genetic purity, and seed health—used to initiate commercial crop cycles across cereals, vegetables, oilseeds, and forage species. These propagules undergo controlled multiplication through breeder, foundation, and certified seed stages to maintain varietal integrity and yield potential. Hybrid technology leads value generation across the region, with GMO traits restricted to specific cotton and soybean applications while organic seed gains traction among export-oriented horticulture clusters. Conventional open-pollinated varieties still dominate volume in South Asian cereal systems where farmer-saved seed practices persist.
Regulatory Framework and Forward Outlook
China's NMPA and Ministry of Agriculture enforce seed registration and variety approval systems that control market entry for genetically modified and hybrid products. India's BIS and CEA align seed standards with international germplasm protocols, while Australia's TGA oversees phytosanitary compliance for imported breeding material. Stakeholders must monitor how China's revised seed law and India's PLI scheme for agriculture reshape local breeding capacity versus import dependency across the region.
Market Dynamics
China's revised seed law and India's PLI scheme for agriculture are accelerating domestic breeding capacity while tightening quality benchmarks, forcing multinational germplasm providers to localize R&D or cede share to state-backed competitors.
Growth Catalysts
- India's PLI scheme for agriculture:Production-linked incentives are accelerating domestic breeding infrastructure and reducing import dependency for hybrid rice and vegetable germplasm.
- Urban food procurement shifts:Southeast Asian cities are contracting directly with commercial vegetable farms, creating certified seed demand that bypasses traditional farmer-saved propagation.
- Hybrid rice technology:Two-line and three-line hybrid systems are expanding planted area as seed companies establish captive research stations in tropical breeding zones.
Market Restraints
- Phosphorus and nitrogen input volatility:Fertilizer cost swings compress margins for seed multiplication contractors in India's Indo-Gangetic Plain.
- Germplasm supply concentration:Tropical vegetable genetics relies on narrow founder populations from Dutch and Japanese public breeding programs.
- GMO trait regulatory friction:China's NMPA maintains lengthy variety approval timelines for genetically modified cotton and soybean candidates.
Strategic Opportunities
- Philippines vegetable export clusters:Organic certification requirements for EU-bound asparagus and mango are creating premium-priced open-pollinated variety demand.
- Gene editing convergence with MAS:CRISPR-Cas9 stacked with marker-assisted selection is shortening breeding cycles for drought-tolerant rice.
- Direct-to-farmer digital channels:Agtech platforms in Vietnam and Indonesia are disintermediating traditional distributor networks for hybrid vegetable seed.
Industry Challenges
- Plant breeder scarcity:Southeast Asia lacks trained germplasm specialists, forcing companies to recruit from Latin American programs or fund university chairs.
- Seed health certification timelines:Australia's TGA phytosanitary protocols create six-month delays for imported breeding material.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Seed Market |
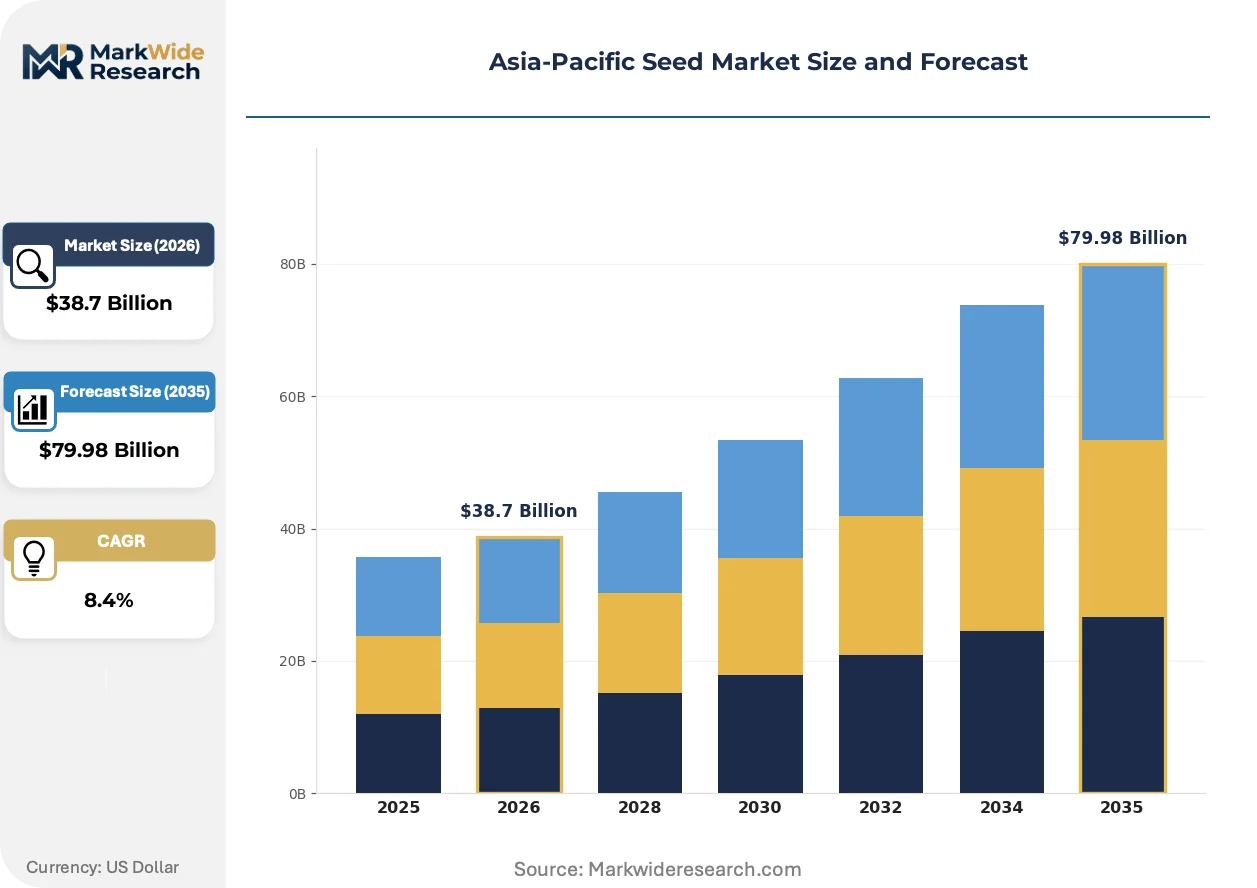
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Oilseeds, Vegetables, Flowers Technology: Hybrid, GMOs, Organic, Conventional End Use: Agronomy, Horticulture, Turf, Biofuels Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Yuan Longping High-Tech Agriculture Co. Ltd, Rijk Zwaan Zaadteelt en Zaadhandel BV, Syngenta Group, Advanta Seeds - UPL, East-West Seed, Bayer AG, Groupe Limagrain, BASF SE, Corteva Agriscience, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Seed Market Strategic Shifts
Gene editing tools and digital breeding platforms are compressing varietal development timelines while regulatory frameworks scramble to classify novel products. These shifts are redrawing competitive boundaries between state research institutes and private multinationals.
CRISPR-mediated trait stacking in rice and wheat is bifurcating the variety approval pathway. China's state breeding institutes are adopting the technology fastest, while private multinationals await clearer NMPA guidance on edited-versus-transgenic classification. The regulatory uncertainty is bifurcating investment flows between state and private R&D pipelines.
India's BIS is aligning seed certification standards with OECD-FAO international protocols, forcing domestic laboratories to upgrade testing infrastructure. The harmonization accelerates export clearance for Indian-bred varieties but raises compliance costs for small regional seed companies. Vegetable seed exporters to Bangladesh and Nepal are consolidating testing contracts with accredited Bangalore and Hyderabad facilities.
Contract farming arrangements are displacing spot-market seed purchases across Southeast Asian vegetable clusters. Thai and Vietnamese supermarket chains now specify certified hybrid varieties in procurement contracts with grower cooperatives. This specification shift concentrates demand with breeders who can guarantee supply continuity and traceability documentation.
Asia-Pacific Seed Market Segmentation
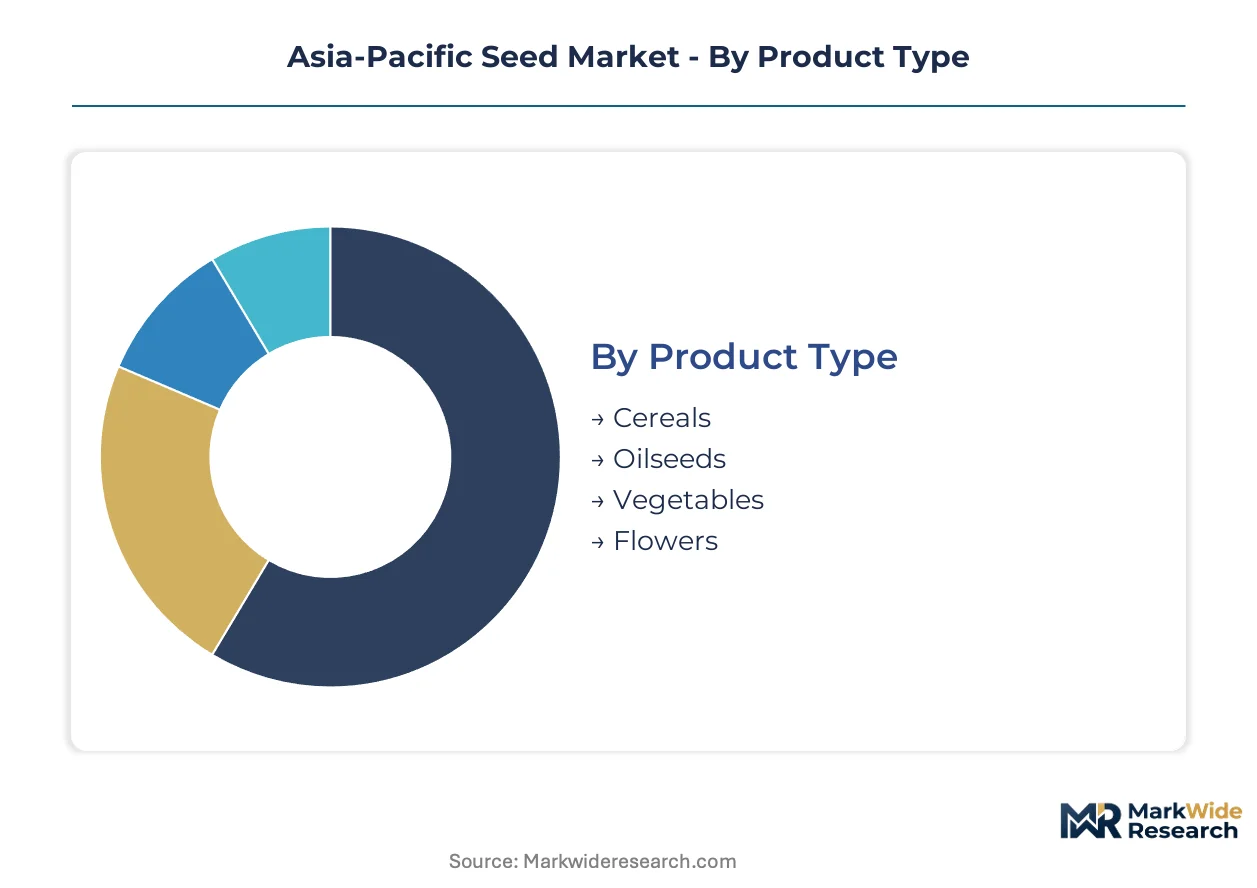
Asia-Pacific seed demand fragments across four structural dimensions that determine pricing power, regulatory exposure, and channel economics. Product type and technology choices anchor farmer purchasing decisions, while end-use applications and distribution channels reshape competitive access.
Product Type:
Cereals and vegetables face divergent substitution pressures—farmer-saved seed persists in grain systems while hybrid vegetable genetics command premium pricing due to trait complexity.
- Cereals:Rice and wheat seed dominates volume across India's Indo-Gangetic Plain and China's Yangtze River basin. State breeding institutes in Haryana and Hunan propagate foundation seed through certified multiplication networks, though farmer-saved varieties still capture substantial planted area in Bangladesh and Nepal.
- Vegetables:Tropical hybrid tomatoes, peppers, and cucurbits concentrate value in Thailand's contract farming clusters and Vietnam's Mekong Delta export zones. East-West Seed and Syngenta Group compete through decentralized breeding programs that deliver regionally adapted germplasm with shorter breeding cycles.
- Oilseeds:Soybean and rapeseed seed demand tracks crushing capacity expansion in China's Jiangsu province and India's Madhya Pradesh.
- Flowers:Ornamental seed imports from Dutch breeders supply China's Yunnan greenhouse complexes and Japan's cut flower cooperatives.
Cereals retains volume leadership; vegetables holds the steepest expansion curve.
Technology:
Cost tier stratification separates technology segments—hybrid platforms require captive R&D infrastructure while conventional systems compete on distribution density.
- Hybrid:Two-line and three-line rice systems anchor proprietary value capture through cytoplasmic male sterility mechanisms. Yuan Longping High-Tech Agriculture Co. Ltd maintains captive research stations in Hainan's tropical breeding zone to accelerate parental line development.
- Conventional:Open-pollinated varieties persist in South Asian cereal systems where seed replacement rates remain below hybrid penetration thresholds. India's BIS certification standards for conventional wheat seed create compliance barriers that favor organized seed companies over informal suppliers.
- GMOs:Insect-resistant cotton and herbicide-tolerant soybeans operate under China's NMPA variety approval system with extended field trial timelines.
- Organic:Non-synthetic seed treatments and heirloom genetics command premium positioning in Philippines asparagus export clusters supplying EU organic certification requirements.
Conventional technology dominates planted hectares; hybrid platforms generate disproportionate revenue concentration.
End Use:
Application-driven demand concentration reshapes segment boundaries—horticulture seed pulls premium pricing while agronomy seed competes on government procurement scale.
- Agronomy:Field crop seed flows through India's state agriculture departments and China's provincial seed stations. India's PLI scheme for agriculture redirects procurement toward domestic breeding capacity, compressing margins for imported germplasm.
- Horticulture:Vegetable seed demand concentrates in Southeast Asian supermarket supply chains that specify certified hybrid varieties in grower contracts. Thai retail chains now mandate traceability documentation that favors breeders with integrated seed processing facilities.
- Turf:Golf course and sports field seed imports from US and Australian breeders serve China's urban greening programs.
- Biofuels:Sorghum and sweet sorghum seed for ethanol feedstock expands in India's Maharashtra and Karnataka state programs.
Agronomy absorbs the largest seed volume; horticulture commands the highest per-kilogram pricing premiums.
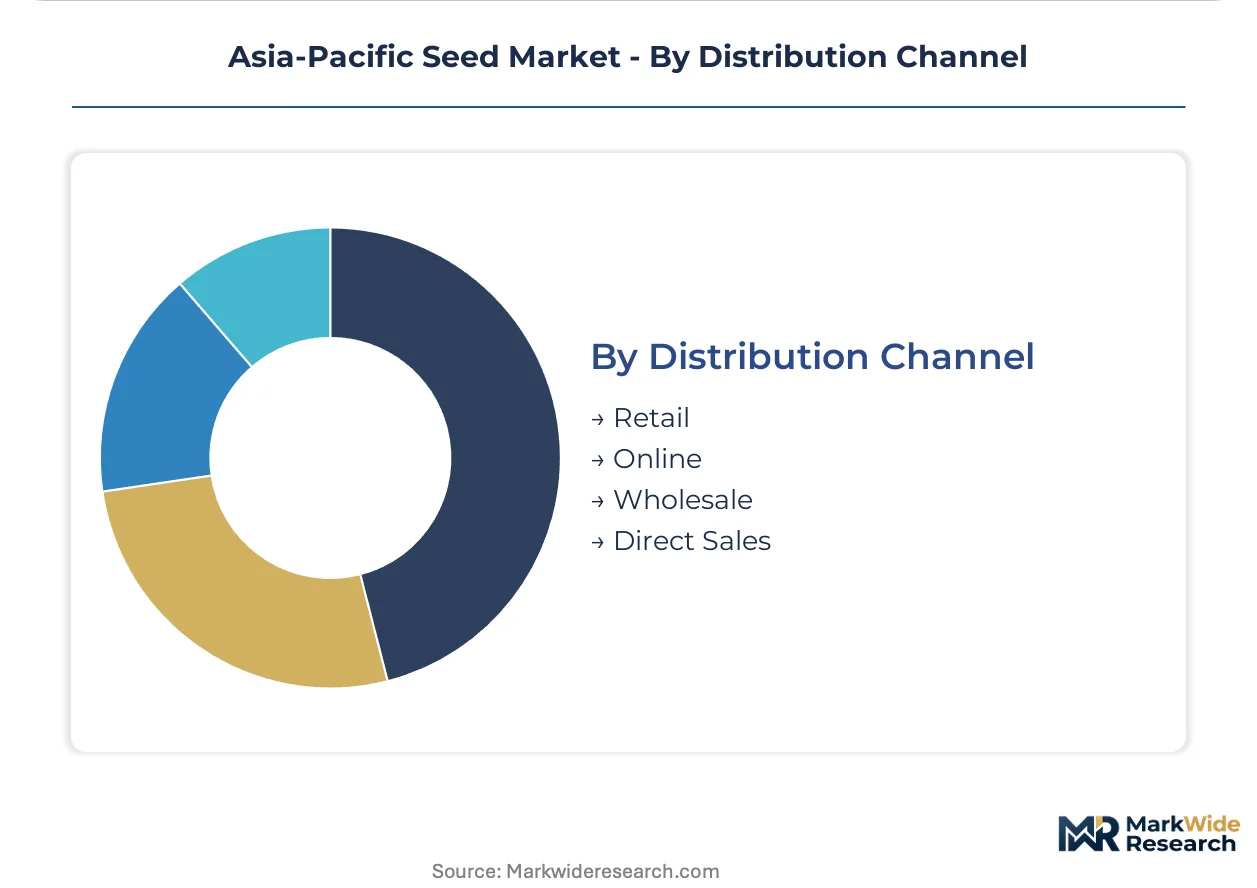
Distribution Channel:
Customer type fragmentation separates channel economics—wholesale networks retain scale in grain seed while digital platforms disintermediate vegetable genetics.
- Wholesale:Aggregator networks in India's Uttar Pradesh and China's Shandong province consolidate smallholder demand into volume contracts with foundation seed producers. These channels capture economies of scale in rice and wheat seed distribution.
- Direct Sales:Breeder-to-farmer relationships dominate hybrid vegetable seed in Indonesia's Java highlands and Philippines' Benguet vegetable clusters. East-West Seed's field technician networks provide agronomic support that locks in varietal loyalty across planting seasons.
- Retail:Branded seed counters in Vietnam's Mekong Delta and Bangladesh's Rajshahi division serve smallholder vegetable producers with pre-packaged hybrid varieties.
- Online:Agtech platforms in Vietnam and Indonesia disintermediate traditional distributor tiers for hybrid vegetable seed, though germplasm authenticity verification remains a adoption constraint.
Wholesale channels retain volume concentration; direct sales platforms are climbing fastest in value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA and Ministry of Agriculture anchor the Asia-Pacific seed regulatory landscape through variety approval systems that govern market entry for hybrid and genetically modified products. The region spans diverse agro-ecological zones from temperate cereal belts to tropical vegetable clusters.
China
Hybrid rice seed demand concentrates in Hunan and Hainan provinces where captive research stations accelerate parental line development. The revised seed law tightens quality benchmarks while accelerating domestic breeding capacity. State breeding institutes in the Yangtze River basin dominate foundation seed multiplication networks.
India
Wheat and rice seed replacement rates are climbing fastest across the Indo-Gangetic Plain as commercial farming expands. The PLI scheme for agriculture redirects procurement toward domestic breeding capacity through production-linked incentives. Seed multiplication contractors in Haryana and Uttar Pradesh face margin compression from fertilizer cost volatility.
Thailand
Supermarket chains now specify certified hybrid vegetable varieties in procurement contracts with grower cooperatives. The country's tropical vegetable genetics demand pulls germplasm from decentralized breeding programs. Contract farming clusters around Bangkok and Chiang Mai concentrate demand for traceable seed supply.
Vietnam
Agtech platforms are disintermediating traditional distributor tiers for hybrid vegetable seed in the Mekong Delta export zones. Urban food procurement shifts are contracting directly with commercial vegetable farms. Retail seed counters serve smallholder producers with pre-packaged hybrid varieties.
Australia
Phytosanitary compliance protocols from the TGA create six-month delays for imported breeding material. The country's seed health certification timelines shape regional germplasm flows. Ornamental seed imports supply greenhouse complexes while cereal breeding focuses on drought-tolerant varieties.
Asia-Pacific Seed Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific seed market. State-backed breeding institutes control foundational germplasm for cereals while multinational trait providers dominate vegetable genetics through proprietary hybrid platforms. The competitive terrain separates into three archetypes: captive R&D conglomerates, decentralized tropical specialists, and state research monopolies. Dominant competitive moves include localization of R&D infrastructure and strategic partnerships with regional multiplication networks.
Among state-linked hybrid rice specialists, Yuan Longping High-Tech Agriculture Co. Ltd exemplifies the captive research station model. Tropical vegetable genetics are represented by East-West Seed, which occupies a position within the decentralized breeding archetype. Syngenta Group anchors the multinational trait pipeline tier through vegetable seed distribution networks.
| Leading Market Players |
|---|
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Syngenta Group |
| Advanta Seeds - UPL |
| East-West Seed |
| Bayer AG |
| Groupe Limagrain |
| BASF SE |
| Corteva Agriscience |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Thai supermarket chains and vegetable seed suppliers lock in germplasm access while freezing price visibility across hybrid tomato and pepper varieties. These arrangements concentrate procurement power with breeders who maintain captive research stations in Hainan and decentralized multiplication networks in Indonesia.
Pricing Analysis
Price spreads between premium hybrid vegetable seed in Vietnam's Mekong Delta and conventional open-pollinated wheat seed in India's Uttar Pradesh exceed fivefold on a per-kilogram basis. Three-tier pricing structure across premium, standard, and economy levels separates certified hybrid varieties with full traceability documentation from farmer-saved seed with no quality assurance. Pricing pressure stems from fertilizer cost volatility compressing margins for seed multiplication contractors in the Indo-Gangetic Plain. Smallholder vegetable producers in Bangladesh exhibit highest price sensitivity, while export-oriented contract farms in Thailand accept premium positioning for guaranteed supply continuity.
Supply Chain Analysis
China and India anchor foundation seed multiplication for rice and wheat genetics across the Asia-Pacific region. Parental line development draws from germplasm collections in Hainan's tropical breeding zones and Hunan's research stations. Supply chain risk centers on single-source vulnerability for tropical vegetable genetics originating from Dutch and Japanese public breeding programs. Distribution runs through state agriculture departments for cereal seed and direct-to-farmer field technician networks for hybrid vegetable varieties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where agtech digital channels in Vietnam and Indonesia are disintermediating traditional distributor tiers, creating interoperability between seed authentication systems and farm management software.
For Market Incumbents: Shield proprietary hybrid platforms by deepening backward integration into parental line development in tropical breeding zones. Establish capacity reservation agreements with fertilizer suppliers to buffer multiplication cost volatility. Lock in channel control through field technician networks that deliver agronomic support beyond germplasm transactions. For New Entrants and Emerging Players: Lead with organic certification-compliant open-pollinated varieties targeting Philippines asparagus export clusters supplying EU markets. Target underpenetrated vegetable seed segments in Nepal and Bangladesh where state procurement systems remain weak. Deploy direct-to-farmer digital channels with embedded germplasm authenticity verification to bypass established distributor tiers. For Investors and Strategic Acquirers: Capital is best deployed toward decentralized tropical breeding specialists with captive farmer relationship networks and regionally adapted germplasm libraries. Long-term viability hinges on regulatory navigation capacity across China's NMPA and India's BIS certification pathways. Watch for inflection signals in gene-edited variety approval timelines that would bifurcate state versus private R&D investment flows.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Research Station Expansion | Yuan Longping's Hainan facilities accelerate parental line development cycles for hybrid rice. |
| Digital Platform Integration | Vietnamese agtech channels disintermediate traditional seed distributor tiers for vegetable genetics. |
| Backward Integration into Multiplication | East-West Seed's decentralized breeding programs in Indonesia secure supply continuity for tropical vegetables. |
| Certification Infrastructure Investment | Bangalore and Hyderabad laboratories align with OECD-FAO protocols for Indian-bred variety exports. |
| Strategic Partnership with State Institutes | Syngenta's trait pipeline collaborations navigate China's NMPA variety approval requirements. |
Study Parameters
A spread of perspectives from seed company R&D directors, state breeding institute scientists, multiplication contract farmers, and supermarket procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with germplasm specialists and regulatory affairs leads at China's Ministry of Agriculture and India's BIS with secondary validation against OECD-FAO seed certification databases, customs trade records for ornamental seed imports, and provincial seed station production statistics. Bottom-up variety-level demand estimates triangulated against top-down sectoral expenditure flows.
Segmentation dimensions modeled include product type, technology platform, end-use application, and distribution channel across the analysis window. CAGRs were derived from trend extrapolation of seed replacement rate trajectories and hybrid penetration curves, cross-referenced with government procurement scale projections under India's PLI scheme and China's revised seed law implementation. Industry-specific forecast inputs incorporated fertilizer cost volatility indices and phytosanitary certification timeline data from Australia's TGA.
The analysis sits within stated boundaries; outcomes outside sustained regulatory support for domestic breeding capacity or abrupt shifts in GMO trait approval timelines would require recalibration. Forecasts reflect documented assumptions about hybrid rice technology adoption rates and contract farming expansion across Southeast Asian vegetable clusters. Recalibration cycles align with material shifts in China's NMPA guidance on edited-versus-transgenic classification and India's BIS harmonization with international germplasm protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Philippines Rice Seed Market
Seeds
Watermelon Seeds Market
Seeds
Europe Grain Seed Market
Seeds
Flax Crop Market
Seeds
Global Maize Seed Market
Seeds
Organic Sesame Seed Market
Seeds
Africa Sorghum Seed Market
Seeds
North America Forage Seed Market
Seeds
Global Forage Seeds Market
Seeds
Organic Seed Market
Seeds
Australia Forage Seed Market
Seeds
Global Grain Seed Market
Seeds
North America Quinoa Seeds Market
Seeds
Global Rice Seed Market
Seeds
Celery Seed Oil Market
Seeds
North America Maize Seed Treatment Market