
 South America Chia Seeds Market | 2026-2036
South America Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
South America Chia Seeds Market Analytics
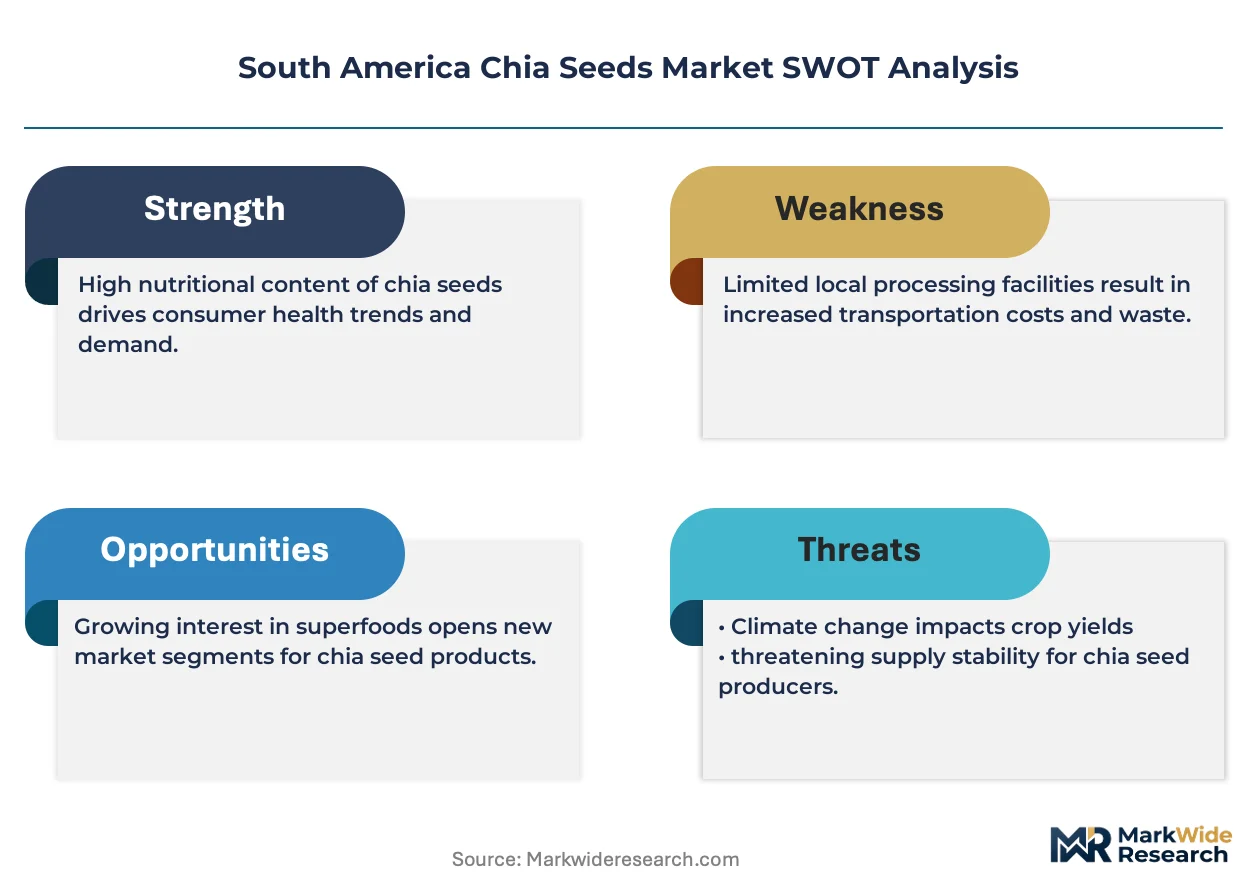
Flaxseed oil is restructuring ingredient economics across South American functional food formulations as chia omega-3 profiles command premium positioning. Benexia leverages its Bolivian origin supply base to sustain raw material cost advantages against Andean competitors. Sambazon anchors its Amazon-sourced branding to differentiate in Brazil's crowded superfood retail channel. The Chia Co competes through Australian-origin quality protocols that occupy premium shelf space in Colombian health food stores.
Chia seeds are oval-shaped annual herb seeds of Salvia hispanica containing approximately 34-40% oil by weight with alpha-linolenic acid comprising 55-65% of total fatty acid content, primarily serving as a plant-based nutritional fortifier in processed foods and supplements. Whole seeds dominate South American bulk export flows due to extended shelf stability and minimal processing overhead, while chia oil extracts capture concentrated margin pools from cosmetics and pharmaceutical buyers in São Paulo and Buenos Aires. Ground seeds and chia flour are gaining traction within Argentine bakery chains reformulating gluten-free product lines.
Argentina's National Food Safety and Quality Service enforces maximum residue limits on oilseed imports that directly shape cross-border sourcing patterns for Brazilian and Paraguayan traders. Brazil's ANVISA nutrition labeling requirements for functional claims compel processors to invest in certified analytical testing before product registration. Bolivia's national standards body maintains seed purity protocols that govern export eligibility to Mercosur partners. Stakeholders must monitor evolving Andean organic certification reciprocity agreements that could redraw competitive access between Bolivian highland producers and Argentine Pampas growers.
Market Dynamics
Contract farming networks in Paraguay's Alto Paraná corridor are consolidating raw material flows toward Argentine and Brazilian processors, compressing spot-market liquidity and elevating quality-grade premiums for aflatoxin-compliant seed lots.
Growth Catalysts
- ANVISA nutrition labeling requirements:Brazil's functional claims framework compels processors to invest in certified analytical testing, creating certified supply tiers that command shelf-space premiums in São Paulo retail channels.
- Gluten-free bakery reformulation:Argentine bakery chains are integrating chia flour into product lines, generating structured offtake agreements that stabilize processor margins against commodity volatility.
- Alto Paraná contract farming density:Paraguayan production clusters are achieving scale efficiencies that reduce per-unit logistics costs for cross-border seed movements.
Market Restraints
- Argentina's aflatoxin maximum residue limits:SENASA enforcement tightens quality thresholds for oilseed imports, rejecting non-compliant Paraguayan and Bolivian lots at border checkpoints.
- Flaxseed oil substitution economics:Alternative omega-3 sources are restructuring ingredient cost calculations for Brazilian functional food formulators, pressuring chia oil premium positioning.
- Andean organic certification fragmentation:Non-reciprocal standards between Bolivian highland producers and Mercosur partners create documentation bottlenecks that delay export eligibility.
Strategic Opportunities
- Colombian health food retail channel:Premium shelf-space availability in Bogotá and Medellín outlets offers positioning upside for quality-certified import brands.
- Cosmetics and pharmaceutical extraction demand:São Paulo and Buenos Aires buyers are purchasing concentrated chia oil for topical formulations at margins exceeding bulk seed exports.
- Evolving Andean organic certification reciprocity:Pending mutual recognition agreements could redraw competitive access between Bolivian highland producers and Argentine Pampas growers.
Industry Challenges
- Analytical testing capacity constraints:Certified laboratory availability for ANVISA-compliant fatty acid profiling remains concentrated in São Paulo and Porto Alegre, extending product registration timelines.
- Cross-border seed purity documentation:Bolivia's national standards body protocols require batch-level traceability systems that many smallholder cooperatives lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Chia Seeds Market |
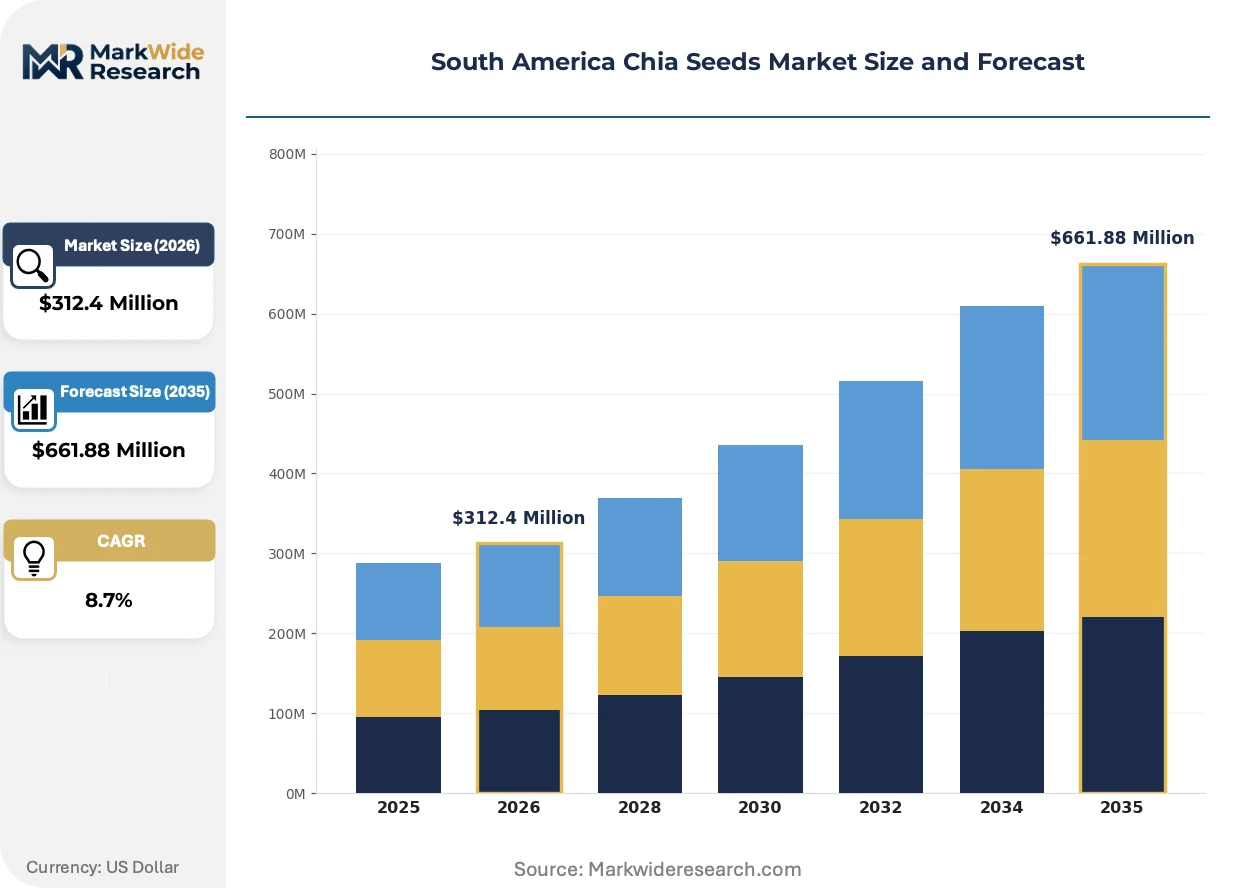
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Chia Oil, Chia Flour End User: Food & Beverage, Dietary Supplements, Bakery, Cosmetics Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales Application: Functional Foods, Beverages, Snack Bars, Bakery Products |
| Companies Covered | Advanta Seeds, Sambazon, Benexia, Navitas Organics, Agricor, Millennium Seed, The Chia Co, Mamma Chia, Soufflet Seeds, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Chia Seeds Market Evolving Landscape
Processing technology diffusion and regulatory harmonization pressures are restructuring how chia seed value migrates from raw commodity to finished ingredient across South American supply chains.
Cold-press oil extraction equipment is decentralizing production geography across the region. Mid-scale processors in Córdoba and Santa Catarina are adopting modular pressing units that enable on-farm oil production, bypassing traditional concentration in Buenos Aires and São Paulo crushing facilities. This technology is decentralizing margin capture toward origin-adjacent operators and compressing the historical logistics-cost advantage of coastal processors.
Argentina's SENASA aflatoxin enforcement protocol is tightening import inspection regimes. The regulation mandates laboratory certification for all oilseed border crossings, industrializing quality assurance as a non-negotiable cost layer. Paraguayan exporters are responding by consolidating around accredited testing cooperatives in Ciudad del Este to pre-clear shipments.
Direct-procurement relationships between Brazilian functional food manufacturers and Paraguayan contract farming networks are displacing spot-market intermediation. Large processors in Minas Gerais are signing multi-season offtake agreements that specify cultivar, organic status, and delivery windows. This pattern concentrates most visibly in the Alto Paraná corridor, where farming associations are reorganizing around processor-dictated quality protocols.
South America Chia Seeds Market Segmentation
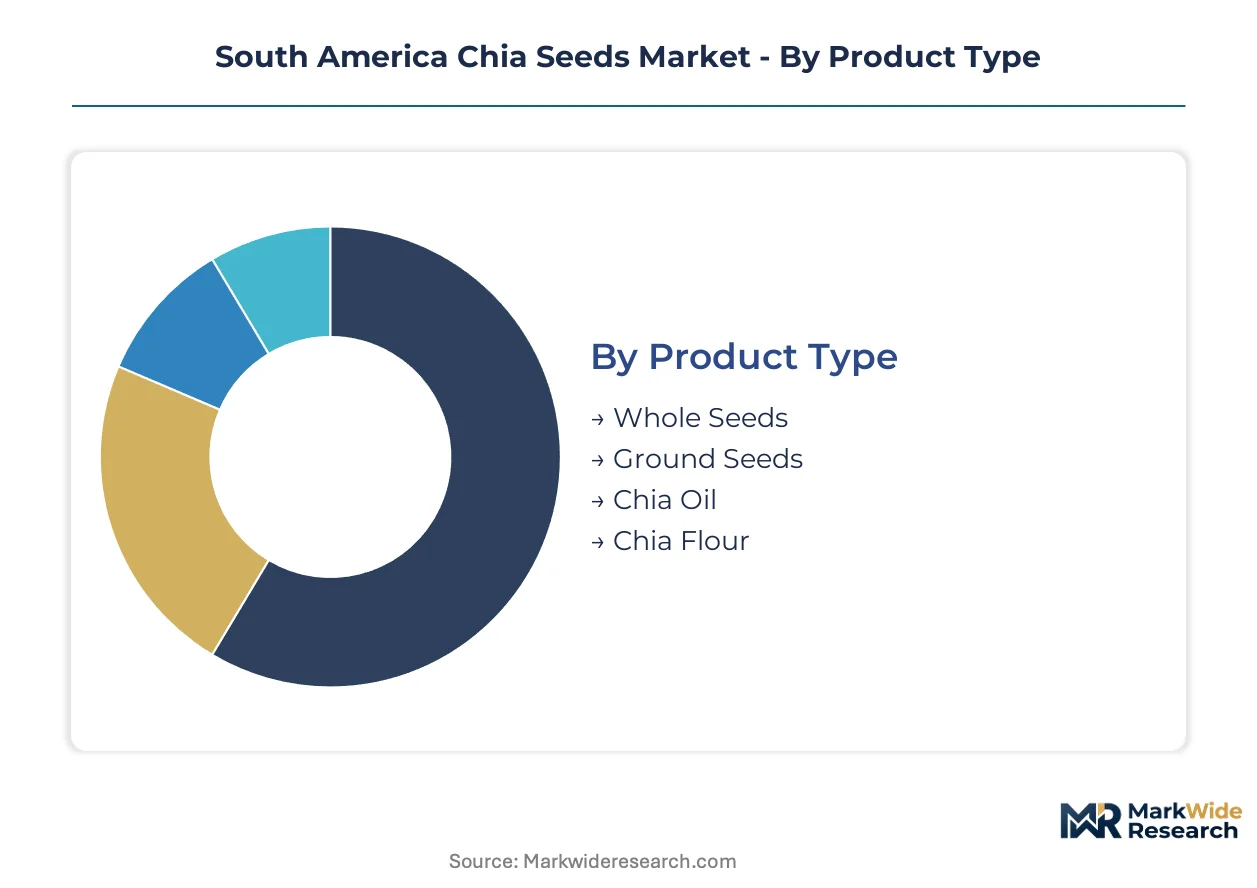
Chia seed value migration across South American supply chains follows distinct certification and processing pathways. Each segment carries specific regulatory burdens that reshape procurement economics and margin distribution.
Product Type:
Whole seeds require only phytosanitary clearance for cross-border movement within Mercosur, while oil and flour derivatives trigger ANVISA and SENASA nutritional labeling mandates.
- Whole Seeds:Unprocessed oval seeds retain 34-40% oil content by weight with alpha-linolenic acid comprising 55-65% of fatty acid profiles. Paraguayan exporters in the Alto Paraná corridor dominate bulk flows to Argentine crushing facilities, though SENASA aflatoxin screening rejects non-compliant lots at Ciudad del Este checkpoints.
- Chia Oil:Cold-pressed extraction yields concentrated omega-3 formulations for São Paulo cosmetics laboratories and Buenos Aires pharmaceutical compounders. ANVISA fatty acid profiling requirements extend registration timelines, creating certified supply tiers that command premium positioning.
- Ground Seeds:Milled products serve Argentine gluten-free bakery chains reformulating product lines with structured offtake agreements.
- Chia Flour:Defatted meal byproducts integrate into protein-fortified snack formulations across Brazilian processing hubs.
Whole seeds sit at the top of the volume ranking, with chia oil climbing the fastest.
End User:
Customer procurement scale determines testing burden distribution, with large food manufacturers internalizing analytical costs that smaller cosmetics buyers outsource.
- Food & Beverage:Brazilian functional food manufacturers in Minas Gerais and São Paulo states drive contract farming consolidation. Multi-season offtake agreements specify cultivar, organic status, and delivery windows that displace spot-market intermediation.
- Dietary Supplements:Capsule and tablet formulators source certified organic grades through Colombian health food retail channels. Bogotá and Medellín outlets offer positioning upside for quality-verified import brands facing ANVISA compliance costs.
- Bakery:Argentine chains integrate chia flour into gluten-free lines with processor-dictated quality protocols stabilizing margins against commodity volatility.
- Cosmetics:Topical formulation buyers in São Paulo purchase concentrated oil at margins exceeding bulk seed exports.
Food and beverage captures the largest procurement volumes, with dietary supplements expanding most quickly.
Distribution Channel:
Channel selection dictates traceability system requirements, with direct sales and health food stores demanding batch-level documentation that supermarket and online retail channels relax.
- Direct Sales:Processor-farmer relationships in Paraguay's Alto Paraná corridor bypass traditional trader intermediation. Farming associations reorganize around quality protocols specified by Brazilian buyers.
- Health Food Stores:Colombian outlets in Bogotá and Medellín provide premium shelf-space access for certified organic grades. Australian-origin quality protocols occupy differentiated positioning against Andean competitors.
- Supermarkets:Mass retail channels in São Paulo and Buenos Aires concentrate volume flows of whole seeds with minimal processing overhead.
- Online Retail:E-commerce platforms reduce per-unit logistics costs for cross-border seed movements from Bolivian highland producers.
Supermarkets maintain volume leadership, with direct sales gaining share fastest.
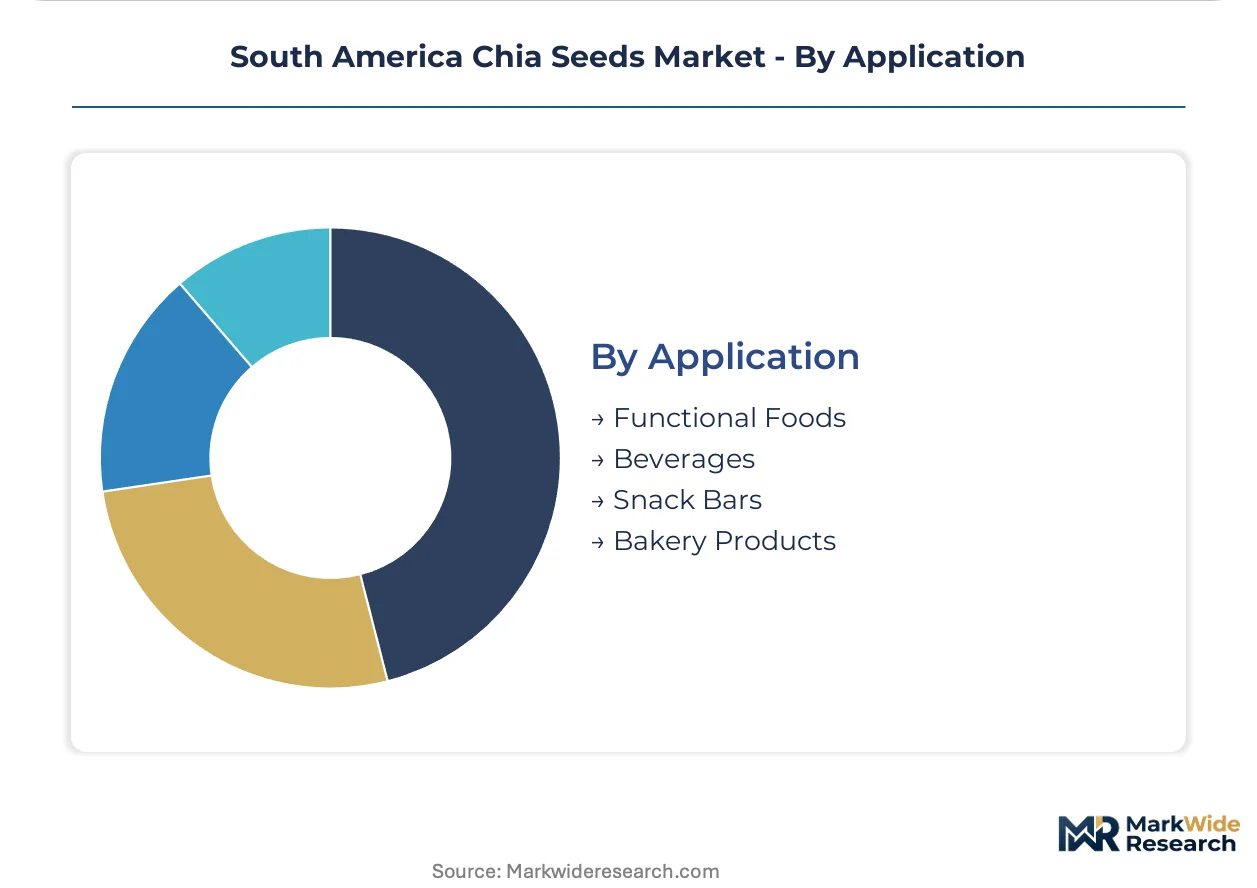
Application:
End-use formulation complexity determines margin capture, with beverage integration requiring emulsion stability testing that snack bar and bakery applications avoid.
- Functional Foods:Fortified product lines in Brazil compel processors to invest in certified analytical testing before ANVISA registration. Nutrition labeling requirements for functional claims create certified supply tiers commanding shelf-space premiums.
- Beverages:Chia gel incorporation into Brazilian fortified beverages demands emulsion stability verification. Manufacturers expand chia incorporation as flaxseed oil substitution economics pressure omega-3 ingredient sourcing.
- Snack Bars:Binding and texture modification applications utilize whole and ground seed grades with extended shelf stability requirements.
- Bakery Products:Argentine gluten-free reformulation drives structured offtake agreements for chia flour derivatives.
Functional foods hold the top volume position, with beverages showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alto Paraná corridor contract farming networks concentrate South American chia seed production, funneling raw material toward Argentine and Brazilian processing hubs while regulatory enforcement reshapes cross-border trade flows.
Brazil
ANVISA nutrition labeling requirements for functional claims compel processors to invest in certified analytical testing before product registration. São Paulo and Minas Gerais states anchor demand from fortified beverage manufacturers expanding chia incorporation. Direct procurement relationships with Paraguayan farming associations are displacing traditional spot-market intermediation.
Argentina
Gluten-free bakery chains in Buenos Aires and Córdoba drive structured offtake agreements for chia flour derivatives. SENASA aflatoxin maximum residue limits tighten quality thresholds for oilseed imports, rejecting non-compliant Paraguayan and Bolivian lots at border checkpoints. Santa Fe province processors consolidate cold-press extraction capacity for cosmetics and pharmaceutical buyers.
Paraguay
Contract farming density in the Alto Paraná corridor achieves scale efficiencies that reduce per-unit logistics costs for cross-border seed movements. Farming associations reorganize around processor-dictated quality protocols specified by Brazilian buyers. Ciudad del Este testing cooperatives pre-clear shipments to navigate SENASA enforcement regimes.
Bolivia
Highland producers leverage origin supply base cost advantages against Andean competitors. The national standards body maintains seed purity protocols governing export eligibility to Mercosur partners. Non-reciprocal organic certification standards with Mercosur partners create documentation bottlenecks delaying export eligibility for smallholder cooperatives.
Colombia
Bogotá and Medellín health food retail channels offer premium shelf-space positioning for quality-certified import brands. Australian-origin quality protocols occupy differentiated positioning against Andean competitors in urban outlets. Dietary supplement capsule formulators source certified organic grades through established distribution networks.
South America Chia Seeds Market Competitive Landscape
Global majors compete with regional champions across certification and sourcing dimensions, creating a tiered structure where origin-based quality protocols determine shelf-space access. The market fragments across three strategic archetypes: Andean-origin suppliers leveraging highland production cost structures, Australian-import brands occupying premium positioning through quality protocols, and Amazon-sourced operators differentiating through biodiversity branding. Dominant competitive moves include backward integration into contract farming networks and geographic expansion through health food retail channel penetration.
Within the origin-specialist tier, Benexia anchors Bolivian highland supply base positioning, Sambazon exemplifies Amazon-sourced biodiversity differentiation, and The Chia Co occupies Australian-import quality protocol representation. These three entities collectively illustrate how geographic origin branding reshapes competitive access across Brazilian and Colombian retail channels, with each archetype commanding distinct margin pools based on certification tier and traceability documentation depth.
| Leading Market Players |
|---|
| Advanta Seeds |
| Sambazon |
| Benexia |
| Navitas Organics |
| Agricor |
| Millennium Seed |
| The Chia Co |
| Mamma Chia |
| Soufflet Seeds |
| Others |
Value Network & Pricing Analysis
ANVISA organic certification mandates gate both qualified supply and premium-tier pricing access in Brazil's functional food channels, compressing margin capture for non-compliant operators while rewarding certified processors with shelf-space premiums in São Paulo retail networks. This regulatory filter concentrates pricing power among accredited testing cooperatives and pre-qualified Paraguayan exporters.
Pricing Analysis
Input-cost pass-through from aflatoxin testing and ANVISA fatty acid profiling flows unevenly across contract tiers, with multi-season offtake agreements insulating Argentine and Brazilian processors from spot-market volatility. Price differentiation rests on certification grade and volume scale, where SENASA-compliant lots command substantial premiums over uncertified Bolivian alternatives. Pricing pressure intensifies as flaxseed oil substitution economics erode chia omega-3 positioning in beverage formulations. Large functional food manufacturers exhibit lowest price sensitivity due to captive supply arrangements, while cosmetics buyers in Buenos Aires demonstrate highest elasticity.
Supply Chain Analysis
Freight cost differentials between Alto Paraná corridor origins and coastal crushing facilities in Buenos Aires and São Paulo shape procurement geography for Brazilian processors. Supply concentrates in Paraguay, Bolivia, and Argentina, with raw material dependencies spanning cultivar seed stock, cold-press extraction equipment, and certified laboratory capacity. Single-source vulnerability runs through Ciudad del Este testing cooperatives pre-clearing SENASA shipments. Distribution runs through direct-procurement relationships displacing traditional trader intermediation, with farming associations reorganizing around processor-dictated quality protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America chia seeds market functions as a stable compounder, with ANVISA regulatory compliance requirements perpetually renewing demand for certified supply tiers across Brazilian functional food channels.
For Market Incumbents: Extend backward integration into Alto Paraná contract farming networks to secure cultivar-specific supply against Bolivian highland cost competition. Deepen captive testing capacity in São Paulo and Porto Alegre to compress ANVISA registration timelines for new product launches. Lock multi-season offtake agreements with Paraguayan farming associations before organic certification reciprocity agreements redraw competitive access. For New Entrants and Emerging Players: The premium-economy price-point gap in Colombian health food retail channels offers accessible positioning against Australian-import incumbents. Target Bogotá and Medellín outlets with certified organic grades bypassing ANVISA compliance costs borne by Brazilian competitors. Pursue white-label supply relationships with Argentine gluten-free bakery chains seeking structured offtake stability. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cold-press extraction operators because decentralized processing technology is compressing historical logistics-cost advantages of coastal crushing facilities. Platform consolidation around Córdoba and Santa Catarina processing hubs captures margin migration toward origin-adjacent operators. Watch for Andean organic certification reciprocity implementation as inflection signal for Bolivian highland producer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Secures cultivar-specific supply in Paraguay's Alto Paraná corridor against spot-market volatility. |
| Certified Laboratory Capacity Expansion | Compresses ANVISA fatty acid profiling timelines for São Paulo functional food manufacturers. |
| Organic Certification Reciprocity Pursuit | Unlocks Mercosur market access for Bolivian highland producer cooperatives. |
| Direct-Procurement Relationship Deepening | Displaces trader intermediation in Brazilian-Paraguayan cross-border seed flows. |
| Cold-Press Extraction Technology Adoption | Enables on-farm oil production in Córdoba and Santa Catarina bypassing coastal facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with functional food formulators, ANVISA regulatory consultants, Paraguayan farming association leaders, and Argentine bakery chain procurement managers with secondary validation through SENASA enforcement bulletins, ANVISA product registration databases, Mercosur trade flow records, and organic certification body reciprocity filings. Bottom-up farmer survey data and top-down processor capacity assessments were triangulated against cross-border shipment manifests.
Historical reference periods anchored the projection horizon to established growth trajectories in functional food ingredient markets, with segmentation modeling across product type, end user, distribution channel, and application dimensions. CAGRs were derived from fitted trend analysis incorporating aflatoxin compliance rates, cold-press extraction capacity expansion, and direct-procurement contract penetration as industry-specific inputs.
The model assumes a particular technology adoption path for decentralized cold-press extraction; alternative pathways for on-farm oil processing would alter the outlook for coastal crushing facility margins. Forecasts reflect assumptions around ANVISA regulatory stability and SENASA enforcement consistency. A model refresh is warranted upon material change in Andean organic certification reciprocity implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Fruit Seed Waste Market
Seeds
Sesame Seeds Market
Seeds
Organic Sesame Seed Market
Seeds
Cannabis Seeds Market
Seeds
Custom Selected Seed Market
Seeds
Mustard Seeds Market
Seeds
Cotton Seed Treatment Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Vegetable Seed Protein Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Ghana Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Global Rice Seed Market
Seeds
Native Grass Seeds Market
Seeds
Asia-Pacific Quinoa Seeds Market