
 North America Forage Seed Market | 2026-2036
North America Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Forage Seed Market Analytics
Seed treatment subscription services is expanding how forage genetics reach dairy and beef producers in North America. Bayer AG leverages its crop science infrastructure to bundle seed coatings with digital agronomy platforms across the Corn Belt. Corteva Agriscience anchors its forage portfolio through proprietary alfalfa trait stacks and dealer network density. KWS SAAT SE & Co. KGaA competes on perennial ryegrass breeding intensity for high-elevation ranch systems.
Forage seed comprises genetically improved propagules of grasses, legumes, and mixed species bred for germination rate, digestibility, and winter hardiness, primarily serving ruminant livestock nutrition and soil stabilization objectives. Legumes carry premium pricing in dairy-intensive counties due to crude protein advantages and nitrogen-fixation benefits that reduce synthetic fertilizer outlays. Grasses dominate volume throughput across beef cattle ranches where tonnage per acre drives procurement decisions, while cover crop applications gain traction in corn-soy rotations seeking erosion mitigation.
USDA Animal and Plant Health Inspection Service protocols govern phytosanitary certification for interstate seed movement, while CFIA seed regulations in Canada mandate varietal purity testing and weed seed tolerance limits for commercial lots. The EPA oversees pesticide-treated seed stewardship requirements that constrain coating chemistry options and label claims. Stakeholders must monitor evolving carbon credit eligibility for perennial forage plantings and corresponding verification standards that could reshape seed variety selection criteria.
Market Dynamics
Feed cost volatility is compressing dairy margins across the Upper Midwest, accelerating perennial pasture conversions and certified seed procurement as operators seek multi-year cost predictability.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Conservation cost-share agreements offset establishment expenses for perennial forage systems, driving certified seed uptake in Wisconsin and Minnesota dairy counties.
- Precision agriculture platforms:Variable-rate seeding technology enables site-specific cultivar matching, improving stand establishment rates and reducing replant costs for Corn Belt operators.
- Dairy processor sustainability mandates:Scope 3 emission targets downstream are pressuring farm suppliers to document carbon-sequestering forage rotations, favoring perennial legume varieties with verified nitrogen-fixation credits.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress seed treatment margins, constraining coating chemistry investments for regional distributors.
- Variety approval timelines:CFIA's cultivar registration process in Canada extends commercialization cycles, delaying novel trait introductions in Ontario's dairy corridor.
- Climate variability:Erratic winter hardiness zones are elevating replant risk for perennial stands, dampening multi-year contract commitments among risk-averse beef ranchers.
Strategic Opportunities
- Carbon credit verification protocols:Emerging soil carbon quantification standards for perennial forage plantings create premium positioning for deep-rooted grass cultivars in voluntary offset markets.
- Seed treatment subscription bundling:Agronomy-as-a-service models integrate coated genetics with digital scouting, penetrating mid-size dairy operations previously served by commodity dealers.
- Cover crop integration:Corn-soy rotations in Iowa and Illinois are adopting multi-species forage blends for erosion control, opening non-livestock demand channels for regional seed houses.
Industry Challenges
- Phytosanitary certification complexity:Interstate movement protocols under USDA APHIS create documentation bottlenecks, extending order fulfillment cycles for cross-border seed lots.
- Trait stewardship compliance:EPA-treated seed label requirements constrain coating formulation flexibility, forcing reformulation investments that strain smaller conditioning facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Forage Seed Market |
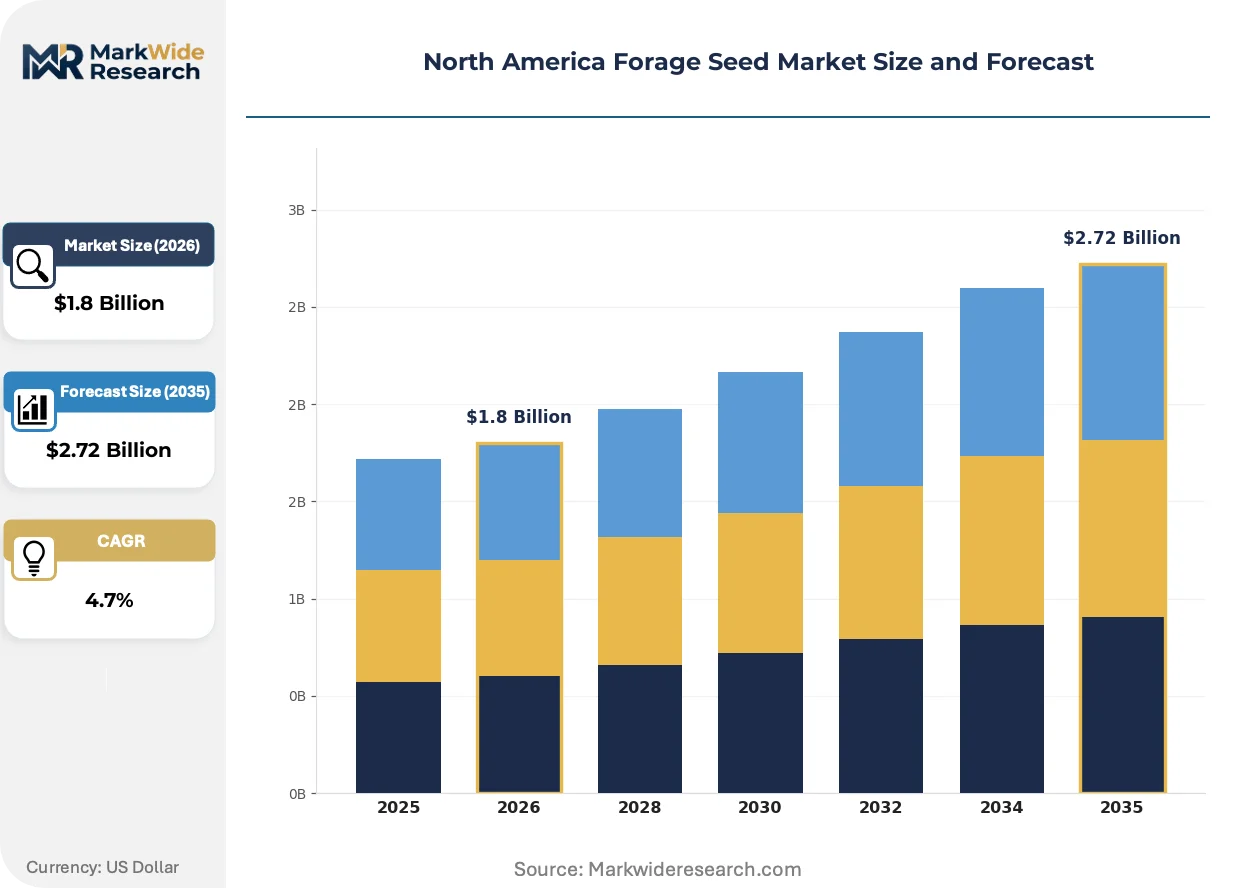
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Mixtures, Cover Crops End User: Dairy Farms, Beef Cattle Ranches, Poultry Farms, Horse Farms Distribution Channel: Online Retailers, Agricultural Supply Stores, Direct Sales, Wholesalers Application: Animal Feed, Soil Erosion Control, Green Manure, Wildlife Habitat |
| Companies Covered | KWS SAAT SE & Co. KGaA, Royal Barenbrug Group, Bayer AG, Ampac Seed Company, Advanta Seeds - UPL, Corteva Agriscience, Land O'Lakes Inc., Allied Seed LLC, DLF, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Forage Seed Market Evolving Landscape
Digital agronomy tools are rewiring how genetic performance reaches livestock producers, compressing the feedback loop between field data and cultivar selection while elevating service-based revenue models.
CRISPR-edited alfalfa lines with condensed tannin profiles are expanding into dairy nutrition programs, enabling direct grazing without bloating risk. Wisconsin-based cooperatives are piloting these cultivars across rotational paddocks, compressing the timeline for novel trait commercialization from decade-long cycles toward five-year variety turnover.
CFIA's updated weed seed tolerance regulations are tightening commercial lot standards, forcing conditioning facilities to upgrade optical sorting infrastructure. Ontario seed houses are consolidating cleaning operations to amortize capital costs, while smaller dealers exit certified legume distribution. The regulatory friction is accelerating dealer network concentration in the province's dairy-intensive counties.
Dairy procurement officers are consolidating vendor relationships around full-service genetics providers, displacing spot-market seed purchases. Large herd operations in Minnesota and New York are negotiating multi-year supply agreements bundling cultivars, treatment, and agronomic support. The contract compression is visible across operations exceeding five hundred milking head, where procurement staffs now prioritize performance guarantees over unit price minimization.
North America Forage Seed Market Segmentation
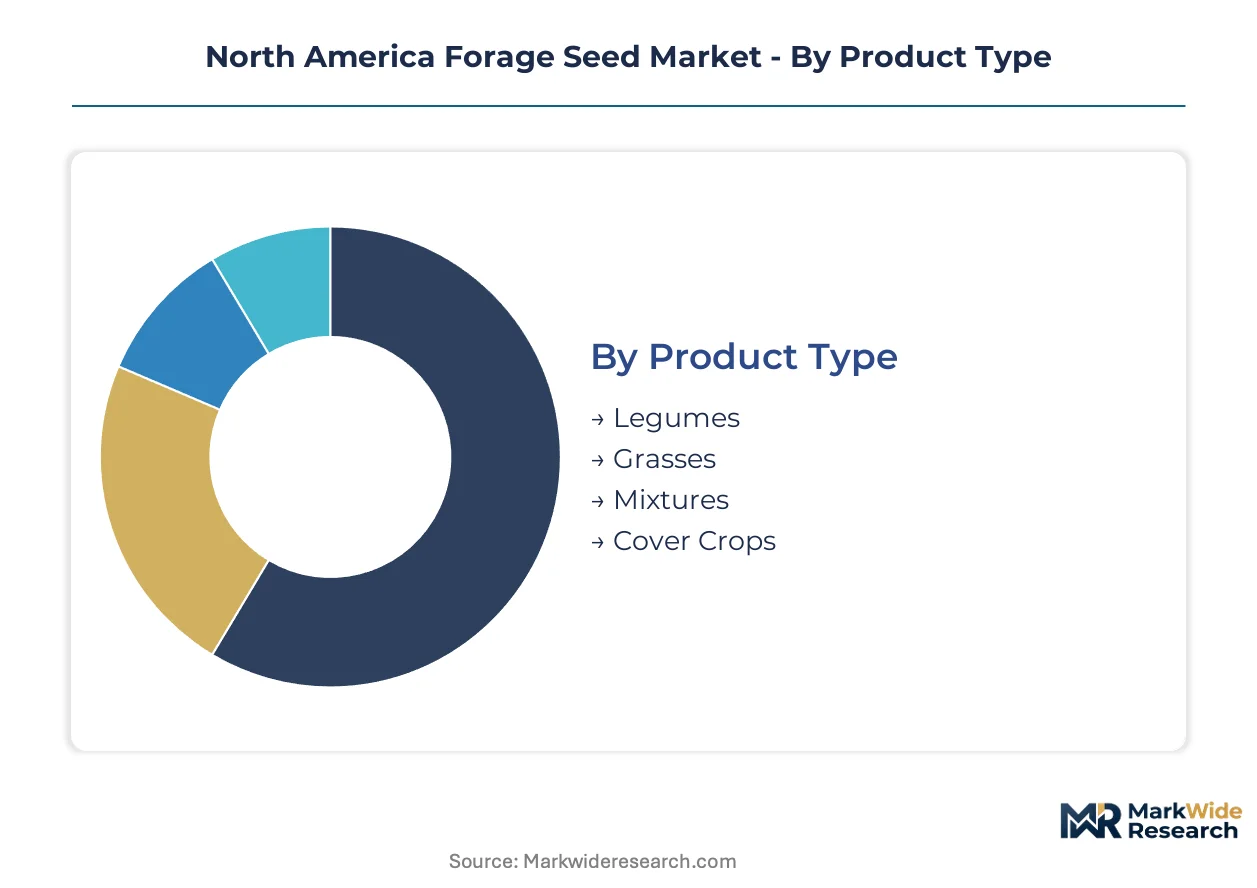
Segmentation in forage seed markets reveals how genetic performance, procurement channels, and end-use requirements diverge across livestock systems and conservation applications. Understanding these divides enables suppliers to match cultivar investments with margin concentration and customer switching costs.
Product Type:
Standardization dominates commodity grasses, while legumes and cover crop blends demand cultivar-specific agronomic support and carry premium positioning.
- Legumes:Alfalfa and clover varieties bred for crude protein content and nitrogen fixation command price premiums in dairy-intensive counties. Upper Midwest dairy belt operators in Wisconsin and Minnesota prioritize certified legume seed for multi-year stand persistence and reduced synthetic fertilizer outlays.
- Grasses:Perennial ryegrass and orchard grass selections emphasize tonnage per acre and winter hardiness ratings. Beef cattle ranches across the Great Plains prioritize volume throughput and drought tolerance over protein content, compressing margins through commodity procurement patterns.
- Mixtures:Multi-species blends balance palatability, seasonal growth curves, and soil adaptation for rotational grazing systems.
- Cover Crops:Annual ryegrass and crimson clover formulations target erosion mitigation and soil carbon building in corn-soy rotations.
Leading the category by volume: Grasses. Growing fastest: Cover Crops.
End User:
Procurement sophistication escalates with herd scale, separating price-sensitive small operators from performance-contracting large enterprises.
- Dairy Farms:Large herd operations exceeding five hundred milking head negotiate multi-year supply agreements bundling cultivars, seed treatment, and digital agronomy support. Minnesota and New York procurement staffs prioritize performance guarantees over unit price minimization.
- Beef Cattle Ranches:Extensive grazing operations across the Great Plains and Mountain West emphasize tonnage per acre and drought tolerance. Risk-averse ranchers dampen multi-year contract commitments due to erratic winter hardiness zones elevating replant risk.
- Poultry Farms:Limited forage seed demand concentrates in pasture-raised egg operations seeking diversified feed sources.
- Horse Farms:Kentucky and Florida equine operations prioritize low-sugar grass cultivars for metabolic health management.
Dairy Farms anchor procurement value. Horse Farms represent the steepest expansion trajectory as equine nutrition science advances.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and inventory carrying capacity across the seed value chain.
- Agricultural Supply Stores:Dealer networks with conditioning facilities and certified seed storage dominate legume distribution in Ontario's dairy corridor. CFIA weed seed tolerance regulations are forcing consolidation as smaller dealers exit certified distribution.
- Direct Sales:Genetics providers bypass intermediaries for large herd operations, bundling cultivars with agronomic-as-a-service platforms. Bayer AG and Corteva Agriscience leverage crop science infrastructure to penetrate mid-size dairy operations previously served by commodity dealers.
- Online Retailers:E-commerce penetration remains limited by phytosanitary certification complexity and interstate movement documentation requirements.
- Wholesalers:Volume aggregation serves smaller beef ranchers and cover crop adopters in Iowa and Illinois corn-soy rotations.
Agricultural Supply Stores retain channel dominance. Direct Sales is gaining share fastest as procurement consolidation accelerates.
Application:
Application segmentation separates livestock nutrition economics from environmental service payments and emerging carbon credit eligibility.
- Animal Feed:Ruminant nutrition drives cultivar selection for digestibility, protein content, and palatability. Dairy processor sustainability mandates pressuring Scope 3 emission documentation favor perennial legume varieties with verified nitrogen-fixation credits.
- Soil Erosion Control:USDA Environmental Quality Incentives Program cost-share agreements offset establishment expenses for perennial forage systems. Wisconsin and Minnesota conservation districts drive certified seed uptake for waterway buffer plantings.
- Green Manure:Nitrogen-building rotations in organic systems prioritize crimson clover and hairy vetch for biomass accumulation prior to cash crop planting.
- Wildlife Habitat:State wildlife agency contracts and private landowner conservation programs sustain demand for diverse native grass and forb mixtures.
Animal Feed commands application value. Soil Erosion Control shows the most rapid demand acceleration as carbon credit verification protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates forage seed consumption across the continent, while Canadian production clusters concentrate in Ontario and Quebec. Mexico's emerging dairy sector imports certified genetics to rebuild pasture infrastructure. Sub-regional specialization separates Upper Midwest dairy systems from Great Plains beef operations and Mountain West high-elevation ranching.
United States
Wisconsin and Minnesota dairy counties drive certified legume demand through multi-year stand conversions. USDA Environmental Quality Incentives Program cost-share agreements offset perennial pasture establishment expenses. The I-94 corridor between Madison and Minneapolis anchors dealer network consolidation as precision agriculture platforms penetrate mid-size operations.
Canada
Ontario's dairy belt imports novel alfalfa genetics delayed by CFIA cultivar registration timelines. Health Canada and CFIA seed regulations mandate varietal purity testing that forces conditioning facility upgrades. Guelph-Waterloo research clusters pilot CRISPR-edited cultivars while smaller dealers exit certified distribution.
Mexico
Expanding dairy processor capacity in Jalisco and Nuevo León drives imported perennial ryegrass demand. The country's national agricultural regulator enforces phytosanitary protocols for cross-border seed movement. Bajío Region ranchers adopt drought-tolerant orchard grass selections as feed cost volatility compresses margins.
North America Forage Seed Market Competitive Landscape
Top-tier vendors anchor genetics and digital platform bundling, while regional distributors compete on conditioning infrastructure and local agronomic relationships. The market structures around three tiers: multinational crop science conglomerates with crop protection integration, specialized forage breeders with perennial grass portfolios, and cooperative-aligned distributors with geographic density. Dominant competitive moves include seed treatment subscription bundling and precision agriculture platform partnerships that displace commodity dealer relationships.
Among German-origin seed houses, KWS SAAT SE & Co. KGaA exemplifies perennial ryegrass breeding intensity for high-elevation ranch systems. Bayer AG and Corteva Agriscience occupy positions as crop science conglomerates leveraging infrastructure across the Corn Belt. These three represent distinct archetypes: specialized perennial breeding, integrated crop protection bundling, and trait-stacked alfalfa commercialization.
| Leading Market Players |
|---|
| KWS SAAT SE & Co. KGaA |
| Royal Barenbrug Group |
| Bayer AG |
| Ampac Seed Company |
| Advanta Seeds - UPL |
| Corteva Agriscience |
| Land O'Lakes Inc. |
| Allied Seed LLC |
| DLF |
| Others |
Value Network & Pricing Analysis
Chicago Board of Trade corn futures volatility cascades through North American forage seed pricing tiers, compressing margins for commodity grass distributors while legume genetics with certified purity premiums retain pricing power across Wisconsin and Minnesota dairy procurement desks.
Pricing Analysis
Margin tightening in standard grass cultivars reflects fertilizer cost pass-through limitations and spot-market procurement patterns among Great Plains beef ranchers. Three-tier pricing structure across certified legume, treated grass, and commodity open-pollinated varieties separates dairy operations with multi-year contracts from price-sensitive ranchers purchasing volume-tonnage lots. Cost-down pressure on seed treatment coatings accelerates because EPA stewardship requirements force chemistry reformulation investments that smaller conditioning facilities cannot amortize. Beef cattle ranches demonstrate highest price sensitivity, while large herd dairy operations exceeding five hundred milking head prioritize performance guarantees over unit price minimization.
Supply Chain Analysis
Seasonal labor availability in Oregon's Willamette Valley and Idaho's Magic Valley conditioning facilities constrains harvest-to-cleaning throughput during peak autumn windows. Supply concentrates in the United States, Canada, and limited Mexican import channels for novel alfalfa genetics. Raw material dependencies include foundation seed stocks, coating polymer chemistries, and optical sorting equipment. Single-source vulnerability sits with proprietary trait-stacked germplasm controlled by crop science conglomerates. Distribution runs through agricultural supply stores with certified seed storage, though direct sales penetration accelerates as genetics providers bundle cultivars with digital agronomy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American forage seed markets operate as a cost-of-compliance story where CFIA cultivar registration timelines and EPA-treated seed stewardship requirements erect barrier-to-entry moats favoring conditioning facilities with capital reserves for regulatory infrastructure.
For Market Incumbents: Anchor dealer network density in Ontario's dairy corridor through conditioning facility consolidation that amortizes optical sorting capital costs against tightening weed seed tolerance regulations. Defend against direct sales penetration by bundling certified legume genetics with agronomic-as-a-service platforms for mid-size Wisconsin and Minnesota operations. Prioritize backward integration into foundation seed production to secure germplasm access amid trait stewardship compliance pressures. For New Entrants and Emerging Players: Agricultural supply store partnerships offer lowest-friction channel access for cover crop blend penetration in Iowa and Illinois corn-soy rotations. Target soil erosion control applications where USDA Environmental Quality Incentives Program cost-share agreements offset establishment expenses and reduce customer acquisition friction. White-space exists in carbon credit verification protocol development for deep-rooted perennial grass cultivars entering voluntary offset markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor cooperative-aligned distributors with geographic density in the Upper Midwest dairy belt. Long-term viability over the coming decade hinges on precision agriculture platform integration capabilities and seed treatment subscription bundling infrastructure. Monitor CFIA cultivar registration timeline compression as inflection indicator for novel trait commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Seed Treatment Subscription Bundling | Agronomy-as-a-service models penetrate mid-size dairy operations previously served by commodity dealers. |
| Precision Agriculture Platform Partnership | Variable-rate seeding technology enables site-specific cultivar matching across Corn Belt operations. |
| Conditioning Facility Consolidation | Optical sorting infrastructure upgrades amortize capital costs as CFIA weed seed tolerance regulations tighten. |
| Carbon Credit Verification Protocol Development | Soil carbon quantification standards for perennial forage plantings create premium positioning in voluntary offset markets. |
| Direct Sales Channel Expansion | Genetics providers bypass intermediaries for large herd operations bundling cultivars with performance guarantees. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, triangulated with primary interviews involving seed conditioning facility operators, dairy procurement officers, agricultural supply store managers, and CFIA regulatory affairs specialists. USDA APHIS phytosanitary certification databases, EPA pesticide-treated seed label registries, and provincial seed regulatory filings provided validation anchors. Bottom-up cultivar volume estimates and top-down market sizing converged through iterative reconciliation across the analysis window.
Segmentation granularity modeled product type at cultivar level, end user at herd scale tier, distribution channel at service bundling intensity, and application at carbon credit eligibility status. CAGRs derived from logistic growth curve fitting against historical adoption patterns and policy incentive trajectories. Forecast inputs incorporated dairy processor sustainability mandate timelines and precision agriculture platform penetration curves without year-specific milestones.
Caveats apply where CFIA cultivar registration timeline compression, EPA coating chemistry restriction revisions, or carbon credit verification standard maturation could materially shift the outlook. Forecasts reflect documented assumptions regarding conservation program funding continuity and feed cost volatility persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Australia Oilseed Market
Seeds
Global Soybean Seed Market
Seeds
Spain Forage Seed Market
Seeds
Cucumber Seeds Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Flaxseed (Linseed) Market
Seeds
Vietnam Seed Market
Seeds
Wax Gourd Seed Market
Seeds
Global Seed Market
Seeds
Hybrid Rice Seeds Market
Seeds
North America Tomato Seed Market
Seeds
Global Wheat Seed Market
Seeds
Myanmar Seed Market
Seeds
Asia-Pacific Maize Seed Market