
 Global Sunflower Market | 2026-2036
Global Sunflower Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sunflower Market Outlook
Black Sea sunflower seed stockpiles is rebalancing trade flows after harvest disruptions redirected cargoes toward Romanian and Bulgarian ports. Bunge Ltd leverages its Danube River crush assets to sustain European oil deliveries despite upstream seed shortages. Kernel Holding S.A. anchors Ukrainian export volumes through alternative overland routes, while Cargill Incorporated competes by extending Black Sea origination networks into Central Asian supply basins.
Sunflower denotes the cultivated oilseed Helianthus annuus and its derivative products, with seed oil content typically ranging from 40-50% by weight depending on hybrid variety and growing conditions. The primary commercial purpose centers on edible oil extraction for frying and baking applications, plus high-protein meal output for livestock rations. Oil dominates product type value generation due to its ubiquity in packaged foods and foodservice frying across European and South Asian kitchens. Snacks occupies a premium niche where roasted kernel products command shelf space in German and Turkish retail channels. Meal trails in absolute margin contribution but supports crush economics through steady demand from Polish and Spanish compound feed manufacturers.
FDA nutrition labeling requirements and EFSA trans fat restrictions shape product formulation decisions among North American and European food manufacturers, directly lifting high-oleic sunflower oil demand. REACH chemical registration and EU Green Deal sustainability criteria govern input sourcing disclosures for cosmetics-grade refined oil sold into French and German personal care supply chains. Stakeholders must monitor seed origin certification requirements and crushing capacity relocation patterns as trade policy volatility redefines optimal asset positioning.
Market Dynamics
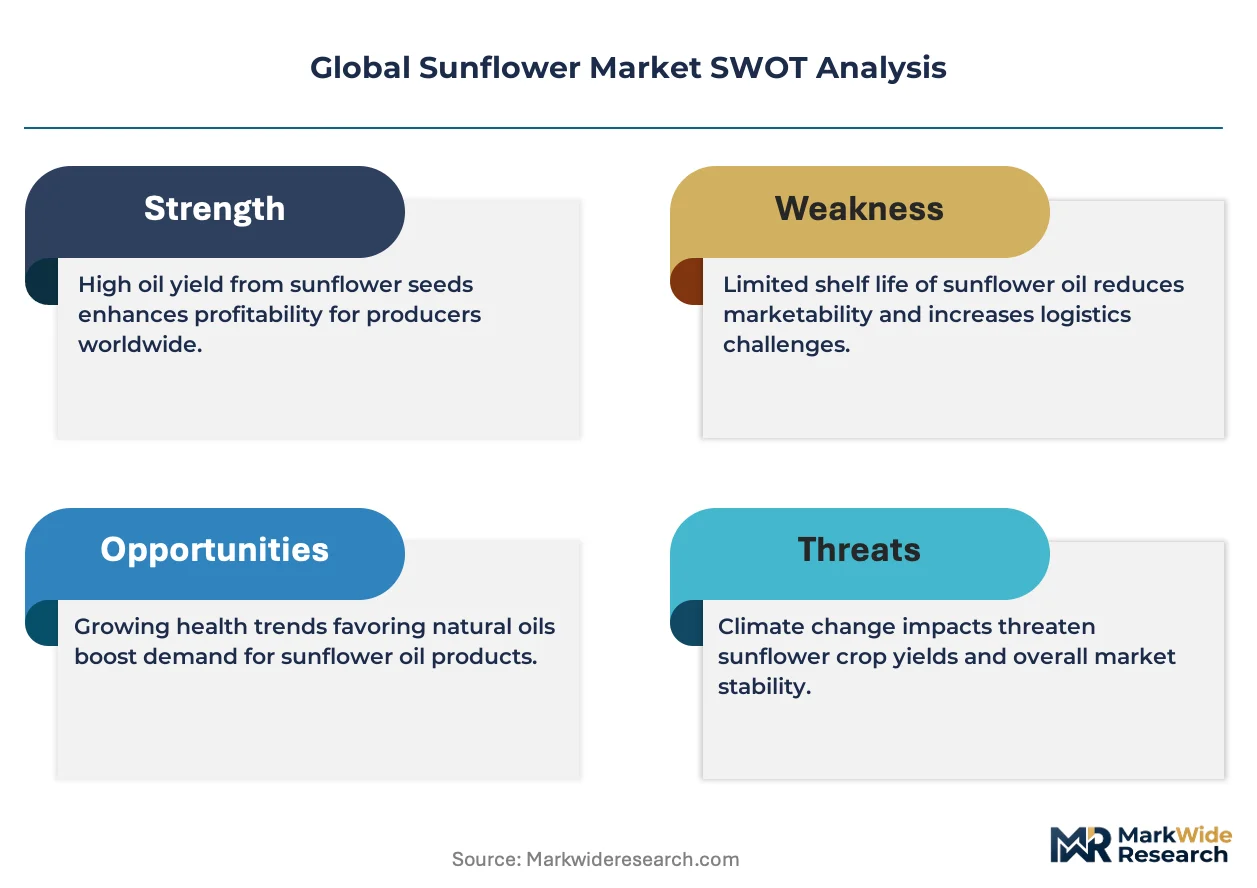
Black Sea supply concentration has created structural vulnerability for European and Asian refiners, forcing accelerated diversification into Romanian crushing corridors and Central Asian seed sourcing networks that bypass traditional maritime routes.
Growth Catalysts
- Trans Fat Reformulation Mandates:FDA and EFSA labeling rules compel food manufacturers to replace hydrogenated oils with high-oleic sunflower variants in frying and baking applications.
- Livestock Protein Demand:Polish and Spanish compound feed manufacturers sustain crush economics through steady meal offtake, anchoring processor margins even during oil price volatility.
- Cosmetics-Grade Refining Expansion:REACH registration requirements and EU Green Deal sustainability criteria drive certified-origin oil premiums in French and German personal care supply chains.
Market Restraints
- Input Cost Volatility:Fertilizer and natural gas price swings directly compress Ukrainian and Russian farmgate seed economics, transmitting margin pressure downstream.
- Supply Concentration Risk:Over 60% of exportable seed originates from Black Sea ports where military disruption and insurance cost spikes fragment shipment reliability.
- Substitution Threat:Palm oil price competitiveness in South Asian frying applications and rapeseed oil expansion in Northern European retail channels constrain sunflower volume growth.
Strategic Opportunities
- Central Asian Seed Development:Kazakhstan and Uzbekistan acreage expansion offers European crushers alternative origination outside conflict-exposed supply basins.
- Bioplastics Feedstock Pivot:High-oleic sunflower oil is integrating into bio-based polymer formulations as EU Green Deal industrial decarbonization mandates tighten petrochemical substitution requirements.
- Direct-to-Refiner Contracting:Bypassing traditional export houses through Turkish and Bulgarian port direct origination agreements captures margin currently absorbed by intermediary traders.
Industry Challenges
- Certification Timeline Compression:EU Deforestation Regulation geolocation traceability requirements demand farm-level GPS documentation that legacy supply chain IT infrastructure cannot deliver.
- Crushing Capacity Relocation:Relocating processing assets from Ukraine to Romania and Bulgaria requires 18-24 month permitting and utility connection timelines that strand seed supply during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sunflower Market |
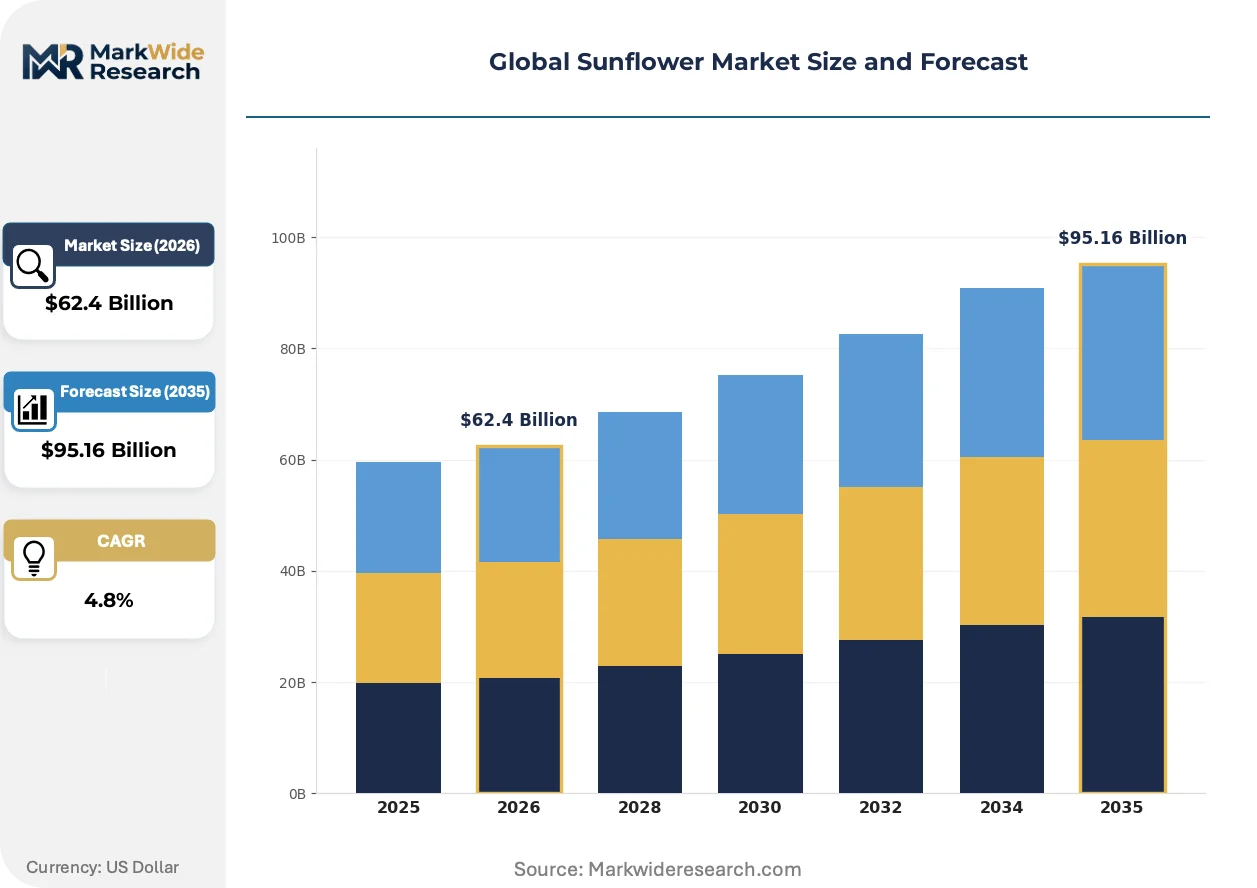
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Seeds, Snacks, Meal End Use Industry: Food & Beverages, Cosmetics, Biofuels, Animal Feed Packaging Type: Bags, Bottles, Cans, Tetra Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Bunge Ltd, Corteva Agriscience, Cargill Incorporated, Syngenta AG, Kernel Holding S.A., Archer Daniels Midland Co, Louis Dreyfus Company B.V., Bayer AG, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sunflower Market Strategic Shifts
Digital traceability infrastructure and oleochemical process innovation are restructuring how seed provenance is verified and how oil fractions are valorized beyond traditional food applications.
Near-infrared spectroscopy is integrating into crush facility intake protocols to assess oil content and moisture in real-time, eliminating laboratory bottlenecks. Romanian and Bulgarian processors deploy these systems to certify seed quality for EU Deforestation Regulation compliance. The technology is integrating farmgate verification with refiner audit requirements, compressing documentation chains from weeks to hours.
REACH chemical registration and EU Green Deal sustainability criteria now mandate cradle-to-gate carbon disclosure for cosmetics-grade refined oil entering French and German personal care markets. This regulatory architecture forces crushers to document energy inputs and transport emissions. German formulators respond by sourcing exclusively from Black Sea corridors with verified low-carbon crushing configurations.
Foodservice operators in Germany and Turkey now specify high-oleic sunflower oil through annual fixed-volume contracts rather than spot market purchases, locking supply security after Black Sea disruption. This procurement consolidation shifts pricing power toward crushers with dedicated origination networks. The pattern is most visible in Istanbul and Frankfurt metropolitan foodservice procurement where volume concentration enables direct refiner relationships.
Global Sunflower Market Segmentation
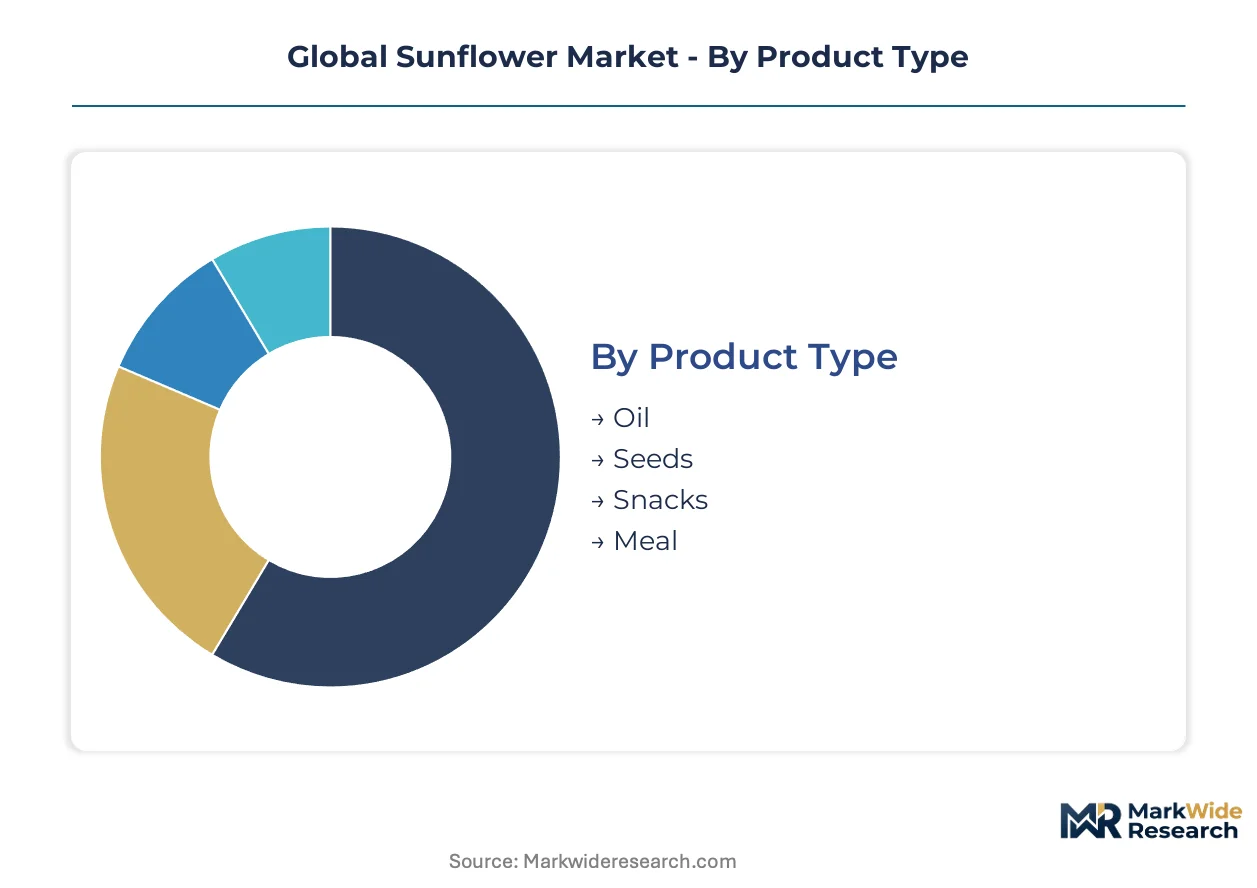
Sunflower market segmentation reveals how value migrates across processing stages and end-use specifications. Buyers prioritize oil content percentages, fatty acid profiles, and origin certifications when selecting between otherwise interchangeable commodity offerings.
Product Type:
Crush economics and downstream margin capture drive processor allocation decisions across product categories.
- Oil:Standard and high-oleic variants dominate commercial flows, with fatty acid composition determining suitability for frying stability or shelf-life extension. European food manufacturers under EFSA trans fat mandates source high-oleic grades from Black Sea crushers, while standard linoleic oil supplies South Asian frying applications where price sensitivity overrides oxidative stability requirements.
- Meal:Protein content ranging from 28-42% depending on dehulling intensity positions sunflower meal as a competitive substitute for soybean meal in Polish and Spanish compound feed rations. Livestock producers value consistent amino acid profiles over price volatility, anchoring crush economics when oil margins compress.
- Seeds:Confectionery-grade seeds with striped hulls and lower oil content serve Turkish and German retail snack channels, commanding premiums over oil-type hybrids.
- Snacks:Roasted kernel products occupy premium shelf space in Istanbul and Frankfurt metropolitan retail, with flavor innovation driving repeat purchase rates.
Volume sits with Oil; growth tilts toward high-oleic specialty grades.
End Use Industry:
Regulatory thresholds and formulation specifications fragment demand across application categories with divergent certification requirements.
- Food & Beverages:Frying, baking, and margarine applications absorb the majority of refined oil flows, with FDA nutrition labeling rules and EFSA trans fat restrictions compelling reformulation toward high-oleic sunflower variants. German foodservice operators now contract annual volumes directly with Black Sea crushers, bypassing spot market exposure.
- Animal Feed:Protein meal demand from Polish and Spanish compound feed manufacturers sustains crush facility operating rates during oil price downturns, providing margin stability through volume consistency.
- Cosmetics:REACH registration and EU Green Deal sustainability criteria mandate cradle-to-gate carbon disclosure for refined oil entering French and German personal care supply chains, creating certified-origin premiums.
- Biofuels:High-oleic oil integrates into bio-based polymer formulations as EU industrial decarbonization mandates tighten petrochemical substitution requirements.
Revenue concentrates in Food & Beverages; certification premiums expand fastest in Cosmetics.
Packaging Type:
Shelf-life requirements and channel economics determine container selection across retail and foodservice segments.
- Bottles:PET and glass containers dominate European retail channels where consumer transparency preferences favor visible product presentation.
- Bags:Flexible packaging serves Turkish and German foodservice bulk procurement, reducing per-unit logistics costs for high-volume frying operations.
- Cans:Metal containers preserve oil quality in extended distribution chains reaching Central Asian markets.
- Tetra Packs:Aseptic cartons capture emerging demand in premium retail segments requiring extended ambient stability.
Foodservice procurement favors Bags; retail premiumization pushes Tetra Pack adoption.
Distribution Channel:
Procurement consolidation and traceability requirements are restructuring how buyers access sunflower products across geographies.
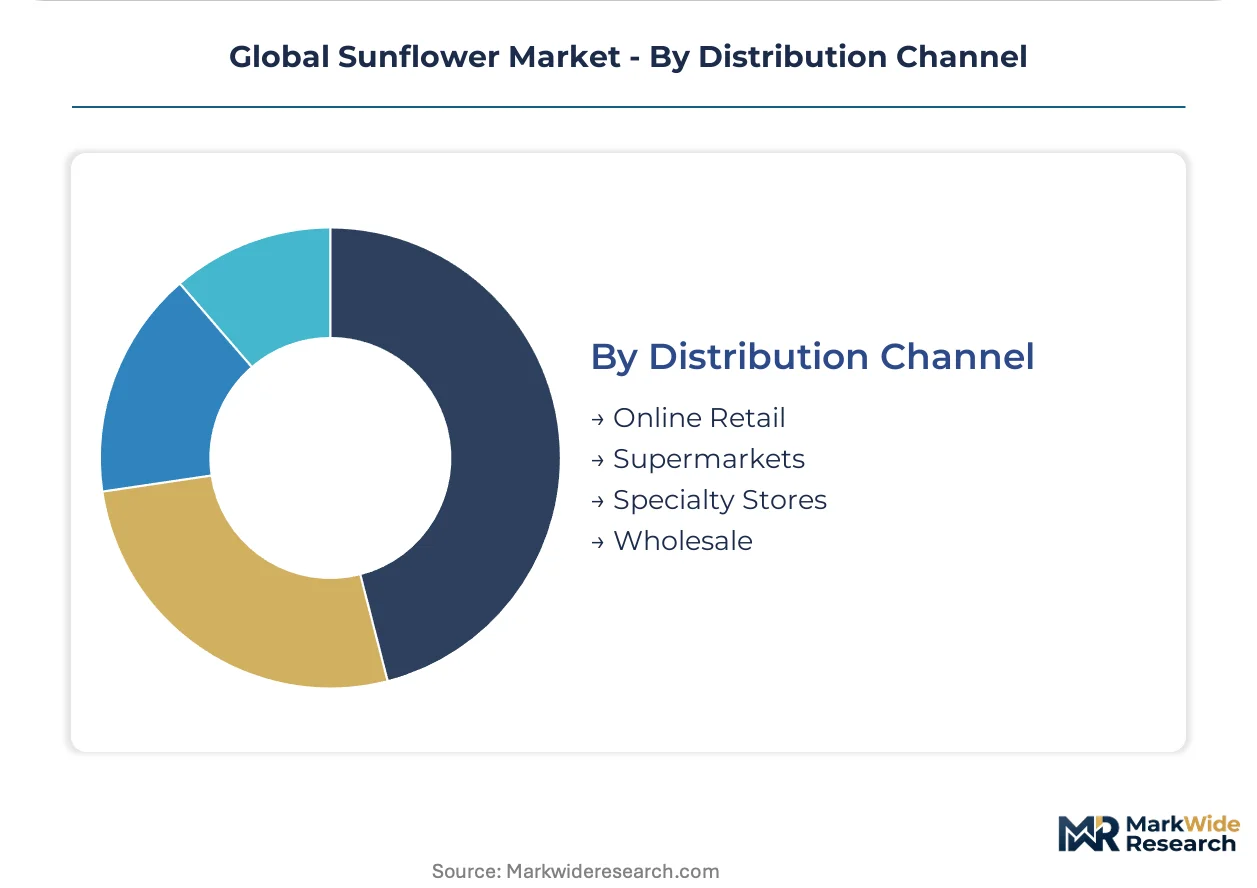
- Wholesale:Direct refiner relationships dominate Istanbul and Frankfurt metropolitan foodservice procurement, with annual fixed-volume contracts replacing spot market exposure after Black Sea supply disruption.
- Supermarkets:German and Turkish retail chains specify origin-certified oils to satisfy EU Deforestation Regulation geolocation requirements, compressing documentation chains from weeks to hours through digital traceability infrastructure.
- Specialty Stores:Confectionery seed and premium roasted kernel products command dedicated shelf space in urban Turkish retail.
- Online Retail:E-commerce channels serve dispersed European consumers seeking specialty high-oleic variants unavailable in conventional retail.
Transaction volume flows through Wholesale; traceability investment concentrates in Supermarket direct sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukrainian sunflower seed harvests anchor Black Sea export flows, though military disruption has rerouted crushing volumes toward Romanian and Bulgarian port infrastructure. Argentine and Turkish processors now capture European refiner demand through expanded origination networks.
Ukraine
Kernel Holding S.A. sustains export volumes through overland rail corridors to Romanian Black Sea terminals after Odessa port closures severed maritime routes. The country's agricultural regulator enforces seed quality certification for EU Deforestation Regulation compliance. Crushing clusters in Dnipropetrovsk and Odessa oblasts have relocated processing assets westward toward Lviv railheads.
Russia
Rostov-on-Don and Krasnodar Krai crushing facilities supply high-oleic oil to German foodservice operators under annual fixed-volume contracts. EFSA trans fat restrictions on imported refined products shape formulation specifications for cross-border shipments. Volgograd processors are expanding storage silo capacity to buffer against export insurance cost volatility.
Argentina
Buenos Aires province crushers supply European refiners seeking alternative origination outside Black Sea supply basins. The national agricultural agency administers export registration protocols aligned with EU sustainability disclosure requirements. Rosario port terminals are upgrading loading infrastructure to accommodate larger Panamax vessels for Atlantic crossings.
Turkey
Istanbul metropolitan foodservice procurement now specifies direct refiner relationships bypassing traditional export houses. The Turkish Ministry of Agriculture imposes origin documentation standards for re-export consignments to Middle Eastern markets. Trakya region crushing plants leverage Danube River barge connections to access Romanian and Bulgarian seed supplies.
Romania
Constanta port terminals absorb redirected Ukrainian seed cargoes through expanded unloading and storage capacity. REACH chemical registration requirements govern cosmetics-grade oil re-exports to French and German personal care manufacturers. Danube Delta crushing corridors are integrating near-infrared spectroscopy systems for real-time seed quality verification.
Global Sunflower Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue Central Asian origination partnerships and bio-based polymer feedstock certification. Black Sea supply concentration has stratified the vendor base into three functional tiers: integrated trading houses with captive crushing assets, regional processors with port-adjacent logistics, and seed technology developers licensing high-oleic hybrids. Dominant competitive moves include backward integration into farmgate origination networks and geographic expansion into Kazakh and Uzbek acreage development.
Among integrated trading houses, Bunge Ltd, Cargill Incorporated, and Kernel Holding S.A. exemplify the asset-heavy archetype that anchors European oil deliveries through Danube River and overland rail corridors. These entities occupy positions where crushing capacity relocation and alternative route development determine supply security for downstream refiners.
| Leading Market Players |
|---|
| Bunge Ltd |
| Corteva Agriscience |
| Cargill Incorporated |
| Syngenta AG |
| Kernel Holding S.A. |
| Archer Daniels Midland Co |
| Louis Dreyfus Company B.V. |
| Bayer AG |
| Wilmar International Limited |
| Others |
Value Chain & Pricing Dynamics
EU Deforestation Regulation geolocation traceability requirements gate qualified supply access and premium-tier pricing for European refiners sourcing Black Sea sunflower oil. Crushers lacking farm-level GPS documentation face exclusion from German and French foodservice contracts, compressing margins to spot-market levels while certified-origin suppliers capture structured premiums.
Pricing Analysis
Service bundling separates contract-based annual volume agreements from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price differentiation intensifies as high-oleic specialty grades command premiums under FDA and EFSA trans fat mandates, while standard linoleic oil faces cost compression from palm oil substitution in South Asian frying applications. Polish compound feed manufacturers exhibit highest price sensitivity due to meal margin volatility, whereas German cosmetics formulators show lowest sensitivity given REACH compliance requirements.
Supply Chain Analysis
Seed supply rests on Ukrainian and Russian farmgate production, with Kazakhstan and Uzbekistan emerging as alternative origination basins. Fertilizer inputs, natural gas for drying, and maritime insurance coverage constitute critical dependencies. Single-source vulnerability concentrates in Black Sea port infrastructure where military disruption fragments shipment reliability. Distribution runs through Danube River barge networks and overland rail corridors to Romanian and Bulgarian crushing terminals, bypassing traditional maritime routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy deployment for real-time seed quality verification is displacing legacy laboratory-based intake protocols across Black Sea crushing facilities. This technology transition compresses certification timelines from weeks to hours, restructuring competitive advantage toward processors with integrated digital traceability infrastructure.
For Market Incumbents: Deploy backward integration into Central Asian farmgate origination networks to hedge Black Sea concentration risk. Bunge Ltd and Cargill Incorporated exemplify asset-heavy positioning through Danube River crush assets and overland rail corridor development. Kernel Holding S.A. sustains volume through alternative route investment, demonstrating how captive logistics infrastructure defends margin position against spot-market volatility. For New Entrants and Emerging Players: Launch via direct-to-refiner contracting models bypassing traditional export house intermediaries. Turkish and Bulgarian port-adjacent processors capture margin currently absorbed by traders through annual fixed-volume agreements with Frankfurt and Istanbul metropolitan foodservice operators. White-space concentration sits in cosmetics-grade refining for French and German personal care supply chains, where REACH registration and EU Green Deal sustainability criteria create certified-origin premium capture opportunities. For Investors and Strategic Acquirers: Crushing capacity relocation announcements into Romania and Bulgaria signal the leading indicator that supply chain reconfiguration is accelerating. Long-term viability favors processors with integrated origination networks spanning Ukrainian, Kazakh, and Uzbek acreage development. Acquisition targets should display dual capability in high-oleic hybrid licensing and digital traceability infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Central Asian Seed Development Partnership | Kazakhstan and Uzbekistan acreage expansion diversifies origination outside conflict-exposed Black Sea basins. |
| Digital Traceability Infrastructure Deployment | Near-infrared spectroscopy integration compresses EU Deforestation Regulation documentation from weeks to hours. |
| Direct-to-Refiner Contracting Model | Annual fixed-volume agreements with German foodservice operators capture margin from intermediary traders. |
| High-Oleic Hybrid Technology Licensing | Corteva Agriscience and Syngenta AG seed development supports FDA and EFSA trans fat reformulation demand. |
| Danube River Logistics Corridor Expansion | Bulgarian and Romanian port infrastructure absorbs redirected Ukrainian seed cargoes through barge connectivity. |
Study Parameters
Multi-period observation of crushing capacity utilization, seed origin certification adoption, and refiner procurement contract structures anchored the trend analysis, supplemented by interviews with crushing facility operations managers, agricultural commodity traders, compound feed procurement leads at Polish and Spanish manufacturers, and cosmetics formulators in France and Germany. Secondary validation drew from customs and trade data, EFSA regulatory filings, EU Deforestation Regulation implementation guidance, and SEC 10-K disclosures from integrated trading houses. Bottom-up volume modeling across seed intake, oil extraction yields, and meal offtake triangulated against top-down market value estimates.
Segment-weighting across product type, end-use industry, and regional production hub dimensions structured the analytical framework across the projection horizon. Oil, meal, seeds, and snacks categories were modeled with differential margin capture assumptions. High-oleic versus standard linoleic fatty acid profiles, dehulling intensity for protein content variation, and confectionery-grade versus oil-type hybrid specifications provided industry-specific forecast inputs. CAGRs were derived from trend extrapolation adjusted for regulatory mandate implementation timelines and trade flow reconfiguration patterns.
The model assumes a particular technology adoption path for digital traceability infrastructure; alternative pathways for farm-level GPS documentation and near-infrared spectroscopy deployment would alter the outlook for certification timeline compression and premium-tier pricing access. Forecasts reflect assumptions regarding Black Sea port operational continuity, EU Deforestation Regulation enforcement intensity, and Central Asian acreage expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Garlic Chive Seeds Market
Seeds
Sweet Corn Seeds Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Drought Tolerant Seeds Market
Seeds
Psyllium Seed Market
Seeds
Global Onion Seed Market
Seeds
Hemp Seeds Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Europe Cannabis Seeds Market
Seeds
Americas Seeds Market
Seeds
Pumpkin Seeds Market
Seeds
Poppy Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Global Forage Seeds Market
Seeds
South America Seed Market
Seeds
Cherry Tomato Seeds Market