
 Pumpkin Seeds Market | 2026-2036
Pumpkin Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Pumpkin Seeds Market Intelligence
Sunflower seed oil is hardening as a cost benchmark, pressuring pumpkin seed processors to defend margin through oil-content differentiation and yield optimization. South GA Seed Company leverages its southeastern US growing base to sustain year-round germplasm availability for commercial buyers. Johnny's Selected Seeds anchors the heirloom and organic niche with varietal purity protocols that command contract premiums. Siegers Seed Company competes on processing scale, operating dedicated hulling and roasting lines that reduce third-party tolling dependency.
Pumpkin seeds are the dried, hulled or unhulled kernels of Cucurbita pepo and related species, typically containing 35-50% oil by weight and 25-30% protein, with cold-press extraction yielding virgin culinary oil and press cake for feed or flour applications. Their primary commercial purpose spans direct consumption, oil extraction, and ingredient supply to packaged food and nutraceutical formulators. The organic product type captures expanding shelf space as retailers impose non-GMO verification requirements that conventional lots struggle to meet. Snack manufacturers represent the fastest-growing end user category, though health stores still occupy the highest margin pool per kilogram due to supplement-grade pricing. Bulk packaging dominates food-service procurement, while vacuum packs are displacing tins in retail channels seeking extended shelf life without preservative additives.
The USDA organic seal and EU organic regulation shape import eligibility, with third-country equivalency determinations gatekeeping market access for non-US origin supply. FDA food facility registration and FSMA preventive controls apply to roasted and flavored product lines, raising compliance costs for small hullers without in-house quality systems. Stakeholders must monitor how evolving allergen labeling thresholds and prop 65 litigation risk in California reshape formulation and origin documentation requirements.
Market Dynamics
The EU Green Deal's tightening organic certification standards are forcing importers to restructure sourcing networks, while sunflower seed oil's cost benchmark pressures processors to differentiate through oil-content optimization rather than price competition.
Growth Catalysts
- EU organic regulation equivalency requirements:Third-country suppliers investing in certification infrastructure gain preferential shelf-space access at German and Austrian retailers prioritizing non-GMO verification.
- Snack manufacturer portfolio expansion:Functional food formulators are embedding pumpkin seed protein isolates into energy bars and plant-based meat analogues, creating pull-through for hulling capacity.
- Cold-press extraction technology:Virgin culinary oil production is capturing premium positioning in health stores, with press cake co-products feeding adjacent feed and flour markets.
Market Restraints
- Input cost volatility:Fertilizer and irrigation energy costs in southeastern US growing regions compress margins for germplasm suppliers without captive acreage.
- Supply concentration risk:Styrian hulling infrastructure dominates EU processing capacity, creating bottleneck vulnerability for organic lots requiring specialized handling.
- Substitution threat:Sunflower seed oil's price advantage in bulk food-service procurement limits pumpkin seed oil penetration in cost-sensitive frying applications.
Strategic Opportunities
- Underpenetrated nutraceutical channel:Supplement-grade pricing in Japanese and South Korean health stores remains underserved by current export-focused processors.
- Emerging bakery application:German muesli and artisan bread segments are specifying hull-free kernels for texture consistency, rewarding varietal purity investments.
- USDA organic seal tailwind:California's Proposition 65 litigation environment is accelerating retailer demand for certified origin documentation that organic handlers can supply.
Industry Challenges
- Allergen labeling threshold compliance:FSMA preventive controls require small hullers to implement in-house quality systems that strain capital reserves.
- Capex intensity of dedicated roasting lines:In-house processing equipment demands exceed the financing capacity of regional seed companies dependent on third-party tolling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pumpkin Seeds Market |
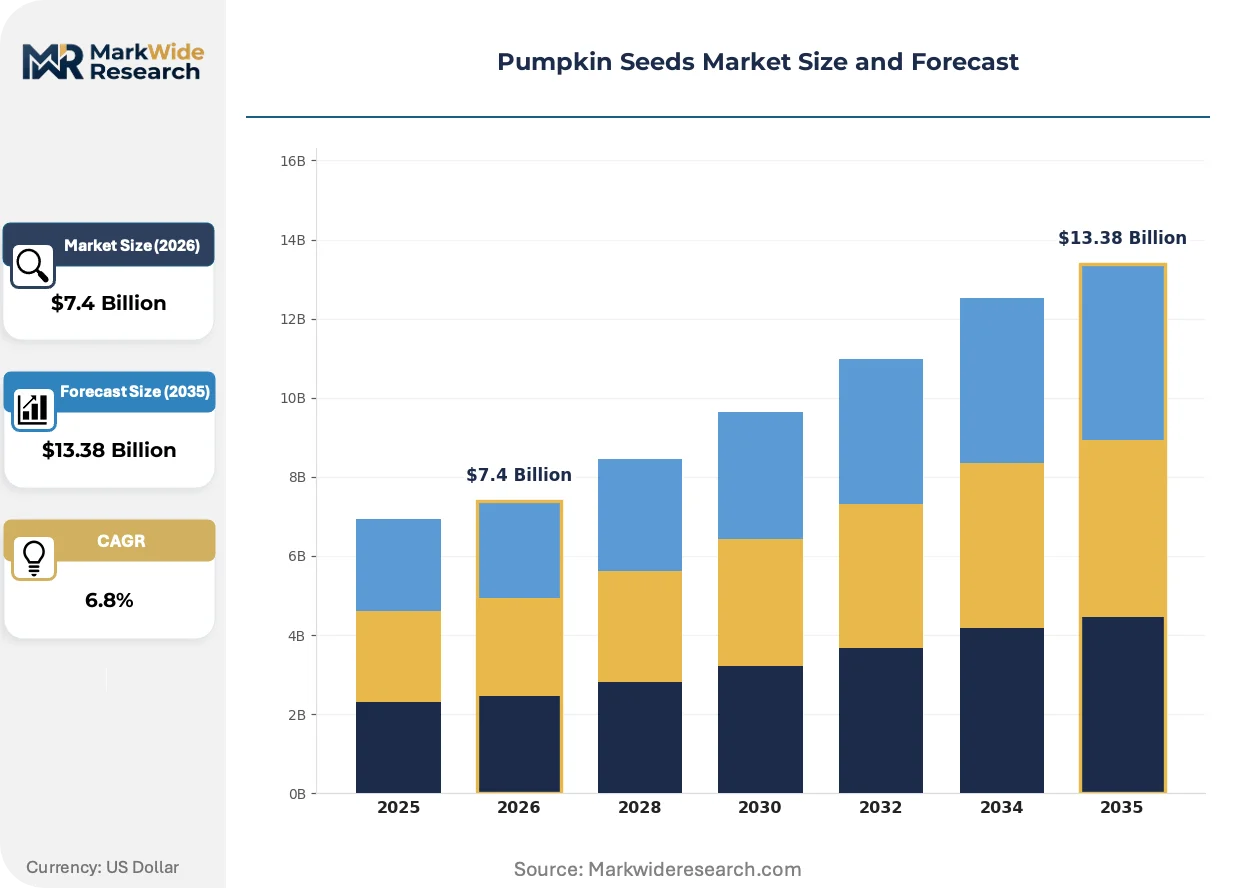
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw, Roasted, Flavored, Organic End User: Food Industry, Snack Manufacturers, Health Stores, Retailers Packaging Type: Bags, Tins, Vacuum Packs, Bulk Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | South GA Seed Company, St. Croix Growers Association, Holmes Seed Company, Johnny's Selected Seeds, Siegers Seed Company, Harris Seeds, Wallace's Whoppers, Burpee Seeds, Clifton Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pumpkin Seeds Market Strategic Shifts & Innovations
Vacuum packaging technology is displacing traditional tin formats across retail channels, while regulatory divergence between FDA and EU organic frameworks is fragmenting import documentation requirements. These shifts are compressing legacy supply chain configurations.
Cold-press extraction equipment with nitrogen blanketing is overtaking conventional mechanical pressing in premium oil production. Health store buyers and culinary oil bottlers in Germany and Austria are specifying oxygen-minimized processing to extend shelf life without synthetic antioxidants. This technology is enabling processors to command contract premiums that conventional extraction cannot match.
REACH chemical safety assessments and EFSA novel food consultations are extending approval timelines for pumpkin seed protein isolates in EU functional foods. The industrial consequence is delayed market entry for new ingredient suppliers, with established handlers leveraging existing registrations. Organic-certified isolates face the tightest scrutiny, diverting investment toward US FDA GRAS self-affirmation pathways.
Health store buyers are consolidating procurement around suppliers offering dual organic and non-GMO verification, displacing conventional lot acceptance. This certification-driven preference shift concentrates volume with handlers investing in third-party audit infrastructure. The pattern is most visible in California and Pacific Northwest retail clusters where retailer compliance departments enforce strict documentation standards.
Pumpkin Seeds Market Segmentation
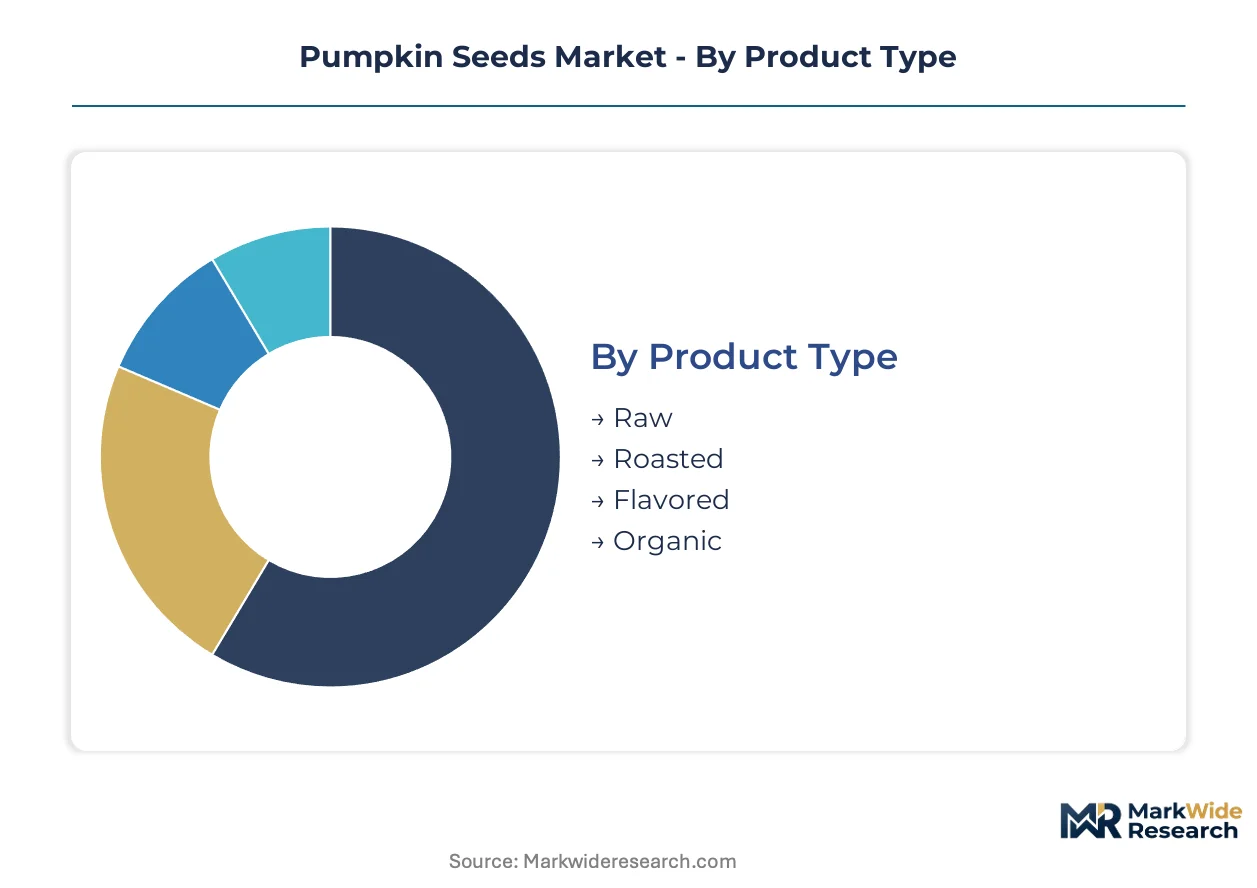
Pumpkin seed procurement splits sharply between commodity bulk channels and premium certified lots. Understanding where volume concentrates versus where margins accumulate shapes portfolio allocation for processors and handlers.
Product Type:
Raw seeds dominate tonnage flows while roasted and organic variants capture value extraction.
- Raw:Unprocessed kernels with 35-50% oil content serve as feedstock for cold-press extraction operations and ingredient supply to food manufacturers. Demand concentrates in Styrian hulling clusters where processors lack in-house roasting capacity but maintain organic certification infrastructure.
- Organic:USDA seal and EU organic regulation compliance command shelf-space access at German retailers enforcing non-GMO verification. California's Proposition 65 litigation environment accelerates retailer demand for certified origin documentation that organic handlers can supply.
- Roasted:Dedicated thermal processing lines add flavor development and shelf stability for direct consumption channels.
- Flavored:Seasoning applications target snack manufacturer portfolios with functional food positioning.
Mature deployment sits with Raw. Newer deployment is concentrated in Organic.
End User:
Snack manufacturers are expanding procurement fastest while health stores defend the highest margin pool per kilogram.
- Snack Manufacturers:Functional food formulators embed pumpkin seed protein isolates into energy bars and plant-based meat analogues, creating pull-through for hulling capacity. German and Austrian retail clusters prioritize suppliers offering dual organic and non-GMO verification.
- Health Stores:Supplement-grade pricing in Japanese and South Korean channels remains underserved by export-focused processors. Virgin culinary oil production captures premium positioning with oxygen-minimized processing specifications.
- Food Industry:Bakery and muesli applications in Germany specify hull-free kernels for texture consistency.
- Retailers:Vacuum packaging displacement of tin formats extends shelf life without preservative additives.
Volume leadership belongs to Food Industry. Margin extraction concentrates in Health Stores.
Packaging Type:
Bulk formats serve food-service procurement while vacuum technology reshapes retail shelf presence.
- Bulk:Food-service and ingredient supply channels favor unpackaged kernel delivery for cost minimization in high-volume frying and baking applications.
- Vacuum Packs:Nitrogen blanketing technology extends shelf life without synthetic antioxidants, enabling processors to command contract premiums that conventional extraction cannot match.
- Bags:Flexible packaging dominates conventional retail channels with lower barrier properties.
- Tins:Traditional metal formats face displacement as vacuum packs gain share in extended-shelf-life positioning.
Cost-sensitive procurement favors Bulk. Premium positioning is accelerating in Vacuum Packs.
Distribution Channel:
Wholesale intermediaries still handle most tonnage while direct sales build traceability premiums.
- Wholesale:Aggregators consolidate fragmented huller output for onward supply to snack manufacturers and food industry formulators lacking direct farm relationships.
- Online:E-commerce platforms enable health store buyers to consolidate procurement around dual-certified suppliers with third-party audit infrastructure.
- Retail Stores:Physical shelf space allocation increasingly hinges on organic seal presence and non-GMO verification documentation.
- Direct Sales:Captive relationships between Styrian processors and German bakery chains reduce intermediary margin extraction.
Established volume flows through Wholesale. Channel expansion is climbing the fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany anchors premium pumpkin seed procurement through bakery and muesli applications. Styrian hulling clusters in Austria concentrate EU organic processing capacity. Japanese and South Korean health stores command supplement-grade pricing that export-focused processors struggle to serve.
United States
Southeastern growing regions sustain year-round germplasm availability for commercial buyers. FDA food facility registration and FSMA preventive controls raise compliance costs for small hullers lacking in-house quality systems. South Georgia seed operations supply raw feedstock to Styrian processors seeking non-EU organic origin.
Germany
Retailers enforce non-GMO verification requirements that conventional lots fail to meet. EU Green Deal organic certification standards tighten input requirements for imported seeds. Munich and Hamburg distribution hubs consolidate procurement for artisan bread segments specifying hull-free kernel texture.
Austria
Styrian hulling infrastructure dominates EU organic processing capacity for specialized handling. EFSA novel food consultations delay pumpkin seed protein isolate approvals for functional food formulators. Graz-area processors operate dedicated roasting lines reducing third-party tolling dependency.
Japan
Health store buyers consolidate procurement around dual organic and non-GMO verification suppliers. METI import standards shape eligibility for virgin culinary oil positioning. Tokyo and Osaka retail clusters enforce strict documentation standards that organic handlers can supply.
South Korea
Supplement-grade pricing in Seoul health stores remains underserved by current export-focused processors. MFDS food safety assessments extend approval timelines for new ingredient suppliers. Busan import gateways channel vacuum-packed retail formats displacing traditional tin packaging.
Pumpkin Seeds Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments. The vendor base clusters around germplasm suppliers, hulling processors, and retail-facing seed companies. Three archetypes dominate: southeastern US growing-base operators, Styrian hulling-scale processors, and heirloom-certified niche specialists. Capacity expansion and certification infrastructure investment represent the primary competitive moves as margin pressure intensifies.
Among US-based germplasm suppliers, South GA Seed Company and Johnny's Selected Seeds occupy distinct positioning archetypes. South GA Seed Company leverages its southeastern growing base to sustain year-round commercial availability. Johnny's Selected Seeds anchors the heirloom and organic niche with varietal purity protocols commanding contract premiums. Siegers Seed Company exemplifies the processing-scale archetype through dedicated hulling and roasting lines.
| Leading Market Players |
|---|
| South GA Seed Company |
| St. Croix Growers Association |
| Holmes Seed Company |
| Johnny's Selected Seeds |
| Siegers Seed Company |
| Harris Seeds |
| Wallace's Whoppers |
| Burpee Seeds |
| Clifton Seed Company |
| Others |
Cost & Logistics Intelligence
Styrian hulling technician concentration in Graz-area processing clusters anchors labor-cost differentials that widen spreads between commodity raw kernels and certified organic lots. EU organic regulation compliance premiums reflect this specialized workforce scarcity, with German bakery buyers absorbing tiered labor premiums for hull-free kernel consistency.
Pricing Analysis
Volume leadership sits with raw seed bulk channels while margin extraction concentrates in certified organic and cold-press oil tiers. Three-tier pricing structure across premium organic, standard conventional, and economy feed-grade lots tracks certification burden and oil-content verification. Pricing pressure stems from sunflower seed oil's cost benchmark in food-service frying applications, compressing pumpkin seed oil penetration. Snack manufacturers exhibit highest price sensitivity due to formulation cost targets, while health store buyers absorb premium positioning for supplement-grade isolates.
Supply Chain Analysis
Dual-sourcing requirements from German retailers mandate multi-supplier qualification across Styrian hullers and southeastern US germplasm operators. Geographic supply concentration centers on Austria for EU organic processing, the United States for year-round germplasm availability, and China for hulling equipment components. Raw material dependencies include nitrogen fertilizers, irrigation energy, and specialized roasting line components. Single-source vulnerability runs through Styrian organic hulling infrastructure for specialized handling. Distribution runs through wholesale aggregators consolidating fragmented huller output for onward supply to snack manufacturers and bakery formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal organic certification tightening is forcing consolidation as smaller hullers lack capital reserves for in-house quality system investments. Weaker players without captive acreage or tolling independence face margin compression exit pressure.
For Market Incumbents: Acquire dedicated roasting and hulling capacity to eliminate third-party tolling dependency and defend margin against Styrian processor bottleneck vulnerability. Secure backward integration into southeastern US germplasm supply through contract acreage or seed company partnerships. Expand nitrogen-blanketed cold-press extraction lines to capture health store premium positioning that conventional extraction cannot match. For New Entrants and Emerging Players: Capture underpenetrated Japanese and South Korean health store channels where supplement-grade pricing exceeds current export-focused processor service levels. Target German artisan bakery segments specifying hull-free kernel texture consistency with varietal purity protocols. Enter through direct sales relationships reducing wholesale intermediary margin extraction. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale processors possessing dual organic and non-GMO certification infrastructure given California Proposition 65 litigation tailwinds accelerating retailer documentation demands. Long-term viability favors handlers with integrated hulling-roasting-oil extraction capabilities across the 5-10 year window. Monitor EFSA novel food consultation timelines for pumpkin seed protein isolate approvals as inflection indicator for functional food ingredient demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | USDA organic seal and EU organic regulation compliance unlocks German retailer shelf-space access. |
| Cold-Press Extraction Scale-Up | Nitrogen blanketing technology commands contract premiums from Austrian and German health store buyers. |
| Backward Integration into Germplasm | Southeastern US growing base capture reduces input cost volatility from fertilizer and irrigation energy. |
| Direct Sales Channel Development | Captive relationships with Munich and Hamburg bakery chains eliminate wholesale margin extraction. |
| Vacuum Packaging Technology Deployment | Nitrogen blanketing extends shelf life without synthetic antioxidants, displacing traditional tin formats. |
Research Approach
Independent corroboration across hulling processor executives, organic certification auditors, German bakery procurement leads, and snack manufacturer formulators underwrites the qualitative findings. Primary interviews with Styrian processing operators, southeastern US germplasm suppliers, and health store category buyers combined with secondary validation from USDA organic certification databases, EU TRACES import documentation, FDA food facility registration records, and customs trade data. Bottom-up volume builds from hulling capacity and acreage estimates triangulated against top-down retail scanner data.
Rate-of-change decomposition across the analysis window segments volume and value by product type, end user, packaging format, and distribution channel. CAGRs derive from modeled progression of organic certification penetration, cold-press extraction capacity expansion, and snack manufacturer protein isolate adoption. Forecast inputs incorporate EU Green Deal implementation timelines, EFSA novel food consultation trajectories, and Proposition 65 litigation frequency patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU organic regulation equivalency determinations and sunflower seed oil price volatility. Deviation in Styrian hulling infrastructure availability or EFSA approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Australia Oilseed Market
Seeds
Vegetable Seed Protein Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Celery Seed Oil Market
Seeds
Dragon Fruit Seeds Market
Seeds
Asparagus Seeds Market
Seeds
Russia Seed Market
Seeds
Europe Forage Seed Market
Seeds
Flower Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Global Seed Market
Seeds
Americas Seeds Market
Seeds
Uganda Seeds Market
Seeds
Field Crop Seeds Market