
 Seed Cracker Market | 2026-2036
Seed Cracker Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Cracker Market Analytics
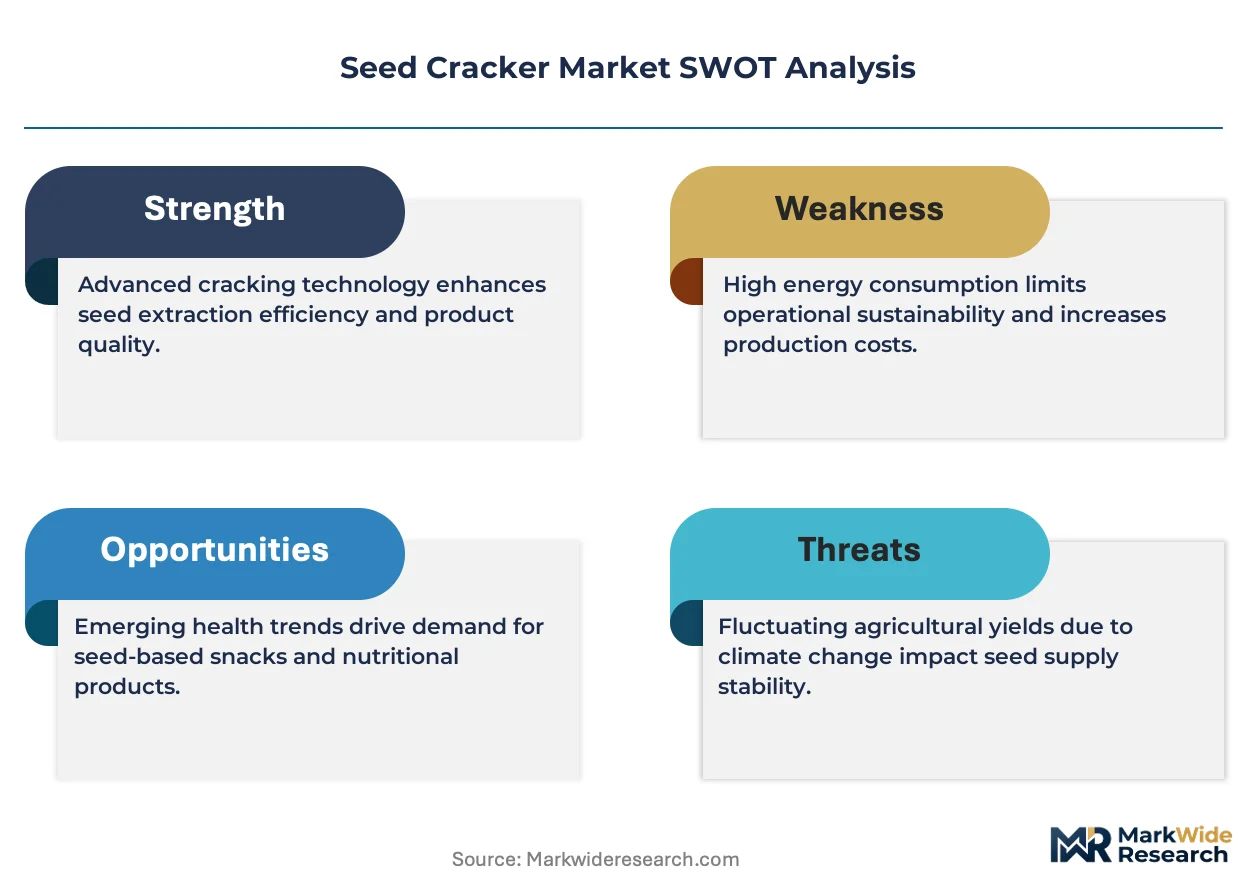
REACH compliance is rebalancing the cost-of-entry calculus for European seed cracker manufacturers, forcing reformulation of coating agents and packaging substrates. Mary's Gone Crackers leverages its organic supply chain to sustain premium positioning across North American natural grocery channels. Simple Mills anchors its competitive edge through grain-free ingredient architecture, while Crunchmaster dominates the gluten-free mass-market segment with scaled manufacturing.
A seed cracker is a flat, baked crisp composed of milled seeds, grains, and binding agents, typically ranging from 1-3 millimeters in thickness and achieving moisture content below 5% through convection or hybrid baking processes; its primary commercial purpose is to serve as a shelf-stable, nutrient-dense carrier for spreads and toppings in both retail and foodservice channels. Stainless steel equipment configurations lead the material type segment due to sanitation mandates in commercial bakeries, while electric crackers command the product type category as automated throughput replaces manual batch processing in food processor facilities. Online stores represent the fastest-growing distribution channel, though retail outlets still occupy the dominant share of household user transactions.
The FDA governs nutritional labeling and allergen declarations for US seed cracker producers, while the EU Green Deal shapes carbon accounting requirements for imported oilseeds and packaging materials. BIS certification in India affects equipment standards for industrial cracker lines exported to South Asian food processors. Stakeholders must monitor how evolving Extended Producer Responsibility frameworks in the European Union and emerging state-level packaging laws in California reshape material sourcing decisions and equipment upgrade cycles.
Market Dynamics
Clean-label reformulation is compressing conventional ingredient sourcing windows as EU Green Deal packaging mandates force immediate substrate transitions across European seed cracker manufacturing.
Growth Catalysts
- EU Green Deal carbon accounting:Imported oilseed traceability requirements are accelerating certified organic supply chain investments among food processors seeking premium market access.
- Convection baking automation:Hybrid thermal systems are reducing moisture variability below 5% thresholds, enabling shelf-life extension without chemical preservatives.
- German artisanal consumption clusters:Regional density of clean-label households anchors volume concentration for heritage seed varieties in Central European distribution networks.
Market Restraints
- REACH coating agent reformulation:ECHA substance restrictions on conventional anti-stick compounds force costly binder redevelopment cycles for established manufacturers.
- Stainless steel equipment concentration:Sanitation-mandated capital intensity in commercial bakeries creates entry barriers for mid-scale processors lacking scale economies.
- Gluten-free flour substitution threat:Alternative crisp categories using legume bases compete directly for carrier-function shelf space in natural grocery channels.
Strategic Opportunities
- California state packaging laws:Extended Producer Responsibility frameworks create first-mover advantage for compostable substrate innovators supplying West Coast retail chains.
- Online direct-to-household channels:E-commerce fulfillment infrastructure enables subscription-model penetration beyond conventional retail outlet density constraints.
- Grain-free architecture convergence:Binding agent innovations combining aquafaba with milled chia are opening formulation white space outside conventional wheat-adjacent positioning.
Industry Challenges
- Clean-label certification timelines:USDA Organic and Non-GMO Project verification queues create 12-18 month product launch delays for reformulated lines.
- Legacy equipment integration:Electric cracker automation retrofits into existing convection lines require specialized controls engineering scarce in regional labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Cracker Market |
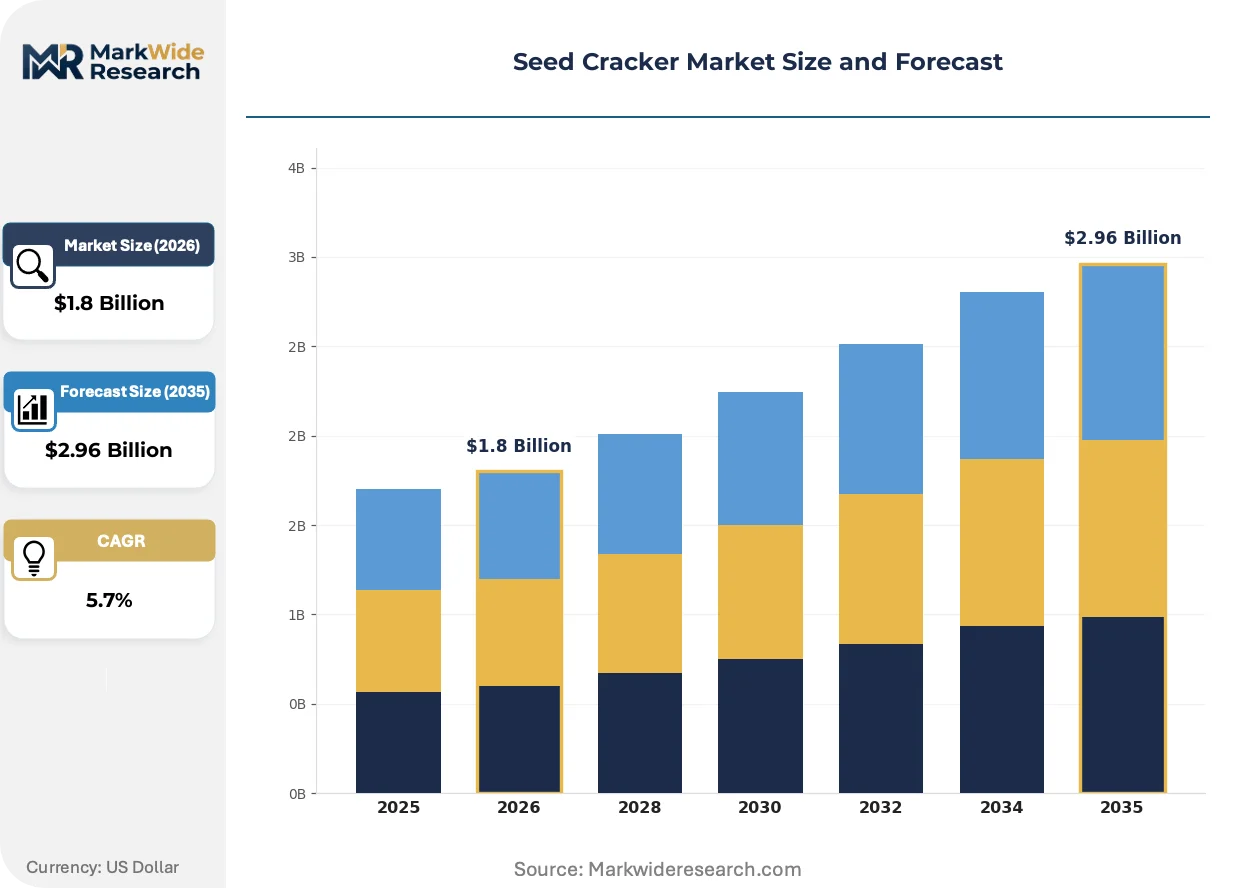
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Crackers, Electric Crackers, Portable Crackers, Industrial Crackers End User: Farmers, Food Processors, Retailers, Household Users Material Type: Stainless Steel, Plastic, Aluminum, Wood Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Others |
| Companies Covered | Mary's Gone Crackers, Simple Mills, Crunchmaster, Back to Nature, Finn Crisp, Blue Diamond Almonds, Good Thins, Late July, Kii Naturals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Cracker Market Evolving Landscape
Active thermal processing advances and binding chemistry breakthroughs are compressing traditional batch-cycle durations while regulatory substrate mandates force material science pivots across equipment and packaging tiers.
Hybrid convection-infrared baking systems are automating moisture extraction uniformity across variable seed density loads. Mid-scale food processors in the Upper Midwest are retrofitting existing lines with radiant top-surface modules to achieve sub-5% moisture targets without extending dwell time. This automation is compressing throughput differentials between manual batch and continuous-flow configurations.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating conventional non-stick coating options for cracker-forming dies. European manufacturers face immediate tooling replacement cycles as ECHA substance evaluation timelines accelerate. German equipment suppliers are responding with ceramic-composite die surfaces certified for direct food contact under EFSA migration limits.
Subscription-based household replenishment is displacing conventional retail pantry-loading patterns among clean-label consumers. Direct-to-door fulfillment platforms are capturing repeat-purchase loyalty previously anchored by natural grocery aisle placement. This channel rotation is most pronounced in coastal US metropolitan markets where delivery density supports cold-chain-free distribution economics.
Seed Cracker Market Segmentation
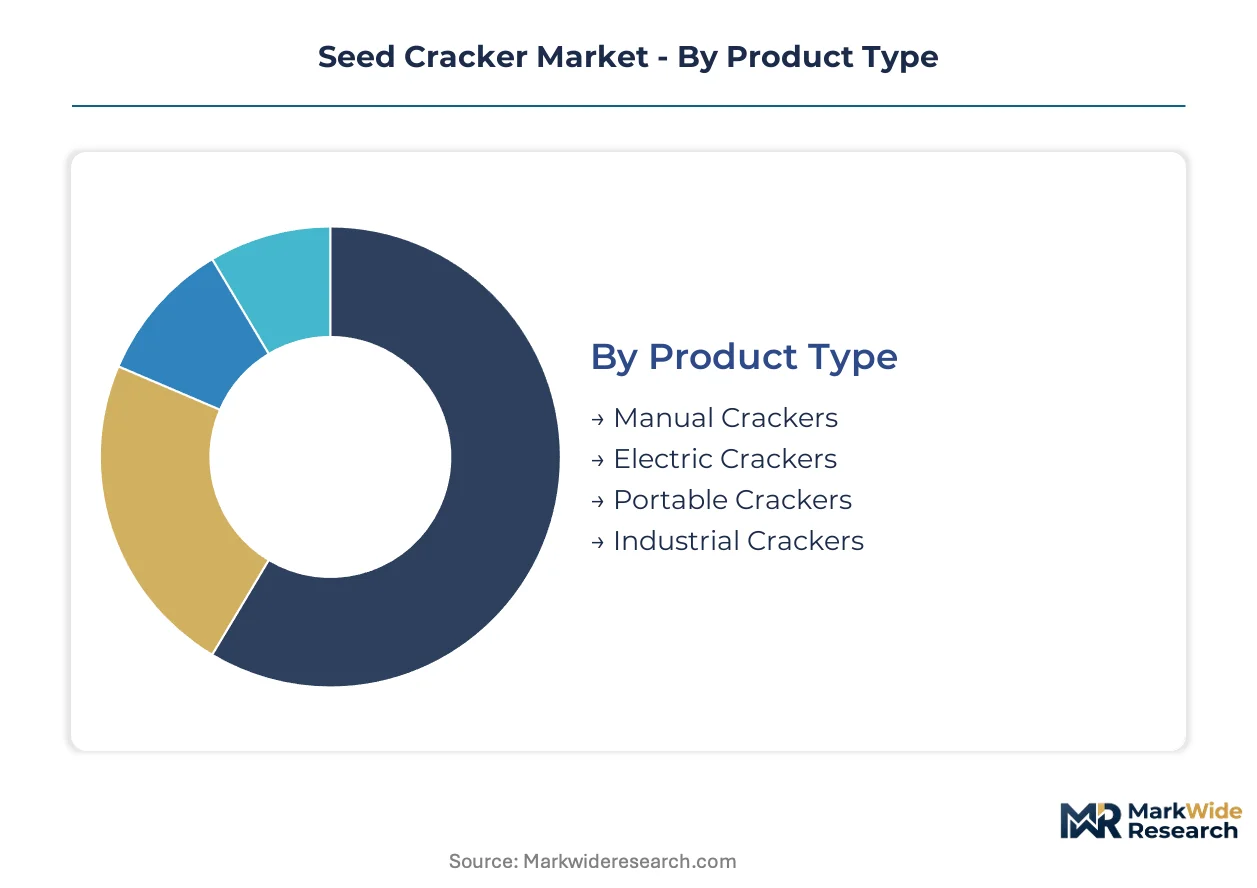
Seed cracker manufacturers configure product lines around throughput requirements and sanitation mandates. Equipment material choices and distribution pathways determine margin capture across food processor and household channels.
Product Type:
Food processors prioritize throughput consistency and labor reduction when selecting cracker equipment tiers.
- Electric Crackers:Automated batch and continuous-flow systems deploy precision motor drives and programmable thermal controls to achieve sub-5% moisture targets. Demand concentrates among North American food processors replacing legacy manual lines to meet clean-label shelf-life requirements without chemical preservatives. These units anchor volume concentration in commercial bakeries scaling gluten-free and grain-free production.
- Manual Crackers:Hand-operated lever or screw mechanisms process small seed batches for artisanal producers and test-kitchen environments. German craft bakeries and heritage seed cooperatives sustain demand for mechanical simplicity and equipment portability absent electrical infrastructure requirements.
- Portable Crackers:Compact, mobile units serve on-farm processing and remote foodservice applications where fixed-line installation proves uneconomical.
- Industrial Crackers:High-capacity continuous lines integrate convection, infrared, and hybrid thermal modules for mass-scale output.
Electric crackers lead on scale; portable crackers lead on momentum as on-farm processing expands.
End User:
Volume concentration follows supply chain position from raw seed handling through packaged goods distribution.
- Food Processors:Commercial bakeries and co-manufacturing facilities operate electric and industrial cracker lines at scale. These stakeholders drive equipment upgrade cycles as EU Green Deal packaging mandates and FDA nutritional labeling requirements force reformulation investments.
- Farmers:Direct seed processing for value-added sales and cooperative supply contracts. On-farm cracker adoption accelerates where regional organic certification programs create premium market access for processed goods.
- Retailers:Private-label seed cracker programs require dedicated processing partnerships or captive production facilities.
- Household Users:Small-batch manual and electric units serve home-based clean-label snacking preparation.
Food processors lead on scale; farmers lead on momentum as vertical integration into seed processing spreads.
Material Type:
Sanitation standards and capital intensity differentiate material selection across production tiers.
- Stainless Steel:Food-grade 304 and 316 alloys dominate commercial bakery configurations due to FDA and EFSA sanitation mandates. The material withstands caustic washdown cycles and prevents microbial harborage in continuous production environments. Equipment concentration in this tier creates entry barriers for mid-scale processors lacking depreciation scale.
- Plastic:Polymer composites serve portable and entry-level household units where cost minimization outweighs thermal durability requirements.
- Aluminum:Lightweight alloys balance thermal conductivity with equipment portability for mid-scale food processors.
- Wood:Traditional material persists in heritage craft production and display-oriented retail presentations.
Stainless steel leads on scale; aluminum leads on momentum as weight-reduction priorities spread.
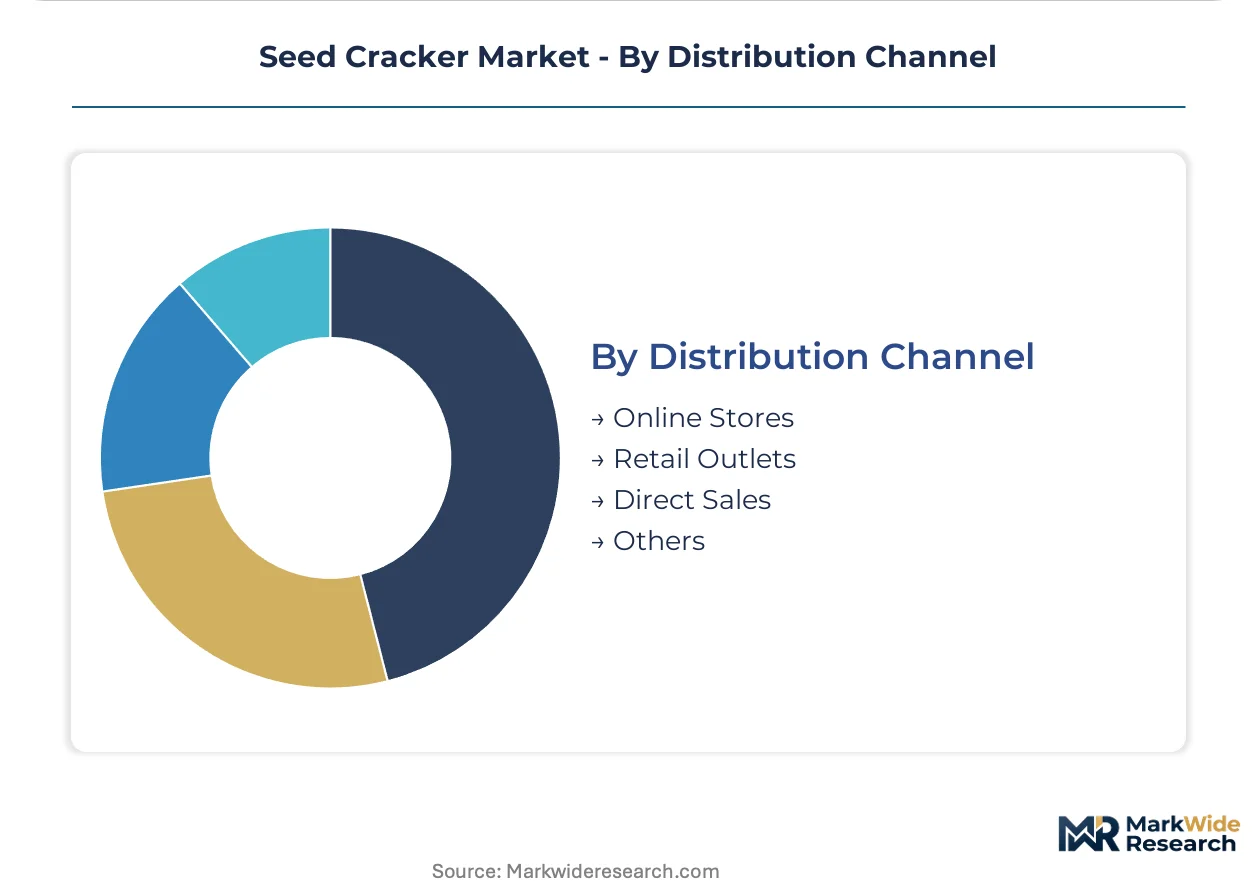
Distribution Channel:
Channel selection determines customer acquisition economics and repeat-purchase loyalty mechanics.
- Online Stores:Direct-to-household fulfillment platforms capture subscription-model penetration beyond conventional retail density constraints. Coastal US metropolitan markets and German urban clusters show steepest expansion trajectory where delivery density supports cold-chain-free distribution economics.
- Retail Outlets:Natural grocery and mass-market shelf placement still occupies dominant share of household user transactions. Clean-label aisle positioning anchors brand recognition and impulse purchase conversion.
- Direct Sales:Equipment manufacturers sell industrial and electric cracker lines through specialized food processing distributors.
- Others:Foodservice supply contracts and institutional procurement channels serve non-retail volume.
Retail outlets lead on scale; online stores lead on momentum as subscription replenishment displaces pantry-loading patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisanal bakery clusters in Bavaria and Baden-Württemberg anchor European seed cracker production expertise, while California's clean-label food manufacturing corridor concentrates North American innovation capacity.
Germany
Heritage seed cooperatives in Baden-Württemberg and artisanal consumption clusters in Bavaria sustain premium demand for organic seed crackers. EU Green Deal carbon accounting requirements for imported oilseeds force supply chain traceability investments among processors. Stuttgart's food technology corridor hosts equipment manufacturers developing ceramic-composite forming dies to meet REACH Annex XVII restrictions on perfluorinated compounds.
United States
Subscription-model household replenishment concentrates in coastal metropolitan markets from Seattle to Boston, displacing conventional retail pantry-loading patterns. FDA nutritional labeling and allergen declaration requirements govern reformulation cycles for clean-label lines. California's Central Valley organic seed processing cooperatives are integrating on-farm cracker production to capture premium value-added margins.
India
Food processors in Maharashtra and Gujarat drive equipment upgrade cycles as BIS certification mandates affect industrial cracker line imports. FSSAI clean-label guidelines accelerate organic certification adoption among export-oriented manufacturers. Mumbai's co-manufacturing facilities are retrofitting stainless steel convection lines to serve European private-label contracts requiring EU Green Deal compliance documentation.
United Kingdom
Natural grocery channel expansion in Greater London and the Southeast sustains demand for grain-free and gluten-free seed cracker varieties. UK-EU trade friction post-Brexit complicates oilseed sourcing from continental organic suppliers. Yorkshire's heritage grain cooperatives are piloting heritage seed cracker production using regionally sourced linseed and hemp.
Canada
Clean-label snacking adoption in Toronto and Vancouver metropolitan areas supports premium seed cracker market development. Health Canada and PMRA govern food contact substance approvals for novel binding agents and coating materials. Prairie provinces' organic oilseed growers are vertically integrating into small-batch cracker processing for direct-to-retail distribution.
Seed Cracker Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: organic supply chain integrators, grain-free formulation specialists, and gluten-free mass-market scale operators. Consolidation pressure concentrates among mid-scale processors lacking depreciation economies for stainless steel equipment mandates. Dominant competitive moves include strategic partnerships with organic certifiers and geographic expansion through e-commerce fulfillment infrastructure.
Among North American clean-label specialists, Mary's Gone Crackers and Simple Mills occupy positions within the organic and grain-free archetype tiers respectively, while Crunchmaster anchors the gluten-free mass-market segment. These companies exemplify divergent strategic postures: supply chain integration versus ingredient architecture specialization versus scaled manufacturing efficiency. Their competitive positioning reflects broader industry segmentation between premium certification-driven pricing and volume-driven mass-market penetration.
| Leading Market Players |
|---|
| Mary's Gone Crackers |
| Simple Mills |
| Crunchmaster |
| Back to Nature |
| Finn Crisp |
| Blue Diamond Almonds |
| Good Thins |
| Late July |
| Kii Naturals |
| Others |
Value Network & Pricing Analysis
Food processor procurement concentration in Germany and California drives contract-based long-term offtake structures that tie organic certification premiums to multi-year volume commitments.
Pricing Analysis
Equipment sales bundle hardware with installation and maintenance services while consumables trade on spot markets. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel electric lines from aluminum manual units and plastic household models. Cost compression in mid-scale electric tiers is intensifying because REACH-compliant ceramic-composite die surfaces carry 15-20% material premiums over conventional coatings. Mass-market retailers show highest price sensitivity; organic-certified food processors accept premium positioning for traceability guarantees.
Supply Chain Analysis
Organic oilseed supply rests on Canadian prairie growers, Ukrainian sunflower cooperatives, and Indian guar gum processors for binding agents. Stainless steel equipment fabrication draws from German engineering clusters, Chinese component suppliers, and Italian thermal system specialists. Single-source vulnerability concentrates in ceramic-composite die manufacturing where Stuttgart-based suppliers dominate REACH-compliant tooling. Distribution runs through specialized food processing equipment distributors serving commercial bakeries and co-manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed cracker equipment and ingredients constitute a late-cycle quality story as clean-label snacking shifts demand toward certified organic supply chains with full traceability documentation.
For Market Incumbents: Deploy ceramic-composite die certification investments to lock in European food processor contracts before REACH Annex XVII enforcement accelerates. Consolidate position through captive organic oilseed sourcing agreements in Canadian prairie provinces. Defensive moves must counter aluminum equipment challengers from Italian thermal specialists and plastic portable entrants targeting on-farm processing. For New Entrants and Emerging Players: Begin with portable electric units for Indian and US on-farm vertical integration where organic certification programs create premium market access. Target Maharashtra food processors retrofitting BIS-certified lines for European export compliance. Go-to-market leverage rests on subscription-based equipment financing paired with organic seed supply contracts. For Investors and Strategic Acquirers: Food processing conglomerates seeking clean-label portfolio expansion are the most active acquirer in this space. Five-to-ten year viability hinges on organic certification infrastructure rather than commodity seed processing. Target mid-scale electric equipment manufacturers with installed base conversion potential. Watch EU Green Deal carbon accounting implementation timelines as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA Organic and EU organic logos unlock 30-40% price premiums in German and US natural grocery channels. |
| Ceramic-Composite Die Deployment | REACH Annex XVII compliance eliminates perfluorinated compound risks for European equipment exports. |
| On-Farm Processing Integration | Canadian and Indian organic growers capture value-added margins through direct seed-to-cracker production. |
| Subscription Fulfillment Infrastructure | Coastal US metropolitan delivery density supports cold-chain-free household replenishment economics. |
| Hybrid Thermal System Retrofit | Convection-infrared modules reduce moisture variability below 5% thresholds without chemical preservatives. |
Research Methodology
Coverage spans Germany, the United States, India, the United Kingdom, and Canada, with primary inputs from each market cluster. The approach combines interviews with commercial bakery operations directors, organic certification program managers, food processing equipment procurement leads, and co-manufacturing facility engineers alongside secondary validation. Sources include EU Green Deal implementation documentation, FDA nutritional labeling guidance, BIS equipment certification records, and trade data from organic oilseed customs filings. Bottom-up equipment shipment analysis triangulates against top-down food processor capacity estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions encompass product type tiers, material specifications, end-user categories, and distribution channel economics. CAGRs derive from fitted growth curves calibrated to organic certification adoption rates and equipment replacement cycles. Industry-specific forecast inputs include REACH substance restriction timelines and California Extended Producer Responsibility implementation phases.
Caveats apply where EU Green Deal carbon accounting enforcement delays or ceramic-composite die supply bottlenecks could materially shift the outlook. Forecasts reflect assumptions about organic certification queue durations and stainless steel equipment depreciation schedules. A small set of named triggers—REACH Annex XVII expansion, California packaging law precedents, and Indian BIS standard updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Chamomile Seeds Market
Seeds
Faba Beans Market
Seeds
Poppy Seed Market
Seeds
Eucommia Seed Oil Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
United States Forage Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Cucumber Seeds Market
Seeds
Europe Sesame Seed Market
Seeds
North America Cannabis Seeds Market
Seeds
South America Seed Market
Seeds
North America Tomato Seed Market
Seeds
South Africa Seed Market
Seeds
Canary Seeds Market
Seeds
Cowpeas Market