
 India Vegetable Seed Market | 2026-2036
India Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
India Vegetable Seed Market Foresight
Maharashtra's seed multiplication infrastructure is tilting toward precision breeding facilities and climate-controlled storage. Syngenta Group leverages its global germplasm library to anchor hybrid development programs targeting tropical vegetable varieties. Nuziveedu Seeds Ltd. sustains its position through deep distribution networks across South Indian vegetable belts. BASF SE competes on trait integration, particularly disease resistance stacks in solanaceous crops.
India vegetable seed comprises genetically stable propagules bred for specific agro-climatic performance, including hybrid F1 generations with controlled pollination, open-pollinated varieties with generational genetic consistency, and trait-enhanced lines carrying resistance markers for viral and fungal pathogens; these seeds function as the foundational biological input determining yield, uniformity, harvest timing, and post-harvest shelf life for commercial vegetable production. Hybrid seeds command the dominant value share due to farmer willingness to pay for yield premiums and pest tolerance, while organic seeds represent a faster-expanding margin pool as certified cultivation area expands under export-facing contract farming arrangements. Distribution through co-operatives captures substantial volume in Maharashtra and Gujarat, though e-commerce channels are gaining traction among progressive farmers accessing varietal performance data digitally.
India's seed regulatory environment operates under the Seeds Act administered by the Central Seed Committee, with BIS certification governing minimum germination and genetic purity standards, while the PLI scheme for agriculture inputs provides production-linked incentives for domestic breeding infrastructure expansion. CDSCO oversight applies to any genetically modified seed traits requiring environmental release clearance, creating a dual-track compliance pathway that shapes R&D investment timelines. Stakeholders must monitor state-level seed subsidy allocation shifts and evolving BIS standards for organic seed certification as these will determine competitive positioning in premium vegetable seed segments.
Market Dynamics
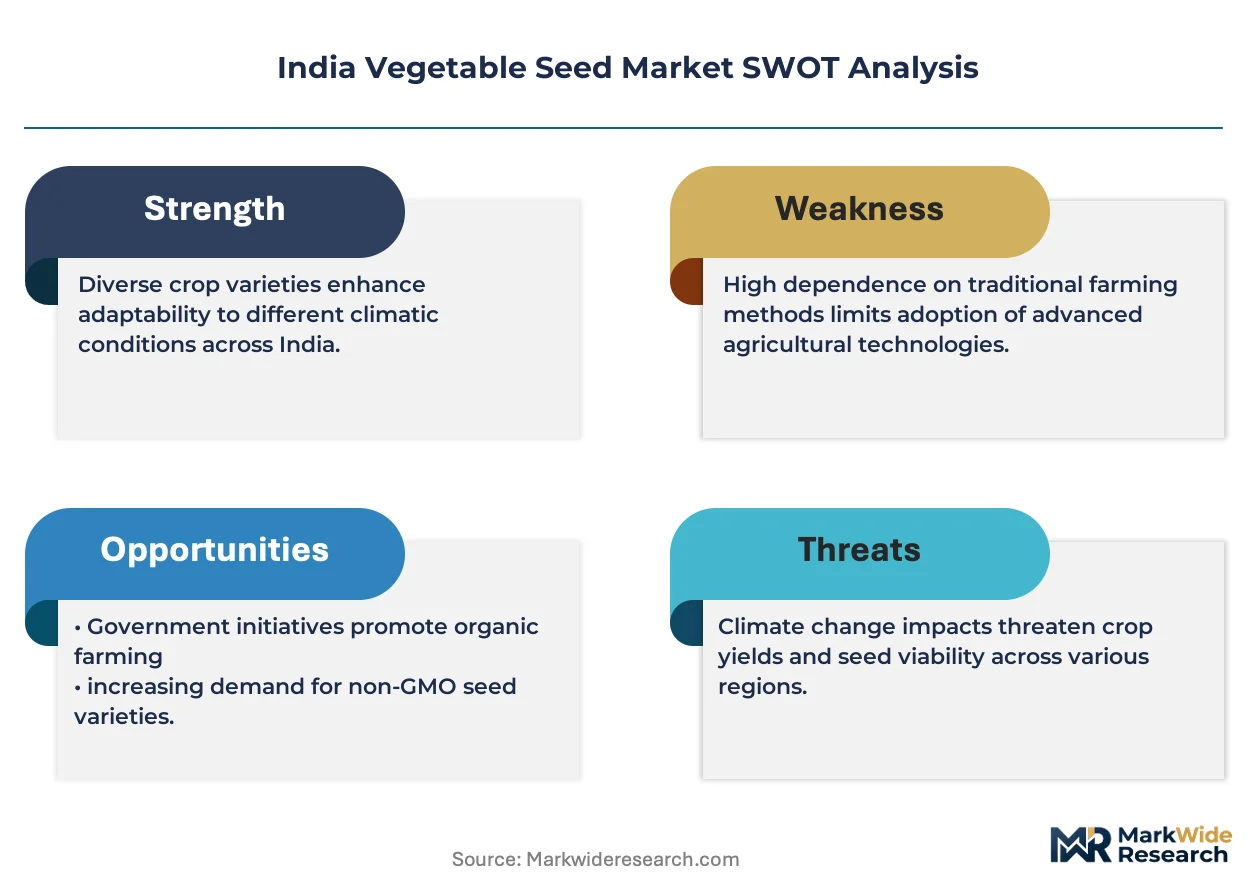
Hybrid seed penetration in India's vegetable sector is accelerating as the PLI scheme for agriculture inputs redirects domestic breeding investment toward climate-resilient tropical varieties, compressing the innovation cycle from germplasm selection to commercial release.
Growth Catalysts
- PLI Scheme for Agriculture Inputs:Production-linked incentives are expanding domestic breeding infrastructure capacity, reducing reliance on imported parental lines for solanaceous and cucurbit crops.
- Gujarat Seed Processing Clusters:Concentrated investment in climate-controlled storage and precision sorting equipment is improving genetic purity compliance rates for export-bound certified seed.
- Digital Extension Services:Smartphone-based varietal performance data is accelerating farmer switching from open-pollinated to hybrid F1 generations in Maharashtra's commercial tomato belts.
Market Restraints
- Parental Line Import Dependency:Critical germplasm for heat-tolerant hybrids remains concentrated with multinational breeding programs, exposing domestic formulators to currency volatility and licensing restrictions.
- CDSCO Trait Approval Timelines:Environmental release clearance for disease-resistant stacked traits operates on multi-year review cycles, delaying commercialization of CRISPR-edited lines.
- Informal Seed Networks:Farmer-saved seed and unregistered local varieties capture substantial volume in the Indo-Gangetic Plains, compressing formal channel pricing power.
Strategic Opportunities
- Organic Certification Expansion:Export-facing contract farming arrangements in Karnataka are creating dedicated demand pools for certified organic vegetable seed with full traceability documentation.
- E-Commerce Direct-to-Farmer Channels:Progressive growers in Andhra Pradesh are accessing performance data and placing varietal orders through agritech platforms, bypassing traditional cooperative distribution.
- Climate-Adaptive Trait Stacks:Convergence of marker-assisted selection with rapid generation advance protocols is enabling faster development of drought-tolerant okra and brinjal lines for rainfed production zones.
Industry Challenges
- Genetic Purity Testing Bottlenecks:BIS certification requirements for minimum germination standards face laboratory capacity constraints, creating shipment delays during peak sowing windows.
- Skilled Breeder Shortage:Domestic universities produce insufficient tropical vegetable physiologists to staff expanded R&D facilities under PLI-funded infrastructure builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Vegetable Seed Market |
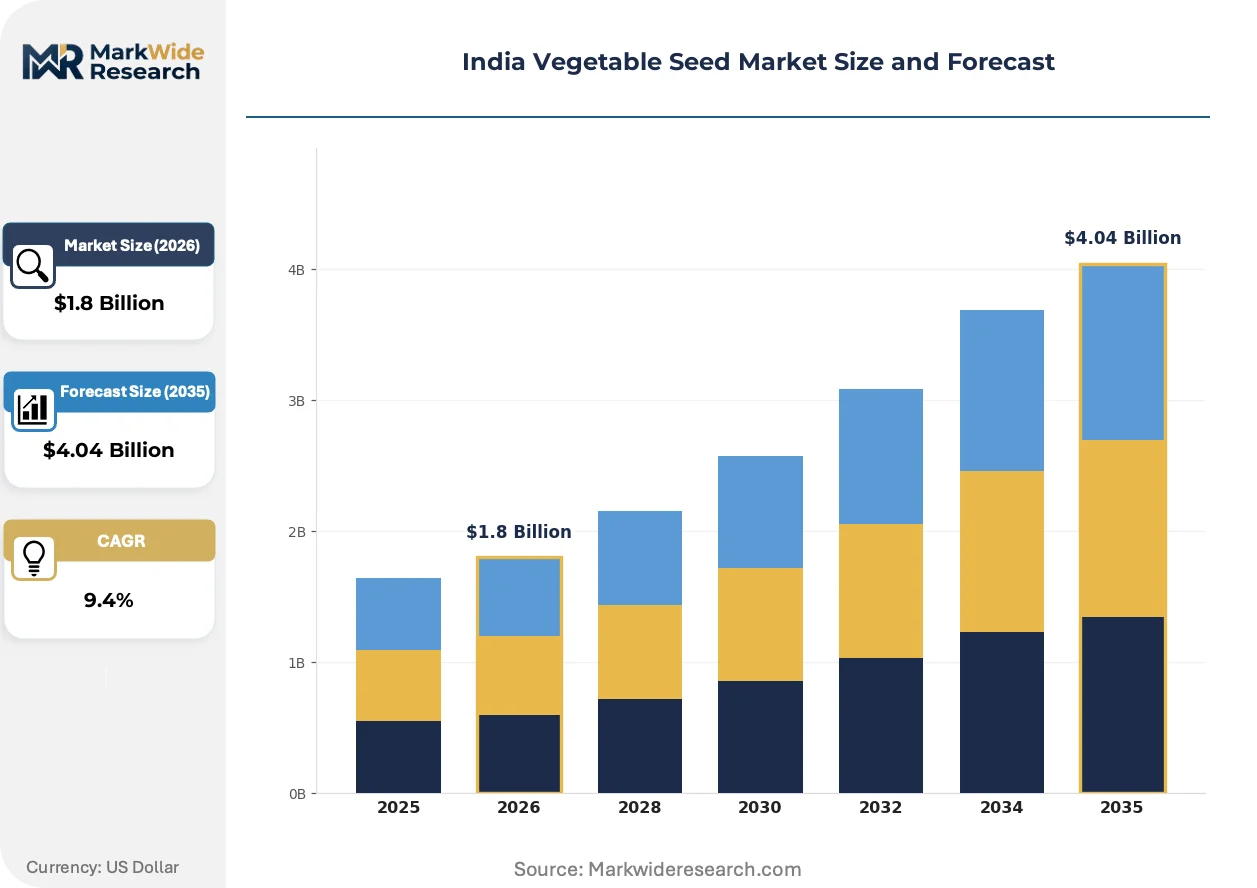
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, Genetically Modified Seeds, Organic Seeds Distribution Channel: Direct Sales, Retail Stores, E-Commerce, Co-operatives Cultivation Method: Conventional Farming, Organic Farming, Greenhouse Cultivation, Hydroponics End User: Farmers, Commercial Growers, Home Gardeners, Agribusiness Firms |
| Companies Covered | VNR Seeds Private Limited, Sakata Seed Corporation, Syngenta Group, Nuziveedu Seeds Ltd., Takii & Co., Ltd., Maharashtra Hybrid Seeds Company Private Limited, BASF SE, Corteva Agriscience, UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Vegetable Seed Market Shifts & Advancements
Digital phenotyping platforms are compressing the variety development pipeline, while regulatory clarity on gene-edited crops and shifting procurement channels among commercial growers are restructuring competitive positioning in India's vegetable seed sector.
Marker-assisted selection combined with rapid generation advance protocols is virtualizing the traditional multi-season field testing cycle. Seed companies in Maharashtra and Karnataka are deploying these tools to slash development timelines for heat-tolerant tomato hybrids. The technology is virtualizing the competitive advantage of established breeding programs by enabling smaller domestic players to match varietal release frequencies previously achievable only by multinationals with extensive germplasm libraries.
The Seeds Act regulatory updates are clarifying the pathway for gene-edited vegetable varieties outside the transgenic approval framework. CDSCO oversight continues to apply to stacked-trait products requiring environmental release clearance, but site-directed nuclease edits without foreign DNA are shifting toward BIS purity standards alone. This bifurcation is accelerating investment in CRISPR-based disease resistance programs targeting Fusarium wilt in solanaceous crops across South Indian breeding stations.
Commercial growers in the Indo-Gangetic Plains are consolidating seed procurement through direct relationships with breeding houses, disintermediating the cooperative channel that historically captured Maharashtra and Gujarat volume. Large-scale tomato and capsicum producers are demanding performance guarantees and replant compensation clauses, transferring agronomic risk upstream to seed suppliers. This shift is most visible in Haryana and Punjab vegetable belts where contract farming aggregators negotiate variety-specific supply agreements with integrated pest management obligations.
India Vegetable Seed Market Segmentation
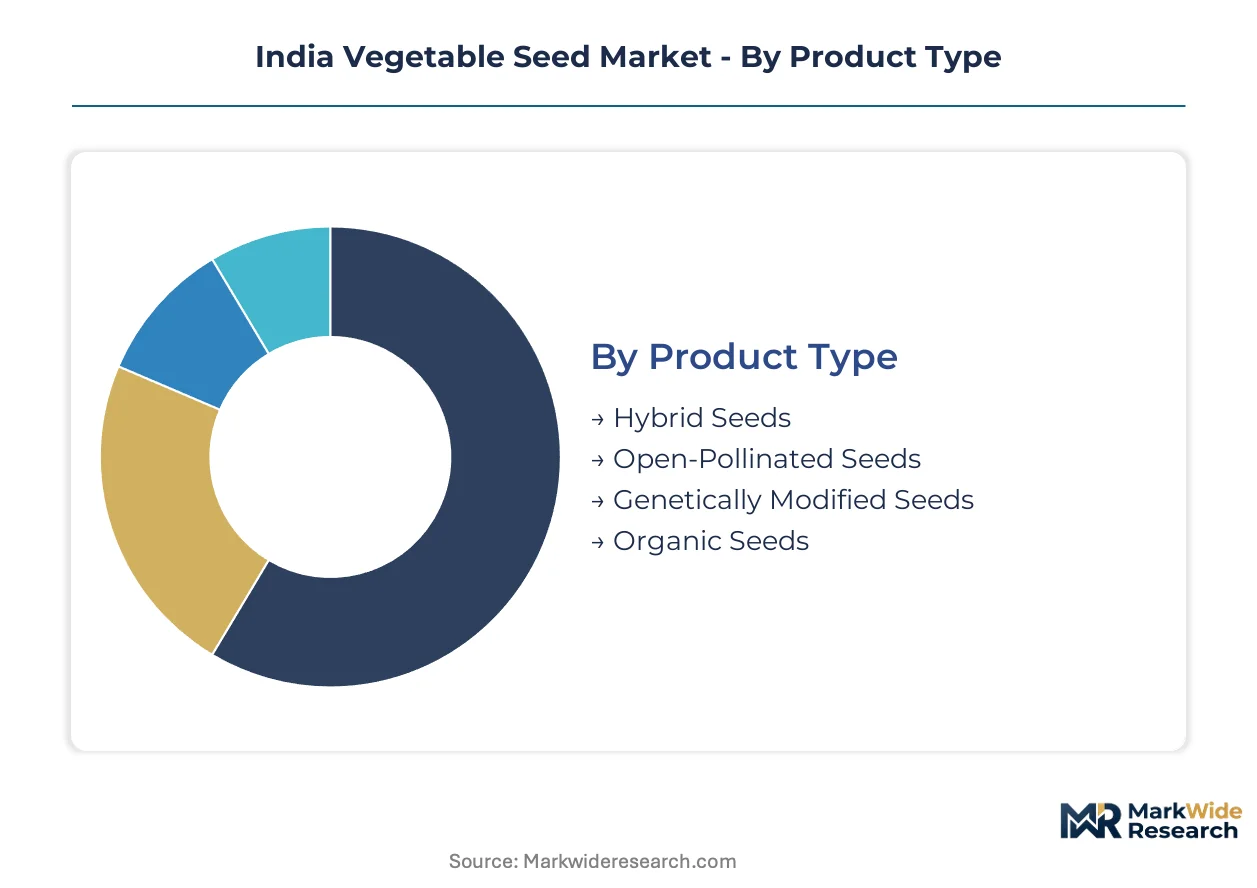
India's vegetable seed market segments along four critical dimensions that determine pricing power, channel strategy, and regulatory exposure. Each category reveals distinct competitive dynamics between formal breeding houses and informal seed networks, with hybrid penetration and digital channel adoption reshaping traditional procurement patterns across Maharashtra and Karnataka growing belts.
Product Type:
Mature hybrid categories dominate commercial value while emerging organic and gene-edited lines capture premium positioning in export-facing supply chains.
- Hybrid Seeds:F1 generation seeds produced through controlled cross-pollination of inbred parental lines deliver genetic uniformity, yield premiums, and stacked disease resistance. Demand concentrates in Maharashtra's tomato belts and Karnataka's okra districts where commercial growers pay for harvest timing predictability and post-harvest shelf life extension.
- Open-Pollinated Seeds:Varieties maintaining generational genetic consistency through natural pollination mechanisms serve resource-constrained farmers in the Indo-Gangetic Plains. Farmer-saved seed networks in Bihar and Uttar Pradesh sustain this segment despite formal channel expansion, compressing pricing power for certified OPV suppliers.
- Genetically Modified Seeds:Transgenic lines carrying foreign DNA inserts for insect resistance or herbicide tolerance face CDSCO environmental release clearance requirements. Bt brinjal remains the sole commercialized GM vegetable trait in India.
- Organic Seeds:Certified propagules bred under organic standards with full traceability documentation serve Karnataka's export-facing contract farming arrangements. Premium pricing reflects compliance with EU and US organic import protocols.
Hybrid Seeds retain volume leadership; Organic Seeds hold the steepest expansion curve.
Distribution Channel:
Channel structure reflects the tension between cooperative legacy systems and digital disintermediation among progressive commercial growers.
- Direct Sales:Breeding houses maintain field-level relationships with large-scale tomato and capsicum producers in Haryana and Punjab, offering performance guarantees and replant compensation clauses that transfer agronomic risk upstream.
- Retail Stores:Agro-dealer networks in Gujarat's seed processing clusters provide physical access to certified varieties with BIS documentation, though inventory depth varies by sowing season timing.
- E-Commerce:Agritech platforms enable Andhra Pradesh growers to access varietal performance data and place direct orders, bypassing cooperative markups.
- Co-operatives:Maharashtra and Gujarat farmer cooperatives aggregate procurement volume, capturing substantial share through subsidized distribution aligned with state seed programs.
Co-operatives retain volume leadership; E-Commerce holds the steepest expansion curve.
Cultivation Method:
Method segmentation tracks the divergence between rainfed traditional systems and protected cultivation infrastructure investment in peri-urban supply zones.
- Conventional Farming:Open-field rainfed and irrigated production across the Indo-Gangetic Plains consumes bulk volume of heat-tolerant okra and brinjal varieties, with seed selection driven by drought tolerance and local market acceptability.
- Organic Farming:Certified cultivation areas in Karnataka and Maharashtra demand untreated seeds with documented genetic purity for export contract compliance, creating dedicated sourcing requirements distinct from conventional input streams.
- Greenhouse Cultivation:Polyhouse and nethouse systems around Pune and Bangalore require determinate tomato hybrids and parthenocarpic cucumber varieties bred for controlled environment performance.
- Hydroponics:Soilless systems in peri-urban corridors near Delhi and Hyderabad specify compact rootstock varieties with enhanced nutrient uptake efficiency for NFT and DWC configurations.
Conventional Farming retains volume leadership; Hydroponics holds the steepest expansion curve.
End User:
User segmentation captures the capability gap between subsistence operators and integrated agribusiness firms with technical advisory capacity.
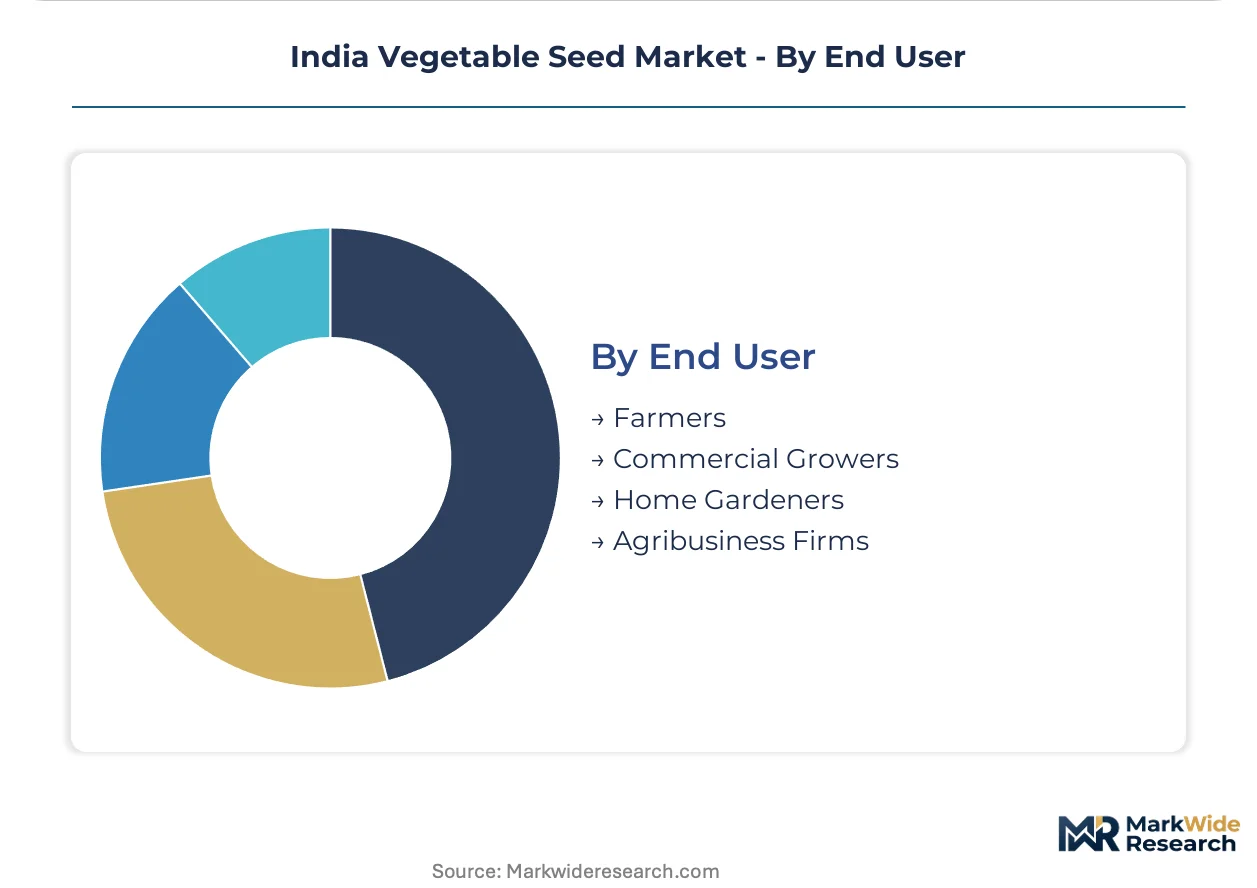
- Farmers:Smallholder operators across Bihar and Uttar Pradesh prioritize seed cost minimization and local variety familiarity, sustaining informal seed exchange networks despite formal channel expansion.
- Commercial Growers:Large-scale tomato and capsicum producers in Maharashtra and Karnataka negotiate direct supply agreements with breeding houses, demanding variety-specific integrated pest management protocols.
- Home Gardeners:Urban consumers in Bangalore and Hyderabad drive demand for compact vegetable varieties through retail and e-commerce channels, though absolute volume remains marginal.
- Agribusiness Firms:Integrated operations managing contract farming aggregators in Gujarat and Punjab standardize on specific hybrid lines to ensure harvest uniformity for processing and export commitments.
Farmers retain volume leadership; Commercial Growers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic breeding infrastructure concentrates in Maharashtra and Karnataka, where precision breeding facilities and climate-controlled storage anchor the national seed multiplication network. Gujarat's processing clusters handle genetic purity certification for export-bound volumes. The Indo-Gangetic Plains sustain substantial open-pollinated seed demand through farmer-saved networks.
Maharashtra
Commercial tomato and okra growers in Nashik and Pune districts drive hybrid F1 seed procurement through direct breeding house relationships. The state's PLI scheme allocation expands precision breeding infrastructure near Aurangabad. Seed processing capacity clusters around Jalna and Latur, where climate-controlled storage facilities improve germination compliance rates.
Karnataka
Export-facing contract farming arrangements in Bengaluru Rural and Kolar districts generate certified organic vegetable seed demand with full traceability documentation. The state's seed subsidy programs channel formal channel adoption in rainfed brinjal and okra belts. Processing infrastructure concentrates around Dharwad and Hubballi, serving the Deccan plateau vegetable cultivation zone.
Gujarat
Seed processing and genetic purity testing infrastructure dominates the Gandhinagar-Ahmedabad corridor, supplying certified volumes to domestic and export markets. The state's cooperative distribution networks capture substantial smallholder volume through subsidized channels. BIS certification laboratory capacity in Anand and Vadodara handles peak-season germination testing loads.
Haryana
Large-scale tomato and capsicum producers in Karnal and Sonipat districts negotiate direct supply agreements with integrated pest management obligations. The state's contract farming aggregators disintermediate traditional cooperative procurement channels. Processing infrastructure near Hisar serves the peri-urban vegetable supply zones feeding Delhi-NCR markets.
Andhra Pradesh
Progressive growers in Guntur and Krishna districts access varietal performance data through agritech platforms, bypassing cooperative markups for hybrid seed orders. The state's digital extension services accelerate farmer switching from open-pollinated to hybrid generations. Coastal climate conditions drive demand for heat-tolerant tropical vegetable varieties.
India Vegetable Seed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying germplasm and trait technologies. The market structures around multinational breeding houses with global germplasm libraries, domestic formulators with deep distribution networks, and regional specialists with climate-adaptive local varieties. Three archetypes dominate: germplasm licensors, integrated breeding-to-seed enterprises, and distribution-focused domestic players. Competitive moves center on trait licensing agreements and backward integration into parental line development.
Within the multinational tier, Syngenta Group and BASF SE occupy positions anchored by global germplasm access and trait integration capabilities. Nuziveedu Seeds Ltd. exemplifies the domestic integrated archetype, with distribution depth across South Indian vegetable belts. These three represent the competitive spectrum from germplasm-dependent global platforms to regionally embedded seed suppliers.
| Leading Market Players |
|---|
| VNR Seeds Private Limited |
| Sakata Seed Corporation |
| Syngenta Group |
| Nuziveedu Seeds Ltd. |
| Takii & Co., Ltd. |
| Maharashtra Hybrid Seeds Company Private Limited |
| BASF SE |
| Corteva Agriscience |
| UPL Limited |
| Others |
Supply & Pricing Matrix
The Mumbai-Jalna freight corridor's logistics cost dynamics amplify supply concentration effects in Maharashtra's seed processing clusters while forcing downstream price differentiation between cooperative-subsidized and direct-channel procurement tiers.
Pricing Analysis
BIS certification standards dictate the pricing tier structure across India's vegetable seed market, separating export-grade certified hybrids with full germination documentation from informal channel volumes lacking genetic purity verification. Premium-mid-economy pricing differentiation reflects certification grade and volume scale, with large commercial growers in Haryana negotiating contract-based long-term offtake while smallholders in Bihar remain most price-sensitive. Cost compression in economy-tier open-pollinated seeds is intensifying because farmer-saved seed networks bypass formal channel markups entirely.
Supply Chain Analysis
CDSCO trait approval restrictions and germplasm licensing controls limit flows of CRISPR-edited parental lines into domestic breeding programs, constraining supply flexibility. Production concentrates in India, Netherlands, and Japan for specialized hybrid parental lines, while critical inputs include climate-controlled storage infrastructure, marker-assisted selection platforms, and BIS-certified testing laboratory capacity. Single-source vulnerability runs through multinational germplasm libraries for heat-tolerant tropical varieties. Distribution runs through cooperative aggregators in Maharashtra and Gujarat, though direct-to-farmer channels are gaining share among progressive commercial growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's vegetable seed market is approaching a platform-economics inflection where agritech data interoperability determines competitive access to progressive grower segments, with digital extension services reconstituting traditional cooperative lock-in.
For Market Incumbents: Entrench germplasm advantage through backward integration into parental line development for heat-tolerant tropical varieties, insulating against currency volatility in licensed trait imports. Expand climate-controlled storage capacity in Jalna and Dharwad processing clusters to capture peak-season certification demand and defend against regional specialists with localized climate-adaptive lines. For New Entrants and Emerging Players: The Indo-Gangetic Plains' rainfed okra and brinjal belts present the most penetrable geography, where informal seed networks dominate and formal channel substitution offers substantial white space. Target contract farming aggregators in Karnataka's export-facing organic belts with certified traceability documentation as the primary go-to-market angle, bypassing cooperative distribution entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic formulators with established BIS certification pathways and deep cooperative relationships over pure-play germplasm licensors facing regulatory approval timeline risk. Acquisition targets should demonstrate integrated breeding-to-seed capabilities with existing parental line development programs. Monitor CDSCO guidance on gene-edited crop classification as the critical inflection signal determining R&D investment viability timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Parental Line Development Investment | Reduces licensing cost exposure to Syngenta and BASF germplasm libraries for tropical hybrid programs. |
| Climate-Controlled Storage Expansion | Enables BIS germination compliance during peak sowing windows in Jalna and Gandhinagar clusters. |
| Agritech Platform Partnership | Secures direct access to progressive growers in Andhra Pradesh bypassing cooperative markups. |
| Organic Certification Infrastructure | Unlocks export contract farming demand in Karnataka with EU and US import protocol compliance. |
| Marker-Assisted Selection Capability Buildout | Compresses variety development timelines to match multinational release frequencies for tomato hybrids. |
Research Methodology
The analysis maps hybrid F1 seeds, open-pollinated varieties, organic certified lines, and gene-edited propagules, each validated through breeding program directors, cooperative procurement managers, state seed certification officers, and agritech platform operators. Primary field engagement combined with secondary validation from Seeds Act regulatory filings, BIS certification databases, state subsidy allocation records, and CDSCO environmental release dockets. Bottom-up variety-level volume estimates triangulated against top-down sector aggregation across the analysis window.
Assumptions held fixed include PLI scheme continuation for agriculture inputs, current BIS germination standards, and existing CDSCO trait approval timelines, while varying hybrid penetration rates and digital channel adoption curves. Segmentation dimensions modeled include product type, distribution channel, cultivation method, and end-user archetype. CAGRs derived from fitted growth curves incorporating state-level seed subsidy allocations, processing infrastructure expansion timelines, and export contract farming area growth.
Practitioners should monitor PLI scheme funding reallocations, BIS organic seed certification standard updates, and CDSCO gene-editing regulatory guidance for early signals of forecast revision triggers. Material shifts in germplasm import licensing restrictions or state-level seed subsidy program suspensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Caraway Seeds Market
Seeds
Asparagus Seeds Market
Seeds
Hemp Seeds Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Russia Seed Market
Seeds
North America Cannabis Seeds Market
Seeds
Punnet Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Genetically Modified Seeds Market
Seeds
Asia-Pacific Seed Market
Seeds
United States Forage Seed Market
Seeds
Lupin Market
Seeds
Global Soybean Seed Market
Seeds
Agricultural Seeder Market
Seeds
Apple Seed Oil Market