
 Philippines Hybrid Rice Seed Market | 2026-2036
Philippines Hybrid Rice Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Hybrid Rice Seed Market Analytics
Smallholder cooperatives are collapsing as the dominant buyer archetype as large commercial farming enterprises and consolidated agricultural companies expand their share of certified hybrid seed procurement. SL Agritech Corporation dominates domestic breeding programs tailored to Philippine agroclimatic zones. Bayer AG competes through advanced biotech traits integrated into hybrid parental lines. Yuan Longping High-Tech Agriculture Co. Ltd anchors supply of two-line system germplasm critical to yield stability.
Philippines Hybrid Rice Seed refers to the first-generation progeny of controlled crosses between genetically distinct inbred parental lines, typically exhibiting heterosis that delivers yield advantages of 15-30% over conventional inbred varieties while requiring precise water and nutrient management. The product category stratifies into high-yield, disease-resistant, aromatic, and specialty segments, with disease-resistant varieties capturing expanding margin pools as bacterial leaf blight and tungro virus pressure intensify across tropical lowlands. Distribution channel structure reveals direct sales and distributor networks as the primary volume conduits, though online platforms are gaining traction among younger farmer demographics in digitally connected provinces.
The Department of Agriculture and the Philippine Rice Research Institute shape market access through seed certification protocols and the National Seed Quality Control Services, while the Rice Tariffication Law redirects import levy revenues toward farmer mechanization and certified seed subsidies. BIS-equivalent seed standards and the Seed Industry Development Act govern varietal registration and intellectual property protection. Stakeholders must monitor how regulatory adjustments to the Rice Competitiveness Enhancement Fund allocation rules reshape procurement patterns across irrigated and rainfed production zones.
Market Dynamics
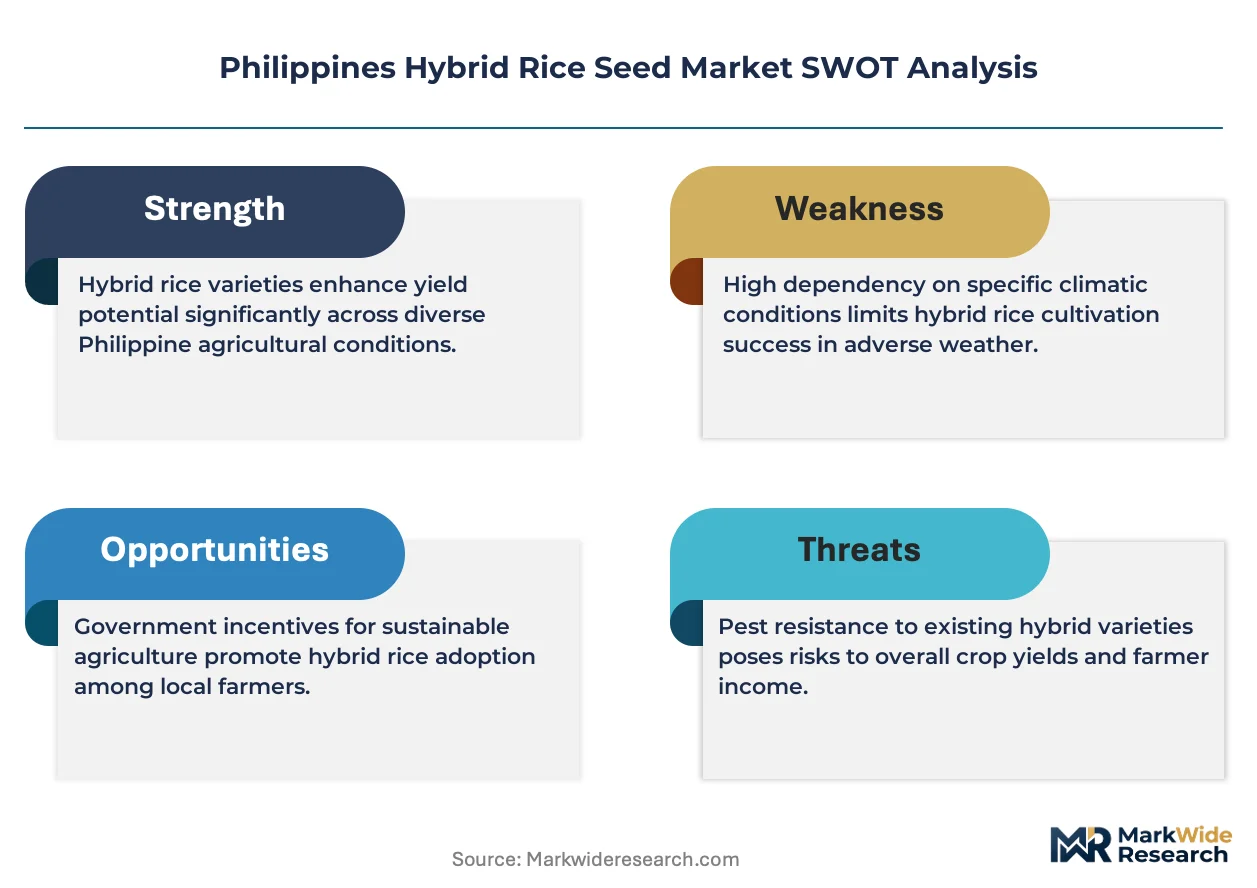
The Rice Competitiveness Enhancement Fund is consolidating procurement power toward commercial farming enterprises, collapsing the traditional cooperative-based distribution architecture and reconfiguring how certified hybrid seed reaches irrigated lowlands.
Growth Catalysts
- Rice Tariffication Law revenue recycling:Import levy redirection into farmer mechanization and certified seed subsidies expands addressable demand among commercial operators upgrading from saved seed.
- Central Luzon irrigation density:Concentrated water infrastructure in this region enables intensive hybrid cultivation cycles that maximize seed turnover and repeat purchase frequency.
- Two-line system germplasm:Advanced breeding platforms from Chinese suppliers improve yield stability under tropical stress, accelerating replacement of three-line system varieties in disease-pressured lowlands.
Market Restraints
- Fertilizer cost volatility:Hybrid varieties demand precise nutrient management; urea price spikes compress operating margins and deter adoption among risk-averse smallholders.
- Parental line import concentration:Critical germplasm dependencies on external breeding programs expose supply continuity risks during trade friction or phytosanitary disputes.
- Seed certification timeline:National Seed Quality Control Services protocols extend varietal registration cycles, delaying market entry for improved resistance traits.
Strategic Opportunities
- Mindanao rainfed expansion:Underpenetrated upland provinces present volume growth potential as drought-tolerant hybrid lines demonstrate yield stability in erratic precipitation zones.
- Digital platform distribution:E-commerce seed procurement is gaining traction among younger farmer demographics in digitally connected provinces, bypassing traditional distributor markups.
- Disease-resistant premium tier:Bacterial leaf blight and tungro virus pressure intensifies demand for resistant varieties, opening margin expansion in specialty seed segments.
Industry Challenges
- Certified seed production capacity:Scaling breeder seed multiplication to match commercial demand requires capital-intensive infrastructure expansion that outpaces current investment flows.
- Intellectual property enforcement:Weak varietal protection under the Seed Industry Development Act enables brown-bag seed saving, eroding royalty capture for proprietary hybrid developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Hybrid Rice Seed Market |
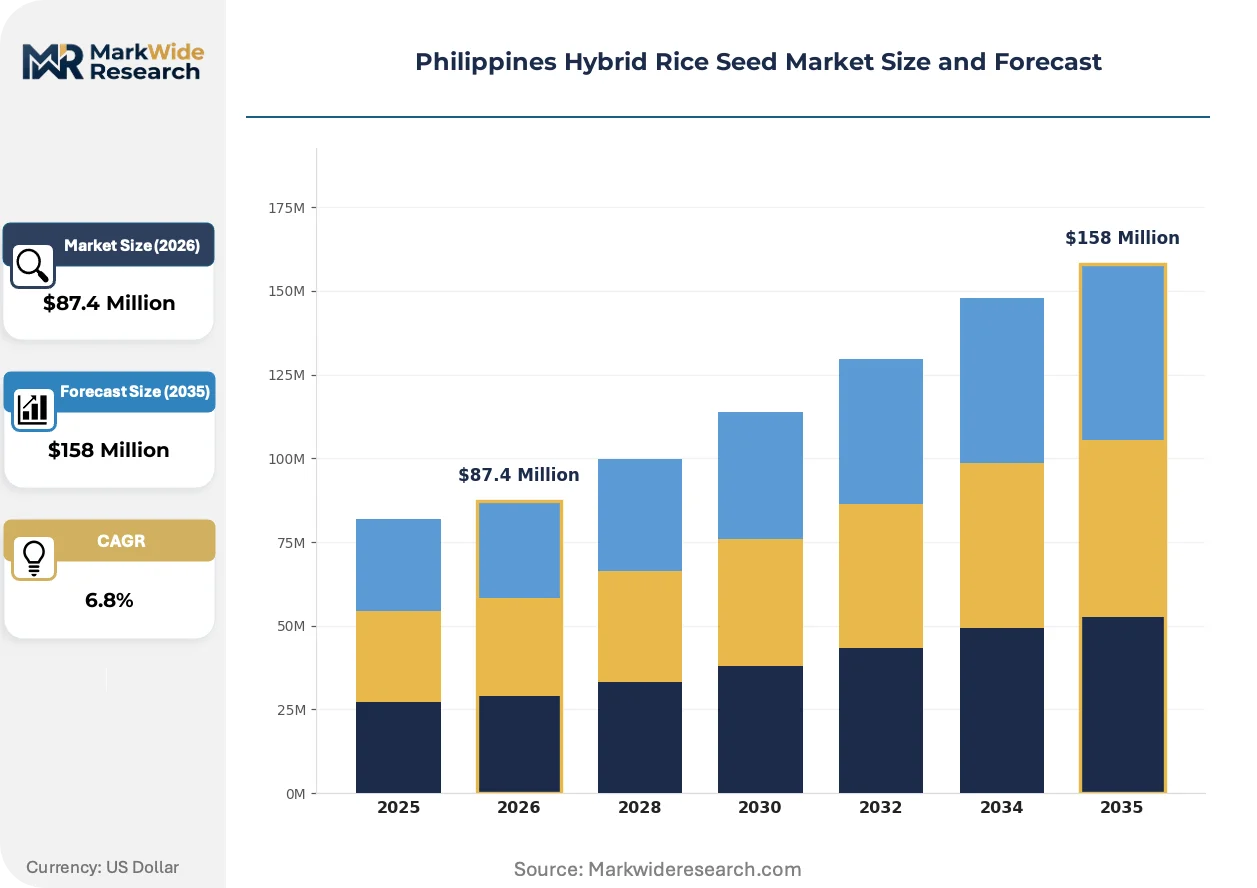
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Yield, Disease-Resistant, Aromatic, Specialty End User: Farmers, Cooperatives, Agricultural Companies, Research Institutions Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Distributors Application: Irrigated Fields, Rainfed Areas, Commercial Farming, Subsistence Farming |
| Companies Covered | Corteva Agriscience, Yuan Longping High-Tech Agriculture Co. Ltd, SL Agritech Corporation, Vietnam National Seed Corporation (Vinaseed), UPL (Advanta Seeds), Bayer AG, SeedWorks International Private Limited, Bioseed (DCM Shriram Ltd), Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Hybrid Rice Seed Market Evolving Landscape
Biotechnology integration and digital distribution channels are restructuring how hybrid rice seed is developed, certified, and delivered to Philippine farming operations.
Marker-assisted selection is bifurcating breeding program efficiency. Philippine Rice Research Institute and domestic seed houses deploy genomic screening to accelerate trait stacking for blast resistance and grain quality. Commercial farms with capital access adopt these advanced lines first, compressing the performance gap between elite hybrids and conventional inbred varieties while marginalizing late-adopting smallholders.
Department of Agriculture adjustments to Rice Competitiveness Enhancement Fund allocation rules are reshaping subsidy mechanics. Revised procurement protocols favor direct commercial farm engagement over cooperative intermediation, redirecting public support toward consolidated operators with mechanization capacity. Central Luzon and Ilocos regions experience the most pronounced subsidy flow reconfiguration.
Farmer purchasing behavior is fragmenting across generational lines. Younger operators in Pangasinan and Nueva Ecija provinces bypass agricultural supply cooperatives for mobile-enabled direct seed purchases, disintermediating traditional distributor networks. This channel rotation compresses price transparency and accelerates switching between seed brands based on real-time yield performance data shared through farmer digital communities.
Philippines Hybrid Rice Seed Market Segmentation
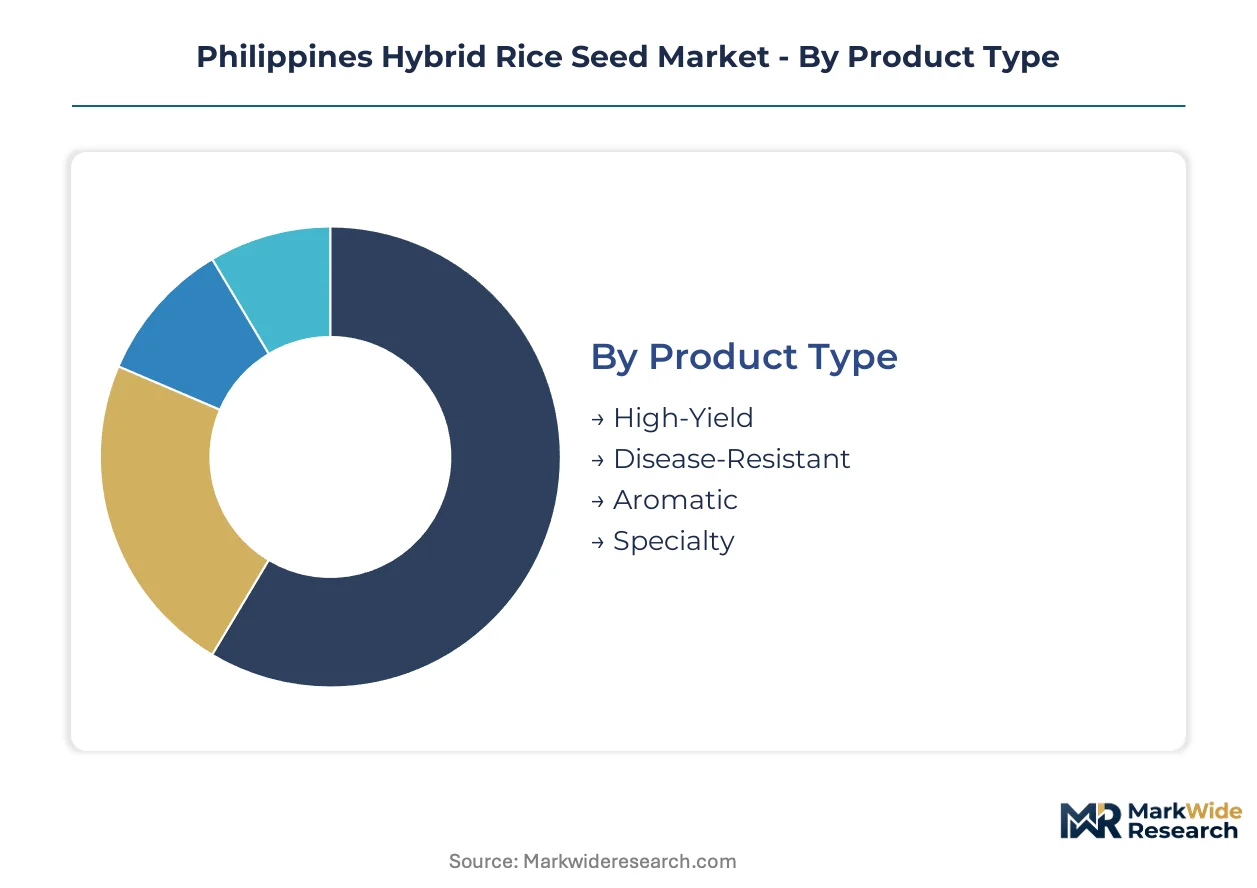
Philippine hybrid rice seed procurement patterns diverge sharply across buyer archetypes and cultivation contexts. Channel preferences, water access, and scale of operation determine which segments capture volume and margin.
Product Type:
Direct sales networks and agricultural supply cooperatives move distinct product tiers to different farming operations. High-yield and disease-resistant lines flow through certified distributor channels, while aromatic and specialty varieties reach premium buyers via targeted agronomist relationships.
- High-Yield:First-generation hybrids engineered for maximum grain output per hectare under intensive management. Central Luzon commercial farms with mechanized harvesting capacity drive repeat purchases of these lines.
- Disease-Resistant:Varieties incorporating stacked resistance traits against bacterial leaf blight and tungro virus. Demand concentrates in tropical lowlands where pathogen pressure intensifies with monsoon patterns.
- Aromatic:Premium fragrance-profile hybrids commanding price premiums in specialty rice markets. Niche adoption among contract farming arrangements supplying export-oriented mills.
- Specialty:Segmented lines for organic certification or specific grain morphology requirements. Limited volume through direct breeder relationships with institutional buyers.
High-yield dominates installed base. Disease-resistant is where expansion concentrates.
End User:
Procurement scale and subsidy access determine which buyer categories shape demand. Rice Competitiveness Enhancement Fund mechanics increasingly favor consolidated operators over fragmented smallholders.
- Farmers:Individual operators ranging from subsistence cultivators to mechanized commercial managers. Central Luzon and Ilocos irrigated zones host the most capitalized farmer segment.
- Cooperatives:Aggregated smallholder purchasing bodies historically central to seed distribution. Collapsing market share as direct commercial farm engagement expands under revised subsidy protocols.
- Agricultural Companies:Consolidated farming enterprises and plantation-style operations with hundred-plus hectare holdings. These buyers negotiate volume discounts and technical support packages directly with breeders.
- Research Institutions:Philippine Rice Research Institute and university breeding programs sourcing foundation stock. Limited commercial volume but critical for varietal pipeline development.
Agricultural companies are gaining share fastest. Cooperatives face structural displacement.
Distribution Channel:
Channel economics and farmer demographics determine route-to-market efficiency. Digital penetration varies sharply between generational cohorts and provincial connectivity levels.
- Direct Sales:Breeder-to-farm transactions eliminating distributor markups. Large commercial operations in Nueva Ecija and Pangasinan prefer this channel for technical support access.
- Retail Outlets:Provincial agricultural supply stores serving smallholder catchments. Physical inspection of seed quality remains important for risk-averse buyers.
- Online Platforms:Mobile-enabled procurement gaining traction among younger farmers. Price transparency and yield performance data sharing accelerate brand switching.
- Distributors:Multi-tier networks reaching remote barangays with credit extension. Inventory carrying costs and working capital requirements limit geographic coverage.
Distributors still handle majority volume. Online platforms show steepest expansion trajectory.
Application:
Water security and scale of operation create divergent seed performance requirements. Irrigated infrastructure availability determines hybrid adoption feasibility across Philippine agroecological zones.
- Irrigated Fields:Controlled water delivery enabling intensive hybrid cultivation cycles. Central Luzon irrigation systems support maximum seed turnover and repeat purchase frequency.
- Rainfed Areas:Precipitation-dependent cultivation requiring drought-tolerant germplasm. Mindanao upland provinces present underpenetrated expansion potential.
- Commercial Farming:Large-scale mechanized operations optimizing input-output ratios. These buyers prioritize yield stability and harvest timing predictability.
- Subsistence Farming:Smallholder production primarily for household consumption. Saved seed and informal exchange limit certified hybrid penetration.
Irrigated fields anchor current demand. Rainfed areas represent the largest untapped volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese germplasm suppliers anchor the upstream trade corridor into Philippine seed houses, with two-line system parental lines flowing through direct breeder relationships before domestic multiplication and certification under National Seed Quality Control Services protocols.
Central Luzon
Irrigation density in Nueva Ecija and Pangasinan provinces enables intensive hybrid cultivation cycles that maximize seed turnover. The Rice Competitiveness Enhancement Fund directs subsidy flows toward mechanized commercial farms in this corridor, collapsing traditional cooperative intermediation. Tarlac and Bulacan host the densest concentration of certified seed processing facilities serving national distribution networks.
Ilocos Region
Transplanted hybrid adoption in Ilocos Norte and Ilocos Sur benefits from established water associations managing communal irrigation systems. The Philippine Rice Research Institute maintains breeding trial stations in this zone, accelerating varietal adaptation to northern Luzon agroclimatic conditions. Laoag City anchors seed distributor networks reaching rainfed upland barangays.
Mindanao
Drought-tolerant hybrid lines penetrate Cotabato and Bukidnon provinces where erratic precipitation patterns limit three-line system performance. The Department of Agriculture scales demonstration plots for stress-tolerant germplasm, though seed certification infrastructure lags behind Luzon. Davao del Sur hosts emerging commercial farm consolidation driving direct breeder relationships.
Western Visayas
Iloilo and Negros Occidental combine irrigated lowlands with sugarcane rotation systems that create seasonal rice planting windows favoring short-duration hybrids. Provincial agricultural offices administer Rice Tariffication Law subsidy vouchers, though distributor credit extension remains weaker than in Central Luzon. Bacolod seed depots serve as transshipment points for southern island distribution.
Cagayan Valley
Isabela and Cagayan provinces present frontier expansion potential as irrigation investments from the National Irrigation Administration extend coverage. Upland rainfed zones in Quirino and Nueva Vizcaya remain underpenetrated, with saved seed dominating smallholder procurement. Tuguegarao City hosts regional seed quality control laboratory capacity easing varietal registration bottlenecks.
Philippines Hybrid Rice Seed Market Competitive Landscape
Player mix skews toward integrated breeding-to-distribution conglomerates with proprietary parental line libraries and captive seed processing infrastructure. Market structure concentrates around three operational tiers: multinational technology licensors with advanced biotech trait platforms, domestic seed houses with localized germplasm adaptation capabilities, and regional distributors with credit-extension relationships to farming cooperatives. Dominant competitive moves include strategic partnerships between Chinese germplasm suppliers and Philippine multipliers, plus backward integration into breeder seed production to reduce import dependency.
Among multinational technology providers, Bayer AG and Syngenta Group occupy positions emphasizing biotech trait integration into hybrid parental lines. Corteva Agriscience represents the integrated breeding-to-commercialization archetype with direct farm engagement capabilities. Domestic multiplier SL Agritech Corporation anchors localized adaptation programs, while Yuan Longping High-Tech Agriculture Co. Ltd exemplifies the Chinese germplasm supply tier critical to yield stability improvements. These named entities illustrate how competitive positioning stratifies across technology licensing, domestic multiplication, and upstream germplasm provision.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| SL Agritech Corporation |
| Vietnam National Seed Corporation (Vinaseed) |
| UPL (Advanta Seeds) |
| Bayer AG |
| SeedWorks International Private Limited |
| Bioseed (DCM Shriram Ltd) |
| Syngenta Group |
| Others |
Value Network & Pricing Analysis
Two-line system germplasm displacing three-line varieties from Chinese breeding programs simultaneously redraws procurement geography toward direct breeder relationships and compresses margin structures for traditional distributor intermediaries. The Rice Competitiveness Enhancement Fund subsidy mechanics amplify this shift by favoring volume purchasers with capital for upfront seed payments.
Pricing Analysis
Three-line system hybrids trade at discount tiers against two-line premium lines with superior yield stability under tropical stress. Pricing stratifies across certified distributor channels, direct breeder sales, and cooperative aggregators, with volume scale and technical support bundling as the primary differentiation drivers. Cost compression in the cooperative tier intensifies as commercial farms bypass intermediaries for direct procurement. Smallholder cooperatives exhibit highest price sensitivity; consolidated agricultural companies with mechanization capacity show lowest sensitivity due to yield-per-hectare optimization focus.
Supply Chain Analysis
Strait of Malacca transit underwrites germplasm flow from Chinese breeding programs to Philippine multiplication facilities. Parental line supply concentrates in China, with domestic seed processing anchored in Central Luzon and Ilocos Region. Breeder seed multiplication draws from Yuan Longping High-Tech Agriculture germplasm, proprietary domestic lines, and Syngenta biotech trait platforms. Single-source vulnerability in two-line system germplasm creates supply continuity exposure during phytosanitary disputes. Distribution runs through certified seed networks reaching irrigated lowlands, with direct sales gaining share among commercial operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against saved-seed propagation that erodes certified hybrid penetration among risk-averse smallholders. Brown-bag seed saving threatens royalty capture and varietal investment returns across the breeder ecosystem.
For Market Incumbents: Fortify breeder seed production capacity through backward integration into foundation stock multiplication, reducing import dependency on Chinese germplasm during trade friction. Secure channel control by embedding technical agronomists directly with Rice Competitiveness Enhancement Fund beneficiary farms, displacing cooperative intermediation. Priority R&D investment targets drought-tolerant lines for Mindanao rainfed expansion.
For New Entrants and Emerging Players: Lead with digital platform distribution targeting younger farmer demographics in Pangasinan and Nueva Ecija provinces where mobile-enabled procurement bypasses traditional markups. Penetrate the disease-resistant premium tier fastest, as bacterial leaf blight pressure intensifies demand for stacked resistance traits with limited current supply. Go-to-market angle emphasizes real-time yield performance data sharing through farmer digital communities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed agricultural input distributors holding captive relationships in Central Luzon irrigation corridors. Long-term viability hinges on exposure to commercial farm consolidation rather than cooperative-dependent revenue streams. Signal to monitor: Department of Agriculture adjustments to Rice Competitiveness Enhancement Fund allocation rules redirecting subsidy flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breeder Seed Production | Captive supply of foundation stock reduces germplasm import dependency during phytosanitary disputes. |
| Digital Platform Distribution Buildout | Mobile-enabled procurement disintermediates cooperative channels and compresses price transparency. |
| Drought-Tolerant Varietal Development | Mindanao rainfed expansion opens underpenetrated volume pools beyond Central Luzon saturation. |
| Technical Agronomist Embedded Support | Direct farm engagement secures Rice Competitiveness Enhancement Fund subsidy flow capture. |
| Disease Resistance Trait Stacking | Bacterial leaf blight and tungro virus pressure intensifies demand for premium-resistant hybrid tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department of Agriculture subsidy disbursement records, Philippine Rice Research Institute varietal trial data, and National Seed Quality Control Services certification databases. Breeding program directors at domestic seed houses, procurement managers at consolidated agricultural companies, cooperative aggregation officers, distributor network heads, and National Irrigation Administration planning officers provided structured interviews. Customs germplasm import records and Seed Industry Development Act regulatory filings supplied trade flow validation. Bottom-up seed volume estimates triangulated against top-down agricultural census cultivation area data.
Segmentation dimensions modeled include product type stratification, end-user buyer archetype, distribution channel configuration, and application context across irrigated versus rainfed zones. CAGRs derived from historical seed certification volumes projected through elasticity-adjusted demand curves over the projection horizon. Forecast inputs incorporated Rice Tariffication Law revenue recycling mechanics, irrigation infrastructure investment pipelines from the National Irrigation Administration, and generational farmer demographic transition rates.
The analysis sits within stated boundaries; outcomes outside sustained Rice Competitiveness Enhancement Fund allocation levels or stable germplasm import protocols would require recalibration. Forecasts assume continued bacterial leaf blight and tungro virus pressure trajectory, urea price volatility within historical bands, and cooperative displacement pace matching recent Department of Agriculture procurement protocol revisions. Practitioners should keep alternative scenarios live as Rice Tariffication Law political sustainability and Chinese germplasm trade policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Philippines Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Field Crop Seeds Market
Seeds
Africa Peas Market
Seeds
India Vegetable Seed Market
Seeds
Organic Chia Seeds Market
Seeds
Asparagus Seeds Market
Seeds
Safflower Seeds Market
Seeds
Avena Sativa Market
Seeds
Mexico Vegetable Seed Market
Seeds
North America Grain Seed Market
Seeds
Psyllium Seed Market
Seeds
Global Maize Seed Market
Seeds
Rapeseed Market
Seeds
China Seed Market
Seeds
Tomato Seed Market