
 Nepal Seeds Market | 2026-2036
Nepal Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Nepal Seeds Market Insights
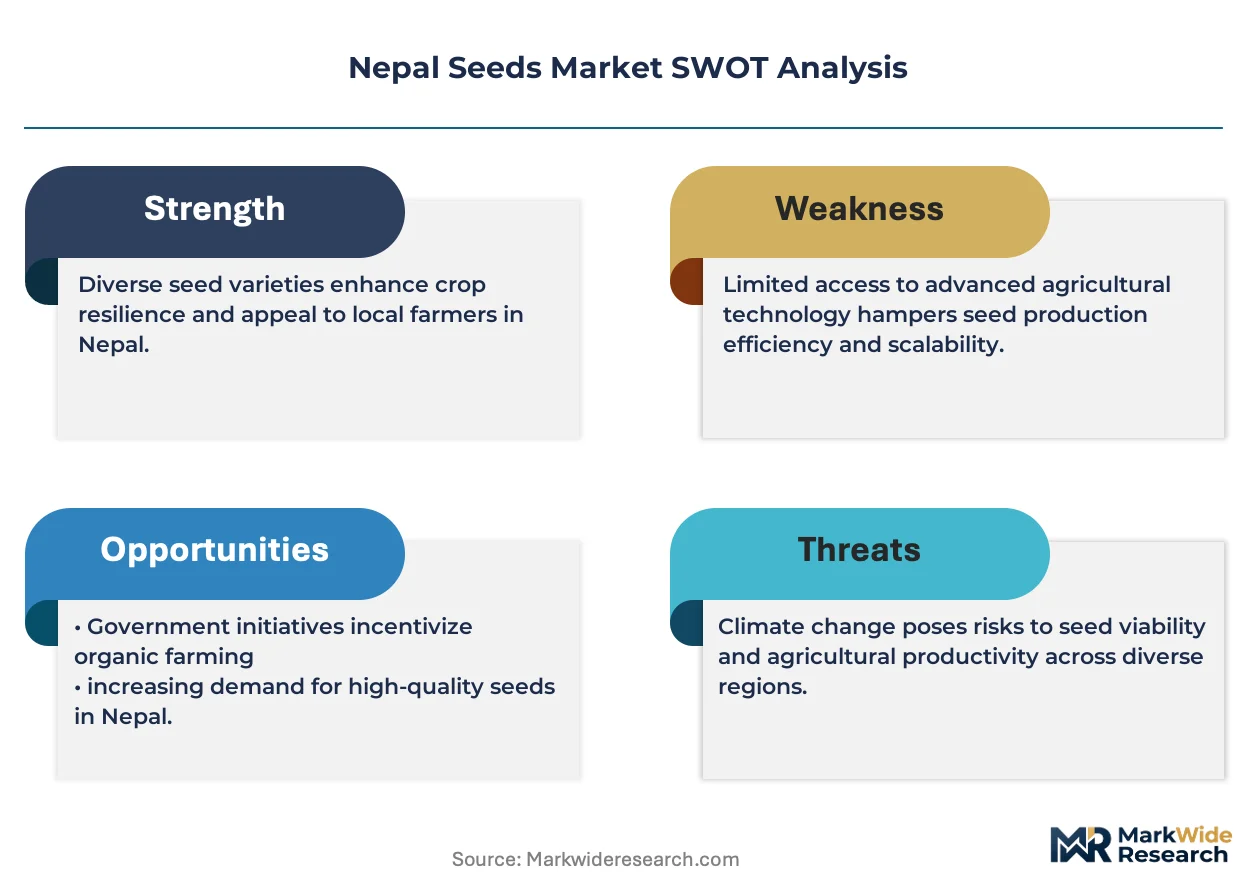
Nepal's Seed Quality Control Act is broadening compliance costs for new entrants while consolidating advantage among established suppliers. UPL Limited leverages its integrated crop protection portfolio to bundle seed-chemical offerings across the Terai corridor. Annapurna Seeds anchors its position through deep distribution into district-level agricultural cooperatives. Syngenta Group competes via proprietary hybrid rice and maize genetics adapted to Nepal's altitudinal gradients.
Seeds comprise embryonic plants enclosed in protective outer coverings, with commercial viability determined by germination rate, genetic purity, moisture content below 12%, and seed vigor indices. Their primary purpose is to establish uniform crop stands that convert into predictable agricultural yields. Cereal seeds occupy the dominant revenue share given rice and maize coverage across Nepal's food security priorities, while vegetable seeds capture expanding margin pools from peri-urban commercial farming near Kathmandu and Pokhara. Oilseed seeds sustain steady offtake from mustard and sunflower rotations in the mid-hills.
Nepal's Ministry of Agriculture and Livestock Development, the National Seed Board, and BIS-aligned seed testing laboratories collectively enforce certification tiers that determine market access for domestic and imported genetic material. These frameworks elevate product standards for germination and field establishment while channeling procurement toward registered suppliers. Stakeholders must monitor evolving varietal registration timelines and hybrid seed import protocols as policy shifts reshape competitive access.
Market Dynamics
Nepal's Seed Quality Control Act enforcement is compressing market access for uncertified suppliers while channeling procurement toward registered domestic and imported genetic material. This regulatory tightening is accelerating consolidation among established seed houses with laboratory testing capabilities.
Growth Catalysts
- Terai Irrigation Expansion:Canal network extensions across southern plains districts enable hybrid rice and maize deployment at commercial scale. Water security converts subsistence plots into certified seed offtake zones.
- National Seed Board Registration:Streamlined varietal approval timelines for priority cereals reduce market entry lag for improved genetics. Registered hybrids gain preferential placement in government procurement programs.
- Cooperative Aggregation:District-level agricultural cooperatives consolidate smallholder demand into volume contracts. Bulk procurement pools lower per-unit certification costs for member farmers.
Market Restraints
- Import Dependency for Parent Lines:Hybrid maize and vegetable seeds rely on captive parent stock from Indian and Chinese breeders. Foreign exchange volatility and phytosanitary delays compress margin predictability.
- Mid-Hills Logistics Costs:Road infrastructure gaps in hill districts inflate transport costs for temperature-sensitive seed lots. Germination degradation during extended transit reduces effective supply.
- Laboratory Capacity Bottlenecks:BIS-aligned seed testing facilities concentrate in Kathmandu and Pokhara. Remote district applicants face extended certification queues during planting-season surges.
Strategic Opportunities
- Peri-Urban Vegetable Intensification:Kathmandu Valley and Pokhara corridor commercial farms seek high-value tomato, cauliflower, and chili hybrids. Premium vegetable seed margins exceed cereal benchmarks.
- Climate-Adaptive Varietal Development:Heat-tolerant rice lines and drought-resistant maize hybrids address monsoon variability. National agricultural research stations partner with international gene banks for trait introduction.
- Digital Extension Platforms:Mobile-based agronomy advisory and seed authentication tools reach remote cooperatives. Real-time germination data and planting calendars reduce information asymmetry.
Industry Challenges
- Seed Analyst Certification Shortfalls:Qualified germination testing personnel concentrate in central laboratories. District-level staffing gaps delay field inspection and certification turnaround.
- Counterfeit Seed Infiltration:Informal channels distribute mislabeled open-pollinated varieties as branded hybrids. Farmer recourse mechanisms remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nepal Seeds Market |
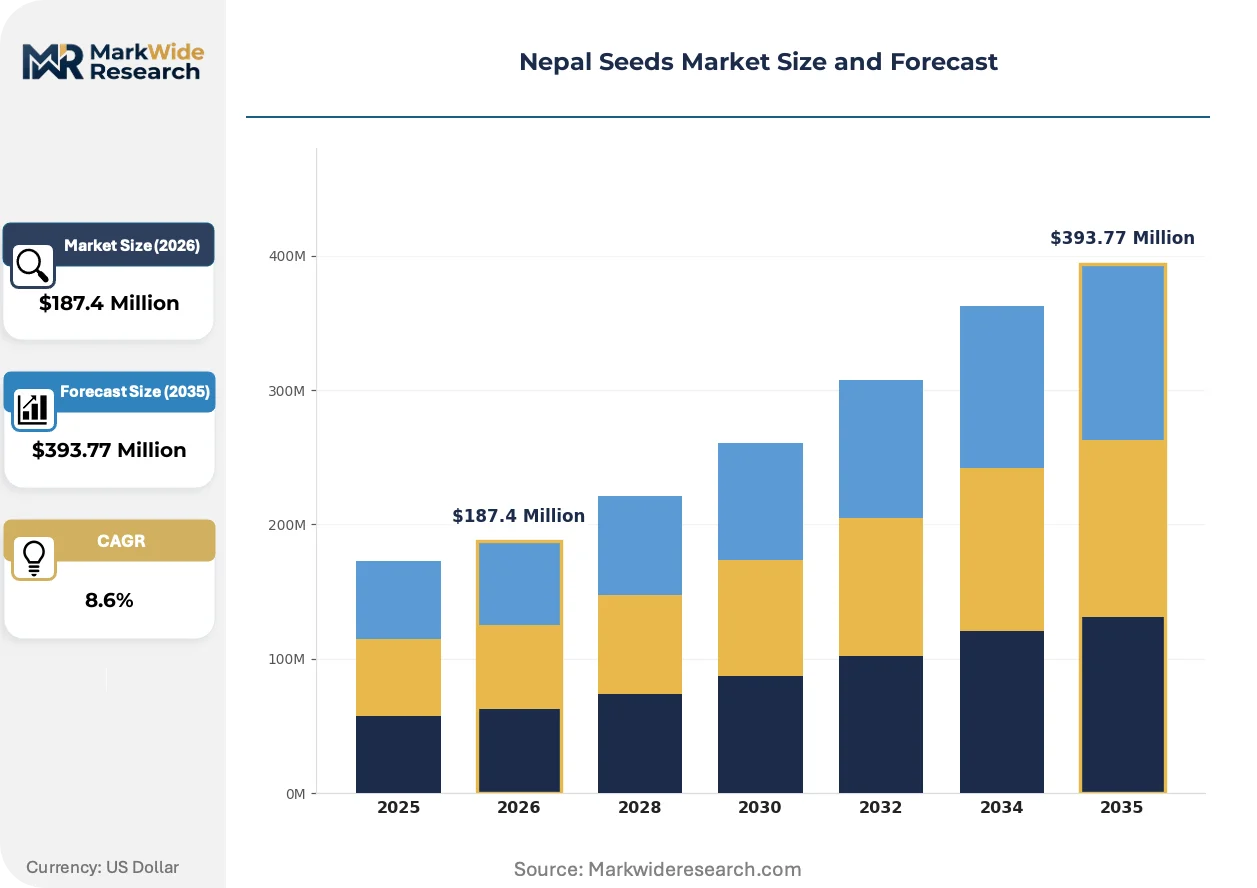
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Oilseed Seeds, Pulses, Vegetable Seeds End Use: Commercial Farming, Home Gardening, Organic Farming, Agroforestry Distribution Channel: Retail Outlets, Online Marketplaces, Agricultural Cooperatives, Direct Sales Packaging Type: Bulk Packaging, Retail Packaging, Seed Bags, Eco-friendly Packaging |
| Companies Covered | Anamolbiu Private Limited, UPL Limited, National Seed Vision Company Limited, CGNS Seeds Pvt. Ltd., Annapurna Seeds, Lumbini Seed Company Pvt. Ltd, Pabitra Seed Company Pvt. Ltd., East-West Seed International B.V., Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nepal Seeds Market Trends and Innovations
Genetic improvement pipelines and digital distribution infrastructure are reshaping how seed reaches Nepali farmers. Three developments merit particular attention.
Marker-assisted selection is electrifying breeding timelines for rice and maize adaptation. Nepal Agricultural Research Council stations deploy genomic screening to accelerate stress-tolerance stacking. Private licensees translate these advances into region-specific hybrid releases within compressed development cycles.
Nepal's Seed Quality Control Act amendments tighten germination labeling requirements and traceability obligations. Registered suppliers must maintain lot-level documentation through distribution. Compliance investments favor integrated houses with captive laboratory and logistics assets over fragmented traders.
Cooperative procurement managers increasingly demand performance guarantees beyond standard germination rates. Seed houses respond with establishment insurance and replant commitment programs. This risk-transfer model concentrates in Terai commercial farming zones where input costs represent significant capital exposure.
Nepal Seeds Market Segmentation
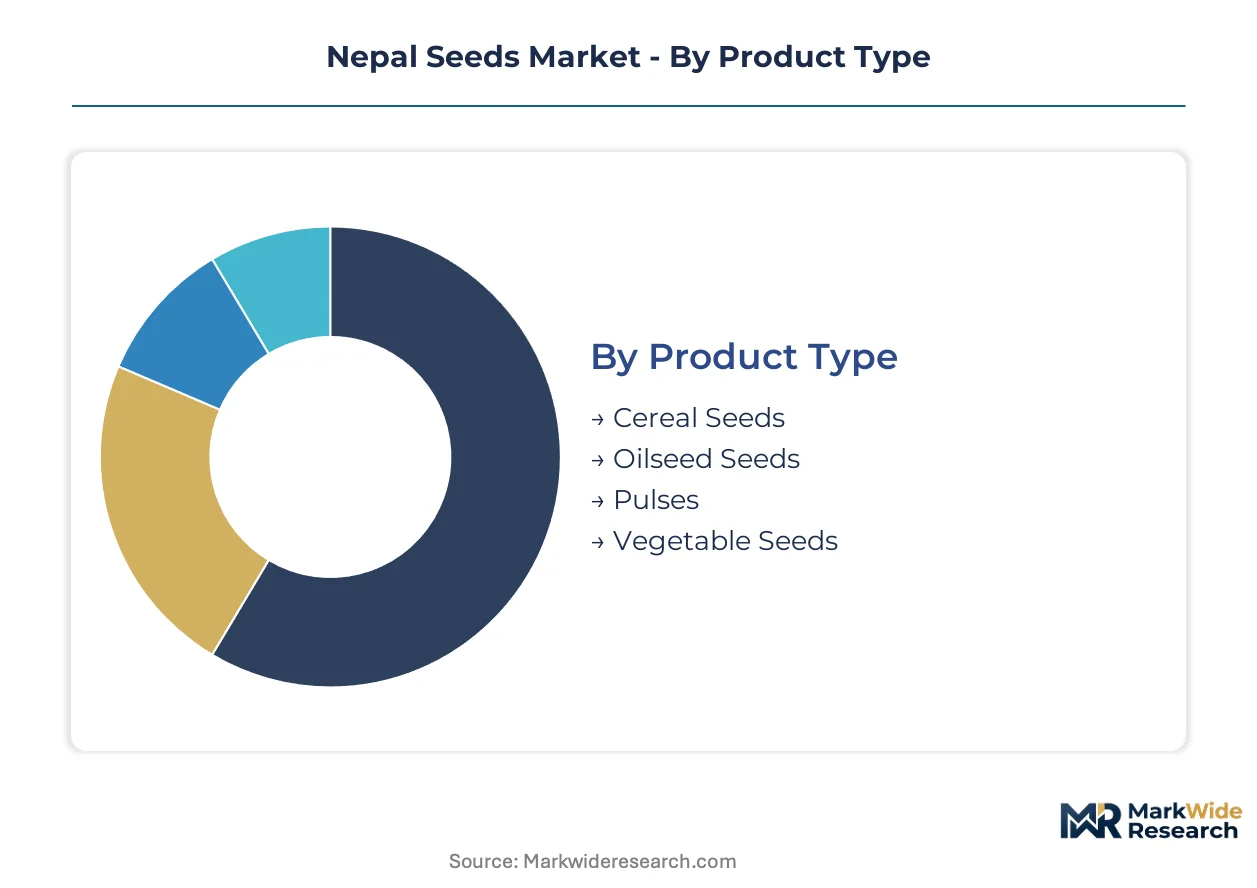
Segmentation reveals how seed procurement patterns diverge across Nepal's farming systems. Terai commercial operations prioritize certified hybrids through cooperative channels, while mid-hills smallholders access open-pollinated varieties via retail networks. Understanding these splits exposes margin concentration and distribution leverage points for suppliers.
Product Type:
Replacement cycles for cereal genetics drive varietal turnover as farmers upgrade to climate-adaptive lines. Seed houses time hybrid releases to coincide with National Seed Board registration windows, compressing development-to-deployment timelines.
- Cereal Seeds:Rice and maize hybrids dominate certified seed offtake, with germination standards enforced under the Seed Quality Control Act. Demand clusters across Jhapa, Banke, and Rupandehi districts where canal irrigation supports commercial-scale deployment. National food security priorities channel subsidy flows toward improved cereal genetics.
- Vegetable Seeds:Tomato, cauliflower, and chili hybrids command premium positioning in Kathmandu Valley and Pokhara corridor peri-urban farms. Heat-tolerant lines from international gene banks address monsoon variability, with shorter replacement cycles than field crops enabling faster trait turnover.
- Oilseed Seeds:Mustard and sunflower rotations sustain steady offtake across mid-hill districts.
- Pulses:Lentil and chickpea open-pollinated varieties serve subsistence and export-oriented production zones.
Volume placements concentrate in Cereal Seeds; the faster expansion belongs to Vegetable Seeds.
End Use:
Cost tier stratification separates input-intensive commercial operations from capital-constrained home gardeners. Certification requirements and irrigation access create divergent procurement economics across use cases.
- Commercial Farming:Terai belt operations deploy hybrid rice and maize at scale, absorbing certification premiums through yield gains. Cooperative aggregation consolidates smallholder demand into volume contracts, reducing per-unit compliance costs. BIS-aligned germination testing validates lot performance before planting-season deployment.
- Organic Farming:Certified organic producers source untreated open-pollinated varieties through specialized cooperatives. Premium crop premiums offset lower yield trajectories, with varietal selection constrained by prohibited input lists. Mid-hills organic clusters in Kavre and Sindhupalchok drive niche demand.
- Home Gardening:Urban and peri-urban households access small-format retail packs through district agricultural service centers.
- Agroforestry:Integrated tree-crop systems in mid-hills districts utilize fodder and timber seed lots alongside annual crops.
Commercial Farming absorbs the largest certified seed volumes; Organic Farming climbs fastest on export premium incentives.
Distribution Channel:
Customer type fragmentation shapes channel economics, with cooperative managers demanding performance guarantees beyond standard germination rates. Digital platforms are penetrating remote districts where physical infrastructure gaps persist.
- Agricultural Cooperatives:District-level bodies consolidate smallholder demand into bulk procurement contracts. Member farmers access certified hybrids at negotiated rates, with cooperative managers screening suppliers for laboratory testing capabilities. Seed houses respond with establishment insurance and replant commitment programs.
- Retail Outlets:Agricultural service centers and private dealers stock open-pollinated varieties and small-format hybrid packs. Germination labeling under Seed Quality Control Act amendments enables farmer verification, though counterfeit infiltration remains a channel risk.
- Direct Sales:Large commercial farms source parent-line dependent hybrids through breeder-direct arrangements.
- Online Marketplaces:Mobile-based platforms extend varietal catalogs to remote cooperatives, with authentication tools reducing information asymmetry.
Agricultural Cooperatives handle the heaviest certified seed flows; Online Marketplaces gain share fastest on digital extension penetration.
Packaging Type:
Supply concentration in Kathmandu and Pokhara laboratories dictates packaging logistics for temperature-sensitive lots. Transit duration to remote districts influences format selection and germination preservation.
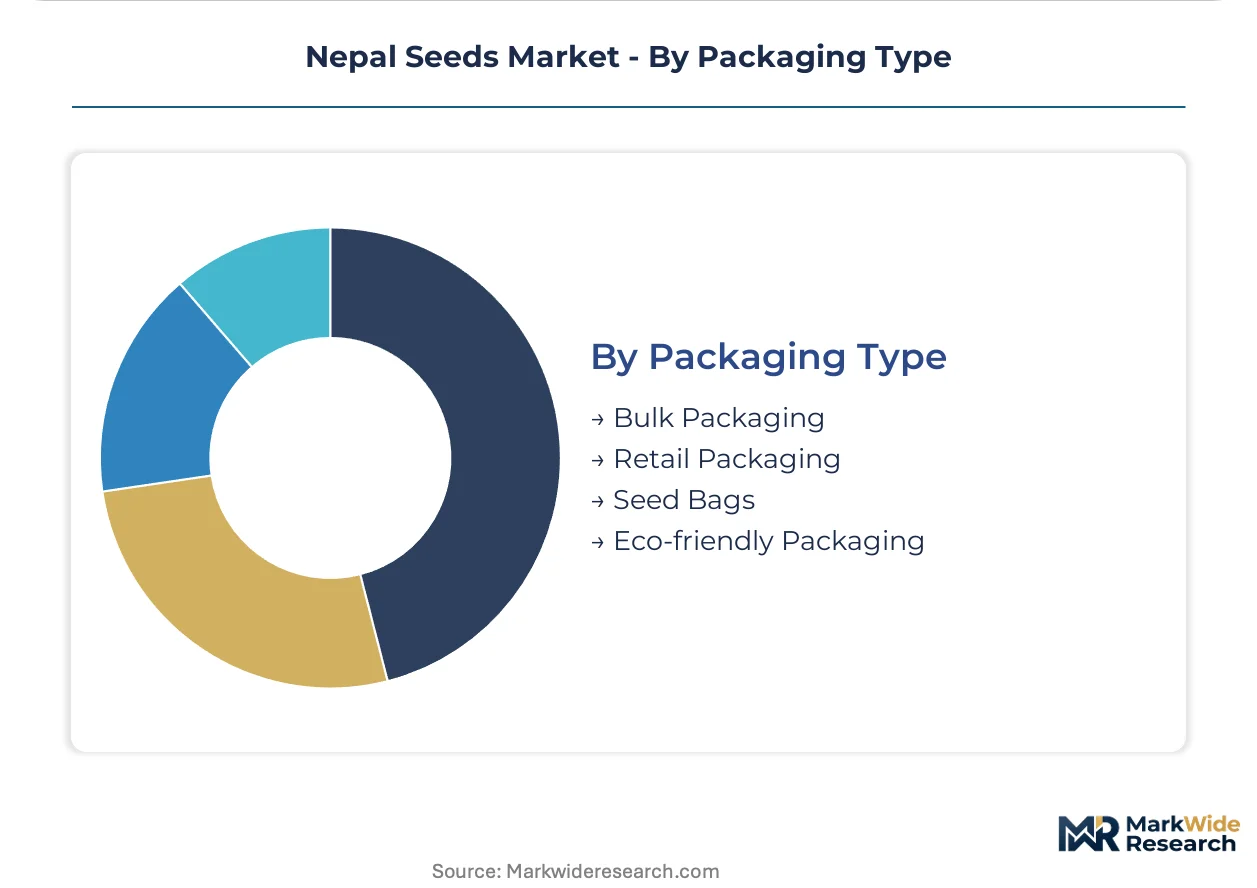
- Bulk Packaging:50-kilogram woven sacks serve cooperative procurement and large commercial farms. Moisture barriers and ventilation specifications maintain seed vigor during extended Terai storage. Bulk formats minimize per-unit logistics costs for high-volume cereal hybrid deployment.
- Retail Packaging:1-5 kilogram laminated pouches target smallholder and home gardening segments. Printed germination rates and varietal registration numbers comply with Seed Quality Control Act traceability obligations. Kathmandu Valley retailers stock diverse vegetable and pulse formats.
- Seed Bags:Standard woven polypropylene containers dominate open-pollinated variety distribution.
- Eco-friendly Packaging:Biodegradable materials address organic farming certification requirements and urban consumer preferences.
Bulk Packaging moves the greatest tonnage; Eco-friendly Packaging expands most quickly on organic segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nepal Seeds Market concentrates along the Terai belt where special economic zone incentives for agribusiness cluster certified seed demand. This southern plains corridor anchors commercial hybrid deployment through irrigation-enabled farming operations.
Jhapa District
Canal-fed rice cultivation drives certified hybrid offtake across eastern Terai commercial farms. The Seed Quality Control Act mandates germination labeling for all distributed lots. Birtamode and Damak trading hubs channel bulk cereal seed flows into cooperative procurement networks.
Banke District
Maize seed demand surges where tube-well irrigation supports double-cropping rotations. National Seed Board registration requirements filter market access toward tested genetic material. Nepalgunj serves as the western Terai distribution nexus for parent-line dependent hybrids.
Rupandehi District
Vegetable seed premiums attract peri-urban commercial farms supplying Kathmandu and Pokhara markets. BIS-aligned testing protocols enforce quality tiers for imported tomato and cauliflower genetics. Butwal agro-industrial zone hosts regional packaging and cold-storage facilities.
Kavre District
Organic certification requirements shape open-pollinated variety demand among mid-hills smallholders. The Ministry of Agriculture and Livestock Development channels subsidy flows toward untreated seed lots. Dhulikhel organic clusters source specialty pulses through district cooperative aggregators.
Kathmandu Valley
Home gardening and peri-urban vegetable intensification sustain retail-format seed pack demand. Seed Quality Control Act traceability obligations extend to urban agricultural service centers. Lalitpur and Bhaktapur urban corridors stock diverse vegetable hybrids for terrace and greenhouse operations.
Nepal Seeds Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Nepal's seed procurement channels. The market structure tilts toward consolidation as regulatory compliance costs compress margins for uncertified entrants. Three archetypes dominate: integrated crop protection houses with bundled chemical-seed offerings, domestic breeders with cooperative distribution depth, and international hybrid specialists with proprietary genetics. Competitive moves center on laboratory certification investments and cooperative partnership deepening.
Among India-linked diversified houses, UPL Limited anchors the crop protection bundling archetype through its integrated portfolio reach. Annapurna Seeds exemplifies domestic cooperative-channel specialization with district-level agricultural cooperative penetration. Syngenta Group occupies the proprietary genetics tier through hybrid rice and maize lines adapted to Nepal's altitudinal gradients.
| Leading Market Players |
|---|
| Anamolbiu Private Limited |
| UPL Limited |
| National Seed Vision Company Limited |
| CGNS Seeds Pvt. Ltd. |
| Annapurna Seeds |
| Lumbini Seed Company Pvt. Ltd |
| Pabitra Seed Company Pvt. Ltd. |
| East-West Seed International B.V. |
| Syngenta Group |
| Others |
Pricing and Supply Chain Analysis
Nepal's Seed Quality Control Act germination mandates gate both qualified supply and premium-tier pricing access. Only registered suppliers with BIS-aligned laboratory capabilities capture certified seed premiums, while uncertified traders face margin compression from compliance exclusion.
Pricing Analysis
Short lead-time premiums dominate procurement economics as planting-season surges compress certification queues. Contract-based long-term offtake secures hybrid parent lines from Indian and Chinese breeders, insulating against foreign exchange volatility. Price differentiation rests on certification grade and cooperative volume scale. Margins are tightening due to laboratory capacity bottlenecks in Kathmandu and Pokhara. Smallholder retail buyers exhibit highest price sensitivity; Terai commercial farms absorb certification premiums through yield-gain economics.
Supply Chain Analysis
Direct-to-cooperative channels handle certified hybrid demand from Terai commercial operations. Parent stock for hybrid maize and vegetable seeds draws from India and China, with germplasm dependencies concentrated among captive breeder networks. Raw material inputs encompass foundation seed lots, moisture-barrier packaging substrates, and cold-chain refrigerants. Single-source vulnerability runs through Indian parent-line suppliers exposed to phytosanitary delays. Distribution runs through district-level agricultural cooperatives consolidating smallholder demand into bulk procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nepal's seeds market is a vertical-integration race where laboratory certification assets and cooperative distribution depth determine competitive survival. Players are pursuing backward integration into captive germplasm testing and cold-storage infrastructure.
For Market Incumbents: Deploy laboratory certification capacity as the primary defensive lever. Expand BIS-aligned testing facilities beyond Kathmandu and Pokhara to capture district-level certification demand before National Seed Board registration windows close. Channel control through cooperative partnership deepening protects against Syngenta Group and UPL Limited bundling strategies. Capacity addition in Jhapa and Banke districts secures Terai belt distribution anchor points. For New Entrants and Emerging Players: Launch via mobile-based digital extension platforms reaching remote mid-hills cooperatives underserved by physical infrastructure. Peri-urban vegetable intensification in Kathmandu Valley and Pokhara corridor represents the most penetrable white-space target, with premium tomato and cauliflower hybrid margins exceeding cereal benchmarks. Seed authentication tools and real-time germination data reduce information asymmetry as the go-to-market angle. For Investors and Strategic Acquirers: National Seed Board registration timeline compression is the leading indicator that cooperative procurement consolidation will accelerate. Long-term viability over the next decade hinges on laboratory asset ownership and district-level distribution density. Acquisition targets include domestic pure-play specialists with deep cooperative penetration and pending varietal registrations. Monitor BIS laboratory accreditation backlogs as the signal for certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | BIS-aligned testing facilities in Jhapa and Banke reduce National Seed Board approval lag for hybrid releases. |
| Cooperative Partnership Deepening | Volume contracts with district agricultural cooperatives consolidate Terai smallholder demand into certified seed offtake. |
| Parent Line Supply Agreement | Long-term offtake with Indian and Chinese breeders insulates hybrid maize programs from foreign exchange volatility. |
| Digital Extension Platform Launch | Mobile-based agronomy advisory reaches remote mid-hills cooperatives where physical infrastructure gaps persist. |
| Climate-Adaptive Varietal Development | Heat-tolerant rice lines from Nepal Agricultural Research Council partnerships address monsoon variability in Terai districts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with seed company executives, National Seed Board registration officers, district cooperative procurement managers, and Nepal Agricultural Research Council breeders combined with secondary validation. Secondary sources encompassed National Seed Board varietal registration databases, Ministry of Agriculture and Livestock Development subsidy disbursement records, BIS laboratory accreditation lists, and agricultural cooperative membership directories. Bottom-up cooperative procurement volume estimates triangulated against top-down cereal and vegetable seed production statistics.
Data-stream reconciliation across product type, end use, distribution channel, and packaging format segmentation underpinned the analytical framework. CAGRs were derived through trend extrapolation of certified seed adoption rates and cooperative aggregation penetration. Modeled dimensions included cereal versus vegetable versus oilseed product splits, commercial farming versus organic farming versus home gardening end-use cases, and bulk versus retail packaging formats. Forecast inputs incorporated irrigation canal expansion timelines in Terai districts and National Seed Board staffing capacity projections.
Policy reversals on hybrid seed import protocols, foreign exchange volatility affecting parent line procurement, and laboratory accreditation delays are the dominant revision risks. Forecasts reflect assumptions regarding Seed Quality Control Act enforcement consistency and cooperative consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Australia Forage Seed Market
Seeds
Flaxseed (Linseed) Market
Seeds
Apple Seed Oil Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Brazil Forage Seed Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
South America Seed Market
Seeds
Sesame Seeds Market
Seeds
Custom Selected Seed Market
Seeds
China Vegetable Seed Market
Seeds
Vietnam Seed Market
Seeds
Mustard Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
South America Forage Seed Market
Seeds
Global Oilseed Market