
 Wooden and Plywood Packaging Market | 2026-2036
Wooden and Plywood Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden and Plywood Packaging Market Analytics
E-commerce fulfillment is repositioning pallet demand toward standardized sizes and higher turnover rates. Kamps Pallets Inc. leverages its national depot network to sustain rapid exchange cycles in retail distribution. Nefab AB specializes in engineered plywood crating for electronics exports, while CHEP dominates pooled pallet pools across North American grocery chains.
Wooden and plywood packaging encompasses fabricated timber structures—pallets, crates, boxes, and dunnage—typically constructed from softwood, hardwood, or engineered plywood sheets bonded with moisture-resistant adhesives, designed to protect goods during handling, storage, and transit. Plywood boxes and crates offer superior strength-to-weight ratios for electronics and pharmaceutical shipments where moisture resistance matters. Marine grade material commands premium positioning in export crating, while structural grade pallets anchor volume demand across manufacturing logistics.
ISPM 15 standards enforced by national plant protection agencies mandate heat treatment or methyl bromide fumigation for cross-border wood packaging, directly shaping supplier certification costs and market access. The EPA and state-level forestry regulators in the United States impose additional logging and treatment standards that filter through to material sourcing. Stakeholders must monitor evolving phytosanitary rules and plywood adhesive emission limits as sustainability criteria harden in buyer procurement specifications.
Market Dynamics
ISPM 15 phytosanitary mandates are compressing supplier certification timelines while e-commerce fulfillment accelerates pallet turnover requirements, forcing parallel investments in heat-treatment capacity and depot network density.
Growth Catalysts
- Cross-border trade compliance:ISPM 15 enforcement by national plant protection agencies in Germany, China, and the United States is mandating heat-treated wood packaging for all export shipments, creating baseline demand for certified suppliers.
- Electronics export crating:Engineered plywood boxes with moisture-resistant adhesives are displacing corrugated alternatives for semiconductor and pharmaceutical shipments where humidity control is critical.
- Retail distribution centralization:Grocery and mass-merchant consolidation around automated distribution centers is standardizing pallet specifications to 48x40 inch footprints for conveyor compatibility.
Market Restraints
- Softwood lumber price volatility:Construction sector competition for southern yellow pine and spruce-pine-fir is compressing packaging margins during housing booms.
- Heat-treatment capacity concentration:ISPM 15-certified kiln infrastructure clusters in Germany, the United States, and China, leaving exporters in peripheral markets dependent on third-party treatment fees.
- Plastic pallet substitution:HDPE pooled pallets from CHEP and competitors are capturing pharmaceutical and food-grade applications where hygiene audits predominate over cost.
Strategic Opportunities
- India manufacturing logistics:PLI scheme incentives for electronics and automotive assembly are creating first-mover openings for ISPM 15-certified crate suppliers near Chennai and Pune industrial corridors.
- Marine-grade plywood crating:Offshore wind component exports from Germany and Denmark require salt-spray-resistant engineered wood packaging with bonded construction.
- Digital depot networks:RFID-tracked pallet pools integrated with warehouse management systems are enabling per-use pricing models that displace capital purchase decisions.
Industry Challenges
- Certification timeline compression:ISPM 15 audit backlogs at national plant protection agencies in peak export seasons delay market access for new treatment facilities.
- Adhesive emission compliance:ECHA formaldehyde restrictions under REACH and evolving EPA air quality standards are forcing reformulation of moisture-resistant plywood bonding agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden and Plywood Packaging Market |
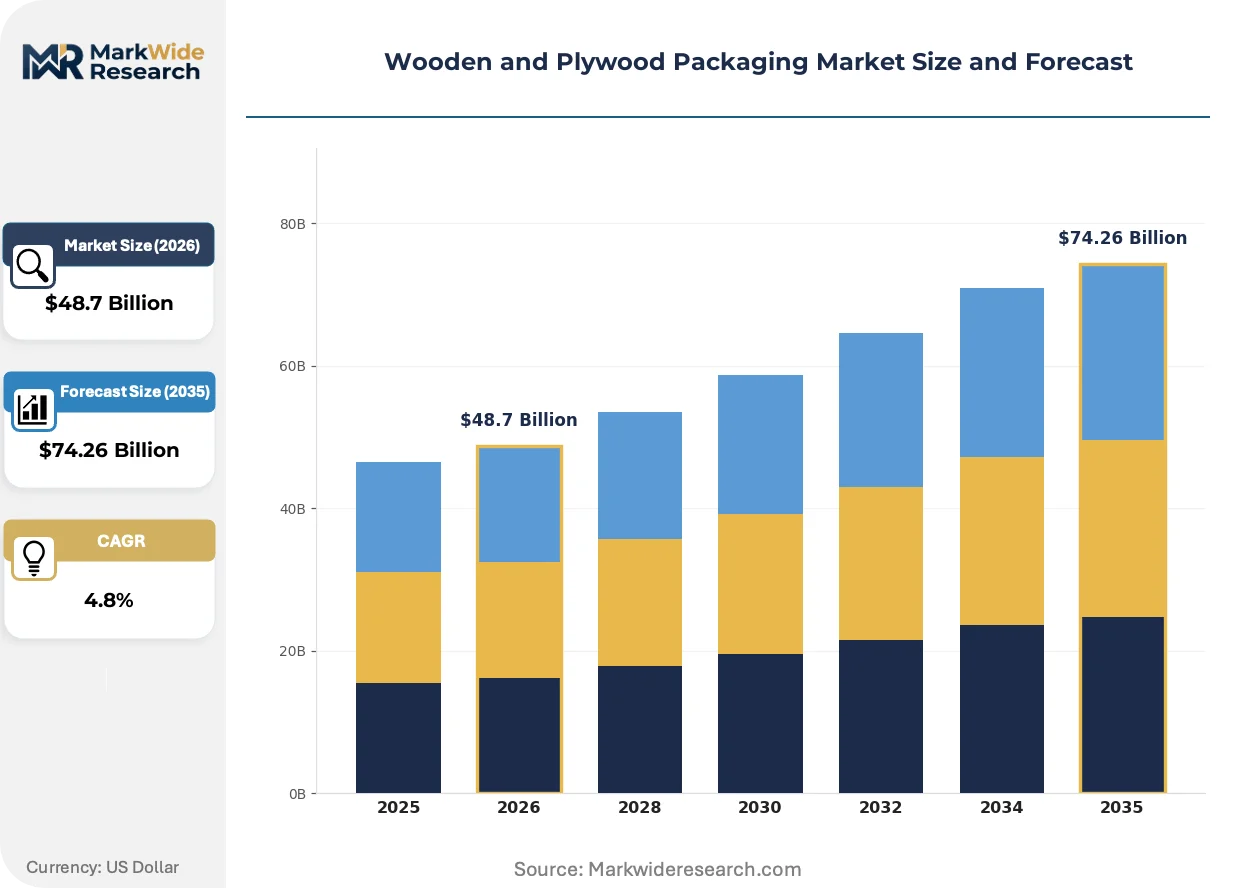
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood Boxes, Crates, Pallets, Decorative Packaging Application: Food & Beverage, Electronics, Furniture, Pharmaceuticals End User: Retail, E-commerce, Manufacturing, Logistics Material Grade: Marine Grade, Structural Grade, Interior Grade, Softwood |
| Companies Covered | Kamps Pallets Inc., Shur-way Industries Inc., Nefab AB, Arrington Lumber and Pallet Company, C&K Box Company Inc., CHEP, Rowlinson Packaging Ltd, Universal Forest Products Inc., PalletOne Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden and Plywood Packaging Market Evolving Landscape
Digital tracking systems and engineered material alternatives are restructuring how packaging assets circulate through supply chains, with sustainability metrics now embedded in procurement specifications.
Collapsible plywood crate systems with snap-fit corner joints are modularizing export packaging for automotive and aerospace components. Tier-one suppliers in Germany and the United States are adopting these systems for just-in-time sequencing deliveries to assembly plants. The technology is modularizing fleet management by reducing return-shipment cube requirements by two-thirds versus rigid alternatives.
EU Green Deal carbon border adjustment mechanisms are tightening embodied-emissions documentation requirements for wood packaging entering European markets. Suppliers must now provide chain-of-custody certification under FSC or PEFC frameworks alongside ISPM 15 compliance. German automotive OEMs and Dutch agricultural exporters are the first segments demanding combined certification bundles in supplier scorecards.
Buyer consolidation among third-party logistics providers is compressing pallet procurement cycles from annual contracts to quarterly volume commitments with price renegotiation clauses. Retail distribution networks in the United States are shifting toward pooled pallet programs that transfer asset ownership risk to pool operators. This pattern is most visible in grocery and mass-merchant verticals where CHEP and competitor pools dominate lane density between distribution centers and store backrooms.
Wooden and Plywood Packaging Market Segmentation
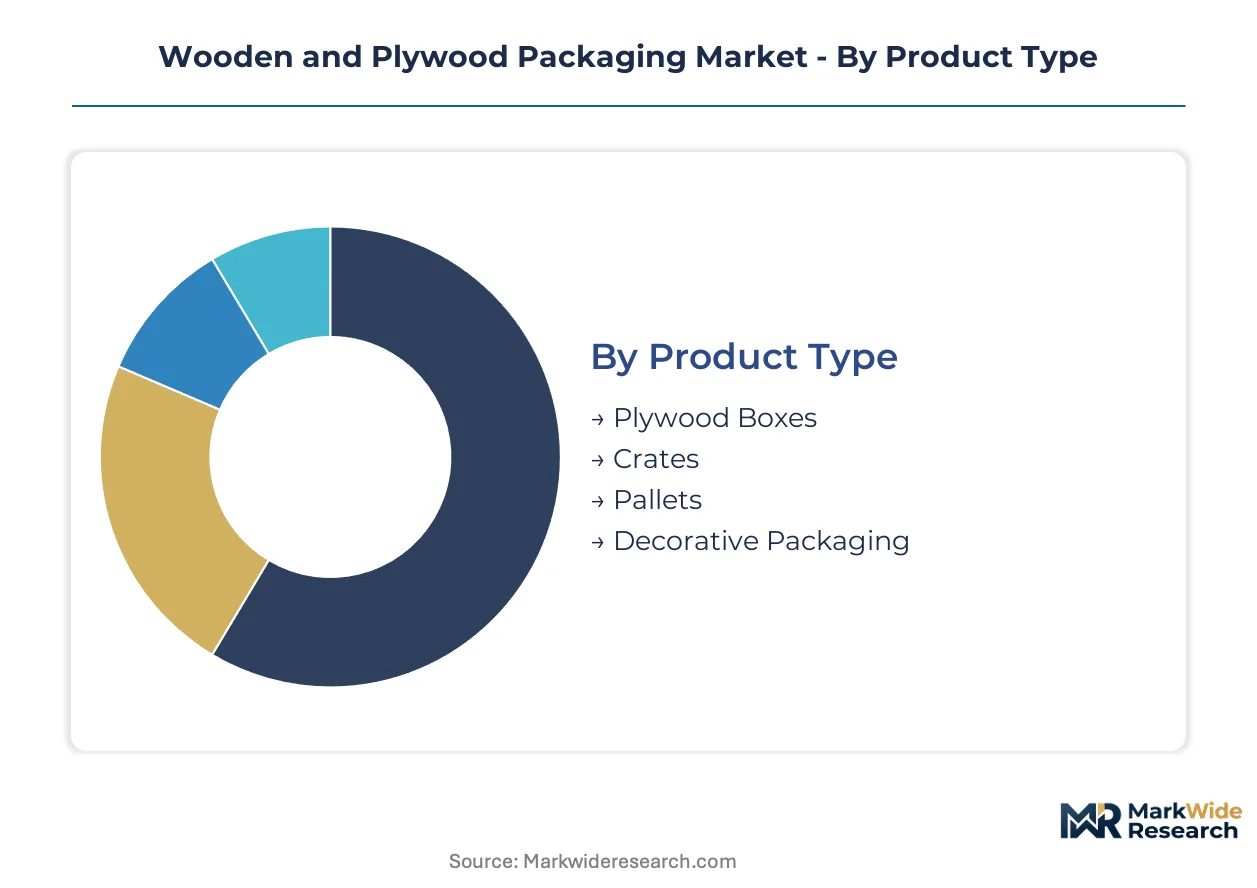
Segmentation in wooden and plywood packaging reflects divergent engineering requirements across export compliance, load-bearing specifications, and moisture resistance. Buyers select product formats and material grades based on phytosanitary mandates, handling automation compatibility, and end-use environmental exposure.
Product Type:
Customization versus standardization splits sharply across this category, with engineered formats commanding premium positioning against commodity pallet volumes.
- Pallets:Standardized 48x40 inch footprints dominate manufacturing and retail distribution, with ISPM 15 heat treatment certification mandatory for cross-border movement. Demand concentrates in automated distribution centers across Germany, China, and the United States where conveyor compatibility and rapid turnover cycles drive procurement.
- Plywood Boxes:Engineered panels bonded with moisture-resistant adhesives provide superior strength-to-weight ratios for electronics and pharmaceutical exports. Semiconductor manufacturers in East Asia and German automotive suppliers specify these for humidity-controlled shipments where corrugated alternatives fail.
- Crates:Heavy-duty timber framing accommodates irregular machinery and aerospace components, with collapsible snap-fit designs gaining traction for just-in-time sequencing.
- Decorative Packaging:Finished hardwood surfaces serve premium consumer goods and gift applications where unboxing experience influences brand positioning.
Leading the category by volume: Pallets. Expanding most quickly: Plywood Boxes.
Application:
Cost tier stratification separates commodity food-grade volumes from precision-engineered pharmaceutical and electronics specifications.
- Electronics:Semiconductor and component shipments demand marine-grade plywood with bonded construction and ESD-compliant lining. Taiwanese and South Korean manufacturers drive specifications for moisture-resistant crating protecting against salt-air exposure during ocean transit.
- Food & Beverage:Pooled pallet programs dominate grocery and mass-merchant distribution, with hygiene audits favoring heat-treated softwood over plastic alternatives in ambient storage.
- Pharmaceuticals:Cold-chain compliance and contamination prevention elevate material grade requirements, with EU GDP guidelines influencing packaging selection for temperature-sensitive biologics.
- Furniture:Knock-down flat-pack designs utilize structural-grade plywood for international retail distribution, optimizing container cube utilization.
Highest margin concentration: Electronics. Steepest volume trajectory: Food & Beverage.
End User:
Customer type determines asset ownership models, with capital purchase giving way to per-use pricing across logistics intermediaries.
- Logistics:Third-party providers consolidate procurement across multiple shipper accounts, compressing contract cycles from annual to quarterly commitments with price renegotiation clauses.
- Manufacturing:Automotive and industrial OEMs maintain captive pallet fleets for inbound supplier sequencing, with just-in-time delivery requirements dictating standardized specifications.
- E-commerce:Fulfillment networks prioritize lightweight, collapsible formats for last-mile efficiency, with return logistics costs driving modular design adoption.
- Retail:Grocery chains leverage pooled pallet programs transferring asset ownership risk to pool operators, with lane density between distribution centers and store backrooms determining operator selection.
Dominant volume share: Manufacturing. Gaining share fastest: E-commerce.
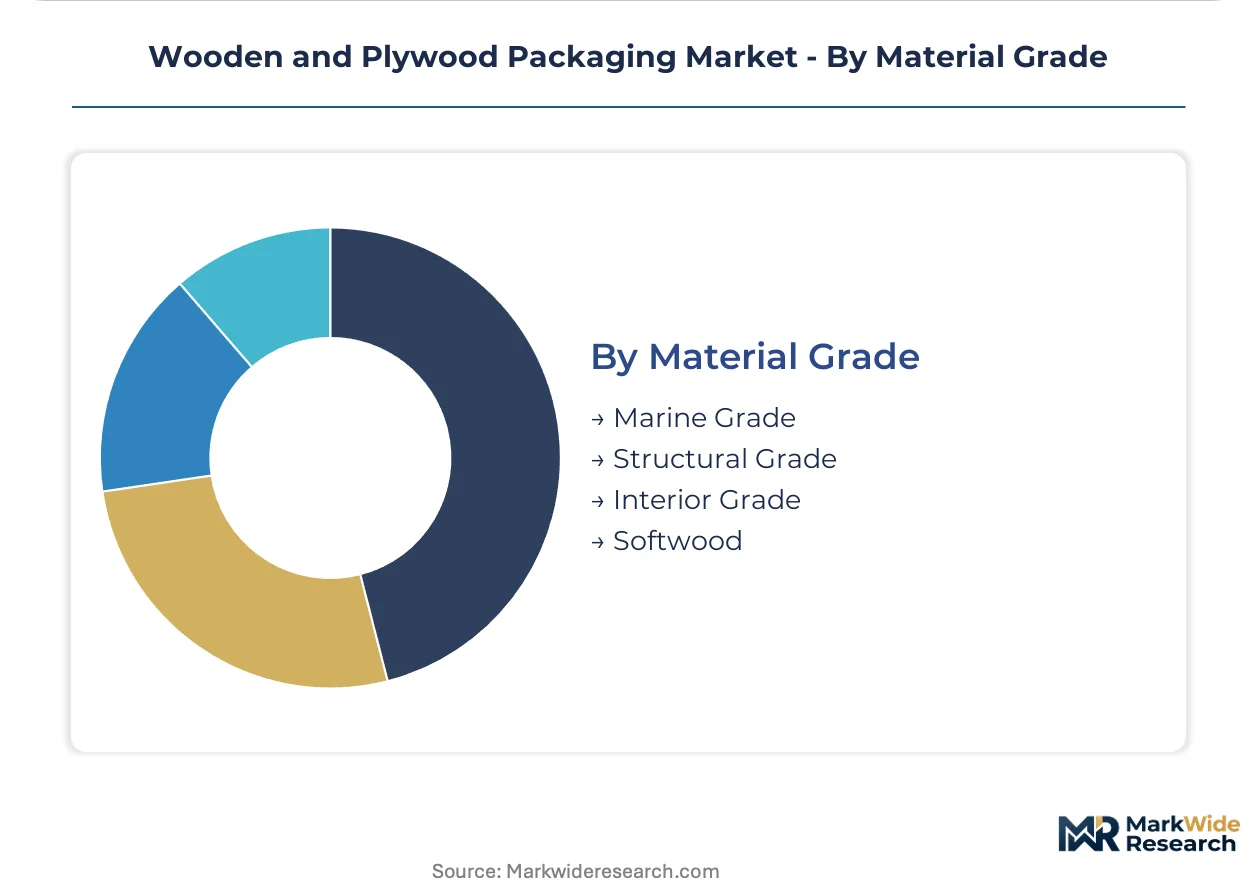
Material Grade:
Supply concentration in certified treatment capacity creates tiered access, with marine-grade availability constrained to specialized mills.
- Marine Grade:Phenolic-bonded plywood with void-free construction resists salt-spray degradation for offshore wind component exports. German and Danish suppliers command premium positioning for North Sea logistics serving turbine manufacturers.
- Structural Grade:Load-bearing softwood and hardwood laminations anchor volume demand across manufacturing logistics, with southern yellow pine and spruce-pine-fir competing with construction sector offtake.
- Interior Grade:Lower adhesive specifications suit domestic distribution and non-export applications where ISPM 15 compliance is unnecessary.
- Softwood:Commodity-grade timber serves single-use export crating, with price volatility tracking housing construction cycles and lumber futures.
Volume leadership: Structural Grade. Premium expansion: Marine Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, China, and the United States, while consumption spreads across manufacturing and logistics corridors in each. Export-oriented economies drive certified treatment demand. Import-heavy markets absorb standardized pallet flows through pooled programs.
United States
Southern yellow pine mills supply structural-grade pallets for automated distribution centers run by grocery and mass-merchant chains. EPA and state forestry regulators enforce logging standards that filter into material sourcing. The Southeast industrial corridor from Georgia to Alabama concentrates heat-treatment capacity serving Atlantic and Gulf export lanes.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify collapsible plywood crates for just-in-time supplier sequencing. EU Green Deal carbon border adjustments require FSC or PEFC chain-of-custody documentation alongside ISPM 15 compliance. The Port of Hamburg anchors North Sea export crating demand for offshore wind components bound for Denmark and the United Kingdom.
China
Electronics manufacturers in the Yangtze River Delta and Pearl River Delta drive marine-grade plywood specifications for semiconductor shipments. GB standards and MIIT regulations shape adhesive emission limits for bonded panel construction. Shenzhen and Shanghai logistics clusters concentrate pallet pooling infrastructure serving bonded warehouse zones.
India
PLI scheme incentives for electronics and automotive assembly near Chennai and Pune are creating first-mover demand for ISPM 15-certified crating. BIS standards and DGFT export procedures govern treatment certification timelines. The Maharashtra industrial corridor is absorbing new heat-treatment capacity as suppliers position for ASEAN trade lane access.
United Kingdom
Post-Brexit phytosanitary checks at Dover and Felixstowe have tightened ISPM 15 enforcement for EU-bound wood packaging. The Health and Safety Executive monitors workplace exposure standards in treatment facilities. Midlands distribution hubs are standardizing 1200x800mm Europallet specifications for continental retail supply chains.
Wooden and Plywood Packaging Market Competitive Landscape
Top-tier vendors anchor pooled pallet networks and multinational crate engineering, while regional sawmills and independent treatment facilities occupy the long tail. The structure splits between asset-heavy pool operators and project-based custom fabricators. Three archetypes dominate: national depot networks, engineered plywood specialists, and vertically integrated sawmill-to-pallet producers. Competitive moves concentrate on depot density expansion and heat-treatment certification acquisition.
Within the pooled-asset tier, CHEP exemplifies the network-scale archetype through lane-density concentration between distribution centers. Nefab AB occupies a position among engineered plywood specialists serving precision export applications. Kamps Pallets Inc. represents the regional depot-network model with rapid exchange cycle capabilities. These three anchors illustrate how scale, specialization, and geographic coverage define competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Kamps Pallets Inc. |
| Shur-way Industries Inc. |
| Nefab AB |
| Arrington Lumber and Pallet Company |
| C&K Box Company Inc. |
| CHEP |
| Rowlinson Packaging Ltd |
| Universal Forest Products Inc. |
| PalletOne Inc. |
| Others |
Value Network & Pricing Analysis
E-commerce fulfillment networks demanding 48x40 inch pallet standardization for conveyor compatibility are compressing supplier margins and forcing heat-treatment facilities to absorb certification costs or lose volume to pooled pool operators.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to ISPM 15-certified crating with sub-72-hour turnaround, while spot inventory of untreated softwood trades at discounts to contract offtake. Pricing stratifies across marine-grade phenolic-bonded plywood, structural-grade heat-treated softwood, and economy-grade interior panels with divergent adhesive specifications. Cost compression in economy tiers is intensifying because construction sector competition for southern yellow pine elevates raw material basis. Third-party logistics providers exhibit highest price sensitivity due to quarterly contract renegotiation clauses, while semiconductor manufacturers accept premiums for moisture-resistant engineered crating.
Supply Chain Analysis
Freight cost differentials between containerized ocean lanes and over-the-road distribution are reshaping sourcing footprints for export crating. Raw material supply concentrates in Germany, China, and the United States, with southern yellow pine mills in the American Southeast, spruce-pine-fir processors in British Columbia, and engineered plywood specialists in the Yangtze River Delta. Production hinges on phenolic resin adhesives, heat-treatment kiln capacity, and FSC-certified timber feedstock. Tariff exposure on Canadian softwood lumber imports into the United States creates margin volatility for cross-border pallet producers. Distribution runs through bonded warehouse zones near Shenzhen, Hamburg, and Savannah, with depot network density determining lane economics for pooled asset programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is becoming a vertical-integration race, with players pursuing captive heat-treatment capacity to secure ISPM 15 certification timelines and defend margin structures against pooled pool operators.
For Market Incumbents: To counter plastic pallet substitution in pharmaceutical and food-grade applications, deepen backward integration into certified kiln infrastructure and secure long-term softwood supply agreements with Southeast US mills. CHEP and comparable pool operators represent the displacement threat; channel control through depot density expansion offers the defensive lever.
For New Entrants and Emerging Players: Begin with ISPM 15-certified crate fabrication serving India's PLI-subsidized electronics corridors near Chennai and Pune, where first-mover heat-treatment capacity remains scarce. Target automotive component suppliers with collapsible snap-fit plywood systems for just-in-time sequencing. A direct sales model to Tier 1 suppliers bypasses incumbent pooled network advantages.
For Investors and Strategic Acquirers: The window for entry favors engineered plywood specialists with marine-grade certification and established semiconductor customer relationships. Long-term viability rests on carbon border adjustment readiness and dual FSC-ISPM 15 compliance bundles demanded by EU automotive OEMs. Monitor EU Green Deal implementation velocity as the inflection signal for certification premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | ISPM 15 certification timelines determine market access for cross-border export lanes. |
| Backward Integration into Timber Supply | Captive southern yellow pine sourcing insulates margins from construction sector demand spikes. |
| Digital Depot Network Deployment | RFID-tracked pallet pools enable per-use pricing models that displace capital purchase decisions. |
| Marine-Grade Plywood Certification | Phenolic-bonded construction commands premium positioning for offshore wind component exports. |
| Carbon Border Adjustment Compliance | FSC chain-of-custody documentation alongside ISPM 15 compliance secures EU automotive supplier scorecards. |
Research Methodology
Multi-period observation of pallet turnover rates, heat-treatment facility certification backlogs, and e-commerce fulfillment network expansion anchored the trend analysis, supplemented by interviews with pallet pool operations directors, sawmill procurement managers, automotive Tier 1 supplier logistics leads, and third-party logistics category buyers. Secondary validation drew from customs trade data, EPA and ECHA regulatory filings, FSC and PEFC chain-of-custody databases, and SEC disclosures from publicly traded packaging companies. Bottom-up volume estimates triangulated against top-down macroeconomic drivers.
Input-output matrices modeled demand across product type, material grade, application vertical, and end-user ownership structure throughout the forecast period. CAGRs were derived from regression analysis against manufacturing output indices, cross-border trade volumes, and e-commerce penetration rates. Forecast inputs included ISPM 15 enforcement intensity by national plant protection agencies and adhesive emission limit trajectories under REACH and evolving EPA standards.
Underlying measurement precision varies by segment; pooled pallet program volumes carry tighter precision than custom crate fabrication due to consolidated operator reporting. Forecasts reflect assumptions about regulatory enforcement continuity and softwood lumber price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Urn Liners Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Lidding Foil Market
Packaging Materials
VCI Films Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
PET Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Polystyrene Packaging Market