
 Production Page Volume Market | 2026-2036
Production Page Volume Market Size, Share, and Industry Trends Forecast 2026-2036
Production Page Volume Market Analytics
Buyer concentration among enterprise marketing departments is restructuring procurement patterns across the Production Page Volume Market. Large retailers and technology firms are consolidating page production under in-house studios rather than dispersing spend across multiple vendors. Adobe Inc. leverages its Creative Cloud ecosystem to anchor enterprise workflows, while NVIDIA Corporation competes through AI inference infrastructure that accelerates generative content pipelines. Epic Games Inc. differentiates by extending real-time rendering engines into interactive page formats for immersive brand experiences.
Production page volume denotes the aggregate output of publishable digital pages measured in units generated per period across web, mobile, and embedded platforms, typically tracked through content management system logs and delivery network analytics. The metric serves as a proxy for digital publishing intensity, operational capacity planning, and infrastructure scaling decisions in media and commerce organizations. Agency Services and Subscription-Based delivery models currently dominate revenue capture, though Self-Service platforms are gaining traction among mid-market technology verticals seeking direct control over publication velocity. Video and Interactive Content formats command premium positioning within the Content Format dimension, while Text-based pages retain volume leadership across Retail and Education industry verticals.
FCC guidelines on digital advertising transparency and FTC disclosure requirements for sponsored content directly shape page architecture and metadata standards in the United States market. The EU AI Act and GDPR compliance frameworks in Europe impose additional layers on automated content generation and personalization engines, affecting cross-border page deployment strategies. Stakeholders must monitor how evolving algorithmic accountability rules and platform-specific content policies reshape the cost structure of high-velocity page production.
Market Dynamics
Enterprise marketing departments are consolidating page production under captive studios, compressing vendor ecosystems while AI-assisted authoring tools accelerate output velocity across digital publishing workflows.
Growth Catalysts
- FTC disclosure requirements:Sponsored content mandates in the United States are expanding metadata architecture needs, forcing publishers to increase page production capacity to maintain compliant inventory rotation.
- Real-time rendering engines:Interactive brand experiences in retail and technology verticals are driving demand for immersive page formats that require higher per-unit production investment.
- EU AI Act compliance:Automated content generation frameworks in Europe are creating specialized page architecture requirements that favor vendors with cross-border deployment capabilities.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency in the United States creates single-point vulnerability for high-velocity page delivery networks during regional outages.
- GDPR data localization:European cross-border page deployment faces structural friction from automated content personalization engine restrictions.
- Static text formats:Commoditized document pages face substitution pressure from video and interactive content commanding premium positioning.
Strategic Opportunities
- Mid-market technology verticals:Self-service platform adoption remains underpenetrated among SaaS providers seeking direct publication velocity control.
- ISO 27001 certification:Information security frameworks are becoming procurement gatekeepers for enterprise marketing departments evaluating vendor ecosystems.
- Edge computing convergence:Distributed rendering infrastructure combined with AI inference pipelines enables sub-second personalized page delivery.
Industry Challenges
- Generative AI prompt engineering:Talent scarcity for automated content authoring workflows is constraining in-house studio scaling timelines.
- Legacy CMS migration:Enterprise marketing departments face integration complexity when connecting modern automated layout engines to entrenched content repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Production Page Volume Market |
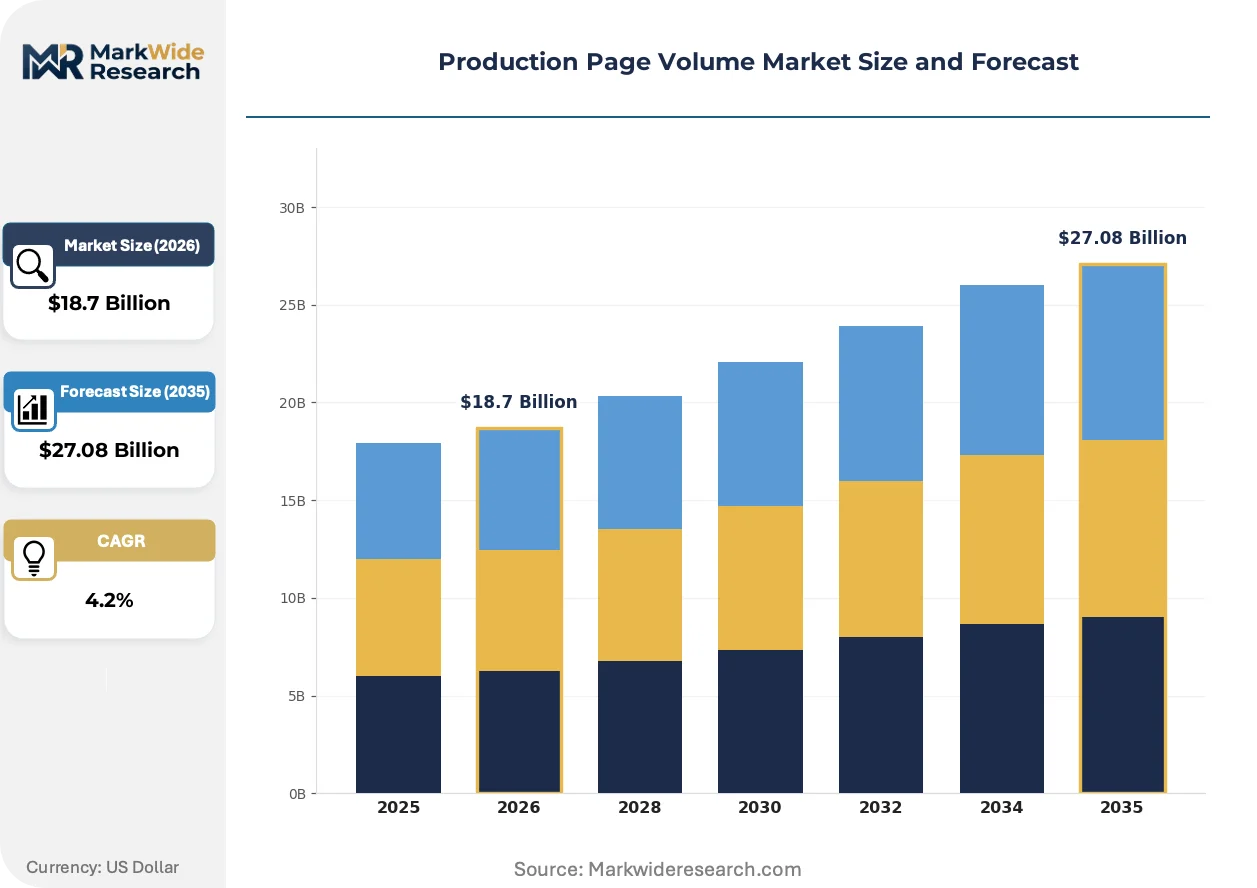
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Webpages, Landing Pages, E-commerce Pages, Blog Posts Delivery Model: Self-Service, Agency Services, Subscription-Based, Pay-Per-Click Content Format: Text, Video, Infographic, Interactive Content Industry Vertical: Retail, Education, Technology, Entertainment |
| Companies Covered | Adobe Inc., Sony Group Corporation, NVIDIA Corporation, Autodesk Inc., ARRI AG, Epic Games Inc., NEP Group, Nikon Corporation, PRG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Production Page Volume Market Evolving Landscape
Automated layout engines and generative authoring pipelines are compressing production timelines while reshaping competitive differentiation around speed-to-publish capabilities.
Neural rendering acceleration is overtaking traditional server-side composition for high-velocity page generation. Retail and technology conglomerates are deploying GPU clusters to achieve sub-second layout computation. This compression is overtaking conventional content management system architectures that relied on pre-rendered template caching.
FCC digital advertising transparency guidelines are mandating standardized metadata schemas across sponsored content inventory. Publishers must re-architect page headers and disclosure placement to maintain broadcast-equivalent transparency. United States technology and media conglomerates are most affected, with compliance teams embedding automated validation into production pipelines.
Subscription-based delivery models are losing ground to usage-tiered pricing among mid-market buyers seeking cost predictability. Agency service retainers face displacement from self-service platforms with metered page generation rates. This pattern is most visible in North American SaaS verticals where procurement teams prioritize operational expenditure flexibility over fixed commitments.
Production Page Volume Market Segmentation
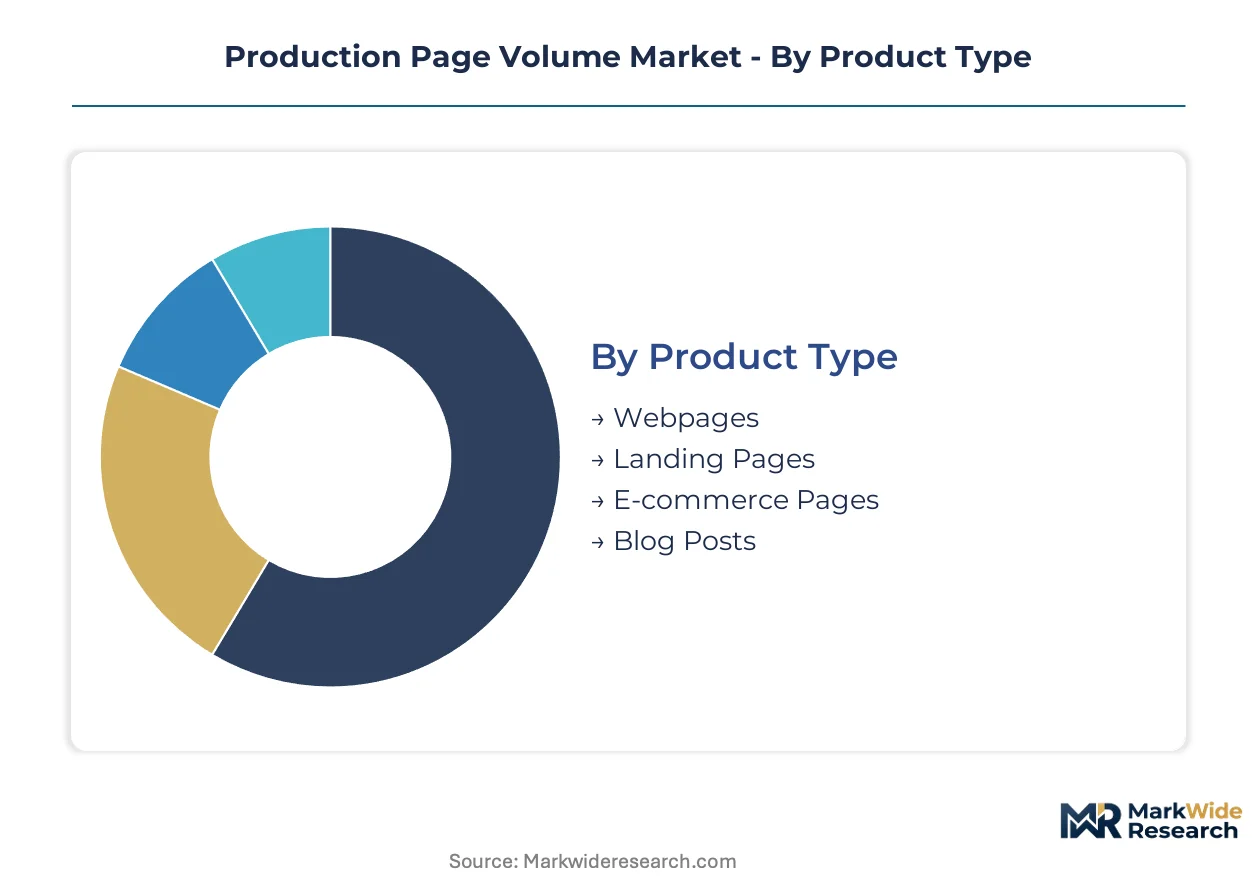
Production page volume segmentation reveals how enterprise buyers prioritize speed, control, and compliance differently across content types and procurement models. Understanding these splits enables vendors to align infrastructure investments with where demand is concentrating.
Product Type:
Volume leadership sits with high-frequency formats, while premium investment flows toward conversion-optimized page architectures.
- Webpages:Standard informational and navigational pages form the baseline output metric for enterprise content operations. Retail conglomerates in the United States generate the highest absolute volumes, driven by SKU expansion and seasonal inventory turnover requirements.
- Landing Pages:Conversion-focused single-purpose pages carry higher per-unit production investment and stricter FTC disclosure compliance overhead. Technology verticals concentrate demand here, particularly SaaS providers running continuous A/B testing programs across paid acquisition channels.
- E-commerce Pages:Product detail and category pages integrate dynamic pricing modules and inventory APIs.
- Blog Posts:Editorial content maintains steady output volumes with lower technical complexity thresholds.
Today's leader: Webpages. Tomorrow's challenger: Landing Pages.
Delivery Model:
Procurement patterns split between buyers seeking operational control and those prioritizing specialized production velocity.
- Agency Services:Retainer-based relationships dominate among Fortune 500 marketing departments requiring rapid scaling for campaign launches. United States technology and media conglomerates maintain the highest agency spend, though consolidation toward fewer, deeper partnerships is compressing vendor counts.
- Self-Service:Direct platform access is gaining fastest among mid-market SaaS providers seeking to eliminate briefing overhead and accelerate publication velocity. North American technology verticals lead adoption, driven by procurement teams prioritizing operational expenditure flexibility.
- Subscription-Based:Fixed-rate access to production capacity retains strength in education and retail verticals with predictable content calendars.
- Pay-Per-Click:Performance-tied pricing aligns vendor incentives with traffic outcomes in performance marketing contexts.
Agency Services still captures the largest revenue pool. Self-Service platforms are climbing the fastest.
Content Format:
Production economics diverge sharply between commodity text output and resource-intensive interactive formats.
- Video:Motion-integrated pages command premium positioning and extended production timelines. Entertainment verticals in the United States drive highest per-page investment, with real-time rendering engines from Epic Games enabling immersive brand experiences that justify higher unit costs.
- Interactive Content:Configurable and personalized page elements require GPU-accelerated layout computation. Retail technology teams are deploying NVIDIA inference infrastructure to achieve sub-second dynamic assembly, particularly for product configurators and personalized recommendation modules.
- Text:Static editorial and informational pages retain volume leadership across all verticals.
- Infographic:Data visualization pages occupy a mid-tier position between text density and visual production requirements.
Text dominates output volume. Video is expanding most quickly in value terms.
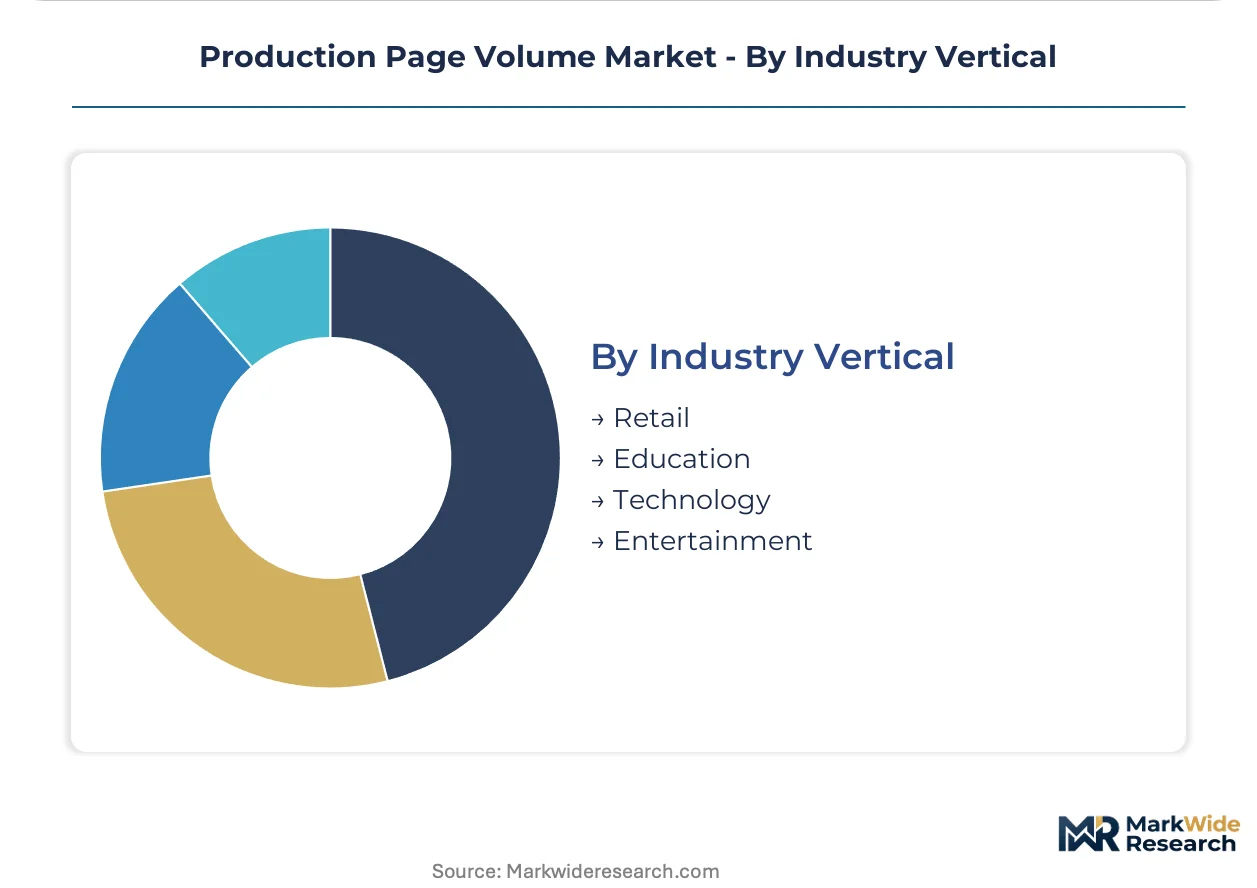
Industry Vertical:
End-use concentration shapes compliance requirements and technology adoption patterns across the market.
- Retail:E-commerce page generation maintains the highest absolute output volumes, with seasonal peaks requiring elastic production capacity. United States retail conglomerates are consolidating page production under captive studios, compressing external vendor ecosystems while deploying Adobe Creative Cloud workflows at scale.
- Technology:SaaS and platform companies prioritize landing page velocity and interactive format experimentation. GDPR compliance friction affects European deployment of automated personalization engines, creating demand for vendors with cross-border architecture capabilities.
- Education:Courseware and institutional content maintains steady text-based page demand with lower technical complexity.
- Entertainment:Immersive and video-heavy formats drive premium positioning and GPU infrastructure investment.
Retail anchors current volume. Technology verticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States technology conglomerates generate substantially higher page output volumes than German industrial marketing departments, yet both markets face divergent compliance architectures that reshape production economics.
United States
Enterprise marketing departments at technology and retail conglomerates drive the highest absolute page volumes worldwide. FTC disclosure requirements for sponsored content and FCC digital advertising transparency guidelines mandate standardized metadata schemas that increase per-page production overhead. Silicon Valley and New York media clusters concentrate demand, with Adobe Creative Cloud workflows dominating captive studio deployments.
Germany
Industrial marketing teams and automotive conglomerates sustain steady e-commerce and technical documentation page generation. EU AI Act compliance frameworks and GDPR data localization rules constrain automated personalization engine deployment across cross-border workflows. Munich and Stuttgart industrial corridors anchor production, with vendors investing in ISO 27001 certification to meet procurement gatekeeping requirements.
United Kingdom
SaaS providers and financial services marketing operations prioritize landing page velocity for paid acquisition channels. GDPR alignment post-Brexit maintains friction on automated content generation frameworks, while domestic regulators enforce transparency standards comparable to FTC mandates. London's technology and media cluster concentrates demand for self-service platform adoption among mid-market buyers.
Japan
Entertainment conglomerates and consumer electronics brands drive premium investment in video-integrated and interactive page formats. METI industrial policy supports GPU infrastructure deployment for real-time rendering acceleration. Tokyo and Osaka metropolitan areas concentrate production studios, with domestic vendors competing on sub-second personalized page delivery capabilities.
South Korea
Technology conglomerates and gaming studios deploy GPU-accelerated layout computation for immersive brand experiences. MFDS data governance frameworks and platform-specific content policies shape automated generation pipeline architectures. Seoul Capital Area anchors demand, with Samsung and LG affiliate marketing operations consolidating page production under in-house studios.
Production Page Volume Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Adobe Inc. anchors enterprise workflow ecosystems through subscription-based creative suites, while NVIDIA Corporation supplies inference infrastructure that accelerates generative pipelines. Three strategic archetypes dominate: full-stack platform providers, specialized rendering engine developers, and agency service consolidators. Competitive moves concentrate on strategic partnerships between software vendors and cloud hyperscalers, alongside portfolio diversification into adjacent content formats.
Within the platform provider tier, Adobe Inc. exemplifies the full-stack archetype through its Creative Cloud ecosystem. NVIDIA Corporation occupies a position as infrastructure backbone for GPU-accelerated page generation. Epic Games Inc. represents the specialized rendering segment, extending real-time engines into interactive formats. These three companies anchor distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Adobe Inc. |
| Sony Group Corporation |
| NVIDIA Corporation |
| Autodesk Inc. |
| ARRI AG |
| Epic Games Inc. |
| NEP Group |
| Nikon Corporation |
| PRG |
| Others |
Value Network & Pricing Analysis
Enterprise marketing department consolidation toward captive studios is forcing supply-side specialization, compressing vendor ecosystems while elevating pricing power for GPU-accelerated layout infrastructure providers. This procurement shift rewards vendors with ISO 27001 certification and cross-border deployment capabilities, widening spreads between compliant premium tiers and commoditized text-format production.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for GPU-accelerated rendering services as hyperscalers expand inference infrastructure. Three-tier pricing structure across premium interactive, standard dynamic, and economy static text levels dominates, with differentiation hinging on ISO 27001 certification status and sub-second personalization latency. Pricing pressure stems from mid-market SaaS providers migrating to metered self-service platforms. Procurement teams at technology verticals exhibit highest price sensitivity, while entertainment conglomerates running immersive brand experiences show least.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for automated layout engines, bypassing traditional agency intermediaries. Supply concentrates in the United States, Taiwan, and South Korea for GPU fabrication and inference hardware. Production draws from advanced node semiconductor wafers, high-bandwidth memory modules, and specialized rendering software licenses. Single-source vulnerability in cloud hyperscaler infrastructure creates regional outage risk for high-velocity page delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-assisted authoring tiers where automation compresses production timelines without proportional cost scaling. Premium interactive format demand justifies infrastructure investment while self-service platform adoption unlocks recurring revenue predictability.
For Market Incumbents: Cement workflow ecosystem dominance by embedding automated compliance validation for FTC disclosure requirements directly into Creative Cloud pipelines. Deepen GPU infrastructure partnerships to secure preferential inference capacity allocation during peak seasonal demand from retail conglomerates.
For New Entrants and Emerging Players: Capture underpenetrated mid-market SaaS verticals in North America with usage-tiered pricing models that eliminate fixed retainer commitments. Target technology procurement teams prioritizing operational expenditure flexibility over legacy agency relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized rendering engine developers possessing real-time immersive format capabilities. Five-to-ten year viability favors vendors bridging automated content generation with cross-border GDPR compliance architecture. Monitor EU AI Act implementation velocity as inflection indicator for European deployment cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| GPU Infrastructure Partnership | NVIDIA inference clusters enable sub-second personalized page assembly for retail technology teams. |
| ISO 27001 Certification Investment | Information security frameworks unlock enterprise procurement gatekeeping requirements in Germany and United States. |
| Self-Service Platform Launch | Metered page generation rates displace fixed agency retainers among North American SaaS verticals. |
| Cross-Border Compliance Architecture | GDPR and EU AI Act alignment enables automated personalization engine deployment across European workflows. |
| Real-Time Rendering Engine Extension | Epic Games Unreal Engine integration creates immersive brand experience differentiation for entertainment conglomerates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with enterprise marketing executives, content operations directors, procurement officers at SaaS providers, and creative studio heads with secondary validation. Sources included SEC filings from Adobe and NVIDIA, hyperscaler capex disclosures, content management system vendor documentation, and trade association data from IAB and MPA. Bottom-up page volume estimates triangulated against top-down infrastructure capacity assessments.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions covering delivery model, content format, industry vertical, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for technology adoption S-curves and compliance cost step-changes. Forecast inputs incorporated GPU cluster deployment timelines and FTC disclosure mandate implementation schedules.
Regulatory enforcement variance, hyperscaler infrastructure concentration events, and generative AI capability breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions on compliance cost trajectories and automation adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Lid Laminates Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
PET Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Finish Foils Market