
 Europe Airless Packaging Market | 2026-2036
Europe Airless Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airless Packaging Market Foresight
European converter investment in airless bottle and pouch capacity is shifting toward mono-material polypropylene lines to meet recyclability targets. AptarGroup, Inc. leverages its fragrance and dispensing heritage to anchor premium skincare contracts across France and Italy. Albea S.A. sustains competitive position through backward integration into injection-molded components for pharmaceutical vials. LUMSON S.p.A. specializes in glass-airless hybrid systems that command margin pools in luxury cosmetic segments.
Airless packaging encloses product within a sealed, collapsible inner chamber that evacuates contents via mechanical pump or pressurized propellant-free mechanism, maintaining oxygen exclusion and preventing back-contamination. The primary commercial purpose centers on extending formulation stability for oxidation-sensitive actives in skincare and sterile preservation in injectable pharmaceuticals. Plastic mono-material formats dominate volume across Personal Care end users due to compatibility with existing recycling streams, while Glass segments retain premium positioning in anti-aging and dermocosmetic lines where perceived purity supports price architecture. Healthcare applications in Preservation functionality are gaining fastest as biologic drug delivery drives demand for barrier-grade primary packaging.
EMA stability guidelines for pharmaceutical primary containers and REACH chemical restrictions on substance migration jointly elevate barrier performance requirements for European suppliers. The EU Green Deal's packaging and packaging waste regulation pushes converters toward verified recycled content thresholds and design-for-recycling certification. Stakeholders must monitor how ECHA's evolving microplastic restrictions reshape pump mechanism material choices and whether national extended producer responsibility schemes in Germany and France accelerate pass-through cost structures.
Market Dynamics
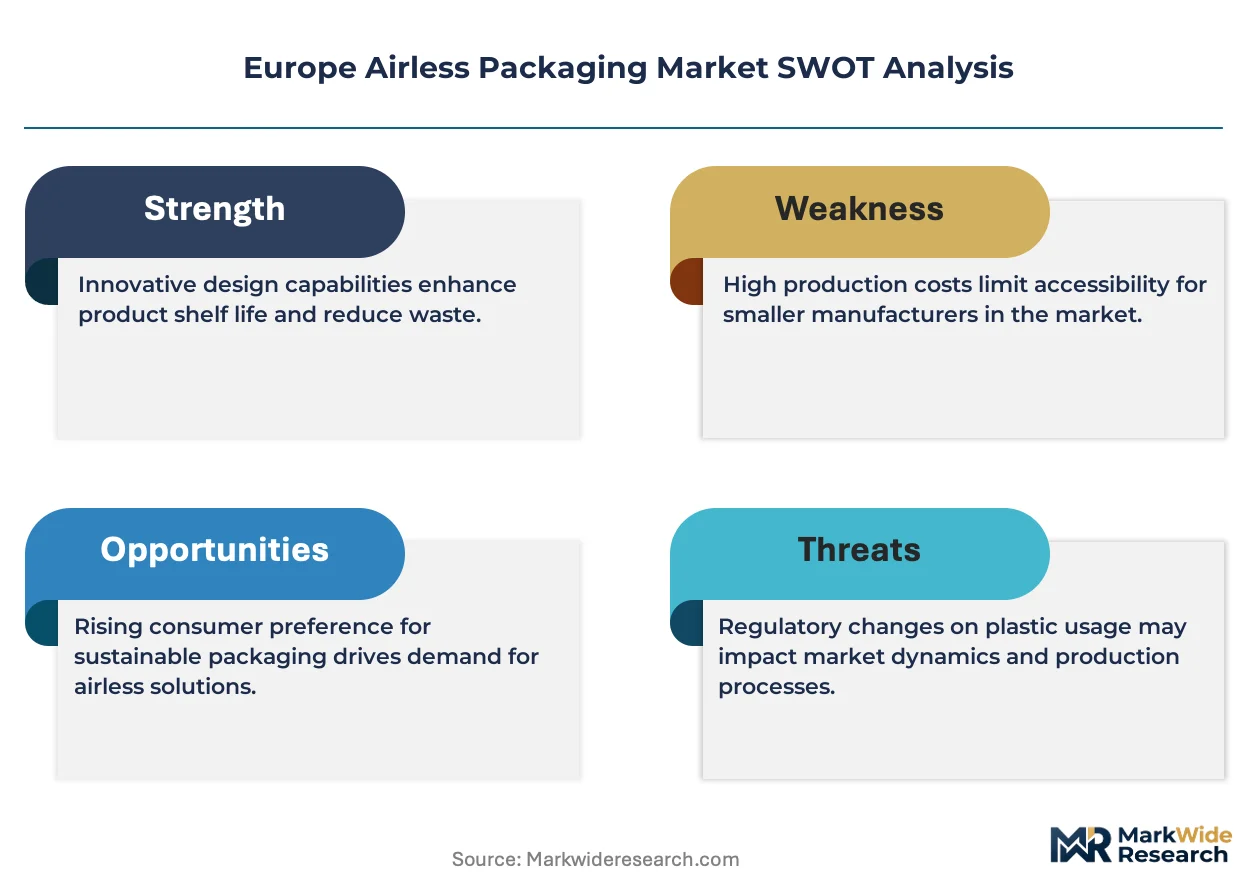
REACH chemical restrictions and the EU Green Deal's circularity mandates are forcing material transitions across European airless packaging supply chains, compressing design cycles and elevating compliance costs for converters serving cosmetics and pharmaceutical end users.
Growth Catalysts
- REACH migration limits:Substance migration thresholds under ECHA guidance are compelling reformulation of pump elastomers and seals, creating pull for barrier-grade mono-material systems that simplify compliance documentation.
- Biologics preservation demand:Injectable biologic drugs requiring oxygen exclusion and sterile primary containment are expanding airless vial adoption in pharmaceutical manufacturing corridors across Germany and Switzerland.
- Italian glass-airless hybrids:Luxury cosmetic brands headquartered in Lombardy and Tuscany are specifying glass outer bodies with collapsible inner pouches to command shelf price premiums in anti-aging segments.
Market Restraints
- Recycled polypropylene feedstock volatility:Post-consumer rPP availability constraints in Germany and France are inflating raw material costs for mono-material pump bodies and limiting production scale-up.
- Mold-making capacity concentration:Precision injection mold fabrication for multi-cavity airless pump mechanisms concentrates among specialized toolmakers in southern Germany, creating supply bottlenecks during demand surges.
- Silicone valve substitution:Alternative dispensing technologies using silicone membrane valves offer lower unit economics for mid-tier skincare, threatening volume share in mass-market personal care applications.
Strategic Opportunities
- Spanish pharmaceutical expansion:Underpenetrated sterile packaging demand from Barcelona's growing injectables manufacturing cluster offers white space for barrier-grade airless vial suppliers.
- Design-for-recycling certification:PRE recyclability assessments and EU Green Deal packaging waste targets are creating first-mover advantage for converters achieving mono-material pump certification ahead of mandates.
- E-commerce refill formats:Concentrate pouch systems compatible with reusable airless dispensers are penetrating direct-to-consumer channels in France and the Netherlands, displacing single-use bottle dependency.
Industry Challenges
- Multi-material separation expertise:Converter engineering teams lack sufficient polymer compatibilization knowledge to achieve clean mono-material transitions without sacrificing pump seal performance.
- EMA stability timeline compression:Accelerated pharmaceutical primary container qualification schedules are compressing validation windows, straining quality assurance bandwidth at mid-tier packaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airless Packaging Market |
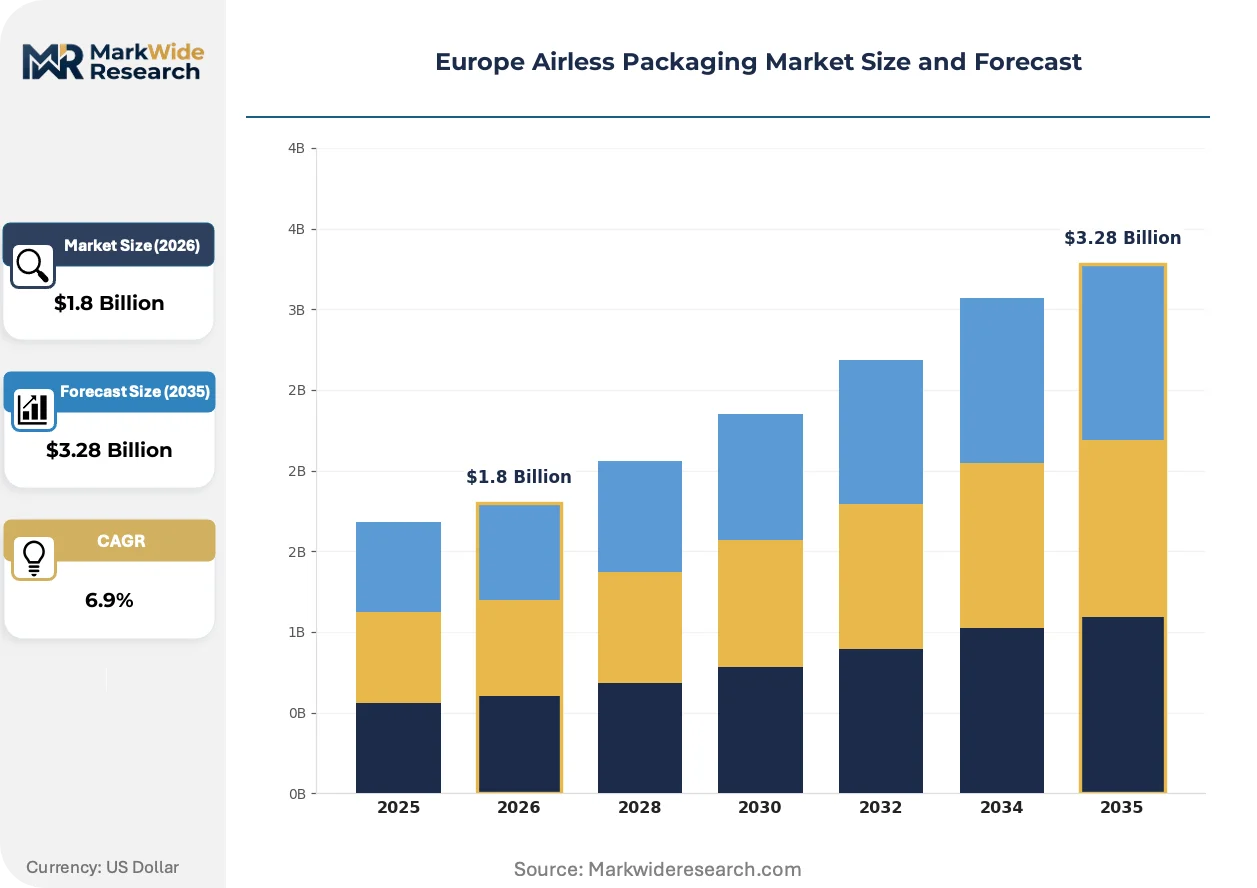
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.28 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Food, Household Material: Plastic, Glass, Metal, Others End User: Personal Care, Healthcare, Food & Beverage, Home Care Functionality: Dispensing, Preservation, Protection, Hygiene |
| Companies Covered | HCP Packaging, LUMSON S.p.A, Albea S.A., Raepak Ltd, Berry Global Group, Inc., AptarGroup, Inc., Quadpack, Gaplast GmbH, Silgan Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airless Packaging Market Shifts & Advancements
Material science advances and regulatory compliance architectures are converging to reshape competitive positioning across European airless packaging, with sustainability verification and barrier performance emerging as dual purchase criteria.
Mono-material polypropylene pump mechanisms are expanding into pharmaceutical and cosmetic applications previously dominated by multi-material assemblies. German and French brand owners are specifying all-PP pump bodies, springs, and valves to satisfy recyclability targets under the EU Green Deal. This technology shift is expanding into barrier-sensitive segments by enabling simplified post-consumer sorting without disassembly.
EMA stability guidelines for primary pharmaceutical containers are tightening oxygen transmission rate requirements for biologic drug packaging. The regulation is elevating barrier-grade polymer specifications and glass-airless hybrid adoption in sterile injectable segments. Swiss and German pharmaceutical manufacturers are responding by qualifying higher-performance ethylene vinyl alcohol coextrusion layers in collapsible pouch systems.
Brand owners are consolidating supplier relationships around converters offering integrated design-for-recycling certification and carbon footprint verification. Mid-tier personal care companies in Italy and Spain are displacing fragmented multi-source procurement with single-partner accountability for mono-material compliance. This concentration is most visible in France, where L'Oréal's supplier sustainability scorecards are reshaping qualification criteria across the cosmetics packaging base.
Europe Airless Packaging Market Segmentation
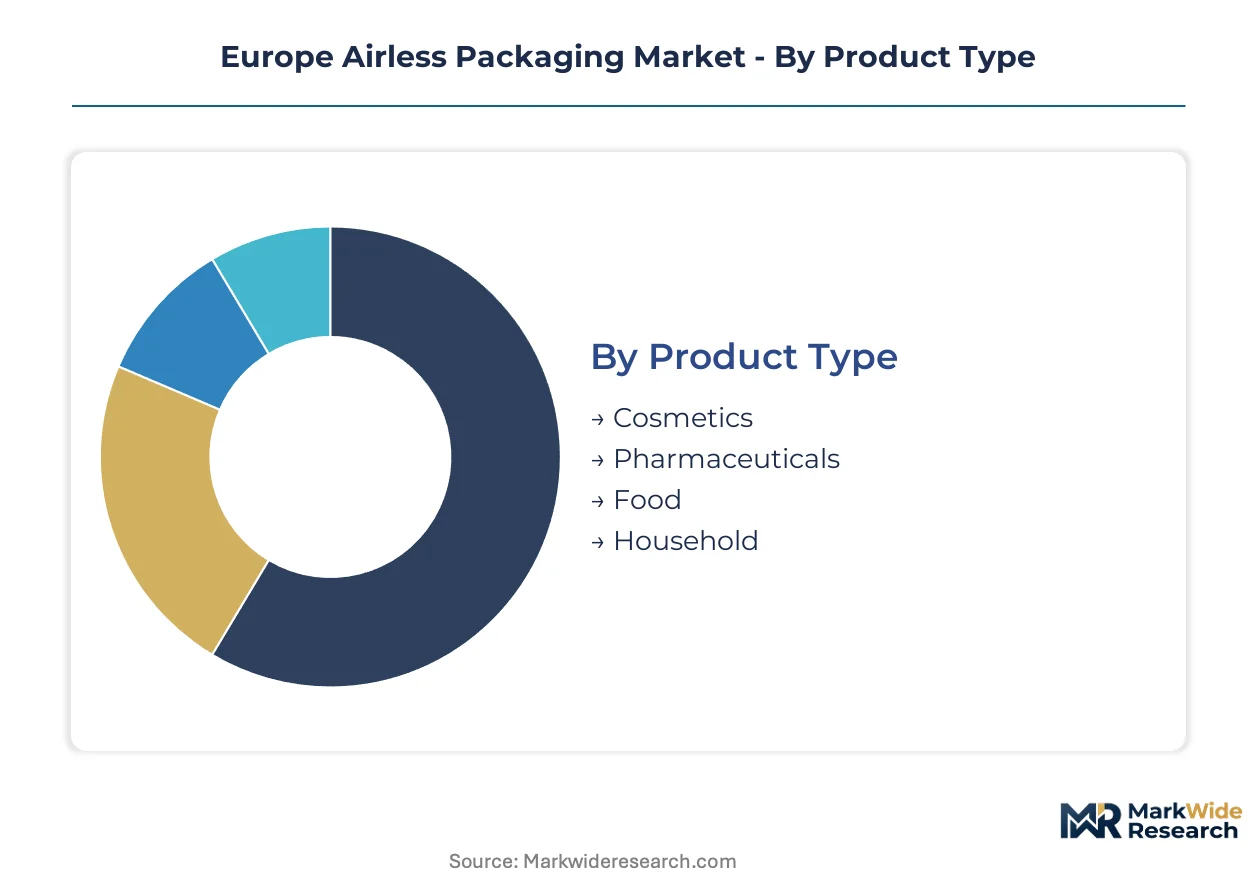
Airless packaging specifications diverge sharply across European end-use sectors, with REACH migration thresholds and EMA stability guidelines imposing distinct certification burdens on each segment. Material compatibility documentation and recyclability verification now function as gatekeepers for supplier qualification across cosmetics and pharmaceutical supply chains.
Product Type:
EMA stability guidelines govern pharmaceutical segments, while REACH substance restrictions dominate cosmetics compliance architecture.
- Cosmetics:Airless pump systems for premium skincare and anti-aging formulations require extensive ECHA migration testing for pump elastomers and seals. German and French brand owners are specifying mono-material polypropylene constructions to streamline recyclability certification under EU Green Deal packaging waste targets. Demand concentrates in Lombardy's luxury cosmetic manufacturing cluster, where glass-airless hybrids command price premiums for oxidation-sensitive actives.
- Pharmaceuticals:Injectable biologic drugs drive barrier-grade specifications for collapsible pouch systems and sterile vials. Swiss and German manufacturers are qualifying ethylene vinyl alcohol coextrusion layers to meet tightening oxygen transmission rate requirements. EMA primary container validation timelines are compressing, straining quality assurance bandwidth at mid-tier packaging suppliers.
- Food:EFSA food contact material approvals govern pump mechanism polymers and barrier films for sensitive condiments and nutritional supplements.
- Household:Cleaning product formulations tolerate lower barrier specifications, with cost-driven procurement favoring simplified mono-material designs.
Cosmetics sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest.
Material:
Recyclability mandates are reshaping procurement priorities across material tiers, with post-consumer content thresholds now embedded in supplier scorecards.
- Plastic:Mono-material polypropylene dominates Personal Care volume due to compatibility with existing mechanical recycling streams. German converters are investing in all-PP pump bodies, springs, and valves to satisfy PRE recyclability assessments. rPP feedstock volatility in France and Germany is inflating raw material costs and limiting production scale-up for certified recycled-content lines.
- Glass:Outer bodies paired with collapsible inner pouches retain premium positioning in anti-aging and dermocosmetic segments where perceived purity supports price architecture. Italian luxury brands headquartered in Tuscany specify glass-airless hybrids to command shelf price premiums.
- Metal:Aluminum barrier layers and pump components serve niche pharmaceutical applications requiring absolute oxygen exclusion.
- Others:Bio-based polymers and compostable films occupy experimental positions pending ECHA microplastic restriction clarity.
Plastic captures the dominant volume share, with Glass expanding most quickly in premium repositioning strategies.
End User:
Barrier performance requirements escalate from Home Care through Healthcare, with sterile preservation demands imposing the steepest specification gradients.
- Personal Care:Skincare and haircare applications drive standard airless pump adoption, with mass-market brands in Spain and Italy consolidating supplier relationships around integrated design-for-recycling certification.
- Healthcare:Injectable biologics and sterile drug delivery systems require barrier-grade primary containment with validated oxygen exclusion. Barcelona's growing injectables manufacturing cluster offers underpenetrated demand for qualified airless vial suppliers.
- Food & Beverage:Sensitive nutritional formulations and premium condiments employ airless dispensing for oxidation prevention, though volume remains constrained by EFSA approval timelines.
- Home Care:Cleaning products utilize simplified airless mechanisms where chemical compatibility outweighs barrier sophistication.
Personal Care leads absolute volume, with Healthcare gaining share fastest on biologics expansion.
Functionality:
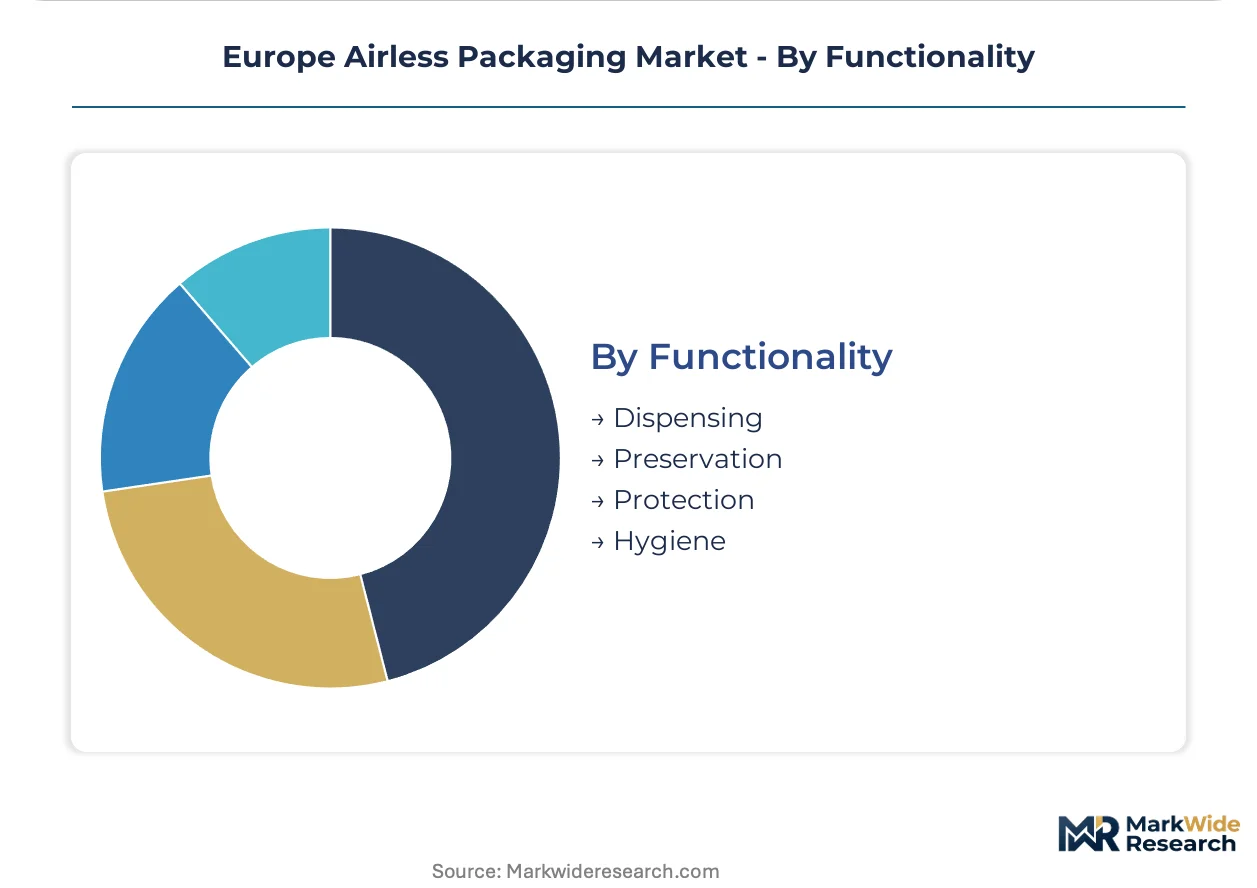
Preservation and protection functions command premium pricing, while dispensing functionality faces commoditization pressure from alternative valve technologies.
- Dispensing:Mechanical pump mechanisms deliver measured product doses via finger-actuated or pressurized systems. Silicone membrane valve alternatives are threatening volume share in mid-tier skincare with lower unit economics.
- Preservation:Oxygen exclusion and sterile containment extend formulation stability for oxidation-sensitive actives and biologic drugs. EMA guidelines are elevating barrier-grade polymer specifications across German and Swiss pharmaceutical corridors.
- Protection:Physical barrier functions prevent contamination and maintain product integrity through distribution and consumer use cycles.
- Hygiene:Touch-free and contamination-resistant designs serve institutional and healthcare settings with elevated sanitation protocols.
Preservation commands the highest value per unit, with Hygiene expanding most quickly on institutional procurement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cosmetics manufacturing corridor generates denser airless packaging demand than France's pharmaceutical clusters, though both markets operate under identical REACH and EU Green Deal compliance frameworks.
Germany
Personal care brand owners in North Rhine-Westphalia specify mono-material polypropylene pumps to satisfy PRE recyclability assessments. REACH substance migration thresholds compel reformulation of pump elastomers and seals. The precision injection mold fabrication cluster in southern Germany concentrates capacity for multi-cavity airless pump mechanisms, creating supply bottlenecks during demand surges.
France
Premium skincare houses headquartered in Île-de-France expand airless pump adoption to extend product shelf life and reduce preservative load. EU Green Deal packaging waste regulation pushes converters toward verified recycled content thresholds. Lombardy and Tuscany luxury brands source glass-airless hybrid systems from French converters to command shelf price premiums in anti-aging segments.
Italy
Lombardy's luxury cosmetic manufacturing cluster drives demand for glass-airless hybrid systems with collapsible inner pouches. ECHA guidance on microplastic restrictions reshapes pump mechanism material choices for Italian converters. Tuscany-based brand owners specify glass outer bodies paired with collapsible pouches to differentiate anti-aging product lines.
Switzerland
Injectable biologic drug manufacturers in the Basel pharmaceutical corridor qualify higher-performance ethylene vinyl alcohol coextrusion layers in collapsible pouch systems. EMA stability guidelines tighten oxygen transmission rate requirements for primary pharmaceutical containers. Swiss pharmaceutical manufacturers anchor barrier-grade airless vial demand across the German-Swiss manufacturing corridor.
Spain
Barcelona's growing injectables manufacturing cluster offers underpenetrated demand for barrier-grade airless vial suppliers. National extended producer responsibility schemes accelerate pass-through cost structures for Spanish converters. Mid-tier personal care companies in Spain consolidate supplier relationships around integrated design-for-recycling certification.
Europe Airless Packaging Market Competitive Landscape
German producers anchor one tier; Italian and French specialists hold differentiated positions in glass-airless hybrids and premium cosmetic applications. The vendor base distributes across consolidated multinational converters and mid-tier regional fabricators with backward integration into injection-molded components. Three archetypes dominate: fragrance and dispensing heritage players, glass-airless hybrid specialists, and pharmaceutical barrier-grade suppliers. Competitive moves concentrate on mono-material line investments and design-for-recycling certification acquisition ahead of regulatory mandates.
Within the premium-tier vector, AptarGroup, Inc. and LUMSON S.p.A. occupy positions shaped by their respective heritage in fragrance dispensing and glass-airless hybrid systems. Albea S.A. exemplifies the backward-integrated archetype through captive production of injection-molded components. These three anchors illustrate how European converters are consolidating supplier relationships around integrated sustainability verification and barrier performance documentation.
| Leading Market Players |
|---|
| HCP Packaging |
| LUMSON S.p.A |
| Albea S.A. |
| Raepak Ltd |
| Berry Global Group, Inc. |
| AptarGroup, Inc. |
| Quadpack |
| Gaplast GmbH |
| Silgan Holdings Inc. |
| Others |
Supply & Pricing Matrix
Post-consumer recycled polypropylene price volatility in Germany and France cascades through converter cost structures, stratifying end-product pricing across premium certified-recycled tiers, standard mono-material lines, and economy multi-material alternatives.
Pricing Analysis
Distributor margins for airless pump systems compress most acutely in mid-tier personal care channels where silicone membrane valve substitutes erode mechanical pump volume. Pricing stratifies across premium, standard, and economy tiers based on PRE recyclability certification status and barrier-grade polymer specifications. Cost compression in standard-tier mono-material lines intensifies because rPP feedstock constraints inflate raw material costs without corresponding price recovery mechanisms. Mass-market personal care brands in Spain and Italy exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers purchasing barrier-grade vials demonstrate lowest elasticity due to EMA validation lock-in.
Supply Chain Analysis
Toolmaking and precision molding workforce availability in southern Germany constrains capacity expansion for multi-cavity airless pump mechanisms. Supply concentrates in Germany, France, and Italy, with raw material dependencies drawing from Belgian petrochemical corridors for virgin PP, Spanish recycling streams for rPP, and Swiss specialty polymer suppliers for EVOH barrier layers. Single-source vulnerability concentrates in precision injection mold fabrication, where southern German toolmakers anchor regional capacity. Distribution runs through converter-direct relationships with cosmetics OEMs in North Rhine-Westphalia and pharmaceutical manufacturers in Basel, supplemented by specialized packaging distributors serving mid-tier Italian and Spanish brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's airless packaging market compounds steadily as biologic drug expansion and REACH compliance mandates create durable replacement demand across pharmaceutical and cosmetics end uses.
For Market Incumbents: Hedge against silicone valve substitution by accelerating mono-material polypropylene line investments ahead of EU Green Deal packaging waste mandates. Defensive consolidation through backward integration into injection-molded components captures margin pools currently leaking to specialized toolmakers in southern Germany. Channel control via direct partnerships with Lombardy luxury cosmetic houses protects premium positioning against glass-airless hybrid specialists. For New Entrants and Emerging Players: Barrier-grade pouch systems for injectable biologics offer technology-first wedge into underpenetrated demand from Barcelona's growing sterile manufacturing cluster. White space concentrates in e-commerce refill formats compatible with reusable dispensers, where concentrate pouch systems displace single-use bottle dependency in French and Dutch direct-to-consumer channels. Go-to-market positioning centers on PRE recyclability certification achievement ahead of mandated thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing captive mold-making capacity and verified mono-material certification pipelines. Long-term viability across the forecast horizon rests on regulatory compliance infrastructure rather than commodity scale. Acquisition target archetype: Italian or Spanish converters with design-for-recycling certification progress and established relationships with consolidating personal care brand owners. Signal to watch: ECHA microplastic restriction finalization reshaping pump mechanism material specifications and disqualifying non-compliant supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Investment | PRE recyclability certification unlocks supplier qualification with L'Oréal and consolidated French cosmetics houses. |
| Backward Integration into Injection Molding | Captive component production insulates margin compression from southern German toolmaker bottlenecks. |
| Barrier-Grade Pouch Qualification | EMA stability guideline compliance opens Swiss and German pharmaceutical manufacturing corridors. |
| E-Commerce Refill Format Development | Concentrate pouch systems penetrate direct-to-consumer channels displacing single-use bottle dependency. |
| Design-for-Recycling Certification | First-mover verification under EU Green Deal packaging waste targets secures procurement consolidation advantages. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at German and French cosmetics OEMs, pharmaceutical quality assurance leads in Swiss and Spanish manufacturing corridors, and converter operations directors across Italian and Spanish production facilities. Secondary validation drew from EMA stability guideline documentation, ECHA REACH substance restriction updates, PRE recyclability assessment protocols, and EU Green Deal packaging waste regulation filings. Bottom-up demand modeling from end-use segment consumption patterns triangulated against top-down supply-side capacity estimates from converter investment disclosures.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product type, material tier, end-use sector, and functionality requirement. CAGRs derived from regression analysis of disclosed capacity additions, regulatory compliance timelines, and brand owner procurement consolidation patterns. Industry-specific forecast inputs incorporated EMA primary container validation compression effects and rPP feedstock availability constraints in German and French recycling infrastructure.
The model holds under stable REACH enforcement and EU Green Deal implementation timelines; deviation in ECHA microplastic restriction severity or accelerated EMA stability guideline revision would shift pharmaceutical segment qualification burdens and converter material transition costs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cork Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Standard Liner Market
Packaging Materials
Finish Foils Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
PET Packaging Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Global Strapping Market