
 Asia-Pacific Waterborne Adhesives Market | 2026-2036
Asia-Pacific Waterborne Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Waterborne Adhesives Market Outlook
Distributor networks serving small-scale woodworking shops across Indonesia and Vietnam is narrowing as Henkel AG & Co. KGaA extends direct-to-mill technical service teams. Dow anchors polymer supply through captive acrylic emulsion plants in Thailand. Pidilite Industries Ltd dominates decorative adhesive retail across India through dense dealer networks. Sika AG competes in construction-grade formulations with specialized mortar-compatible binders.
Asia-Pacific waterborne adhesives are aqueous polymer dispersions, typically acrylic or polyurethane emulsions with solids content between 40% and 60%, manufactured through free-radical polymerization in water with surfactant stabilization. These systems bond porous and non-porous substrates while eliminating volatile organic compound emissions associated with solvent-cured alternatives. Acrylic formulations lead volume in packaging laminate applications where clarity and heat resistance matter most. Polyurethane emulsions command premium positioning in automotive interior assembly where flexibility under thermal cycling determines performance. EVA waterborne grades sustain growth in panel bonding for prefabricated construction modules across East Asian manufacturing hubs.
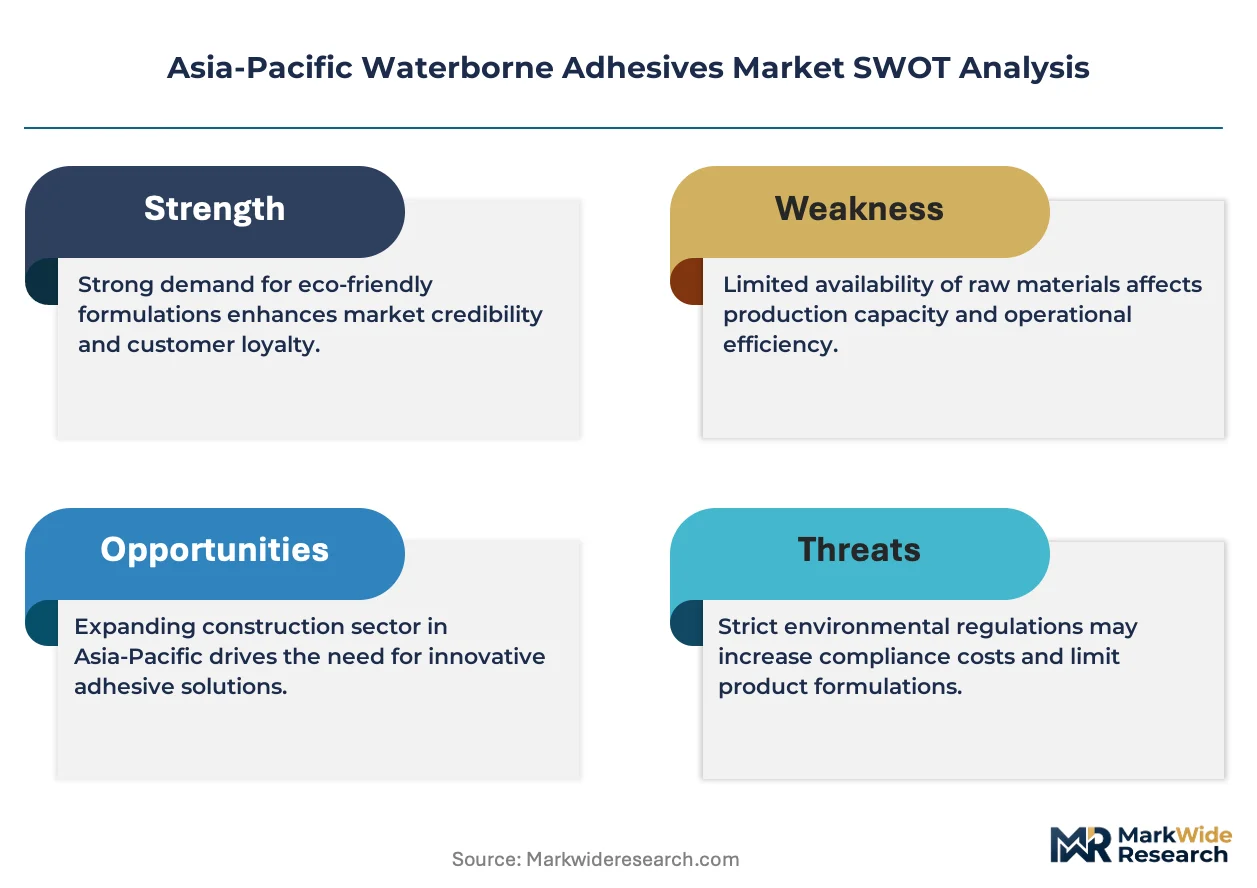
China's MEE enforces GB standards limiting formaldehyde and VOC content in interior building materials, redirecting specification toward certified waterborne systems. India's BIS mandates IS 15490 compliance for adhesive products in food-contact packaging, creating compliance barriers for uncertified imports. Japan's METI promotes JIS-aligned green procurement criteria that favor low-emission bonding technologies in public infrastructure projects. Stakeholders must track how ASEAN harmonization of chemical hazard classifications reshapes cross-border formulation registration requirements.
Market Dynamics
China's dual carbon goals and MEE enforcement are systematically tightening solvent-based adhesive production permits, redirecting manufacturing capacity toward aqueous polymer systems across the Asia-Pacific region.
Growth Catalysts
- Packaging laminate demand:Southeast Asian converters are expanding orders for low-VOC adhesive systems to meet export market specifications for food-contact materials.
- GB standard enforcement:China's MEE limits on formaldehyde and VOC content in interior building materials are mandating certified waterborne system specifications in construction applications.
- Woodworking cluster concentration:India's Gujarat and Punjab manufacturing hubs are driving specification pull for panel-bonding emulsions in prefabricated furniture production.
Market Restraints
- Acrylic monomer cost volatility:Feedstock price swings for petrochemical-derived emulsions compress margin predictability for mid-scale formulators.
- Thai polymer supply concentration:Captive acrylic emulsion production at Dow's Thailand facilities creates single-source dependency risks for regional distributors.
- Curing speed limitations:Waterborne polyurethane systems require extended drying cycles compared to solvent-cured alternatives, restricting high-throughput automotive assembly line adoption.
Strategic Opportunities
- Vietnam woodworking penetration:Small-scale mill technical service gaps create white space for direct-to-manufacturer formulation partnerships outside distributor networks.
- IS 15490 compliance services:India's BIS food-contact certification requirements for adhesive products generate advisory revenue streams for testing laboratories.
- Construction-grade mortar compatibility:Sika AG's specialized binder positioning demonstrates premium capture potential in infrastructure-grade waterborne systems.
Industry Challenges
- Surfactant formulation expertise scarcity:Free-radical polymerization process control requires specialized chemists in short supply across Indonesian and Vietnamese manufacturing zones.
- ASEAN hazard classification harmonization:Cross-border formulation registration delays emerge as member states align chemical safety protocols, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Waterborne Adhesives Market |
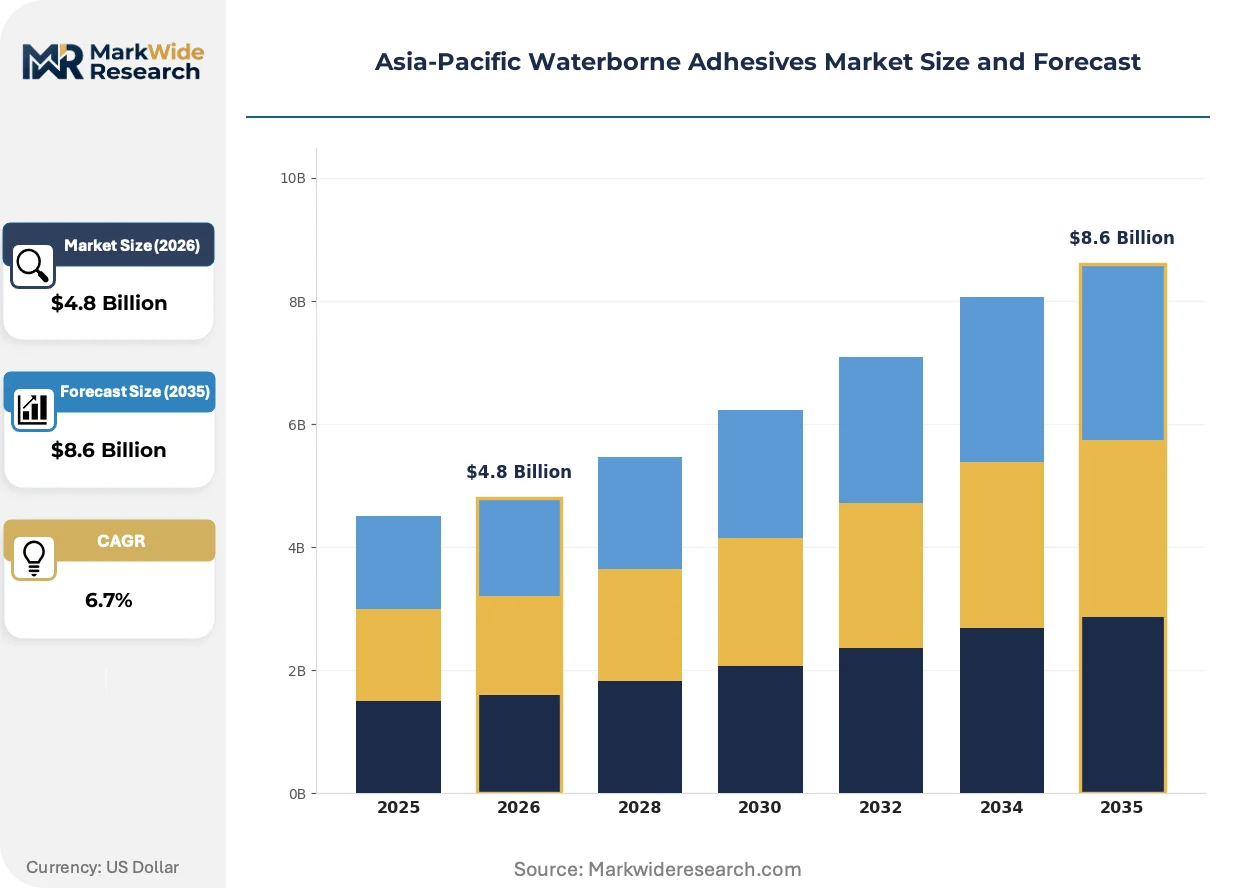
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
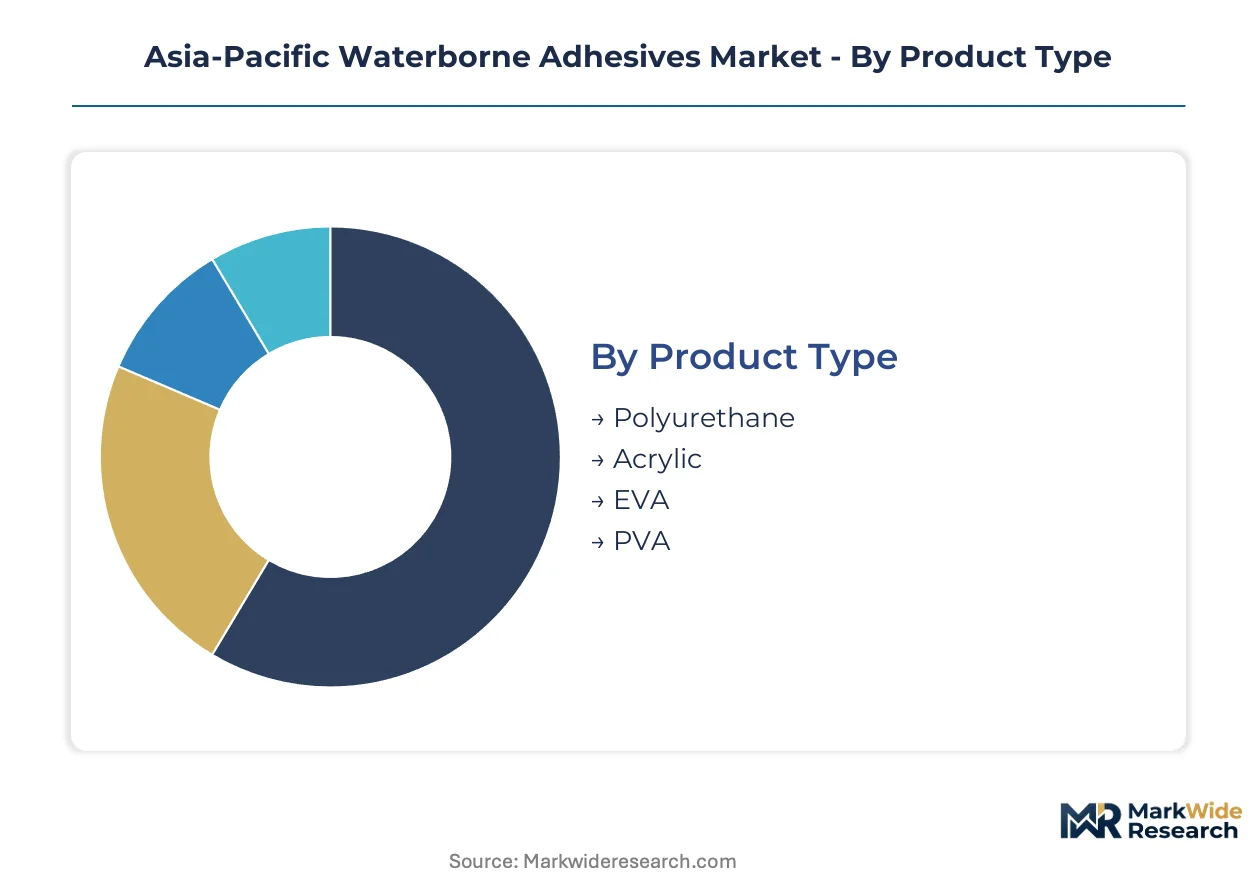
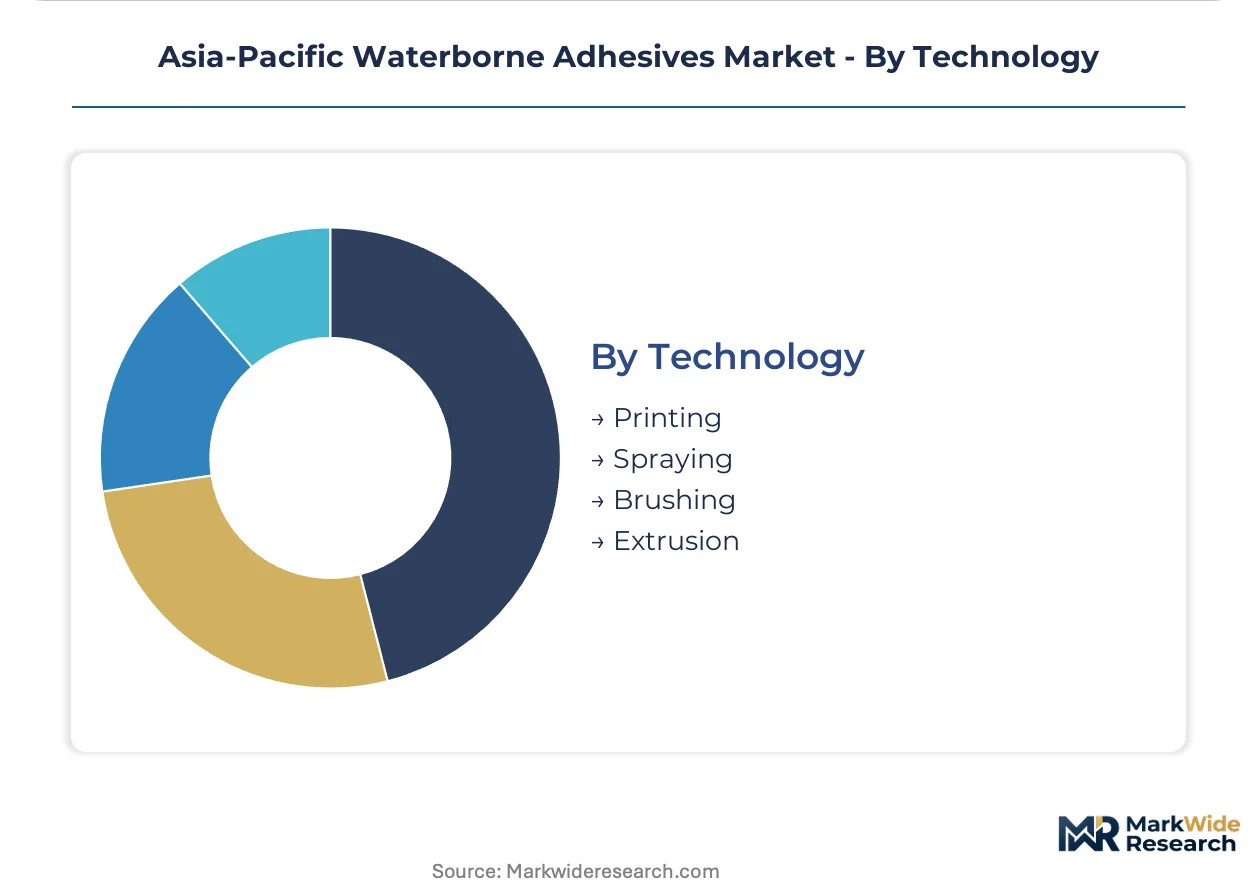
| Segmentation | Product Type: Polyurethane, Acrylic, EVA, PVA End User: Packaging, Woodworking, Construction, Automotive Application: Laminate Flooring, Adhesive Tapes, Panel Bonding, Coatings Technology: Printing, Spraying, Brushing, Extrusion |
| Companies Covered | 3M, Arkema Group, Dow, Henkel AG & Co. KGaA, Sika AG, Ashland, Huntsman International LLC, Pidilite Industries Ltd, Bostik, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Waterborne Adhesives Market Strategic Shifts
Digital formulation databases are compressing technical specification cycles while bio-based feedstock integration and direct-to-mill service models are restructuring traditional distribution economics across the Asia-Pacific waterborne adhesives sector.
Hybrid acrylic-polyurethane copolymer emulsions are virtualizing the performance gap between commodity packaging adhesives and premium automotive-grade systems. Japanese automotive tier-one suppliers are piloting these formulations for interior trim assembly. The technology is virtualizing traditional tier boundaries by enabling mid-range producers to quote on specification-critical applications previously reserved for specialized polyurethane houses.
China's GB standards for interior building materials are eliminating solvent-cured adhesive categories from state-procured construction projects. MEE enforcement teams are conducting unannounced facility audits to verify VOC emission claims. Prefabricated construction module manufacturers in Jiangsu and Guangdong provinces are accelerating waterborne system validation to maintain supplier qualification status.
Specification authority is migrating from distributor sales teams to mill-level technical staff as direct service models expand. Indonesian woodworking clusters are bypassing traditional dealer networks for formulation troubleshooting and batch optimization support. This channel compression is most pronounced in Vietnam's furniture export manufacturing zones where mill engineers now dictate adhesive selection criteria.
Asia-Pacific Waterborne Adhesives Market Segmentation
Waterborne adhesive specifications diverge sharply across end-use cycles, with packaging converters demanding rapid formulation refresh while construction-grade systems lock in multi-year certification windows. Understanding these velocity differentials enables suppliers to calibrate R&D cadence and inventory positioning against segment-specific procurement rhythms.
Product Type:
Acrylic emulsions turn inventory fastest through packaging laminate specifications, while polyurethane systems endure longest validation cycles in automotive interior programs.
- Acrylic:Aqueous polymer dispersions manufactured through free-radical polymerization with 40-60% solids content deliver clarity and heat resistance for flexible packaging laminates. Demand concentrates in Southeast Asian converter facilities supplying export-market food-contact materials where low-VOC certification is mandatory.
- Polyurethane:Emulsion systems with segmented elastomeric backbones provide flexibility under thermal cycling for automotive interior assembly. Premium positioning in Japanese tier-one supplier networks sustains extended specification timelines and higher margin capture relative to commodity grades.
- EVA:Ethylene-vinyl acetate copolymer emulsions serve prefabricated construction module panel bonding across East Asian manufacturing hubs with balanced cost-performance profiles.
- PVA:Polyvinyl alcohol-based systems anchor entry-level woodworking adhesive demand in India's Gujarat and Punjab clusters through established supply chain relationships.
Acrylic formulations anchor the volume base while polyurethane gains share at the steepest rate.
End User:
Margin tiers separate specification-critical automotive programs from price-sensitive woodworking procurement, with packaging and construction occupying intermediate value positions.
- Packaging:Laminate converters across Southeast Asia drive formulation demand for food-contact compliant systems with heat-seal performance. China's dual carbon enforcement and MEE permit restrictions are eliminating solvent-based alternatives from qualified supplier lists.
- Woodworking:Panel bonding applications in India's Gujarat and Punjab manufacturing clusters sustain EVA and PVA emulsion consumption for prefabricated furniture production.
- Construction:Mortar-compatible waterborne binders for infrastructure applications command premium positioning through specialized formulation services.
- Automotive:Interior trim assembly specifications in Japanese manufacturing networks require extended thermal cycling validation and direct-to-mill technical support models.
Packaging commands the broadest regional footprint while automotive delivers the highest per-kilogram value realization.
Application:
Geographic concentration patterns differentiate mature specification environments from emerging demand formation zones across the Asia-Pacific region.
- Laminate Flooring:Waterborne adhesive systems for engineered wood flooring installation face GB standard compliance requirements in China's Jiangsu and Guangdong provinces where prefabricated construction module manufacturing is accelerating.
- Adhesive Tapes:Pressure-sensitive emulsion coatings for industrial and consumer tape applications serve diverse end-use requirements across Japanese and South Korean manufacturing networks.
- Panel Bonding:Structural emulsion systems for furniture and construction module assembly concentrate demand in India's woodworking clusters and Vietnam's furniture export zones.
- Coatings:Waterborne adhesive coatings for protective and decorative applications span construction and industrial maintenance segments with varying performance specifications.
Panel bonding sustains the deepest geographic penetration while laminate flooring exhibits the most rapid specification upgrade trajectory.
Technology:
Application method selection correlates directly with production scale and automation intensity across end-use manufacturing environments.
- Printing:Gravure and flexographic adhesive deposition systems serve high-volume packaging laminate production with precise coating weight control.
- Spraying:Automated spray application dominates automotive interior assembly and large-scale construction module manufacturing where throughput requirements exceed manual method capacity.
- Brushing:Manual application persists in small-scale woodworking shops across Indonesia and Vietnam where equipment investment constraints limit automation adoption.
- Extrusion:Slot-die and roller extrusion systems deliver precise adhesive metering for continuous panel bonding operations in prefabricated construction manufacturing.
Spraying technology captures the most rapid capacity expansion while brushing retains significant volume in fragmented woodworking segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands the steepest per-kilogram value realization in waterborne adhesives procurement, while India's Gujarat and Punjab clusters absorb volume at compressed margin tiers. This pricing-power asymmetry shapes supplier R&D allocation and technical service deployment across the region.
China
Prefabricated construction module manufacturers in Jiangsu and Guangdong provinces are accelerating waterborne system validation to maintain supplier qualification status under tightening environmental enforcement. MEE teams conduct unannounced facility audits to verify VOC emission claims against GB standards for interior building materials. Dual carbon policy targets are systematically eliminating solvent-cured adhesive categories from state-procured construction projects.
Japan
Automotive tier-one suppliers pilot hybrid acrylic-polyurethane copolymer emulsions for interior trim assembly applications requiring extended thermal cycling validation. METI promotes JIS-aligned green procurement criteria that favor low-emission bonding technologies in public infrastructure projects. Kanto and Kansai manufacturing networks sustain premium positioning through direct-to-mill technical support models.
India
Woodworking clusters in Gujarat and Punjab drive specification pull for panel-bonding emulsions in prefabricated furniture production. BIS mandates IS 15490 compliance for adhesive products in food-contact packaging, creating compliance barriers for uncertified imports. Dense dealer networks anchor decorative adhesive retail distribution across secondary cities and rural manufacturing zones.
Vietnam
Furniture export manufacturing zones are bypassing traditional dealer networks for formulation troubleshooting and batch optimization support. Small-scale mill technical service gaps create white space for direct-to-manufacturer formulation partnerships outside distributor networks. Ho Chi Minh City and Hanoi industrial corridors concentrate demand for EVA and PVA emulsion systems.
Thailand
Captive acrylic emulsion production facilities anchor regional polymer supply for packaging laminate converters serving export-market food-contact specifications. Automotive assembly plants in the Eastern Economic Corridor require waterborne polyurethane systems with flexibility under thermal cycling for interior component bonding. Bangkok-based distributors face narrowing margins as direct service models expand upstream.
Asia-Pacific Waterborne Adhesives Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on raw material supply. The Asia-Pacific waterborne adhesives market structures around three distinct competitive layers: multinational chemical conglomerates with captive polymer production, regional formulators with specialized application expertise, and distributor-dependent local blenders serving fragmented woodworking segments. Strategic moves concentrate on backward integration into emulsion manufacturing and direct-to-mill technical service deployment.
Among multinational chemical conglomerates, Dow and Henkel AG & Co. KGaA exemplify the platform-integrator archetype through captive supply chain control and direct service models. Pidilite Industries Ltd occupies a position representing the regional formulator tier with dense distribution networks in price-sensitive segments. These three anchors illustrate how competitive positioning diverges between premium specification-critical applications and volume-driven woodworking procurement.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| Ashland |
| Huntsman International LLC |
| Pidilite Industries Ltd |
| Bostik |
| Others |
Value Chain & Pricing Dynamics
Thai polymer supply concentration creates single-source dependency risks that compress margin predictability for mid-scale formulators while simultaneously widening spreads between captive-integrated and distributor-dependent pricing tiers. Acrylic monomer cost volatility feeds directly into formulation economics, forcing regional players to choose between long-term offtake commitments and spot-market exposure.
Pricing Analysis
Configured-to-order pricing for automotive-grade polyurethane emulsions commands substantial premiums over standard acrylic packaging grades. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact systems from uncertified commodity alternatives. Cost compression in mid-scale woodworking segments is intensifying because Indonesian and Vietnamese mills consolidate procurement volumes. Small-scale furniture manufacturers in Vietnam exhibit the highest price sensitivity, while Japanese automotive tier-one suppliers prioritize thermal cycling performance over unit cost.
Supply Chain Analysis
Export-control regimes on specialized surfactant chemistries limit technology transfer for free-radical polymerization process control. Captive acrylic emulsion production in Thailand, China, and Japan draws from petrochemical feedstock networks with varying degrees of backward integration. Raw material dependencies on acrylic acid, polyurethane prepolymers, and ethylene-vinyl acetate copolymers create vulnerability to feedstock price swings. Single-source vulnerability concentrates at Dow's Thailand facilities for regional packaging converters. Distribution runs through direct-to-mill technical service teams that are displacing traditional dealer networks across Southeast Asian woodworking clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE enforcement of GB standards for interior building materials represents a regulatory inflection that is systematically eliminating solvent-cured alternatives and redirecting specification authority toward certified waterborne systems.
For Market Incumbents: Build formulation certification moats around IS 15490 compliance services and BIS registration pathways in India. Deepen captive emulsion manufacturing in Thailand to offset acrylic monomer cost volatility. Secure direct-to-mill technical service contracts in Vietnam's furniture export zones before distributor networks collapse entirely. For New Entrants and Emerging Players: Small-scale mill technical service gaps in Indonesia and Vietnam represent the most penetrable entry point for formulation partnerships outside established distribution channels. Target advisory revenue streams around India's BIS food-contact certification requirements for adhesive products. Pursue joint development agreements with prefabricated construction module manufacturers in China's Jiangsu and Guangdong provinces seeking GB standard compliance. For Investors and Strategic Acquirers: ASEAN harmonization of chemical hazard classifications reshapes the acquisition landscape by extending product launch timelines and raising compliance barriers. Long-term viability favors targets with captive emulsion manufacturing and established direct service infrastructure. Watch for MEE audit frequency and GB standard expansion into additional construction material categories as signals of regulatory acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Manufacturing | Captive supply from Thailand facilities insulates against monomer cost volatility and single-source dependency. |
| Direct-to-Mill Technical Service Deployment | Henkel's Vietnam expansion demonstrates channel compression that eliminates distributor margin extraction. |
| IS 15490 Compliance Certification Investment | BIS mandates for food-contact packaging create advisory revenue streams and import barriers for uncertified competitors. |
| Hybrid Acrylic-Polyurethane Copolymer Development | Japanese automotive tier-one pilots show virtualization potential between commodity packaging and premium automotive grades. |
| Joint Venture with Prefabricated Construction Manufacturers | GB standard enforcement in Jiangsu and Guangdong accelerates validation partnerships for state-procured projects. |
Study Parameters
Initial hypotheses were tested against primary input from adhesive formulators, packaging converter procurement leads, woodworking mill technical directors, and automotive tier-one supplier engineers and refined through secondary validation against customs trade data, BIS certification registries, MEE enforcement disclosures, and SEC filings from multinational chemical conglomerates. Bottom-up demand modeling across end-use segments was triangulated with top-down supply capacity assessments from regional emulsion manufacturing facilities.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included polymer chemistry type, end-use industry vertical, application method, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis applied to segment-level volume trajectories. Forecast inputs incorporated MEE permit restriction timelines and ASEAN harmonization progress on chemical hazard classifications.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing, currency volatility across Southeast Asian manufacturing currencies, or construction sector investment cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between solvent-cured and waterborne systems. Material shifts in China's dual carbon policy implementation pace or ASEAN regulatory harmonization completion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
China Sealants Market