
 Asia-Pacific Epoxy Curing Agents Market | 2026-2036
Asia-Pacific Epoxy Curing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Epoxy Curing Agents Market Outlook
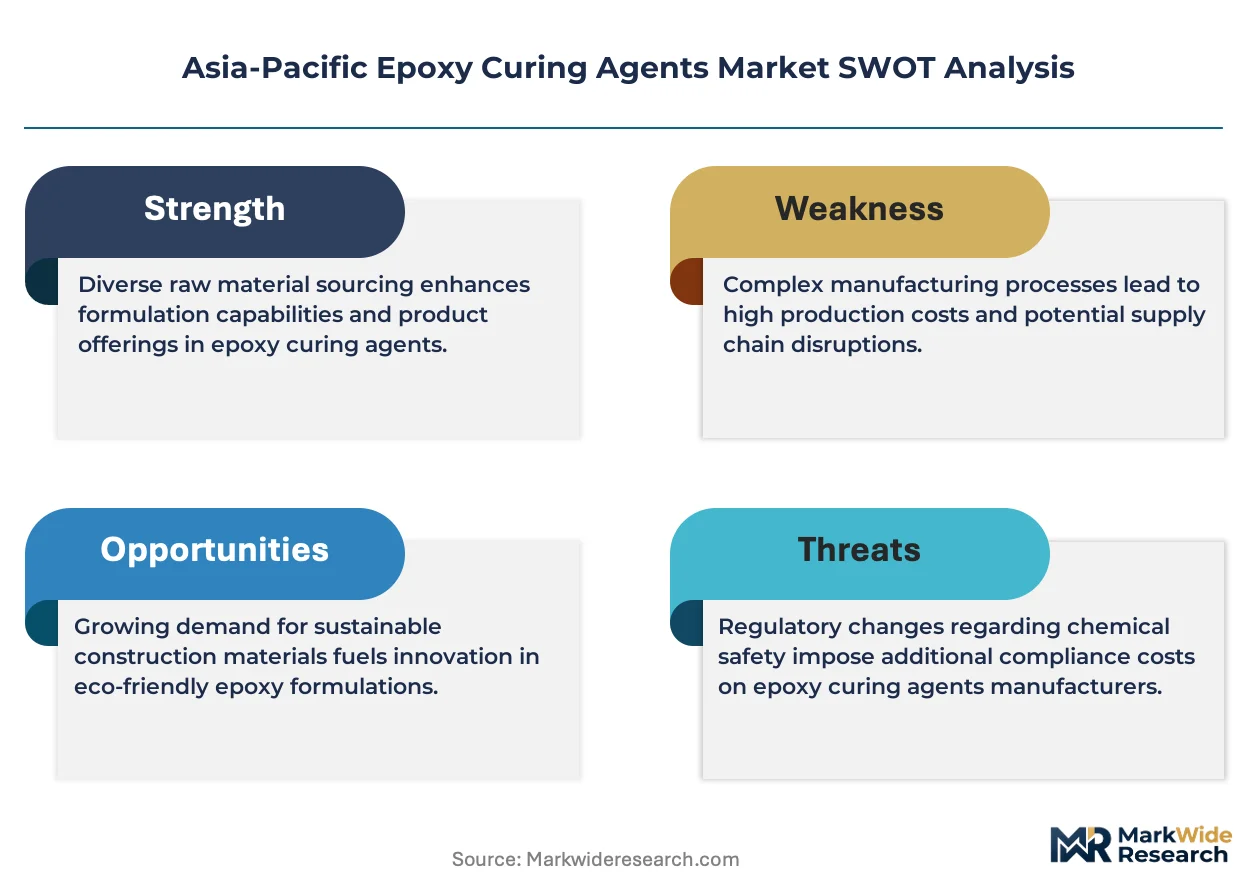
The capability gap between integrated petrochemical producers and regional compounders is collapsing as Chinese state-backed resin complexes achieve captive amine supply. Huntsman Corporation sustains technology leadership through proprietary cycloaliphatic amine platforms serving electronic encapsulation grades. BASF SE anchors its position with backward integration into key intermediates for aromatic amine curing agents. Aditya Birla Chemicals leverages India's phenolic feedstock access to compete on modified phenalkamine systems for marine coatings.
Epoxy curing agents are chemical hardeners—typically amine, phenolic, or imidazole compounds—that cross-link epoxy resins through addition or catalytic reactions, achieving gel times from minutes to hours and glass transition temperatures exceeding 150°C for high-performance grades. Their primary industrial purpose is to convert liquid or solid epoxy prepolymers into thermoset networks with tailored mechanical, chemical, and thermal resistance for protective and structural applications. Aliphatic amine formulations dominate volume in construction floor coatings and civil engineering adhesives where fast cure at ambient temperature commands premium placement. Imidazole segments are expanding fastest in electronic encapsulation for electric vehicle power modules, where latent cure behavior enables automated dispensing without pot-life constraints. Phenolic curing agents occupy stable margin pools in corrosion-resistant marine and industrial maintenance coatings, where phenalkamine chemistry delivers surface-tolerant application on poorly prepared steel.
Japan's METI enforces industrial chemical emission controls that restrict solvent-borne amine usage, while China's SAMR administers GB standards for construction chemical safety that mandate VOC disclosure on curing agent labels. Australia's TGA and South Korea's MFDS maintain separate but converging frameworks for chemical substances in consumer-facing epoxy applications, creating compliance complexity for multi-country suppliers. REACH-equivalent regulatory momentum across ASEAN member states is tightening registration requirements for imported amine hardeners, reshaping import substitution incentives for domestic producers. Stakeholders must monitor regulatory divergence between Northeast Asian precision standards and Southeast Asian phased implementation timelines when configuring regional supply footprints.
Market Dynamics
Chinese state-backed resin complexes are collapsing the capability gap between integrated petrochemical producers and regional compounders through captive amine supply, forcing technology-based differentiation among specialty formulators.
Growth Catalysts
- Construction sector procurement:China's eastern coastal manufacturing belt and Southeast Asian infrastructure projects are expanding high-performance adhesive and coating demand for civil engineering applications.
- METI VOC emission standards:Japan's stricter industrial chemical emission controls under Ministry of Economy, Trade and Industry oversight redirect formulation demand toward low-emission curing systems.
- Electric vehicle power modules:Imidazole latent cure behavior enables automated dispensing without pot-life constraints, accelerating electronic encapsulation adoption.
Market Restraints
- Aromatic amine intermediate concentration:Backward integration by European and North Asian majors limits feedstock access for independent compounders.
- Phenolic feedstock volatility:Modified phenalkamine systems depend on fluctuating phenol derivatives, compressing margin pools in marine coatings.
- REACH-equivalent divergence:ASEAN member states maintain phased implementation timelines that create registration complexity for imported amine hardeners.
Strategic Opportunities
- India phenolic feedstock access:Domestic phenol derivative availability supports modified phenalkamine production for corrosion-resistant marine applications.
- GB standards compliance services:China's State Administration for Market Regulation mandates for construction chemical safety create advisory revenue streams for formulation partners.
- Imidazole-epoxy convergence:Latent cure chemistry integration with automated dispensing equipment opens electric vehicle battery module assembly contracts.
Industry Challenges
- Cycloaliphatic amine synthesis expertise:Electronic encapsulation grades require specialized catalytic hydrogenation capabilities scarce outside integrated producers.
- Multi-jurisdiction label compliance:Australia's TGA, South Korea's MFDS, and Japan's METI maintain divergent disclosure frameworks for consumer-facing epoxy applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Epoxy Curing Agents Market |
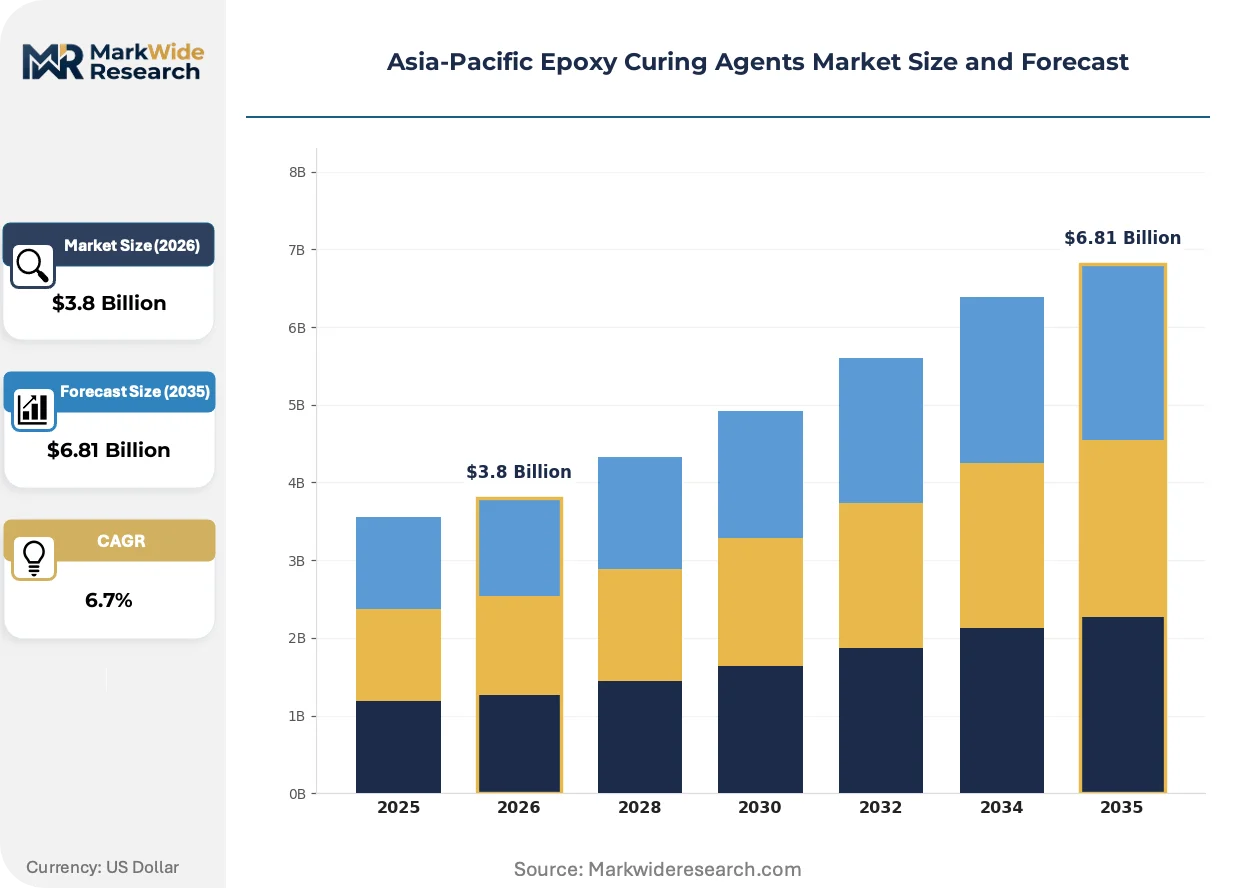
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Amine, Aliphatic Amine, Phenolic, Imidazole Application: Coatings, Adhesives, Composites, Electronic Encapsulation End User: Aerospace, Automotive, Construction, Marine Form: Liquid, Solid, Powder, Gel |
| Companies Covered | BASF SE, Evonik Industries AG, Huntsman Corporation, Hexion, Aditya Birla Chemicals, Mitsubishi Chemical, Atul Ltd., Arkema, Cardolite Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Epoxy Curing Agents Market Strategic Shifts
Formulation chemistry and regulatory compliance frameworks are actively reshaping competitive positioning across the Asia-Pacific epoxy curing agents landscape. Three distinct movements are compressing development cycles and redistributing value capture.
Latent imidazole curing systems are miniaturizing thermal management architectures in electric vehicle power electronics. Automotive OEMs in South Korea and Japan are adopting these chemistries at compressed validation timelines. The technology is miniaturizing heat sink and substrate integration, reducing module footprint while maintaining glass transition temperatures above 150°C.
METI's industrial chemical emission controls and China's GB standards for construction chemical safety are tightening in parallel. Formulators must now maintain separate technical data sheets and hazard classifications for Japanese and Chinese markets. The construction adhesives segment bears the highest compliance burden, with suppliers building dual-track regulatory affairs capabilities.
Specification-driven procurement now dominates automotive and electronics OEM relationships with curing agent suppliers. Long-term supply agreements with embedded technical service requirements are displacing spot market transactions. This pattern is most visible in China's Yangtze River Delta, where downstream resin clusters serve integrated manufacturing ecosystems.
Asia-Pacific Epoxy Curing Agents Market Segmentation
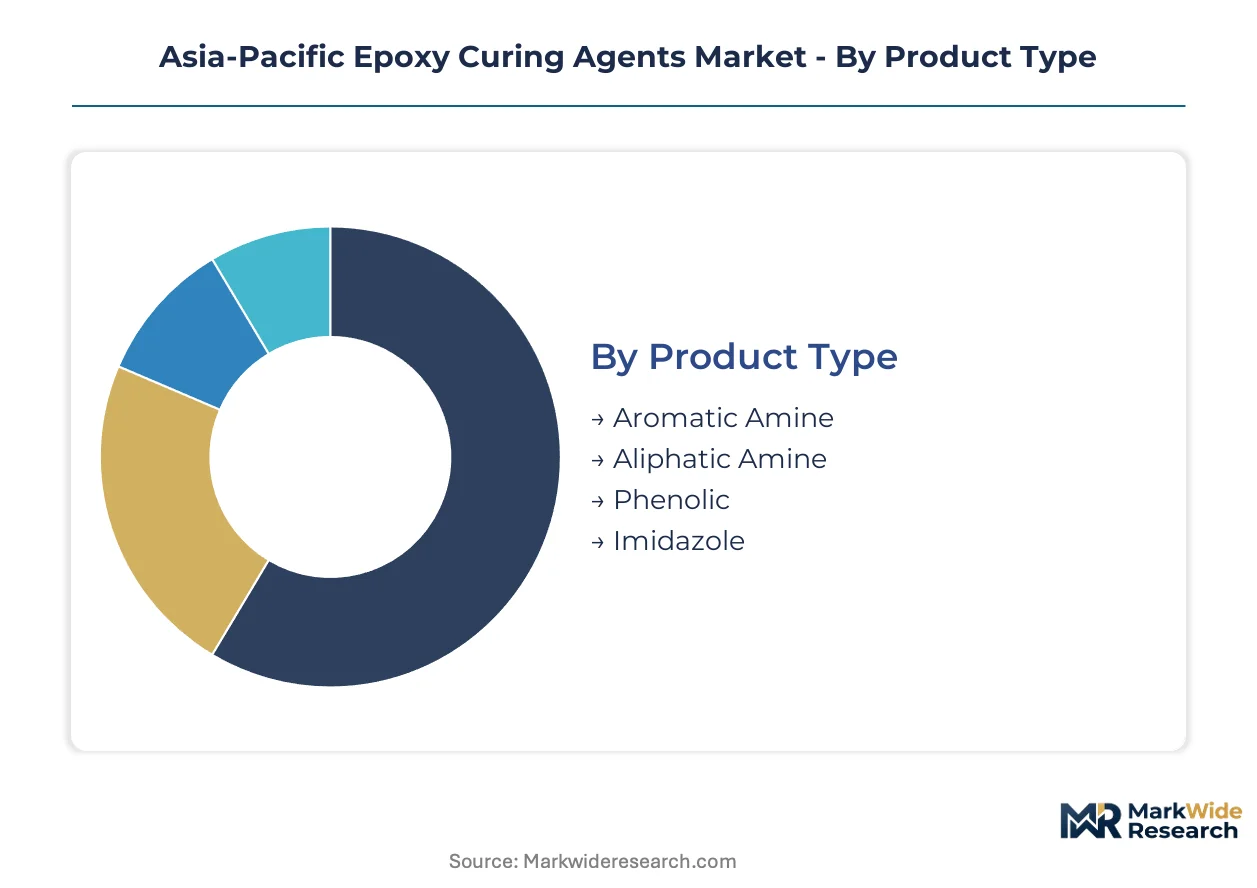
Epoxy curing agent suppliers configure product portfolios around distinct performance thresholds and regulatory constraints. Segmentation clarity determines pricing architecture and technical service allocation across the Asia-Pacific region.
Product Type:
Substitution pressure from Chinese captive amine supply is reshaping margin structures most aggressively in aromatic amine and aliphatic amine categories.
- Aromatic Amine:These aniline-derivative hardeners deliver elevated glass transition temperatures above 150°C and superior chemical resistance for industrial maintenance coatings. Demand concentrates in Japan's chemical processing infrastructure where METI emission controls restrict solvent-borne alternatives.
- Aliphatic Amine:Fast-cure formulations achieve gel times under 30 minutes at ambient temperature, commanding premium placement in China's construction floor coatings sector. Procurement from civil engineering contractors in the Yangtze River Delta is expanding despite volatility in ethyleneamine feedstock costs.
- Phenolic:Phenalkamine chemistry enables surface-tolerant application on poorly prepared steel for marine coatings.
- Imidazole:Latent cure behavior supports automated dispensing in electric vehicle power module assembly without pot-life constraints.
Aliphatic amine retains volume leadership; imidazole holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-driven OEM relationships from price-sensitive maintenance markets.
- Coatings:Protective and marine formulations represent the largest volume outlet, with phenolic curing agents dominating corrosion-resistant applications. China's GB standards for construction chemical safety mandate VOC disclosure that elevates compliance costs for imported formulations.
- Adhesives:Structural bonding applications in civil engineering command premium pricing for fast-cure aliphatic systems. Southeast Asian infrastructure projects are expanding procurement of high-performance grades for bridge and tunnel construction.
- Composites:Wind blade and aerospace prepregs require controlled exotherm profiles achievable through blended amine systems.
- Electronic Encapsulation:Imidazole latent cure chemistry enables miniaturized thermal management in South Korean and Japanese automotive power electronics.
Coatings maintains revenue concentration; electronic encapsulation is climbing the fastest.
End User:
Customer type fragmentation creates divergent service intensity requirements across specification-driven and price-sensitive accounts.
- Construction:Civil engineering contractors in China and Southeast Asia drive volume demand for ambient-cure systems in floor coatings and structural adhesives.
- Automotive:Electric vehicle OEMs in South Korea and Japan are accelerating validation timelines for imidazole-based electronic encapsulation grades.
- Marine:Shipyard maintenance operations in China and Japan specify phenalkamine systems for surface-tolerant corrosion protection.
- Aerospace:Composite prepregs for aircraft structures require catalytic hydrogenation capabilities scarce outside integrated producers.
Construction dominates procurement volume; automotive is gaining share fastest.
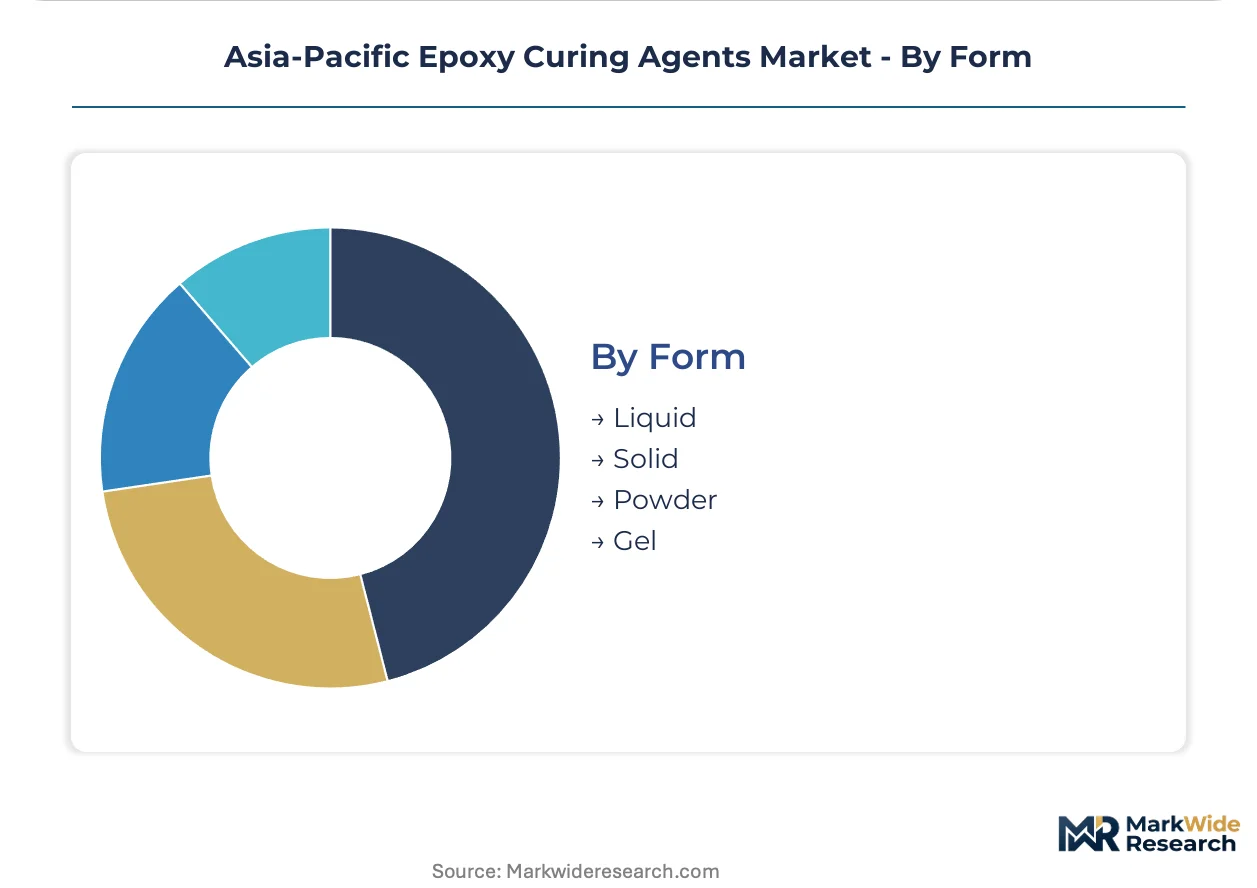
Form:
Supply concentration in liquid formulations is compressing margins for regional compounders lacking solid-phase processing capabilities.
- Liquid:Low-viscosity amine adducts dominate construction and industrial maintenance applications where ease of mixing commands preference. China's eastern coastal manufacturing belt concentrates blending operations for downstream resin clusters.
- Solid:Powder and flake forms enable hot-melt compounding in powder coatings and advanced composites. Japanese electronics OEMs specify solid imidazole derivatives for automated dispensing equipment compatibility.
- Powder:Low-temperature curing grades serve coil coating and appliance finishing applications.
- Gel:Thixotropic formulations support vertical surface application in marine and infrastructure maintenance.
Liquid retains volume leadership; solid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific epoxy curing agents landscape. Procurement in Southeast Asian infrastructure projects remains highly sensitive to feedstock volatility. Japanese and South Korean electronics OEMs exhibit low elasticity for imidazole grades serving power module encapsulation.
China
Civil engineering contractors in the Yangtze River Delta drive volume demand for fast-cure aliphatic amine systems in floor coatings and structural adhesives. SAMR's GB standards for construction chemical safety mandate VOC disclosure on curing agent labels. The eastern coastal manufacturing belt concentrates downstream epoxy resin clusters serving automotive and electronics OEMs with specification-driven procurement.
Japan
Electric vehicle OEMs accelerate validation timelines for imidazole-based electronic encapsulation grades with glass transition temperatures exceeding 150°C. METI enforces stricter industrial chemical emission controls that redirect formulation demand toward low-emission curing systems. The Kanto region around Tokyo hosts precision electronics manufacturers specifying solid imidazole derivatives for automated dispensing compatibility.
South Korea
Automotive power module assembly lines adopt latent cure chemistry enabling miniaturized thermal management without pot-life constraints. MFDS maintains disclosure frameworks for chemical substances in consumer-facing epoxy applications that diverge from Japanese METI standards. The Seoul Capital Area concentrates electronics packaging operations requiring catalytic hydrogenation capabilities for high-performance grades.
India
Domestic phenol derivative availability supports modified phenalkamine production for corrosion-resistant marine coatings with surface-tolerant application properties. CDSCO and BIS administer converging but separate frameworks for industrial chemical safety that create multi-jurisdiction compliance complexity. Gujarat's petrochemical corridor anchors phenolic feedstock access for regional compounders competing on marine coating systems.
Australia
Industrial maintenance contractors specify phenalkamine chemistry for surface-tolerant corrosion protection on poorly prepared steel infrastructure. TGA maintains registration requirements for imported amine hardeners that reshape import substitution incentives for domestic blenders. Queensland and Western Australia concentrate mining equipment maintenance operations driving procurement of ambient-cure protective coatings.
Asia-Pacific Epoxy Curing Agents Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific epoxy curing agents structure. European and North Asian majors control aromatic amine intermediate supply through backward integration into key feedstocks. Three archetypes dominate: integrated petrochemical producers with captive amine supply, specialty formulators with cycloaliphatic synthesis expertise, and regional compounders leveraging local feedstock access. Capacity expansion and technology licensing represent the dominant competitive moves as Chinese state-backed complexes collapse historical capability gaps.
Within the integrated tier, BASF SE anchors European presence through upstream control over aromatic amine intermediates. Huntsman Corporation exemplifies specialty technology leadership with proprietary platforms serving electronic encapsulation grades. Aditya Birla Chemicals occupies a position among regional feedstock-advantaged players leveraging India's phenolic derivative access. These three represent distinct strategic archetypes rather than direct competitors across identical product segments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Huntsman Corporation |
| Hexion |
| Aditya Birla Chemicals |
| Mitsubishi Chemical |
| Atul Ltd. |
| Arkema |
| Cardolite Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive amine substitution by Chinese state-backed resin complexes simultaneously collapses historical supply geography and compresses pricing power for independent compounders across the Asia-Pacific epoxy curing agents landscape. This feedstock displacement redistributes margin capture toward integrated producers while forcing specialty formulators toward technical service bundling.
Pricing Analysis
Technical service contracts and formulation advisory revenue now drive lifetime value beyond base chemical offtake. Three-tier pricing structure across premium electronic grades, standard industrial formulations, and economy construction blends separates specification-driven OEM procurement from spot-market transactions. Cost compression in aliphatic amine construction tiers is intensifying because Chinese captive supply eliminates feedstock scarcity premiums. Civil engineering contractors in China's Yangtze River Delta exhibit highest price sensitivity, while Japanese automotive OEMs show lowest elasticity for imidazole electronic encapsulation grades.
Supply Chain Analysis
Ethyleneamine feedstock transit through Singapore's petrochemical hub underwrites formulation cost stability for Southeast Asian compounders. Manufacturing concentrates in China, Japan, and South Korea, with downstream blending operations clustering in China's eastern coastal belt. Raw material dependencies center on aniline derivatives, phenol feedstocks, and catalytic hydrogenation intermediates. Single-source vulnerability in cycloaliphatic amine synthesis capabilities creates supply risk for electronic encapsulation grades. Distribution runs through regional resin clusters serving automotive and electronics OEMs with specification-driven procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry advisory and regulatory compliance services represent a faster-expanding recurring revenue layer than base curing agent offtake, transforming procurement relationships into embedded technical partnerships.
For Market Incumbents: Consolidate cycloaliphatic amine synthesis capabilities through selective technology licensing to defend electronic encapsulation margins against Chinese state-backed resin complex expansion. Deepen backward integration into key aromatic amine intermediates to secure feedstock access as independent compounders face supply constraints. Prioritize dual-track regulatory affairs capabilities spanning Japan's METI emission controls and China's SAMR GB standards to capture compliance service revenue. For New Entrants and Emerging Players: Differentiate on phenalkamine surface-tolerant chemistry for marine maintenance coatings where established players underinvest in technical service intensity. Target India's Gujarat petrochemical corridor for modified phenolic system production leveraging domestic feedstock access. Pursue imidazole latent cure formulations for South Korean electric vehicle power module assembly as the most penetrable high-growth segment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty formulators with proprietary catalytic hydrogenation capabilities and regulatory compliance expertise. Long-term viability hinges on technology differentiation rather than commodity scale as Chinese captive supply erodes volume-based positioning. Monitor ASEAN REACH-equivalent implementation timelines as the signal to watch for import substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Amine Intermediates | Secures feedstock access against Chinese state-backed resin complex expansion. |
| Long-term Supply Agreement with Electronics OEMs | Locks in specification-driven procurement for imidazole encapsulation grades. |
| Joint Venture for Cycloaliphatic Amine Synthesis | Addresses capability scarcity outside integrated petrochemical producers. |
| Capacity Expansion in India's Phenolic Feedstock Corridor | Captures marine coatings demand with surface-tolerant phenalkamine systems. |
| Green Manufacturing Transition for Low-Emission Curing Systems | Aligns product portfolios with Japan's METI VOC emission standards. |
Study Parameters
The analysis maps aromatic amine, aliphatic amine, phenolic, and imidazole curing agent sub-sectors, each validated through technical R&D directors at integrated producers, procurement leads at automotive and electronics OEMs, and distribution channel partners across the Asia-Pacific region. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings for listed chemical producers. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Consistency checks against external benchmarks validated output robustness across the projection horizon. The analytical framework modeled product type, application, end user, and form dimensions alongside regional production hub clustering. CAGRs derived from segment-level growth trajectory analysis incorporating electric vehicle power module demand curves, construction sector procurement patterns, and regulatory compliance cost escalations. Industry-specific forecast inputs included ethyleneamine feedstock cost volatility and METI emission standard implementation timelines.
Material uncertainties — feedstock substitution acceleration, ASEAN regulatory divergence, and electronics OEM validation timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology adoption curves and supply chain reconfiguration speed. Practitioners should keep alternative scenarios live as Chinese state-backed resin complex capacity expansion and REACH-equivalent registration requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Conductive Adhesive Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Marine Sealants Market