

Acetate Silicone Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Acetate Silicone Sealant Market Insights
Commercial glazing contractors and marine refit specialists are redrawing procurement patterns as acetate silicone sealant specifications tighten across project tiers. Dow anchors its position through captive silane supply and in-house production of polymer intermediates. Sika AG competes on construction channel density, embedding its product lines within contractor specification databases across European markets. Momentive Performance Materials differentiates through heat-cure technology leadership for automotive assembly applications where cycle-time compression commands premium positioning.
Acetate silicone sealant comprises a polydimethylsiloxane base cured by atmospheric moisture with acetic acid release, typically exhibiting Shore A hardness of 20-35 and elongation at break exceeding 400 percent, engineered primarily for bonded sealing in structural glazing and wet-area environments. Neutral cure formulations now lead volume in window and glazing applications where substrate corrosion sensitivity excludes acid-cure alternatives, while specialty grades command the strongest margin pools in electrical encapsulation due to dielectric stability requirements. Room temperature vulcanizing technology sustains the broadest installed base, though UV cure systems are gaining fastest in automotive assembly lines seeking line-speed gains without thermal substrate exposure.
FDA and EPA frameworks govern sealant contact and emission profiles in US food-processing and commercial building applications, while REACH and the EU F-Gas Regulation shape material compliance thresholds for European supply. China's GB standards and MEE directives impose parallel VOC and hazardous substance controls on imported and domestic formulations alike. Stakeholders must monitor divergence between regional cure-chemistry approval lists, as specification misalignment between North American and European contractor standards threatens to fragment product platform economics and force regional formulation duplication.
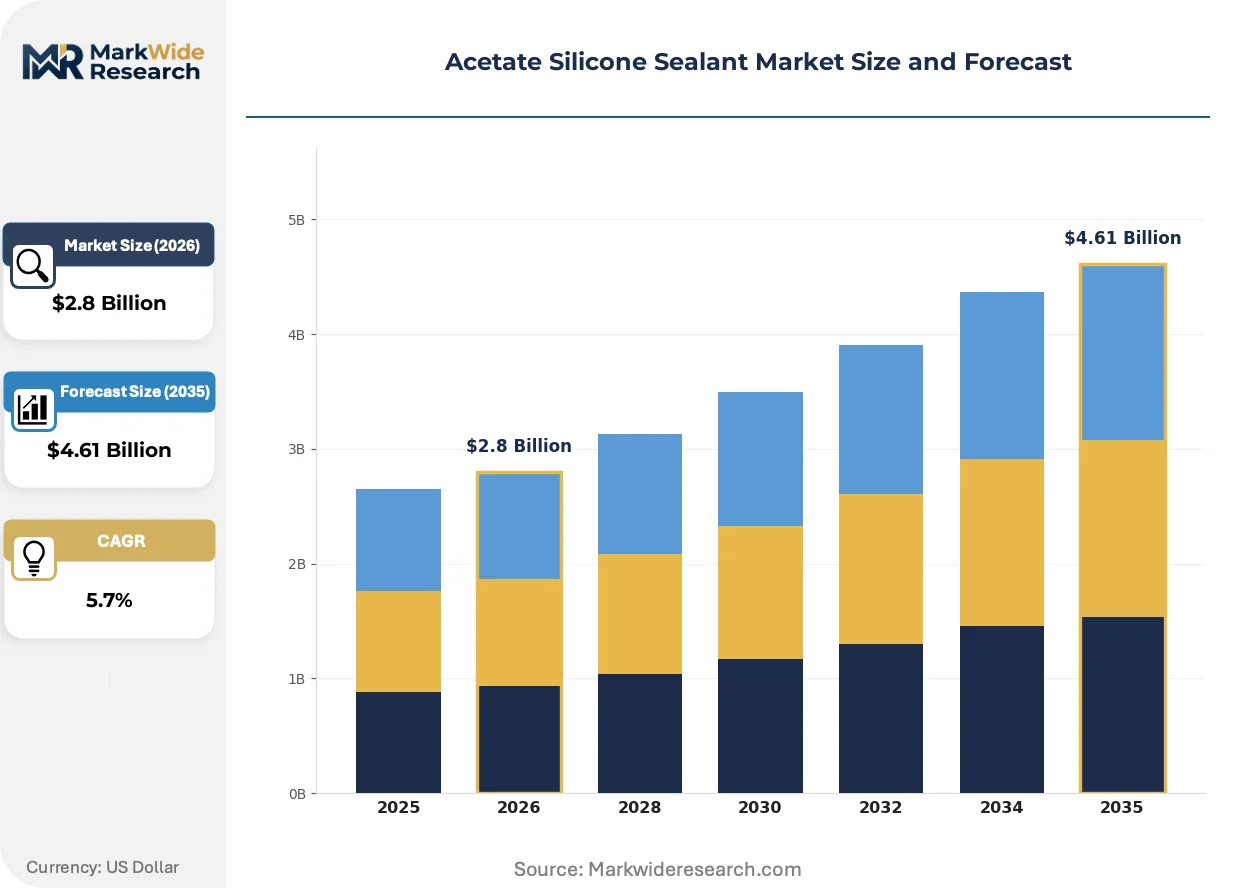
Market Dynamics
Neutral cure silicone sealant chemistry is displacing acetate formulations in high-rise glazing specifications across Germany, China, and the United States as building energy codes tighten substrate corrosion requirements and contractors prioritize multi-substrate adhesion warranties.
Growth Catalysts
- EU Green Deal VOC thresholds:REACH mandates on low-emission cure systems are accelerating specification upgrades toward compliant neutral cure systems in commercial construction across Germany and France.
- Automotive lightweighting programs:Assembly line demand for heat-cure sealants with compressed cycle times is pulling specialty acetate grades into bonded sealing applications for electric vehicle battery enclosures.
- China's MEE directives:Hazardous substance controls on imported formulations are forcing domestic production scale-up of GB-standard compliant sealants for infrastructure glazing.
Market Restraints
- Silane monomer supply concentration:Captive production of polymer intermediates concentrates among three integrated chemical groups, creating input cost volatility for non-integrated formulators.
- Acetic acid emission limitations:Acid-cure chemistry faces technical exclusion from corrosion-sensitive substrates including copper, brass, and certain coated metals in architectural applications.
- Neutral cure substitution pressure:Oxime and alkoxy cure systems are capturing specification share in window and glazing channels where substrate compatibility drives contractor preference.
Strategic Opportunities
- Electrical encapsulation dielectric grades:Specialty acetate formulations with thermal stability above 150°C are opening margin pools in power electronics and EV charging infrastructure.
- Marine refit channel expansion:Wet-area sealing specifications in yacht and commercial vessel maintenance are concentrating procurement through specialized distributors in Mediterranean and Gulf Coast clusters.
- UV cure technology convergence:Hybrid systems combining atmospheric moisture cure with photoinitiated acceleration are enabling line-speed gains without thermal substrate exposure in automotive assembly.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in silane-terminated polymer synthesis and cure kinetics is concentrating among retiring technical staff at established manufacturers.
- Regional approval list divergence:Misalignment between North American contractor standards and European cure-chemistry approvals is forcing product platform duplication and inventory fragmentation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetate Silicone Sealant Market Trends and Innovations
Acetate silicone sealant innovation is compressing around cure speed, emission profile, and substrate compatibility as end-users consolidate specifications and regulators tighten material compliance thresholds across construction and transportation verticals.
Alkoxy-functional silane crosslinkers are displacing traditional acetate cure systems in premium glazing specifications where contractors demand odorless application and corrosion-free adhesion to anodized aluminum and reflective glass coatings. German and Chinese facade engineers are specifying these formulations for high-rise projects with 25-year performance warranties. The shift is compressing acid-cure volume in commercial construction while creating premium pricing tiers for compliant neutral cure alternatives.
REACH authorization requirements for certain siloxane intermediates are forcing reformulation investments across European supply chains as ECHA evaluates substance hazards. Manufacturers with in-house polymer synthesis capabilities are accelerating registration dossiers for alternative crosslinker chemistries. The regulatory pressure is concentrating supply among integrated producers with dedicated regulatory affairs functions and fragmenting access for import-dependent distributors.
Specification databases controlled by major construction channel partners are consolidating contractor procurement decisions around pre-approved product lists with embedded performance testing data. German and US glazing contractors are accessing these platforms through mobile applications that filter sealant selection by substrate, movement capability, and warranty terms. The behavioral shift is compressing brand consideration sets and elevating channel density as a competitive moat for embedded suppliers.
Acetate Silicone Sealant Market Segmentation
Acetate silicone sealant procurement channels fragment sharply by cure chemistry and performance tier, with construction distributors, automotive Tier-1 suppliers, and marine refit specialists each demanding distinct specification bundles. Understanding segment-channel alignment reveals where margin pools concentrate and which technology investments command priority.
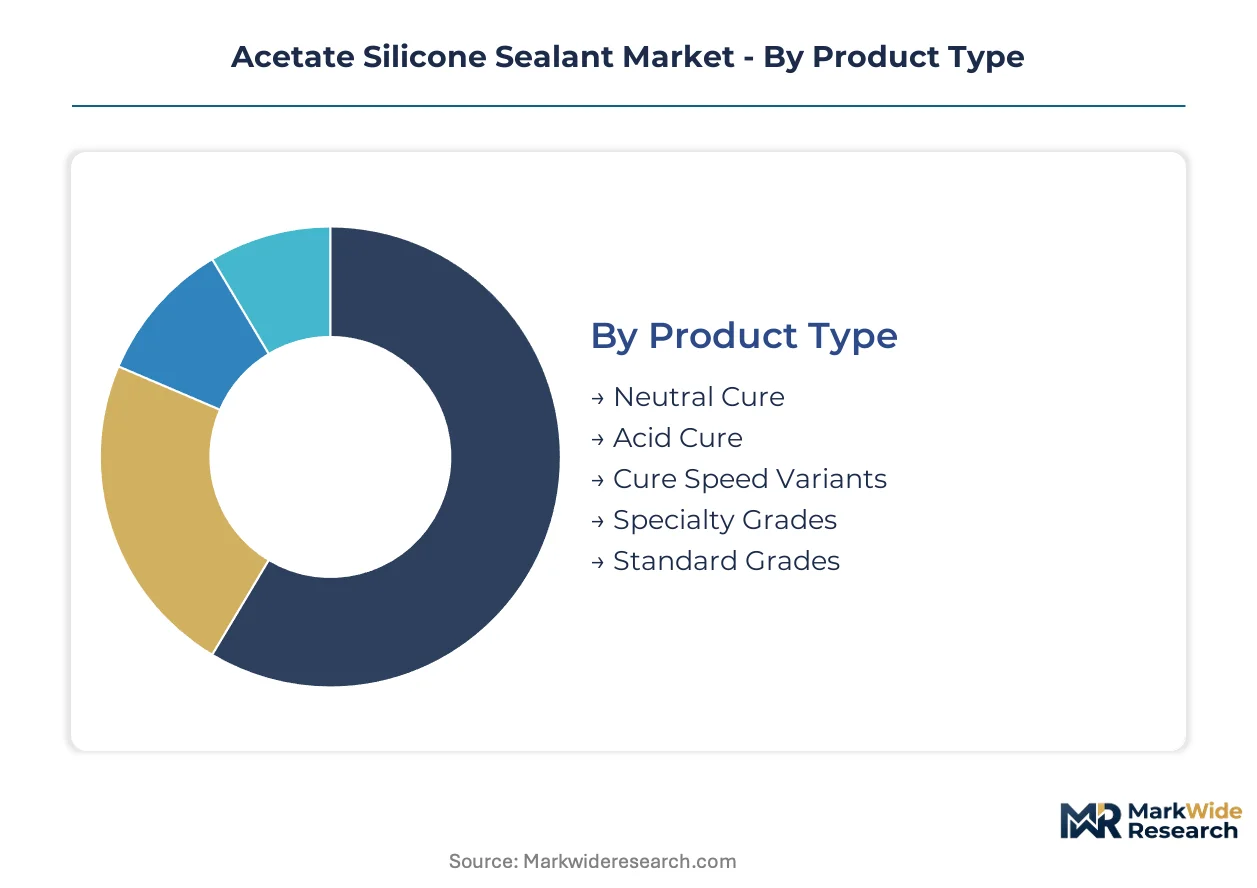
Product Type:
Channel mix varies dramatically by cure chemistry, with neutral cure formulations flowing through architectural specification databases while acid cure products concentrate in retail hardware and contractor direct-buy programs.
- Neutral Cure:Alkoxy-functional silane crosslinkers release methanol or ethanol during cure, eliminating substrate corrosion risk on anodized aluminum and reflective glass coatings. German and Chinese facade engineers specify these formulations for high-rise glazing with 25-year adhesion warranties, compressing acid-cure share in commercial construction.
- Acid Cure:Acetic acid release during atmospheric moisture cure delivers rapid skin formation and strong adhesion to glass, ceramics, and non-porous substrates. Demand concentrates in residential window installation and sanitary sealing where copper and brass exposure is minimal.
- Cure Speed Variants:Fast-skin formulations target production line sealing in automotive assembly where compressed cycle times justify premium positioning.
- Specialty Grades:Dielectric-stable formulations with thermal resistance above 150°C serve power electronics and EV charging infrastructure.
- Standard Grades:General-purpose acetate systems dominate volume in maintenance, repair, and operations procurement through construction wholesalers.
Neutral cure dominates installed base in commercial glazing channels. Specialty grades represent where expansion concentrates for margin-focused manufacturers.
Technology:
Process economics and capital intensity separate these technologies, with room temperature vulcanizing sustaining the broadest equipment base while heat cure and UV systems demand specialized application infrastructure.
- Room Temperature Vulcanizing:Atmospheric moisture activation without thermal or radiant energy input sustains the largest installed application base across construction and maintenance channels. Contractors in the United States and Germany rely on RTV systems for field glazing where portable equipment constraints exclude alternative cure methods.
- Heat Cure:Elevated temperature activation compresses full cure from hours to minutes, enabling bonded sealing in automotive battery enclosure assembly where line-speed targets exclude ambient cure alternatives.
- UV Cure:Photoinitiated polymerization delivers instant handling strength without thermal substrate exposure, gaining specification in automotive paint shops where temperature-sensitive coatings require protection.
- Solvent Release:Evaporative drying systems serve specialized coating and masking applications outside mainstream sealant channels.
- Two-Component Systems:Meter-mixed application delivers accelerated cure in industrial assembly where equipment investment amortizes across high-volume production.
RTV technology anchors volume across construction and maintenance. UV cure is climbing the fastest in automotive assembly lines seeking speed without thermal damage.
Application:
Specification authority resides with distinct stakeholder groups per application, from facade engineers controlling glazing standards to marine surveyors governing wet-area compliance.
- Window & Glazing:Structural and weatherseal bonding in commercial curtainwall and residential fenestration commands the largest formulation volume. REACH VOC thresholds and Germany's energy code enforcement are accelerating neutral cure substitution in this channel.
- Sanitary Sealing:Wet-area applications in bathrooms, kitchens, and food-processing facilities demand mold-resistant formulations with FDA or EFSA compliance for incidental food contact.
- Automotive Assembly:Bonded sealing in electric vehicle battery enclosures and lighting assemblies pulls heat-cure and UV-accelerated systems into high-volume production.
- Electrical Encapsulation:Dielectric stability and thermal management requirements in power electronics create premium pricing tiers for specialty acetate grades.
- Marine Adhesion:Yacht and commercial vessel refit specifications concentrate procurement through Mediterranean and Gulf Coast distributor clusters with surveyor-approved product lists.
Window and glazing holds the deepest installed base. Electrical encapsulation offers the steepest expansion trajectory for margin-accretive specialty formulations.
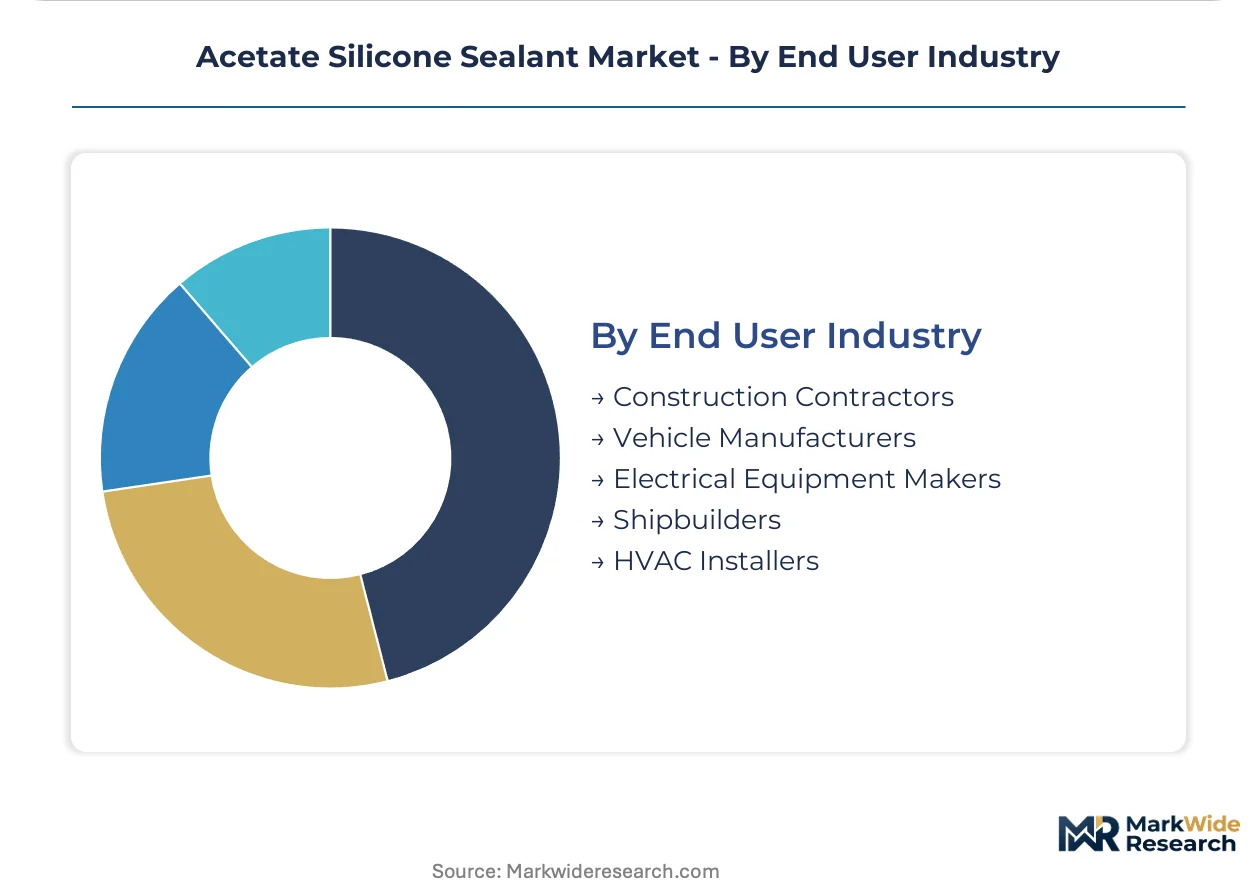
End User Industry:
Procurement sophistication varies sharply, with vehicle manufacturers and electrical equipment makers demanding embedded technical service while construction contractors prioritize specification database access and warranty terms.
- Construction Contractors:Commercial glazing and general contracting firms access sealant specifications through mobile-enabled product databases that filter by substrate compatibility and movement capability. German and US contractors consolidate procurement around pre-approved lists with embedded performance testing data.
- Vehicle Manufacturers:Automotive OEMs and Tier-1 suppliers specify sealants through bonded sealing engineering groups focused on cycle-time compression and corrosion resistance validation.
- Electrical Equipment Makers:Power electronics and EV charging infrastructure manufacturers drive demand for thermal stability and dielectric performance certification.
- Shipbuilders:New construction and refit yards in Mediterranean and Gulf Coast clusters specify through marine surveyor-approved distributor networks.
- HVAC Installers:Mechanical contractors source general-purpose grades through wholesale HVAC distributors with emphasis on temperature resistance and ease of application.
Construction contractors dominate volume throughput. Vehicle manufacturers concentrate expansion as electrification programs accelerate bonded sealing specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive silane production clusters in Germany, China, and the United States concentrate supply leverage for integrated formulators. Building energy codes and automotive lightweighting programs in these markets are accelerating specification upgrades toward low-emission cure systems. Regulatory divergence between REACH-authorization frameworks and China's MEE directives is fragmenting regional formulation requirements.
Germany
Commercial glazing contractors in Frankfurt and Munich are specifying neutral cure formulations for high-rise curtainwall projects with 25-year adhesion warranties. REACH mandates on VOC thresholds and the EU F-Gas Regulation are accelerating compliance investments among sealant formulators. The Rhine-Ruhr industrial corridor hosts integrated chemical producers with in-house polymer synthesis capabilities serving facade engineering clusters.
China
GB standards and MEE directives on hazardous substance controls are forcing domestic production scale-up of compliant sealants for infrastructure glazing. Building energy codes in Beijing and Shanghai are tightening substrate corrosion requirements for commercial fenestration. The Yangtze River Delta concentrates manufacturing capacity for both acid-cure and neutral cure formulations serving domestic contractors and export markets.
United States
FDA and EPA frameworks govern sealant contact and emission profiles in food-processing and commercial building applications across Texas and California. Automotive OEMs in Michigan are specifying heat-cure systems for electric vehicle battery enclosure assembly. The Southeast construction corridor from Florida to Georgia is consolidating procurement through mobile-enabled specification databases filtering by substrate compatibility.
Japan
METI industrial standards and JIS certification requirements shape material compliance thresholds for sealants in automotive and electronics applications. Automotive assemblers in the Nagoya region are adopting UV-accelerated cure systems for paint shop integration. The Kanto industrial belt around Tokyo concentrates demand for dielectric-stable specialty grades in power electronics manufacturing.
United Arab Emirates
MOHAP regulations and municipal building codes in Dubai and Abu Dhabi are tightening material specifications for high-performance glazing in commercial towers. Marine refit specialists in Jebel Ali and Dubai Maritime City are concentrating procurement through surveyor-approved distributor networks. The UAE's position as a Gulf trade hub is attracting regional headquarters for sealant suppliers serving Saudi and Qatari construction markets.
Acetate Silicone Sealant Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling captive silane supply and polymer intermediate production. Three to five multinational groups anchor volume leadership through construction channel density and automotive OEM qualification lists. Strategic archetypes separate into upstream-integrated formulators, specification-embedded construction specialists, and heat-cure technology leaders serving cycle-time-sensitive assembly lines. Dominant competitive moves include backward integration into silane monomer production and geographic expansion through distributor acquisition in Mediterranean marine clusters.
Among integrated chemical producers, Dow and Wacker Chemie exemplify the upstream-control archetype through in-house polymer synthesis capabilities. Sika AG occupies a position within the construction-embedded tier, anchoring specification database presence across European markets. Momentive Performance Materials sits within the specialty technology segment, representing heat-cure formulation expertise for automotive assembly applications.
| Leading Market Players |
|---|
| Dow |
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| Wacker Chemie |
| H.B. Fuller |
| Bostik |
| Shin-Etsu Chemical |
| Momentive Performance Materials |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between integrated silane producers and German automotive OEMs lock in supply access and price visibility across the analysis window. These arrangements insulate qualified formulators from spot volatility in methylchlorosilane intermediates while compressing margin flexibility for non-integrated competitors serving construction channels.
Pricing Analysis
REACH authorization thresholds dictate the pricing tier structure across European supply chains. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered specialty grades from GB-compliant export formulations and generic maintenance products. Price differentiation hinges on certification grade and captive silane integration. Cost compression in standard grades is intensifying because Chinese MEE compliance investments are forcing domestic production scale-up. Construction contractors exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize cycle-time performance over unit cost.
Supply Chain Analysis
Inventory cycles for silane monomers stretch 8-12 weeks from German and Chinese production hubs to downstream formulators. Supply concentrates in Germany, China, and the United States, with the Rhine-Ruhr corridor and Yangtze River Delta anchoring polymer intermediate output. Formulation draws from methylchlorosilane feedstocks, fumed silica reinforcements, and specialty crosslinker packages. Single-source vulnerability in acetate-functional silane crosslinkers creates concentration risk for non-integrated compounders. Distribution runs through construction specification databases in Europe, direct OEM supply agreements in automotive, and marine surveyor-approved distributor networks in Mediterranean clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story. REACH authorization requirements and GB standard compliance create switching costs that cement incumbent positions while raising capital barriers for new entrants.
For Market Incumbents: Secure specification database embedding through mobile-enabled product platforms serving German and US glazing contractors. Deepen backward integration into silane monomer production to offset input volatility from concentrated methylchlorosilane suppliers. Neutral cure substitution pressure from alkoxy-functional alternatives threatens acid-cure volume in commercial construction channels. For New Entrants and Emerging Players: Technical service gaps in electrical encapsulation grades for EV charging infrastructure present the most penetrable white-space target. Marine refit distributors in Mediterranean clusters operate with limited embedded supplier presence and surveyor-approved product list access. A formulation partnership with retired silane synthesis chemists offers the fastest path to credible product registration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier formulators with in-house polymer synthesis capabilities and pending REACH dossier submissions. Long-term viability centers on regulatory compliance infrastructure rather than volume scale. Watch for ECHA substance hazard evaluations as the inflection signal that will concentrate supply among integrated producers with dedicated regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Monomer Production | Captive methylchlorosilane supply insulates margin from input volatility and secures REACH registration continuity. |
| Specification Database Embedding | Mobile-enabled product platforms filter contractor selection and compress brand consideration sets in German glazing channels. |
| Specialty Grade Certification Investment | Dielectric stability testing for 150°C thermal resistance opens margin pools in power electronics and EV infrastructure. |
| Marine Distributor Network Acquisition | Surveyor-approved product lists in Mediterranean and Gulf Coast clusters concentrate yacht and commercial vessel procurement. |
| UV-Cure Technology Licensing | Photoinitiated acceleration systems enable automotive paint shop integration without thermal substrate exposure. |
Research Methodology
A standing panel of commercial glazing contractors, automotive Tier-1 procurement directors, marine surveyors, and silane synthesis chemists provided ongoing calibration across primary research phases. The analysis combined structured interviews with these stakeholders against secondary validation from REACH registration dossiers, GB standard compliance filings, customs trade data, and SEC disclosures from integrated chemical producers. Bottom-up formulation volume estimates triangulated with top-down construction spending and automotive production data.
Consistency checks against external benchmarks validated model outputs across the projection horizon. The analytical framework segmented by cure chemistry, technology type, application vertical, and end-user industry, with regional regulatory clusters as a cross-cutting dimension. CAGRs were derived from installed base growth, substitution elasticity, and specification upgrade trajectories. Key inputs included building energy code enforcement timelines, automotive lightweighting program specifications, and MEE directive implementation schedules.
Forecasts assume regulatory continuity in REACH, GB standards, and FDA frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.