
 Europe Reactive Adhesives Market | 2026-2036
Europe Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Reactive Adhesives Market Foresight
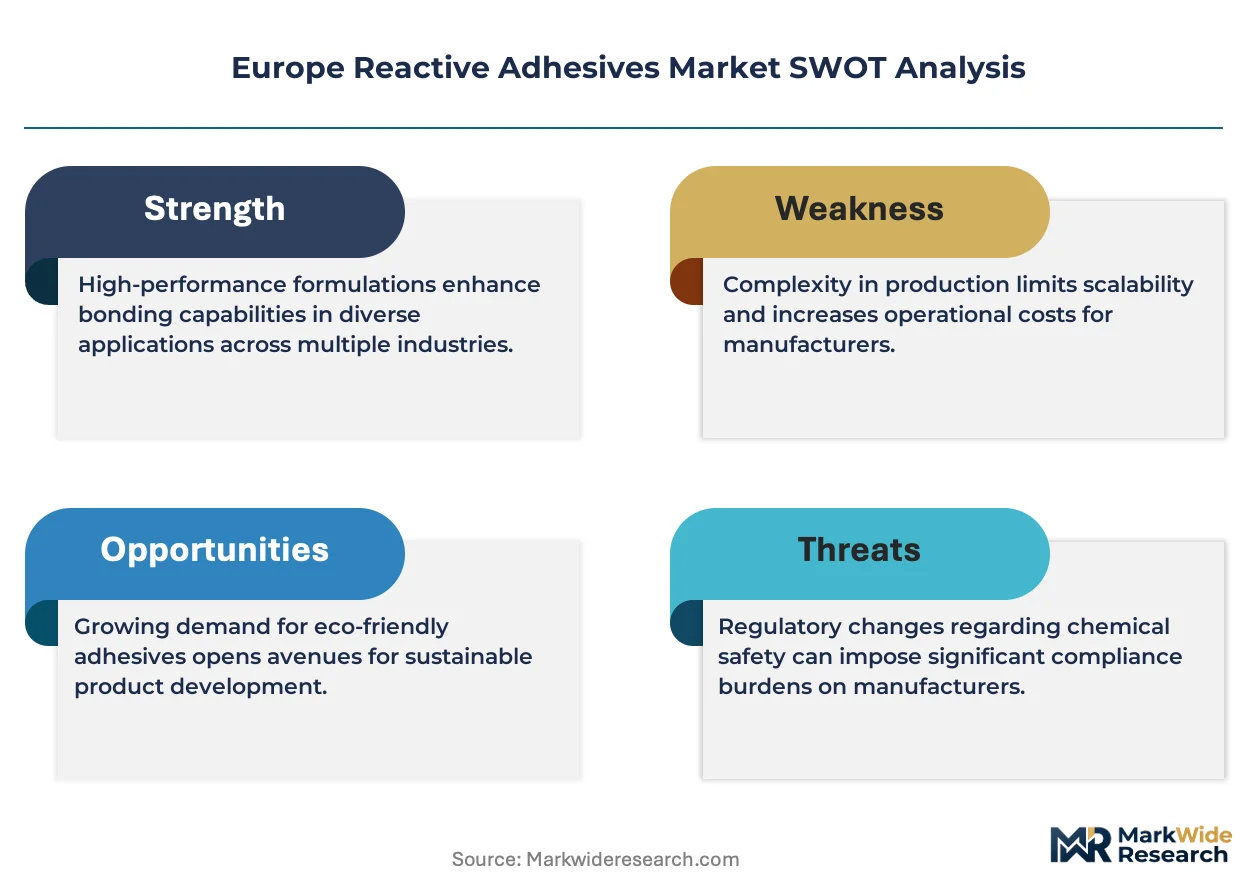
Asset-light leasing models for adhesive dispensing equipment are reshaping competitive entry barriers across Europe. Henkel AG & Co. KGaA leverages its captive R&D network in Düsseldorf to sustain formulation leadership for automotive OEM qualifications. Sika AG anchors its position through backward integration into polymer intermediates at Swiss manufacturing complexes. Dow competes by controlling regional supply of specialty epoxy resins serving electronics fabricators in the Netherlands and Germany.
Reactive adhesives cure through chemical reaction rather than solvent evaporation, forming thermoset bonds with lap shear strengths exceeding 20 MPa in structural epoxy grades. These systems serve critical load-bearing and environmental-sealing functions in transportation and industrial assembly. Polyurethane formulations lead volume consumption across European automotive seating and interior trim applications. UV-cured acrylic segments occupy the fastest-expanding technology tier, driven by electronics miniaturization and medical device assembly lines requiring instant handling strength.
REACH registrations through ECHA govern substance authorization and restrict candidate list chemicals in adhesive raw materials. The EU Green Deal's chemical sustainability targets and F-Gas Regulation phase-downs are forcing reformulation investments across solvent-bearing systems. EMA and national competent authorities in France and Germany scrutinize medical-grade adhesives for biocompatibility under MDR transition timelines. Stakeholders must monitor evolving substance restrictions and carbon border adjustment mechanisms to anticipate raw material cost trajectories and qualification requirements.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's chemical sustainability mandates are forcing simultaneous reformulation across solvent-bearing adhesive portfolios while automotive OEMs in Germany scale bonding operations for electric vehicle battery architectures.
Growth Catalysts
- Electric vehicle battery assembly expansion:German automotive OEMs are qualifying structural epoxy systems for cell-to-pack bonding, creating qualified demand pull for thermally conductive grades.
- UV-cured acrylic adoption:Electronics fabricators in the Netherlands and Germany are replacing solvent-based systems with instant-cure acrylics for miniaturized medical device and semiconductor packaging applications.
- EU Green Deal chemical sustainability targets:The framework's carbon border adjustment mechanisms and F-Gas Regulation phase-downs are accelerating capital allocation toward low-VOC and bio-based formulation R&D.
Market Restraints
- Petrochemical intermediate volatility:Epoxy resin and isocyanate feedstock costs fluctuate with naphtha and propylene pricing, compressing formulation margins for mid-tier producers lacking backward integration.
- Swiss-German polymer intermediate concentration:Captive supply of specialty resins and curing agents concentrates among integrated chemical complexes along the Rhine corridor, creating qualification bottlenecks for second-tier formulators.
- REACH authorization timelines:ECHA's candidate list expansion and substance restriction proposals extend raw material qualification cycles, freezing formulation pipelines for 18-24 months pending hazard assessment outcomes.
Strategic Opportunities
- Polish and Czech industrial corridor penetration:Automotive supplier clusters in Lower Silesia and Moravia lack qualified local adhesive formulators, creating white space for technical service partnerships with battery and seating module assemblers.
- Medical device MDR transition:The EU Medical Device Regulation's biocompatibility documentation requirements favor adhesive suppliers with ISO 10993 pre-certified portfolios, displacing uncertified competitors in catheter and diagnostic device assembly.
- Digital dispensing integration:Convergence of robotic application systems with IoT-enabled viscosity monitoring is enabling predictive maintenance contracts that lock in multi-year adhesive supply agreements.
Industry Challenges
- Polymer chemist and application engineering scarcity:Formulation expertise for high-performance thermosets concentrates among aging technical workforces in Düsseldorf and Basel industrial clusters, constraining R&D expansion.
- Automotive qualification cycle compression:OEMs demand crash-test validated bonding simulations within 12-month windows, forcing adhesive suppliers to parallel-track physical testing with finite element modeling investments.
- Legacy solvent system retrofit complexity:Industrial assemblers in France and Italy face production line reconfiguration costs when transitioning from solvent evaporation to UV or moisture-cure chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Reactive Adhesives Market |
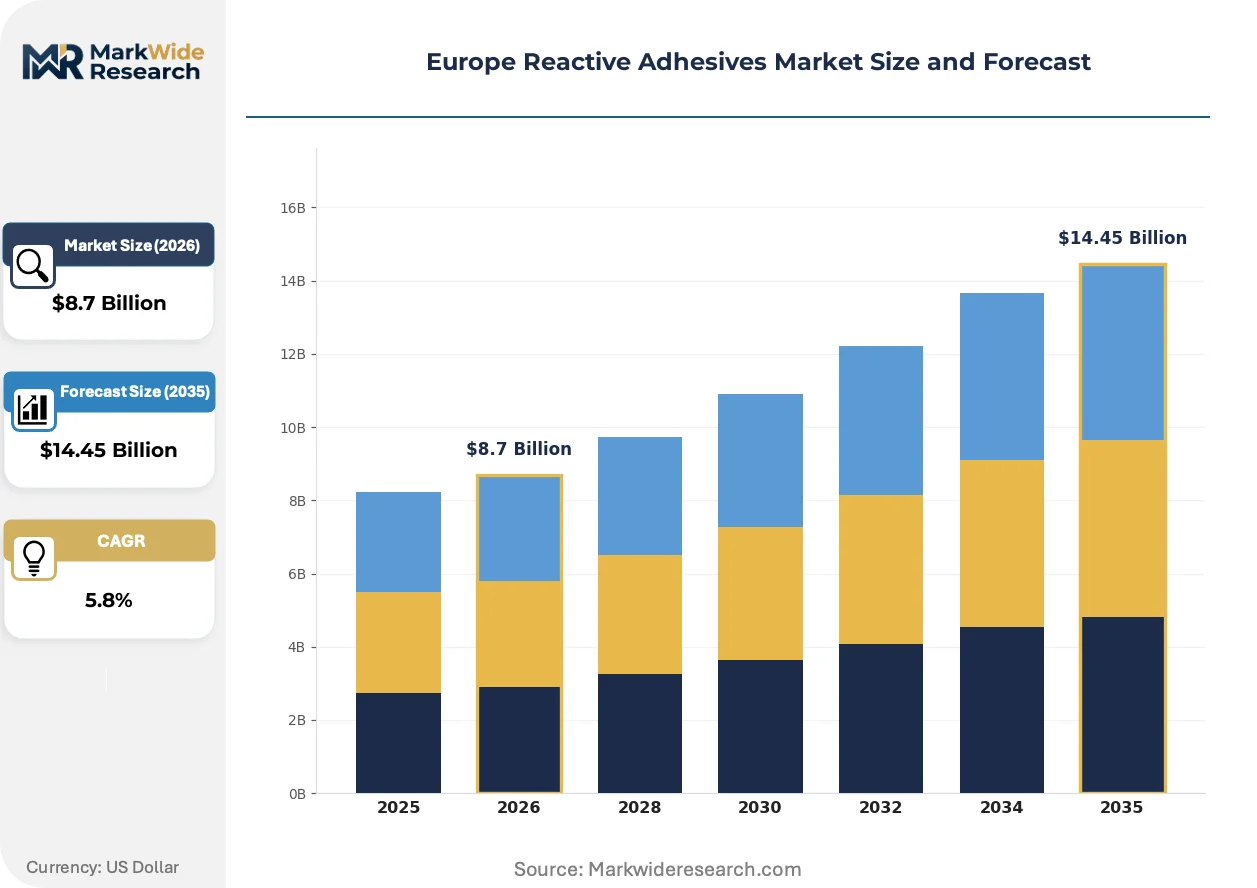
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Aerospace, Automotive, Electronics, Construction Technology: Thermal, UV, Moisture, Chemical Application: Bonding, Sealing, Coating, Assembly |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller Company, Dow, Jowat SE, Avery Dennison Corporation, Huntsman International LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Reactive Adhesives Market Shifts & Advancements
Reactive adhesive technology is bifurcating between high-throughput automated dispensing for electronics and structural thermoset systems for transportation, with regulatory chemistry constraints accelerating material substitution across both paths.
AI-assisted formulation platforms are digitizing molecular screening workflows for epoxy and polyurethane systems. Specialty chemical R&D teams in Germany and Switzerland deploy machine learning models to predict cure kinetics and thermal stability, compressing development cycles from 36 months to 18 months for automotive structural grades. This capability is digitizing competitive moats around intellectual property portfolios.
REACH substance restrictions and the F-Gas Regulation phase-down are eliminating hydrofluorocarbon blowing agents and certain aromatic amine curing agents from polyurethane formulations. Adhesive producers must reformulate with aliphatic alternatives or bio-based polyols, raising raw material costs while creating first-mover advantage for suppliers with pre-qualified sustainable portfolios. Electronics and appliance manufacturers in Germany face the steepest compliance deadlines.
Asset-light leasing of precision dispensing equipment is displacing capital purchase models among mid-tier automotive suppliers. French and Italian seating manufacturers now contract adhesive volume with bundled equipment maintenance, transferring technical risk to formulators while locking in multi-year supply commitments. This arrangement concentrates in regions with fragmented supplier bases lacking in-house application engineering.
Europe Reactive Adhesives Market Segmentation
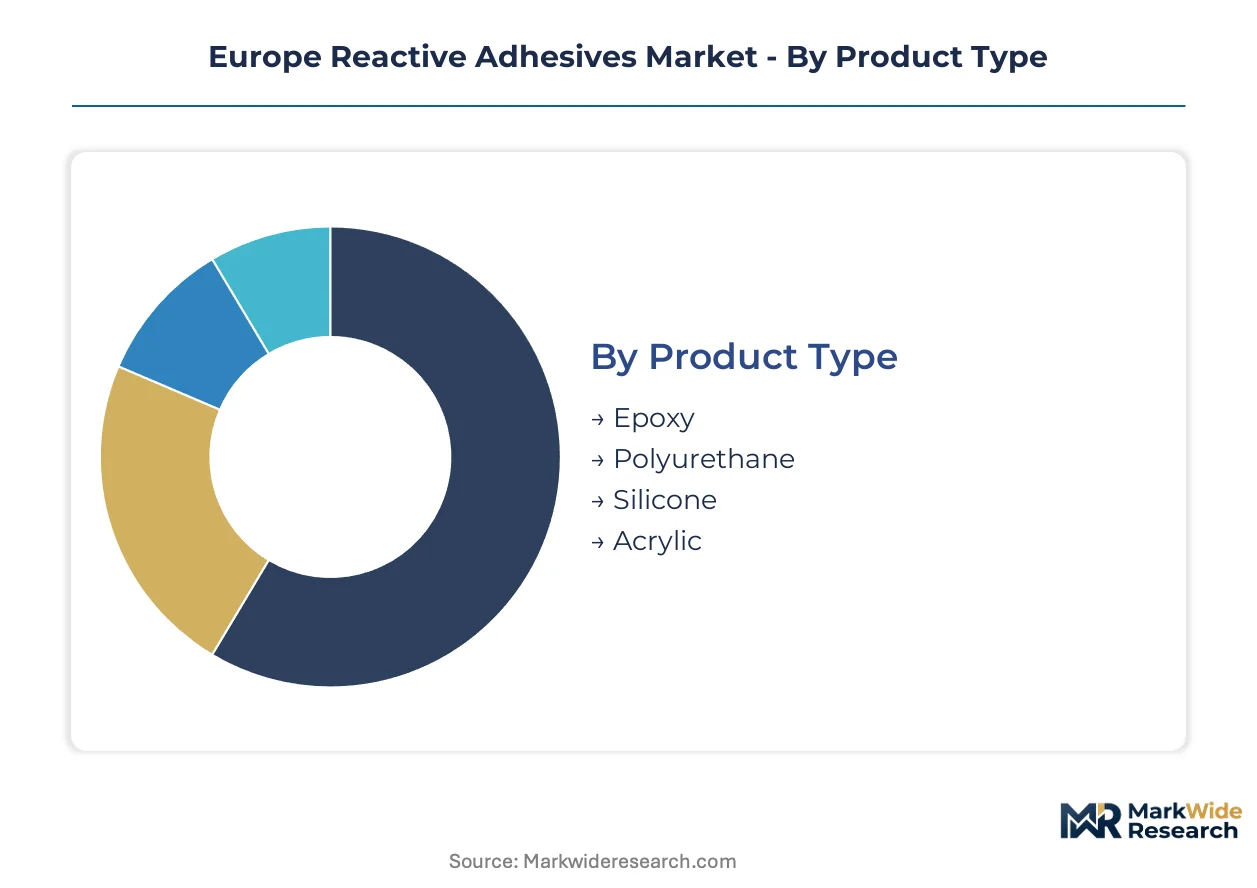
Reactive adhesive segmentation in Europe maps directly to qualification cycles and regulatory exposure. Product chemistry determines REACH authorization burdens, while end-use selection dictates whether suppliers face ECHA substance restrictions or EMA medical device compliance.
Product Type:
Epoxy systems carry the longest qualification timelines for automotive structural bonding, while acrylic UV grades turn over fastest in electronics miniaturization cycles.
- Epoxy:Two-part thermoset systems formulated with bisphenol-A or novolac resins deliver lap shear strengths exceeding 25 MPa for load-bearing transportation applications. German OEMs in Stuttgart and Wolfsburg specify these grades for electric vehicle battery pack cell-to-pack bonding, where thermal conductivity and crash durability are non-negotiable.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture or catalyst reaction, forming flexible bonds with elongation at break above 300%. Seating manufacturers across France and Italy consume these formulations for foam-to-substrate lamination in automotive interior trim, though F-Gas Regulation phase-downs are forcing aliphatic isocyanate substitution.
- Silicone:Room-temperature-vulcanizing systems with silanol condensation chemistry serve high-temperature sealing in aerospace engine compartments and industrial gasketing.
- Acrylic:UV-cured or anaerobic formulations targeting electronics fabrication in the Netherlands and Germany, where instant handling strength enables medical device and semiconductor packaging throughput.
Polyurethane dominates installed base across European automotive seating. Acrylic UV systems are where expansion concentrates for electronics miniaturization.
End User:
Cost tier stratification separates aerospace qualification premiums from construction volume plays, with automotive and electronics occupying intermediate positions.
- Aerospace:Structural film adhesives and paste syntactics must satisfy EASA flame-smoke-toxicity specifications and OEM-specific out-time limits for carbon fiber composite bonding. French and German airframe manufacturers in Toulouse and Hamburg impose 24-month qualification cycles that freeze formulation changes.
- Automotive:Battery electric vehicle architectures are consuming thermally conductive epoxy and polyurethane grades for module assembly, thermal interface materials, and crash-resistant structural bonding. German OEM qualification pipelines now prioritize simulation-validated adhesive performance over legacy mechanical fastening.
- Electronics:Miniaturized medical devices and semiconductor packaging in Dutch and German fabrication facilities demand low-outgassing, ionically pure acrylic and epoxy systems with sub-ppm metallic contamination.
- Construction:Reactive anchoring adhesives and structural bonding pastes for concrete and steel rehabilitation, where CE marking and ETA certification govern load-bearing structural applications across French and German infrastructure projects.
Automotive represents the deepest qualification investment per customer. Electronics is gaining share fastest through UV-cured acrylic displacement of solvent systems.
Technology:
Application method determines capital intensity and throughput economics, with thermal curing demanding batch ovens while UV enables continuous line integration.
- Thermal:Oven-cured epoxy and polyurethane systems requiring 80-180°C exposure for 10-60 minutes, standard for automotive structural bonding and aerospace composite assembly where complete cure conversion is mandatory.
- UV:Photoinitiator-triggered acrylic polymerization delivering handling strength in 2-10 seconds, enabling electronics and medical device throughput in Dutch cleanroom fabrication.
- Moisture:Alkoxy-silane and isocyanate systems curing from ambient humidity, deployed in construction anchoring and field-applied automotive glazing where oven access is impractical.
- Chemical:Two-part mixing activation for epoxies and polyurethanes, offering pot life control and deep-section cure for thick bondlines in industrial assembly.
Thermal curing commands the largest installed equipment base. UV technology is climbing the fastest as electronics fabricators eliminate solvent processing.
Application:
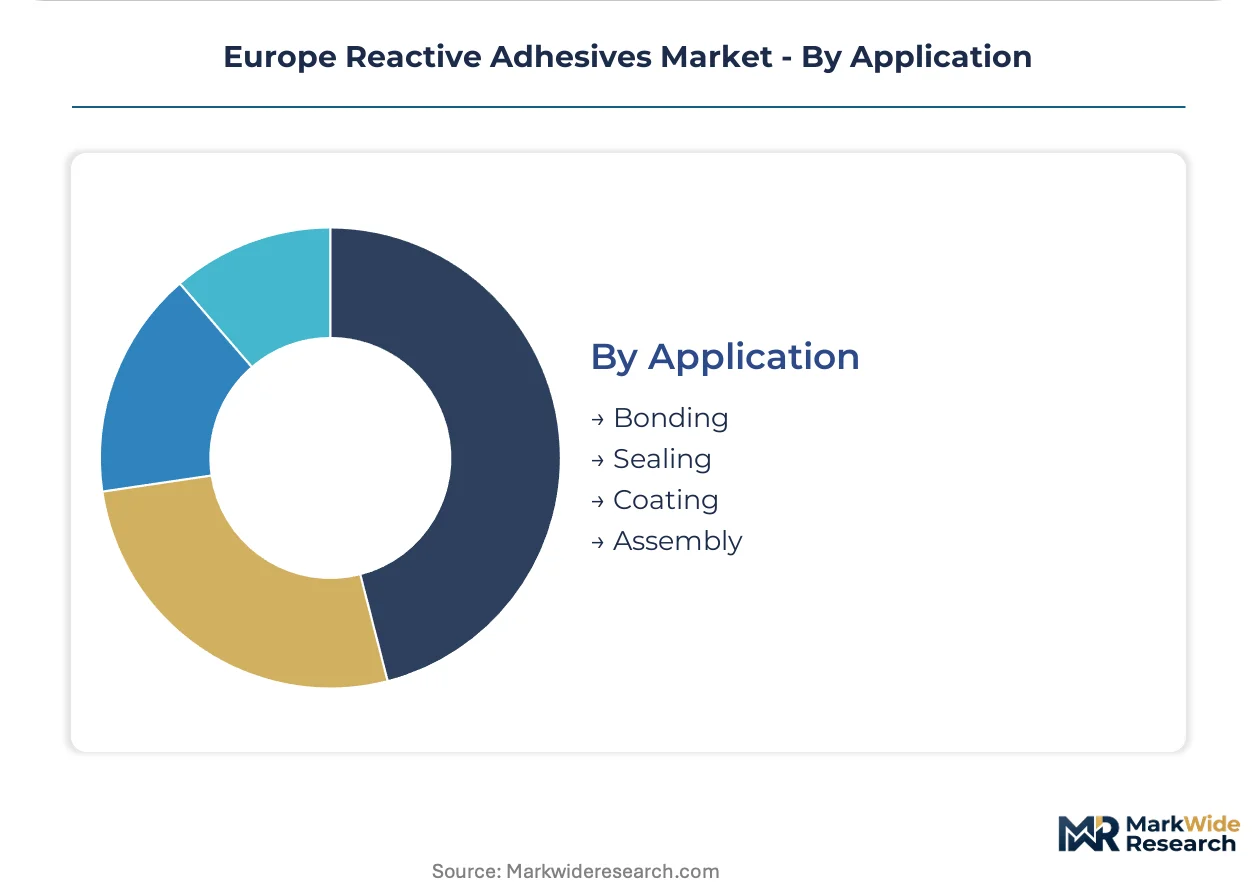
Volume concentration sits with bonding operations, while margin capture favors sealing applications with specification stickiness and aftermarket replacement cycles.
- Bonding:Structural load transfer between dissimilar substrates—metal-to-composite in automotive, glass-to-frame in construction—where failure modes propagate through adhesive bulk or interfacial adhesion.
- Sealing:Environmental barrier functions against moisture, chemicals, and pressure differentials in automotive powertrain, aerospace fuel systems, and medical device enclosures.
- Coating:Protective and functional layers for electronics conformal protection, where parylene and acrylic systems insulate against moisture and ionic migration.
- Assembly:Multi-component integration combining bonding, sealing, and gap-filling in modular construction and appliance manufacturing.
Bonding captures the highest adhesive volume per assembly unit. Sealing applications are where supplier margins concentrate through specification longevity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Dutch electronics fabricators anchor the region's buyer base, with qualification requirements and REACH compliance timelines concentrating purchasing power among technically sophisticated procurement teams.
Germany
Stuttgart and Wolfsburg automotive clusters are qualifying structural epoxy systems for electric vehicle battery pack assembly, where thermal conductivity specifications exceed legacy mechanical fastening requirements. KBA vehicle type approval processes now incorporate adhesive performance validation within crash-test simulation protocols. The industrial corridor stretching from Düsseldorf to Hamburg concentrates captive polymer intermediate production and formulation R&D.
Netherlands
Eindhoven and Amsterdam electronics fabrication facilities are displacing solvent-based systems with UV-cured acrylic adhesives for semiconductor packaging and medical device miniaturization. ECHA substance authorization timelines govern raw material selection for ionically pure formulations. Cleanroom assembly lines in the Randstad region demand sub-ppm metallic contamination standards for conformal coating applications.
France
Toulouse aerospace manufacturers impose 24-month qualification cycles for structural film adhesives used in carbon fiber composite bonding, freezing formulation changes during EASA certification. ANSM scrutiny of medical device biocompatibility under MDR transition timelines favors suppliers with ISO 10993 pre-certified portfolios. Seating manufacturers in the Auvergne-Rhône-Alpes region face F-Gas Regulation phase-down deadlines for polyurethane foam lamination systems.
Switzerland
Basel chemical complexes anchor backward integration into specialty epoxy resins and aliphatic isocyanate curing agents, creating supply bottlenecks for non-integrated formulators. Swissmedic medical device regulations require documentation of adhesive extractables and leachables for diagnostic equipment assembly. The Rhine corridor concentration of polymer intermediate production limits second-tier supplier qualification access.
Poland
Lower Silesia automotive supplier clusters lack qualified local adhesive formulators, creating white space for technical service partnerships with battery module and seating assemblers. EU Green Deal carbon border adjustment mechanisms are accelerating capital allocation toward low-VOC formulation R&D among entrants. Wrocław and Katowice industrial zones are attracting dispensing equipment leasing providers to serve fragmented supplier bases.
Europe Reactive Adhesives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where captive R&D networks and backward integration into polymer intermediates determine qualification access. German and Swiss integrated chemical groups anchor premium-tier positions through in-house resin production, while mid-tier formulators rely on merchant feedstock supply. Strategic moves concentrate on asset-light equipment leasing models and AI-assisted formulation platform deployment to compress development cycles.
Among Düsseldorf-based integrated groups, Henkel AG & Co. KGaA exemplifies the captive R&D archetype sustaining automotive OEM qualification pipelines. Sika AG anchors Swiss manufacturing concentration through upstream control over polymer intermediates. Dow represents the specialty resin supplier archetype serving electronics fabricators in the Netherlands and Germany. These three occupy positions defined by geographic proximity to industrial clusters and regulatory compliance capabilities rather than scale alone.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Jowat SE |
| Avery Dennison Corporation |
| Huntsman International LLC |
| Others |
Supply & Pricing Matrix
Undercapacity in aliphatic isocyanate production across the Rhine corridor is forcing German and Swiss suppliers to prioritize captive customers, tightening spot availability and amplifying price premiums for non-integrated formulators serving automotive and electronics segments.
Pricing Analysis
Certification level creates the primary spread between ECHA REACH-registered formulations and uncertified alternatives. Contract-based long-term offtake dominates, with ISO 10993 pre-certified medical grades commanding sustained premiums over standard industrial tiers. Cost compression in mid-tier polyurethane segments is intensifying because F-Gas Regulation phase-downs are accelerating aliphatic substitution investments. Tier 1 automotive OEMs exhibit lowest price sensitivity due to qualification lock-in, while construction distributors in Southern Europe remain most responsive to spot-market fluctuations.
Supply Chain Analysis
Tariff exposure between Switzerland and EU member states dominates supply chain risk assessments for specialty epoxy resin and curing agent flows. Production concentrates in Germany, Switzerland, and the Netherlands, with the Basel-Rotterdam axis anchoring captive polymer intermediate supply. Feedstock draws from naphtha crackers in Antwerp and Ludwigshafen, with bisphenol-A and isocyanate prepolymers as critical inputs. Single-source vulnerability concentrates around aliphatic amine curing agents from Swiss manufacturing complexes. Distribution runs through regional blending facilities co-located with automotive OEM clusters in Stuttgart and Wolfsburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German automotive OEM consolidation around electric vehicle platforms has concentrated procurement power among fewer platform engineering teams, shifting negotiation leverage toward buyers with multi-year qualification pipelines.
For Market Incumbents: Pre-empt qualification bottlenecks by accelerating backward integration into bio-based polyol supply and securing ECHA early-registration status for next-generation aliphatic curing agents. Threat from AI-assisted formulation platforms operated by mid-tier competitors demands defensive patent filings around cure-kinetics prediction models. Capacity addition in Polish industrial zones represents the priority lever to capture emerging battery supplier demand. For New Entrants and Emerging Players: Lower Silesia automotive supplier clusters in Poland represent the most penetrable entry point for technical service partnerships with battery module assemblers lacking qualified local formulators. Czech Moravia seating manufacturers facing F-Gas compliance deadlines offer secondary white-space for polyurethane reformulation services. Go-to-market through asset-light dispensing equipment leasing bundled with formulation supply transfers technical risk while locking volume commitments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among adhesive suppliers with multi-year automotive qualification pipelines and IoT-enabled dispensing maintenance contracts. Long-term viability centers on formulators with pre-certified sustainable portfolios and captive resin production. Signal to watch is ECHA candidate list expansion pace as inflection indicator for raw material cost trajectories and qualification cycle extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | Secures feedstock independence from petrochemical volatility and EU Green Deal compliance. |
| AI-Assisted Formulation Platform Deployment | Compresses automotive qualification cycles from 36 months to 18 months for epoxy systems. |
| Asset-Light Dispensing Equipment Leasing | Locks multi-year supply agreements with mid-tier French and Italian seating manufacturers. |
| ISO 10993 Pre-Certification Investment | Captures medical device share from uncertified competitors during MDR transition timelines. |
| Polish Industrial Corridor Capacity Expansion | Positions technical service presence near battery module assemblers in Lower Silesia. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulator R&D directors, automotive OEM platform engineers, Tier 1 supplier procurement leads, and ECHA regulatory affairs specialists, and refined through secondary validation against customs trade data, Cefic sector reports, SEC 10-K chemical disclosures, and REACH registration databases. Bottom-up volume modeling triangulated with top-down value estimates derived from production capacity and pricing intelligence.
Demand-supply balance dynamics anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, curing technology type, and regional production cluster proximity to automotive and electronics corridors. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trajectories. Forecast inputs incorporated electric vehicle battery pack content-per-vehicle assumptions and F-Gas Regulation phase-down compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in naphtha and propylene pricing, carbon border adjustment mechanism implementation pace, or REACH authorization timeline extensions would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Italy Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
UV Glue Market