
 Global Inorganic Corrosion Inhibitors Market | 2026-2036
Global Inorganic Corrosion Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inorganic Corrosion Inhibitors Market Foresight
The EU F-Gas Regulation and associated industrial decarbonization mandates is pivoting European petrochemical operators toward lower-toxicity inhibitor chemistries. BASF SE leverages its integrated phosphate supply chain to sustain volume leadership across German and Benelux power generation accounts. Cortec Corporation anchors its position through specialized vapor-phase corrosion inhibitor technology for marine engineering applications. Akzo Nobel N.V. competes on geographic breadth with established supply infrastructure across Nordic metal fabrication clusters.
Inorganic corrosion inhibitors comprise mineral-based chemical compounds—typically phosphates, molybdates, silicates, or borates—formulated to form passive oxide layers on metal surfaces at concentrations between 50 and 500 ppm depending on water chemistry. These compounds function primarily to extend asset life in aqueous industrial environments by interrupting electrochemical oxidation reactions at the anode or cathode. Phosphates occupy the largest product category due to mature supply economics and broad compatibility with steel infrastructure in cooling water systems. Molybdates represent the fastest-expanding product type as operators substitute away from restricted chromate formulations in boiler systems and chemical processing circuits. Liquid formulations dominate volume consumption though granular products command margin premiums in remote oilfield treatment locations where freight costs favor reduced water content.
EPA effluent limitation guidelines and OSHA worker exposure standards constrain permissible chromate and nitrite concentrations in US industrial water circuits. ECHA REACH authorization requirements continue to narrow the viable chemistry set for European cooling water and metal surface protection applications. China's MEE discharge standards for total phosphorus in wastewater tighten formulation tolerances for phosphate-based programs in Yangtze Basin manufacturing zones. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory positions as chemical authorization timelines desynchronize across major demand centers.
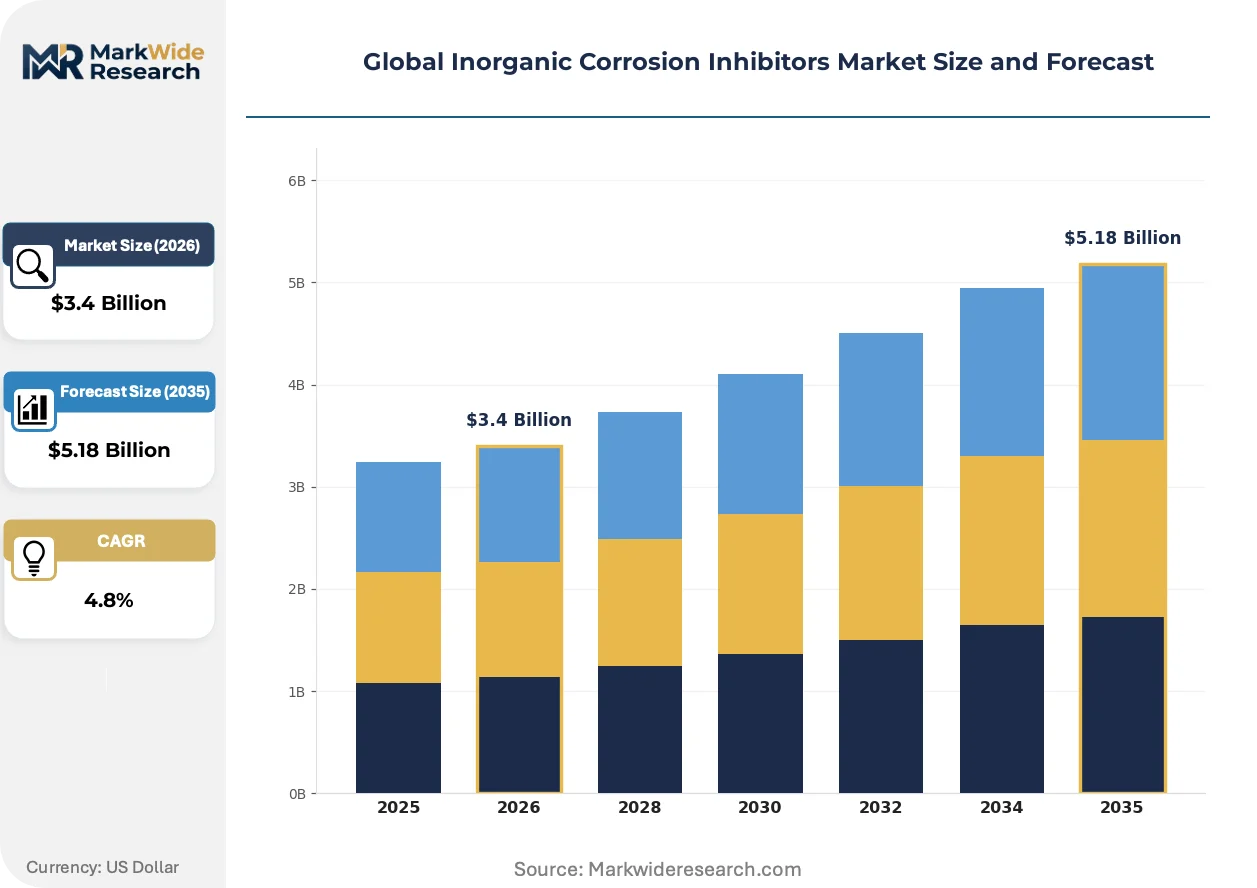
Market Dynamics
Regulatory displacement of chromate formulations is compressing product lifecycles while simultaneously expanding addressable demand for molybdate and silicate alternatives across industrial water treatment infrastructure.
Growth Catalysts
- EU REACH authorization timelines:ECHA restrictions on hexavalent chromium compounds in cooling systems are mandating substitution programs across German and Benelux petrochemical facilities.
- China's Yangtze Basin industrial corridor:Petrochemical and combined-cycle power capacity additions in Jiangsu and Zhejiang provinces are generating multi-year inhibitor supply contracts.
- Phosphate-based boiler water chemistry:Mature formulation economics and broad steel compatibility sustain deployment across North American district heating networks.
Market Restraints
- Molybdenum concentrate supply concentration:Chinese and Chilean mining operations control over 80% of global molybdenum trioxide feedstock, exposing formulation costs to concentrate price volatility.
- EPA effluent limitation guidelines:Tightening discharge limits on total phosphorus in US Great Lakes manufacturing zones are constraining orthophosphate dosing rates in legacy cooling systems.
- Organic polymer substitution:Polyacrylate and phosphonate blends are capturing share in low-temperature once-through cooling applications where film-forming requirements are less stringent.
Strategic Opportunities
- India's National Clean Air Programme:Thermal power plant FGD retrofits and associated water chemistry upgrades are opening phosphate and silicate inhibitor procurement channels.
- Vapor-phase corrosion inhibitor integration:Packaging and marine engineering applications are adopting volatile amine and siloxane chemistries for void space protection.
- Closed-loop geothermal systems:Silicate-based formulations for corrosion control in high-salinity brine circuits represent an emerging specification channel.
Industry Challenges
- Formulation chemist specialization gap:Expertise in electrochemical passivation kinetics and water chemistry modeling is concentrating among retiring specialists at major water treatment service firms.
- REACH authorization dossier costs:SME formulators face six-figure euro expenditures for substance registration and downstream user notification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inorganic Corrosion Inhibitors Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphates, Chromates, Nitrites, Molybdates, Silicates, Borates Application: Oilfield Treatment, Cooling Water Systems, Metal Surface Protection, Boiler Systems, Chemical Processing, Pulp & Paper End User Industry: Petrochemical Plants, Power Generation, Metal Fabrication, Marine Engineering Form: Liquid, Powder, Granular, Suspension |
| Companies Covered | BASF SE, Cortec Corporation, Akzo Nobel N.V., Dai-ichi Karkaria Ltd, Ecolab, Dow Chemical Company, W.R. Grace & Co., Henkel, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inorganic Corrosion Inhibitors Market Shifts & Advancements
Electrochemical monitoring integration and predictive dosing algorithms are transforming how industrial operators manage inhibitor consumption. These capabilities compress chemical overfeed while extending asset protection windows.
Hybrid phosphate-zinc formulations with enhanced anodic inhibition efficiency are electrifying specification standards in high-chloride cooling water environments. US Gulf Coast refineries and Saudi petrochemical complexes are adopting these chemistries at accelerated replacement cycles. The technology is electrifying competitive positioning among formulation houses with captive zinc oxide supply.
ECHA REACH sunset date extensions for chromate authorizations are compressing substitution timelines across European aerospace and metal finishing supply chains. Downstream users must complete technical qualification of molybdate and rare earth inhibitor alternatives before 2026 authorization deadlines. Boiler and closed-loop applications in German automotive supplier parks are most exposed to formulation changeover costs.
Asset operator purchasing departments are consolidating chemical procurement under integrated water management contracts. Third-party water service firms are displacing direct inhibitor sales through performance-based agreements covering chemical supply, monitoring equipment, and regulatory reporting. This consolidation is most visible in US power generation and Nordic pulp and paper installations where staffing reductions have eliminated in-house water chemistry expertise.
Global Inorganic Corrosion Inhibitors Market Segmentation
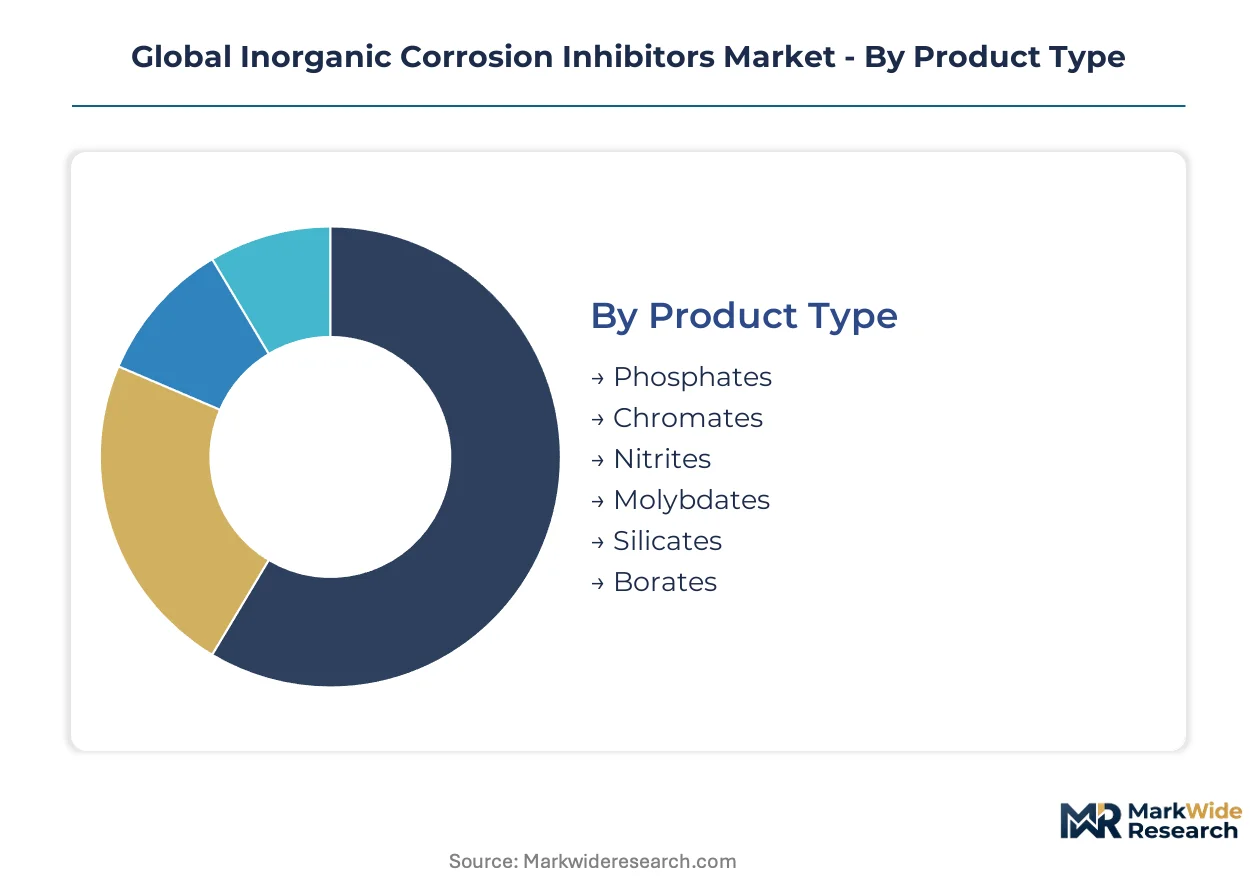
Segmentation in the inorganic corrosion inhibitors market reflects divergent upgrade pressures across industrial water chemistry infrastructure. Replacement cycles vary dramatically by product chemistry and end-use severity, with regulatory deadlines forcing synchronized substitution waves in certain categories while legacy systems extend service life in others.
Product Type:
Upgrade cycles across product categories track directly against regulatory authorization timelines and feedstock cost volatility, with some chemistries facing forced substitution while others benefit from extended qualification periods.
- Phosphates:Orthophosphate and polyphosphate blends remain the baseline specification for steel protection in municipal and industrial cooling circuits. Demand concentrates across North American district heating networks and China's Yangtze Basin manufacturing zones where mature supply economics outweigh phosphorus discharge compliance costs.
- Molybdates:Sodium and ammonium molybdate formulations deliver anodic passivation without the toxicity profile of restricted chromates. German and Benelux petrochemical operators are accelerating technical qualification of these chemistries ahead of ECHA REACH sunset deadlines for hexavalent chromium alternatives.
- Chromates:Strontium and zinc chromate persist in aerospace pretreatment and military specification coatings where authorization extensions delay substitution.
- Nitrites:Sodium nitrite functions primarily in closed-loop antifreeze and engine coolant formulations facing OSHA exposure limit constraints.
- Silicates:Sodium silicate and colloidal silica protect aluminum and galvanized steel in potable water and high-pH environments.
- Borates:Borax and boric acid derivatives serve niche applications in wood treatment and nuclear primary coolant chemistry.
Phosphates sit at the top of the volume ranking, with molybdates climbing the fastest.
Application:
Application segmentation maps to water chemistry severity and asset replacement intensity, with high-temperature high-pressure systems demanding more frequent reformulation than ambient once-through circuits.
- Cooling Water Systems:Open recirculating and once-through cooling towers represent the largest chemical consumption point across power generation and petrochemical infrastructure. Jiangsu and Zhejiang province capacity additions in China are generating multi-year supply contracts for phosphate and molybdate programs.
- Oilfield Treatment:Downhole corrosion control and pipeline protection in high-CO2 high-H2S environments requires specialized inhibitor packages. Granular and suspension formulations dominate remote Permian Basin and North Sea installations where freight economics favor reduced water content.
- Boiler Systems:High-pressure steam generators in pulp and paper and food processing require coordinated phosphate-pH-oxygen scavenger chemistry. India's National Clean Air Programme is driving FGD retrofits and associated water chemistry upgrades at thermal power stations.
- Metal Surface Protection:Pretreatment coatings and temporary corrosion preventives serve automotive and appliance manufacturing.
- Chemical Processing:Acid gas removal and process stream corrosion control in fertilizer and chlor-alkali plants.
- Pulp & Paper:Digester and bleach plant equipment protection in Nordic and Canadian integrated mills.
Cooling water systems command the largest share of formulation volume, while oilfield treatment shows the steepest expansion trajectory.
End User Industry:
End user segmentation reveals concentration in asset-intensive process industries where unplanned corrosion failures carry catastrophic economic consequences.
- Power Generation:Combined-cycle gas turbines, coal-fired boilers, and nuclear steam generators require continuous inhibitor dosing to protect condensers and feedwater heaters. US Gulf Coast refineries and Saudi petrochemical complexes are adopting hybrid phosphate-zinc chemistries at accelerated replacement cycles.
- Petrochemical Plants:Ethylene crackers, aromatics complexes, and polyolefin units operate aggressive water chemistry with high chloride and high temperature extremes. EU F-Gas Regulation and industrial decarbonization mandates are pivoting operators toward lower-toxicity inhibitor specifications.
- Metal Fabrication:Steel mills, galvanizing lines, and metal finishing shops require pretreatment and process bath corrosion control.
- Marine Engineering:Ballast water tanks, void spaces, and offshore platform splash zones adopt vapor-phase and coating-compatible protection systems.
Power generation anchors the largest absolute demand, with petrochemical plants gaining share fastest.
Form:
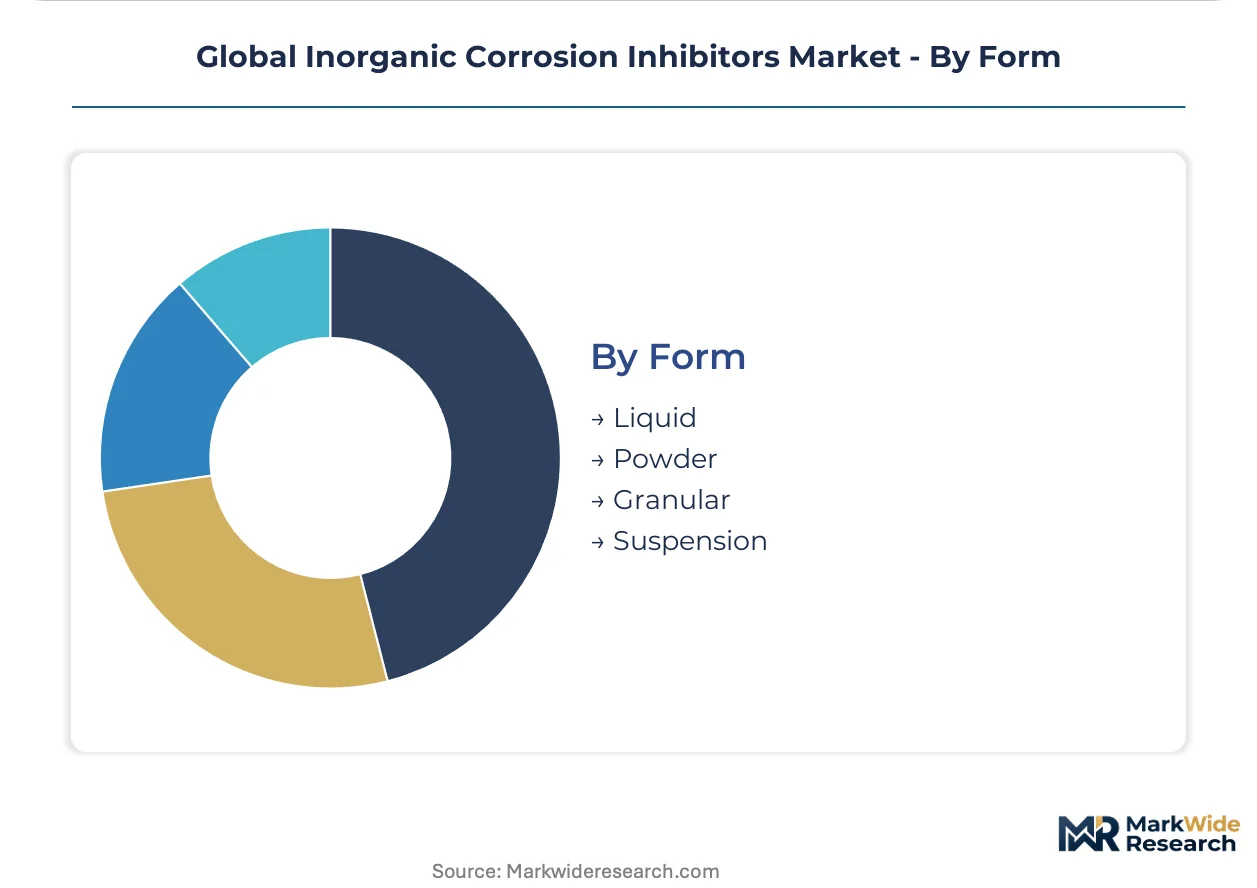
Form factor selection balances freight economics against dissolution kinetics, with concentrated solid products commanding margin premiums in remote locations.
- Liquid:Ready-to-feed solutions dominate volume consumption across centralized water treatment facilities with automated dosing infrastructure. Mature supply chains in the US Great Lakes and German industrial corridors favor liquid delivery economics.
- Granular:Low-moisture crystalline products reduce shipping weight for remote oilfield and mining applications where logistics costs dominate total delivered cost.
- Powder:Fine-ground solids serve formulation houses and on-site compound blending operations.
- Suspension:Concentrated slurries bridge dissolution speed and shipping density for specialized high-dose applications.
Liquid formulations hold the volume lead, with granular products expanding most quickly in remote resource extraction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial water treatment chemistry originated in the German Ruhr Valley and US Great Lakes manufacturing belts during the early twentieth century, establishing phosphate-based formulations as the foundational standard for steel protection in aqueous environments.
Germany
German petrochemical operators along the Rhine corridor are accelerating molybdate qualification programs ahead of ECHA REACH sunset deadlines for hexavalent chromium. The EU F-Gas Regulation compounds decarbonization pressure on BASF SE and downstream users to pivot toward lower-toxicity inhibitor specifications. Industrial clusters in Ludwigshafen and Leverkusen anchor multi-year supply contracts for phosphate and silicate programs serving power generation and chemical processing infrastructure.
United States
US Gulf Coast refineries and Permian Basin oilfield operators drive granular formulation demand where freight economics favor reduced water content. EPA effluent limitation guidelines constrain orthophosphate dosing rates in Great Lakes manufacturing zones, forcing reformulation of legacy cooling systems. Texas and Louisiana petrochemical complexes are adopting hybrid phosphate-zinc chemistries at compressed replacement cycles to manage high-chloride water chemistry.
China
Petrochemical and combined-cycle power capacity additions in Jiangsu and Zhejiang provinces generate multi-year inhibitor supply contracts along the Yangtze River Delta. MEE discharge standards for total phosphorus tighten formulation tolerances in basin manufacturing zones, pushing operators toward optimized dosing protocols. Shanghai and Ningbo industrial ports concentrate procurement of liquid formulations for centralized water treatment facilities with automated dosing infrastructure.
India
Thermal power plant FGD retrofits under the National Clean Air Programme are opening phosphate and silicate inhibitor procurement channels across Maharashtra and Gujarat. CEA mandates on water chemistry upgrades at coal-fired stations drive specification shifts toward compliant formulation packages. Mumbai and Vadodara industrial corridors concentrate demand from chemical processing and metal fabrication clusters upgrading closed-loop cooling infrastructure.
Saudi Arabia
Saudi petrochemical complexes on the Arabian Gulf are adopting hybrid phosphate-zinc chemistries at accelerated replacement cycles comparable to US Gulf Coast installations. SFDA and environmental authority oversight of industrial discharge quality shapes formulation selection for desalination-integrated cooling systems. Jubail and Yanbu industrial cities anchor large-volume supply contracts serving integrated refineries and aromatics complexes.
Global Inorganic Corrosion Inhibitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation specialization and captive raw material access. The vendor base stratifies between integrated chemical majors with phosphate supply chain control and specialized service firms competing on electrochemical monitoring integration. Three archetypes dominate: phosphate-integrated majors, vapor-phase technology specialists, and third-party water management contractors displacing direct chemical sales. Consolidation pressure is intensifying through performance-based contract expansion and geographic tuck-in acquisitions.
Among European-integrated majors, BASF SE and Akzo Nobel N.V. exemplify the phosphate supply chain archetype with established infrastructure across German and Nordic industrial clusters. Cortec Corporation represents the specialized technology tier through its vapor-phase corrosion inhibitor positioning for marine engineering applications. These three anchors illustrate how competitive positioning fragments between raw material integration and application-specific formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Cortec Corporation |
| Akzo Nobel N.V. |
| Dai-ichi Karkaria Ltd |
| Ecolab |
| Dow Chemical Company |
| W.R. Grace & Co. |
| Henkel |
| Ashland |
| Others |
Supply & Pricing Matrix
Molybdenum trioxide concentrate costs cascade through formulation economics from Chinese and Chilean mining operations to finished molybdate pricing tiers serving German petrochemical operators. Freight differentials between liquid and granular forms reshape procurement decisions across remote Permian Basin oilfield installations where logistics dominate total delivered cost.
Pricing Analysis
Contract-based long-term offtake agreements anchor volume procurement across Yangtze River Delta power generation and petrochemical complexes. Price differentiation rests on phosphate grade certification and captive zinc oxide integration, with hybrid phosphate-zinc formulations commanding premiums in high-chloride environments. Cost compression in standard-grade phosphates intensifies as EPA effluent guidelines constrain dosing rates in US Great Lakes zones. Municipal water treatment departments exhibit highest price sensitivity; aerospace and military specification buyers show lowest elasticity due to authorization-driven substitution timelines.
Supply Chain Analysis
Domestic-content mandates in India's National Clean Air Programme are reshaping sourcing patterns for FGD retrofit chemistry packages across Maharashtra and Gujarat thermal power corridors. Molybdenum concentrate supply concentrates in Chinese and Chilean mining operations, with phosphate rock extraction anchored in Moroccan and US Florida deposits. Single-source vulnerability runs through molybdenum trioxide feedstock where Chinese and Chilean operations control over eighty percent of global supply. Distribution runs through integrated water management contractors displacing direct chemical sales across US power generation and Nordic pulp and paper installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Inorganic Corrosion Inhibitors Market functions as a geographic-arbitrage play where REACH authorization costs in Europe diverge from MEE discharge compliance economics in China's Yangtze Basin, creating formulation sourcing advantages for operators with multi-continental production footprints.
For Market Incumbents: Anticipate accelerated substitution cycles as ECHA REACH sunset deadlines compress qualification timelines for chromate alternatives across German automotive supplier parks. Prioritize backward integration into phosphate supply chains to defend margin position against feedstock volatility. Invest in electrochemical monitoring integration capabilities to capture performance-based contract expansion across US power generation accounts where staffing reductions have eliminated in-house water chemistry expertise. For New Entrants and Emerging Players: Electrochemical passivation modeling software represents a technology-first wedge into the formulation chemist specialization gap concentrating among retiring specialists at major water treatment service firms. Target closed-loop geothermal systems as the most penetrable specification channel where silicate-based high-salinity brine chemistry remains underdeveloped. Pursue direct engagement with asset operator purchasing departments consolidating procurement under integrated water management contracts rather than competing on commodity formulation supply. For Investors and Strategic Acquirers: Consolidation pressure builds where SME formulators face six-figure euro REACH authorization dossier expenditures without captive raw material access to absorb compliance costs. Long-term viability favors integrated chemical majors with phosphate supply chain control and specialized service firms with electrochemical monitoring capabilities over commodity formulation houses. Watch ECHA authorization timeline extensions for chromate alternatives as the critical inflection signal determining substitution investment windows across European aerospace and metal finishing supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Supply | Captive phosphate rock access insulates BASF and Akzo Nobel from Moroccan export volatility and secures German power generation accounts. |
| Electrochemical Monitoring Platform Development | Integrated sensor-dosing systems capture performance-based contracts across US Great Lakes manufacturing zones with depleted in-house chemistry teams. |
| Hybrid Phosphate-Zinc Formulation Scale-Up | Enhanced anodic inhibition efficiency meets specification demand from US Gulf Coast refineries managing high-chloride cooling water chemistry. |
| Vapor-Phase Corrosion Inhibitor Specialization | Volatile amine and siloxane chemistries open marine engineering void space protection markets where Cortec anchors technology leadership. |
| Long-Term Supply Agreement Structuring | Multi-year inhibitor contracts with Jiangsu and Zhejiang province petrochemical operators lock in volume across China's Yangtze Basin capacity expansion cycle. |
Research Methodology
Multiple input streams — primary interviews with water treatment service firm technical directors, plant managers at German petrochemical complexes, and procurement leads at US power generation utilities; secondary validation against ECHA REACH authorization databases, EPA effluent limitation guidelines, and Chinese MEE discharge standards; plus customs and trade flow data from major phosphate and molybdenum concentrate corridors — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Segment-level volume and value outputs reflect reconciliation across product chemistry, application severity, end-use industry concentration, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from substitution curve modeling for chromate alternatives, capacity addition pipelines across China's Yangtze Basin, and FGD retrofit timelines under India's National Clean Air Programme. Forecast inputs incorporated ECHA authorization sunset dates, MEE phosphorus discharge limit trajectories, and molybdenum concentrate price volatility indices.
The model holds under stable regulatory authorization timelines and continued concentrate supply concentration; deviation in ECHA sunset date extensions or Chinese mining export restrictions would shift substitution investment cycles and formulation cost structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antiknock Agents Market
Additives
Alginic Acid Market
Additives
Antimicrobial Ingredients Market
Additives
Binding Agents Market
Additives
Global Acidulants Market
Additives
Apocarotenal Market
Additives
Propyl Gallate Market
Additives
Thermal Conductive Additives Market
Additives
Metallic Stearate Market
Additives
Inorganic Filler Market
Additives
South Africa Acidulants Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Sorbitan Esters Market
Additives
Clouding Agents Market
Additives
Americas Coating Additives Market
Additives
Low Melt Inclusions Market