
 Small Molecules Innovator Contract Development and Manufacturing Organization Market | 2026-2036
Small Molecules Innovator Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecules Innovator Contract Development and Manufacturing Organization Market Insights
ISO 9001 and ICH Q7 certification cycles are reorganizing competitive access in contract small-molecule manufacturing, as sponsors restrict vendor pools to audited facilities with current regulatory standing. WuXi AppTec leverages integrated discovery-to-commercial platforms across multiple continents. Lonza Group anchors its position through high-containment capabilities for oncology APIs. Siegfried Holding differentiates via dedicated R&D centers that bridge early-phase chemistry with scalable GMP routes.
Small molecules innovator CDMOs are contract service providers that develop and manufacture proprietary chemical drug substances under GMP conditions, typically handling synthetic route design, process optimization, and commercial batch production for pharmaceutical sponsors. The primary purpose is to convert medicinal chemistry candidates into validated, scalable active pharmaceutical ingredients while meeting stringent purity and stability specifications. Manufacturing services capture the largest value pool given capital intensity and long-term supply agreements, though process development commands premium pricing for complex chiral syntheses and continuous flow transitions. Pharmaceutical companies represent the dominant customer segment, with biotechnology firms representing the fastest-growing demand source as virtual development models proliferate.
FDA enforces ICH M7 guidelines for mutagenic impurity assessment, while EMA applies REACH and F-Gas regulations to solvent emissions from European manufacturing sites, collectively elevating compliance costs and favoring CDMOs with dedicated regulatory affairs infrastructure. The EU AI Act introduces documentation requirements for algorithmic process control systems that optimize reaction parameters. Sponsors must monitor how quality agreements evolve under these overlapping frameworks to avoid supply disruptions during regulatory inspections.
Market Dynamics
Oncology pipeline expansion is concentrating sponsor demand on CDMOs with validated high-potency containment infrastructure, compressing vendor qualification timelines from years to months as FDA impurity mandates tighten.
Growth Catalysts
- ICH M7 Mutagenic Impurity Framework:FDA enforcement of genotoxic impurity risk assessment protocols compels sponsors to outsource to CDMOs with dedicated analytical toxicology capabilities.
- High-Potency Oncology Synthesis:Containment engineering for cytotoxic APIs requires specialized isolator technology that only select contract manufacturers possess.
- Switzerland-Singapore Manufacturing Clusters:These jurisdictions offer combined regulatory credibility and advanced containment infrastructure for hazardous compound production.
Market Restraints
- Specialized Solvent Cost Volatility:Fluorinated solvents and organometallic reagents face supply constraints from Chinese export licensing and ECHA REACH registration costs.
- Single-Site Containment Bottleneck:High-potency API production concentrates in fewer than twenty qualified facilities worldwide, creating geographic supply risk.
- Continuous Flow Equipment Capex:Microreactor and flow chemistry platforms require capital deployment that mid-tier CDMOs cannot access.
Strategic Opportunities
- India Regulatory Pathway Expansion:CDSCO accelerated approval tracks for oncology APIs create entry points for Western sponsors seeking cost-competitive GMP manufacturing.
- EU AI Act Documentation Mandates:Algorithmic process control systems for reaction optimization require qualified validation partners, creating service adjacencies.
- Biotechnology Virtual Model Proliferation:Asset-light development firms lack internal chemistry capabilities, expanding addressable contract research-to-manufacturing relationships.
Industry Challenges
- Process Analytical Technology Integration:PAT implementation for real-time release testing demands cross-functional teams combining spectroscopy, chemometrics, and regulatory science.
- ISO 9001-ICH Q7 Audit Congestion:Sponsor qualification backlogs delay contract initiation as vendor pools narrow to currently certified facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecules Innovator Contract Development and Manufacturing Organization Market |
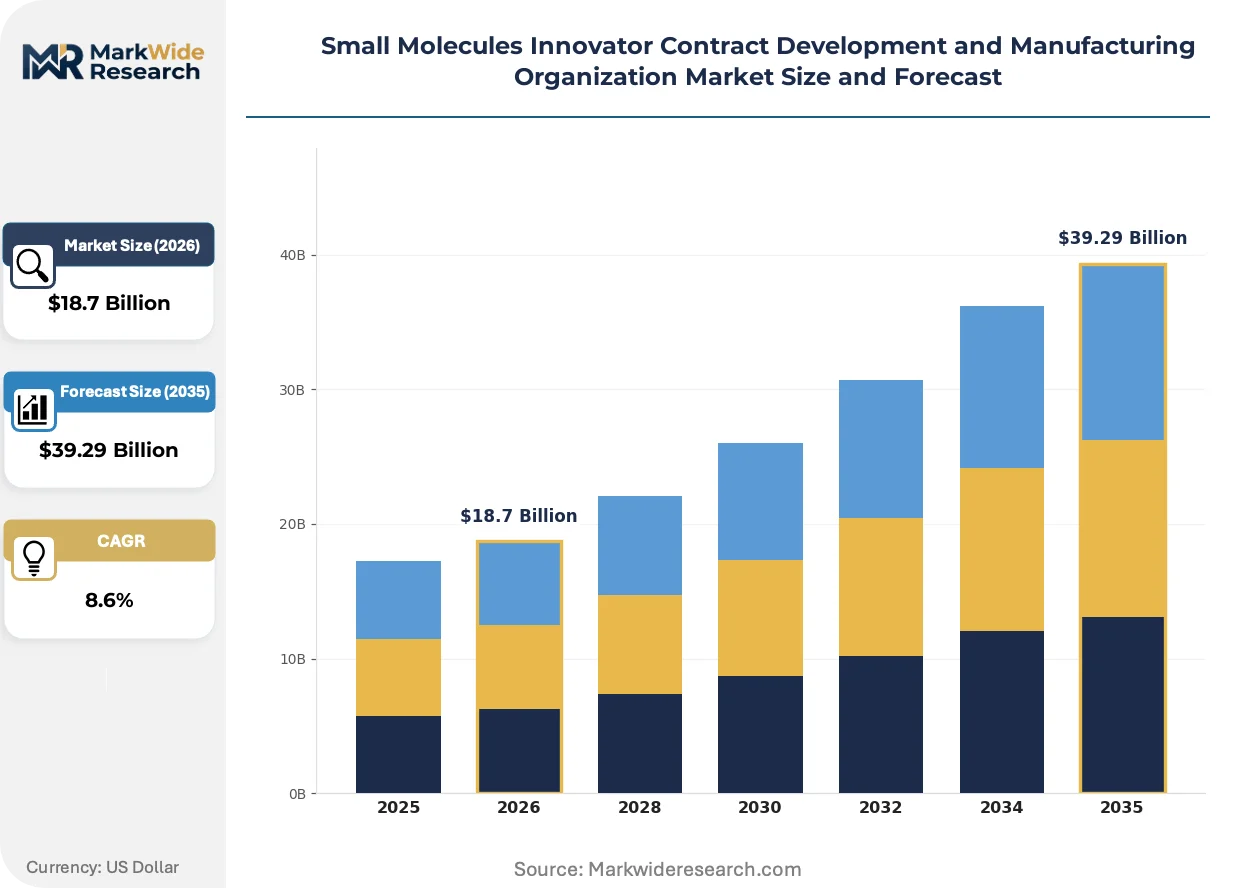
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Services, Manufacturing, Packaging Delivery Model: Onsite, Offsite, Hybrid, Remote Customer Type: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Technology: Chemical Synthesis, Formulation Development, Quality Control, Regulatory Compliance |
| Companies Covered | WuXi AppTec, Siegfried Holding, Lonza Group, CordenPharma, Recipharm, Catalent, Cambrex, Piramal Pharma Solutions, Thermo Fisher Scientific (Patheon), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecules Innovator Contract Development and Manufacturing Organization Market Trends and Innovations
Continuous manufacturing platforms are rewriting process economics for small-molecule APIs, while regulatory digitization and sponsor outsourcing models compress traditional development timelines.
Flow chemistry reactor systems is supplanting batch vessel infrastructure for hazardous nitration and hydrogenation steps. Mid-sized biotechnology sponsors are adopting these platforms for Phase II API supply, eliminating scale-up validation runs that previously consumed twelve to eighteen months. The technology is supplanting traditional kilo-lab campaigns by enabling direct transfer from gram-scale optimization to commercial production.
EMA F-Gas Regulation restricts hydrofluorocarbon solvent emissions from European manufacturing sites, forcing CDMOs to invest in solvent recovery and alternative chemistry routes. Contract manufacturers with integrated distillation and carbon capture infrastructure capture sponsor preference as compliance costs escalate. Swissmedic-licensed facilities in Basel and Singapore's Tuas Biomedical Park lead adaptation through closed-loop solvent systems.
Sponsor quality agreements now specify real-time data sharing through validated electronic systems, replacing quarterly audit cycles with continuous performance monitoring. Large pharmaceutical procurement functions demand API batch records within twenty-four hours of completion, displacing paper-based certificate of analysis exchanges. This behavioral shift is most pronounced in oncology programs where FDA breakthrough therapy designations compress CMC development windows.
Small Molecules Innovator Contract Development and Manufacturing Organization Market Segmentation
Segmentation in the small molecules innovator CDMO market reveals how service bundling, delivery flexibility, and technology specialization determine contract economics. Sponsors select vendors based on where capabilities intersect with pipeline stage and regulatory complexity.
Service Type:
Process development flows through early-phase relationships, manufacturing locks in long-term supply agreements, and analytical services bridge both channels with recurring revenue.
- Process Development:Synthetic route design, scale-up validation, and impurity profiling convert medicinal chemistry leads into GMP-ready processes. Demand concentrates among biotechnology sponsors in Basel and Singapore as virtual development models proliferate and FDA ICH M7 mandates tighten genotoxic impurity assessment requirements.
- Manufacturing:Commercial batch production and campaign management under cGMP conditions represent the capital-intensive core of CDMO value pools. Swissmedic-licensed facilities in Switzerland and Singapore's Tuas Biomedical Park anchor this segment through high-containment infrastructure for oncology APIs.
- Analytical Services:Method development, stability testing, and release analytics support both development and commercial phases.
- Packaging:Primary and secondary packaging for clinical and commercial supply, including serialization for EU FMD compliance.
By volume, Manufacturing leads. By growth pace, Process Development is expanding most quickly.
Delivery Model:
Cost tiers separate capital-heavy onsite commitments from variable offsite arrangements, with hybrid models capturing mid-market sponsors seeking flexibility.
- Onsite:Dedicated personnel and equipment embedded at sponsor facilities for confidential early-phase programs. Large pharmaceutical companies in the US and Germany favor this model for competitive isolation of breakthrough oncology assets.
- Offsite:Fully outsourced execution at CDMO facilities with standardized technology transfer protocols. Biotechnology firms lacking internal chemistry infrastructure drive demand here.
- Hybrid:Blended resourcing combining sponsor oversight with CDMO execution flexibility.
- Remote:Cloud-based project management and virtual collaboration for analytical and regulatory services.
Offsite commands the largest contract value. Hybrid arrangements are climbing the fastest as sponsors balance control with capital efficiency.
Customer Type:
Application intensity varies sharply: pharmaceutical companies prioritize manufacturing scale, while biotechnology firms concentrate spend on development services.
- Pharmaceutical Companies:Established sponsors with internal manufacturing seeking overflow capacity or specialized containment for high-potency compounds. FDA breakthrough therapy designations compress their CMC timelines, forcing reliance on pre-qualified CDMO networks.
- Biotechnology Firms:Asset-light developers without captive chemistry capabilities represent the steepest expansion trajectory. CDSCO accelerated approval tracks in India create cost-competitive entry points for these sponsors.
- Academic Institutions:Grant-funded translational research requiring kilo-lab scale-up for IND-enabling studies.
- Research Organizations:Non-profit and government entities supporting early-stage drug discovery.
Pharmaceutical companies anchor contract value. Biotechnology firms are gaining share fastest.
Technology:
Margin structures diverge: chemical synthesis and formulation development command premium pricing, while quality control and regulatory compliance provide recurring revenue stability.
- Chemical Synthesis:Route scouting, chiral resolution, and continuous flow process design for complex small molecules. EMA F-Gas Regulation restrictions on fluorinated solvents in Europe force investment in alternative chemistry approaches.
- Formulation Development:Solubility enhancement, stability optimization, and dosage form design for poorly soluble APIs.
- Quality Control:Batch release testing, stability monitoring, and method validation under ICH Q2 guidelines.
- Regulatory Compliance:CMC documentation, agency correspondence, and inspection readiness for FDA and EMA submissions.
Chemical Synthesis generates the highest per-project revenue. Regulatory Compliance shows the steadiest expansion as documentation mandates multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basel-Mulhouse-Freiburg tri-border region anchors European small-molecule CDMO capacity through its high-containment infrastructure and Swissmedic-licensed facilities. Singapore's Tuas Biomedical Park connects to global shipping lanes via the Port of Singapore, enabling just-in-time API distribution to oncology sponsors across Asia-Pacific and North America.
United States
FDA breakthrough therapy designations compress CMC timelines for oncology sponsors, forcing reliance on pre-qualified CDMO networks. The agency enforces ICH M7 guidelines for mutagenic impurity assessment, elevating demand for contract manufacturers with dedicated analytical toxicology capabilities. Greater Boston and the San Francisco Bay Area concentrate biotechnology sponsor headquarters, driving demand for integrated discovery-to-commercial platforms.
Switzerland
Swissmedic-licensed facilities in Basel command premium positioning for high-potency API production under stringent containment protocols. The jurisdiction offers regulatory credibility that accelerates sponsor qualification timelines from years to months. Basel's pharmaceutical cluster houses specialized isolator technology for cytotoxic compound synthesis, attracting FDA and EMA submission-bound programs.
Singapore
Tuas Biomedical Park provides advanced containment infrastructure for hazardous small-molecule production with direct port access to Asian and European markets. The Economic Development Board incentivizes pharmaceutical manufacturing through tax and land-use programs. Local CDMOs serve as regional hubs for biotechnology sponsors seeking cost-competitive GMP manufacturing without Chinese supply chain exposure.
India
CDSCO accelerated approval tracks for oncology APIs create entry points for Western sponsors seeking alternative manufacturing geography. The Department of Pharmaceuticals promotes active pharmaceutical ingredient production through PLI scheme incentives. Hyderabad and Ahmedabad clusters specialize in synthetic route development and commercial batch production for export markets.
Germany
ECHA REACH registration costs and EMA F-Gas Regulation restrictions on fluorinated solvents elevate compliance burdens for European manufacturing sites. The regulatory framework favors CDMOs with integrated solvent recovery and carbon capture infrastructure. Frankfurt-Rhine-Main and Bavaria host formulation development centers that bridge process chemistry with commercial scale-up.
Small Molecules Innovator Contract Development and Manufacturing Organization Market Competitive Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The vendor base organizes into three tiers: integrated multinationals with discovery-to-commercial platforms, mid-cap specialists with regional high-containment assets, and boutique providers focused on early-phase chemistry. Strategic archetypes include platform integrators, containment specialists, and R&D bridge builders. Consolidation through acquisition and greenfield capacity expansion in Switzerland and Singapore represent dominant competitive moves.
Within the platform integrator tier, WuXi AppTec and Thermo Fisher Scientific (Patheon) exemplify end-to-end service architectures spanning multiple continents. Lonza Group anchors the containment specialist archetype through Swissmedic-licensed high-potency capabilities. Siegfried Holding occupies a position bridging early-phase chemistry with scalable GMP routes, representing the R&D bridge builder model that biotechnology sponsors increasingly favor.
| Leading Market Players |
|---|
| WuXi AppTec |
| Siegfried Holding |
| Lonza Group |
| CordenPharma |
| Recipharm |
| Catalent |
| Cambrex |
| Piramal Pharma Solutions |
| Thermo Fisher Scientific (Patheon) |
| Others |
Pricing and Supply Chain Analysis
High-containment facility utilization rates above eighty percent in Switzerland and Singapore establish price floors that mid-tier CDMOs cannot undercut without sacrificing ICH Q7 compliance. Scale economies at these specialized sites compress per-batch costs for oncology APIs while elevating barriers to entry for new capacity, concentrating pricing power among validated manufacturers and forcing sponsors into long-term offtake commitments to secure campaign slots.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations, with three-tier pricing separating Swissmedic-licensed high-containment facilities from standard GMP sites and emerging Indian CDSCO-registered plants. Price differentiation hinges on certification grade and geographic delivery cost, with FDA-audited Swiss facilities commanding premiums over Singapore equivalents due to proximity to European sponsor headquarters. Pricing pressure stems from biotechnology sponsor procurement consolidation, as virtual development firms aggregate demand through preferred vendor networks. Large pharmaceutical companies exhibit lowest price sensitivity, prioritizing supply security over per-gram economics, while emerging biotechnology firms drive aggressive benchmarking across Asian manufacturing alternatives.
Supply Chain Analysis
Switzerland and Singapore anchor high-potency API manufacturing through Swissmedic-licensed containment infrastructure, while India and China supply fluorinated solvents and organometallic reagents under tightening export licensing regimes. Raw material dependencies center on palladium catalysts, high-purity solvents, and specialized isolator components sourced from German and Japanese precision engineering suppliers. Single-source vulnerability concentrates in isolator technology providers, where fewer than five qualified vendors serve the global market. Distribution runs through just-in-time air freight corridors connecting Basel and Singapore to sponsor formulation facilities in the United States and Germany, with port congestion at Singapore's Tuas Biomedical Park representing a persistent logistics chokepoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large pharmaceutical sponsors as biotechnology firm consolidation through merger activity reduces the fragmented demand base that previously supported mid-tier CDMO proliferation.
For Market Incumbents: Compound defensive positioning through backward integration into solvent recovery infrastructure and captive supply of high-purity reagents, countering margin erosion from ECHA REACH registration cost escalation. Prioritize capacity addition in Singapore's Tuas Biomedical Park to capture Asia-Pacific sponsor demand while Swiss facilities face EMA F-Gas Regulation compliance investments. Certification investment in ISO 9001-ICH Q7 concurrent audits preserves vendor pool eligibility as sponsor qualification backlogs intensify. For New Entrants and Emerging Players: Lead with CDSCO-accelerated approval track specialization in Hyderabad and Ahmedabad clusters, targeting Western biotechnology sponsors seeking cost-competitive GMP manufacturing without Chinese supply chain exposure. White-space targets include continuous flow process development for Phase II API supply and algorithmic process control validation services under EU AI Act documentation mandates. Go-to-market angle emphasizes direct sponsor collaboration through cloud-based project management platforms displacing quarterly audit cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CDMOs with integrated analytical services and long-term commercial supply agreements, providing cash flow stability across sponsor pipeline volatility. Acquisition target archetype encompasses mid-cap specialists with regional high-containment assets in Switzerland or Singapore, bridging early-phase chemistry with scalable GMP routes. Signal to watch is FDA breakthrough therapy designation volume, which compresses CMC timelines and forces sponsor reliance on pre-qualified vendor networks.| Strategic Initiative | Industry Significance |
|---|---|
| High-Containment Capacity Expansion | Swissmedic-licensed isolator infrastructure captures oncology API demand as FDA impurity mandates tighten. |
| Continuous Flow Technology Investment | Microreactor platforms eliminate scale-up validation runs, compressing sponsor timelines from months to weeks. |
| Regulatory Compliance Service Adjacency | EU AI Act documentation capabilities for algorithmic process control create differentiated service bundles. |
| Backward Integration into Solvent Recovery | Closed-loop distillation infrastructure offsets EMA F-Gas Regulation compliance costs and secures sponsor preference. |
| Geographic Diversification into India | CDSCO-accelerated approval tracks attract Western sponsors seeking cost-competitive manufacturing alternatives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and analytical toxicology specialists; and secondary validation through FDA filings, EMA submissions, Swissmedic licensing records, and CDSCO approval databases. Bottom-up triangulation across sponsor pipeline data and top-down reconciliation with customs trade statistics anchored volume estimates. Cross-functional verification combined chemistry process insights with regulatory science perspectives to assess ICH M7 compliance cost impacts.
Across the analysis window, the analytical framework modeled segmentation dimensions including service type, delivery model, customer archetype, and technology specialization, with additional stratification by regional regulatory cluster and containment capability tier. CAGRs were derived through trend extrapolation of sponsor outsourcing rates, pipeline stage distributions, and capacity utilization trajectories at qualified facilities. Industry-specific forecast inputs incorporated FDA breakthrough therapy designation velocity and EMA F-Gas Regulation implementation timelines affecting European manufacturing economics.
The analysis sits within stated boundaries; outcomes outside sustained oncology pipeline expansion, stable regulatory enforcement intensity, and intact sponsor outsourcing preferences would require recalibration. Forecasts reflect documented assumptions regarding ICH M7 guideline adherence costs and high-containment facility qualification timelines. Recalibration cycles align with material shifts in FDA inspection frequency, CDSCO regulatory pathway modifications, and sponsor consolidation patterns affecting demand fragmentation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Solketal Market
Specialty Compounds
Lentein Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
White Carbon Black Market