
 Tosyl Chloride Market | 2026-2036
Tosyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Tosyl Chloride Market Insights
Specialty chemical distribution is fragmenting across multiple tiers as regional traders and direct-from-manufacturer channels compete for Tosyl Chloride procurement relationships. Jiangsu New Xinlong Medicine Technology leverages its integrated pharmaceutical intermediate pipeline to secure captive demand from domestic drug manufacturers. BASF SE anchors European supply reliability through controlled logistics networks and REACH-compliant documentation systems. Nantong Volant-Chem Corp competes aggressively on specification flexibility, offering customized purity grades that differentiate its portfolio from commodity traders.
Tosyl chloride (4-methylbenzenesulfonyl chloride) functions as a sulfonating and chlorinating reagent, typically supplied at purity levels exceeding 98 percent for pharmaceutical-grade applications where moisture sensitivity demands anhydrous handling protocols. The compound enables tosylation reactions that protect amine functional groups during multi-step organic synthesis, making it indispensable to complex molecule manufacturing. Anhydrous product types command premium positioning due to stringent stability requirements in GMP-regulated pharmaceutical environments, while industrial-grade aqueous solutions serve cost-sensitive dye and agrochemical intermediates. Synthetic reagents represent the fastest-growing application segment as contract research organizations expand outsourced medicinal chemistry services across Asia-Pacific manufacturing clusters.
EPA oversight governs hazardous chemical storage and transport parameters within United States jurisdiction, while REACH registration mandates in Europe impose full substance dossier requirements on importers exceeding one-ton annual thresholds. China's MEE administers dual carbon compliance frameworks that increasingly scrutinize energy-intensive chlorination processes and associated emissions profiles. Manufacturers navigating this triad of regulatory regimes must align product documentation, environmental disclosures, and supply chain audit trails with divergent compliance architectures. Stakeholders should monitor evolving substance restriction proposals and carbon border adjustment mechanisms that could restructure competitive cost positions between Asian producers and Western chemical houses.
Market Dynamics
Specialty chemical distributors face margin compression as pharmaceutical manufacturers consolidate procurement through direct-from-manufacturer channels, bypassing traditional intermediaries that previously captured value across Tosyl chloride supply chains.
Growth Catalysts
- Pharmaceutical outsourcing expansion:Contract research organizations across Asia-Pacific manufacturing clusters scale medicinal chemistry services, driving consumption of high-purity sulfonating reagents for complex molecule synthesis.
- REACH compliance as competitive moat:European importers with full substance dossiers exceeding one-ton annual thresholds secure preferential access to regulated pharmaceutical supply chains against non-compliant traders.
- Agrochemical intermediate diversification:Crop protection manufacturers deploy tosylation chemistry for novel herbicide and fungicide active ingredient pipelines, expanding addressable demand beyond traditional dye applications.
Market Restraints
- Toluene feedstock volatility:Aromatic hydrocarbon price swings transmit directly into tosyl chloride production economics, compressing margin predictability for non-integrated compounders.
- Chlorination process emissions scrutiny:China's MEE dual carbon frameworks intensify compliance burdens on energy-intensive production assets, elevating operating costs for unabated facilities.
- Sulfonyl fluoride substitution pressure:Alternative sulfonating agents with milder handling profiles encroach on pharmaceutical applications where moisture sensitivity drives reagent selection.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-registered domestic drug substance producers build captive intermediate capabilities, creating localized demand for specification-flexible reagent suppliers.
- Continuous flow chemistry adoption:Process intensification technologies enable on-demand tosylation with reduced solvent inventories, aligning with EPA hazardous waste minimization incentives.
- Specialty agrochemical channels:Direct technical sales to Brazil's ANVISA-registered formulators bypass commodity trader markups in crop protection value chains.
Industry Challenges
- Anhydrous handling certification gaps:GMP-compliant logistics providers with validated cold-chain documentation remain scarce outside established pharmaceutical corridors, constraining geographic expansion.
- REACH dossier maintenance burden:Substance data gap assessments and exposure scenario updates demand dedicated regulatory affairs capacity that mid-scale distributors struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tosyl Chloride Market |
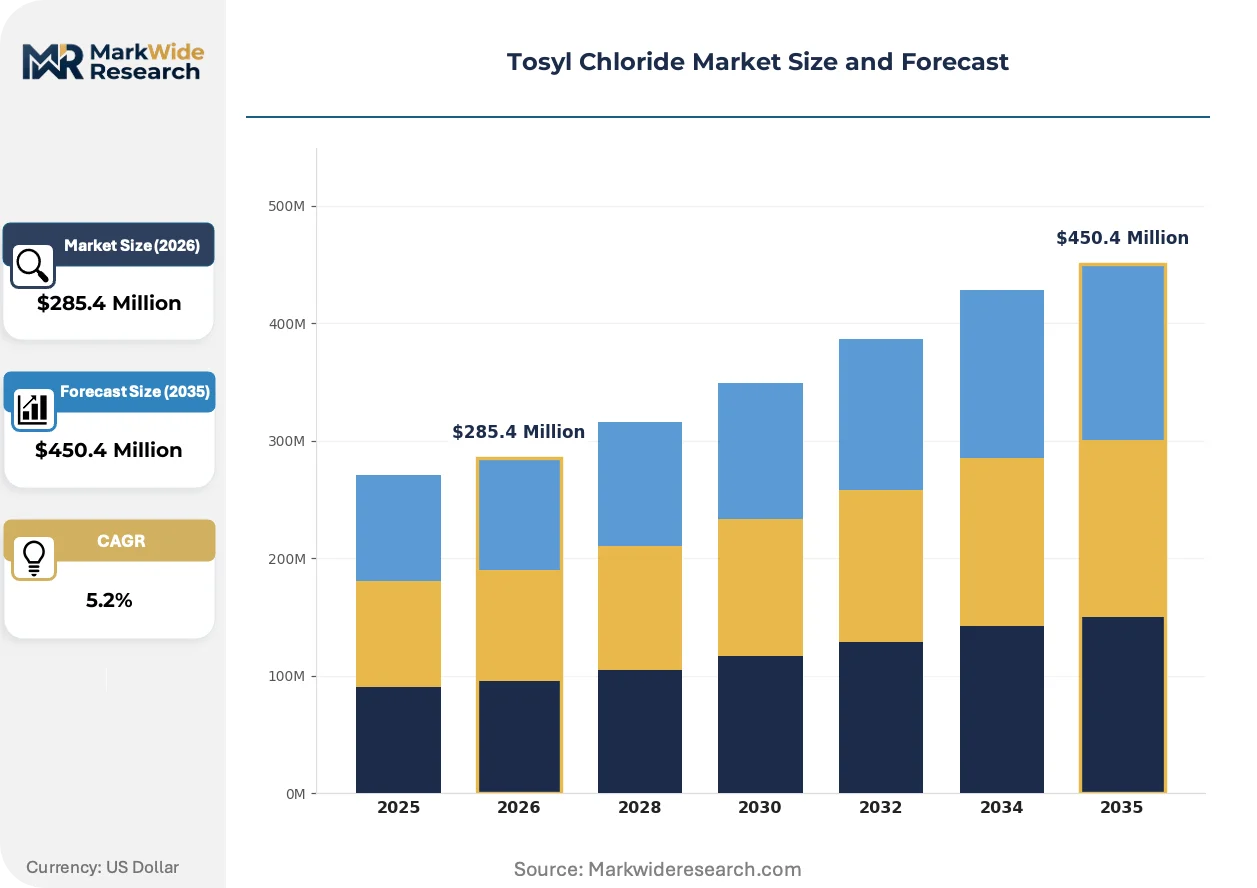
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Aqueous Solution, Other Solvents, Crystalline End User: Pharmaceutical Companies, Chemical Manufacturers, Research Institutions, Industrial Applications Application: Synthetic Reagents, Coupling Agents, Protective Groups, Intermediates Grade: Analytical Grade, Laboratory Grade, Industrial Grade, Reagent Grade |
| Companies Covered | Jiangsu New Xinlong Medicine Technology, Nantong Volant-Chem Corp, Jiaxing Jinli Chemical, Jiaxing Anrui Material Technology, Yangzhou Juhechang Technology, Changzhou Xudong Chemical, Lanxi Sanyi Chemical, Zhejiang Jiahua Energy Chemical, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tosyl Chloride Market Trends and Innovations
Process intensification and regulatory disclosure requirements are restructuring how Tosyl chloride moves from chlorination assets to end-use synthesis, with implications for inventory positioning, specification granularity, and supplier qualification protocols across pharmaceutical and agrochemical value chains.
Continuous flow reactor technology is hybridizing batch sulfonation processes that historically dominated tosyl chloride manufacturing. Pharmaceutical contract manufacturers in Switzerland and Singapore adopt microreactor platforms for on-demand tosylation, eliminating bulk reagent storage liabilities. This architecture compresses working capital requirements while satisfying FDA and Swissmedic inspectorate preferences for closed-system handling.
REACH Article 33 supply chain communication obligations now extend to downstream pharmaceutical formulators using tosyl chloride-derived intermediates. ECHA SCIP database submissions force ingredient-level traceability that legacy procurement systems cannot support. European generic drug manufacturers respond by consolidating supplier panels to entities with pre-submitted dossier transparency.
Specification-driven purchasing now dominates pharmaceutical procurement, displacing spot-market spot-buying for commodity-grade material. Quality agreement templates with locked purity certificates and residual solvent specifications reduce incoming testing burden. This pattern concentrates most visibly among South Korean MFDS-registered API producers building dual-source strategies for critical reagents.
Tosyl Chloride Market Segmentation
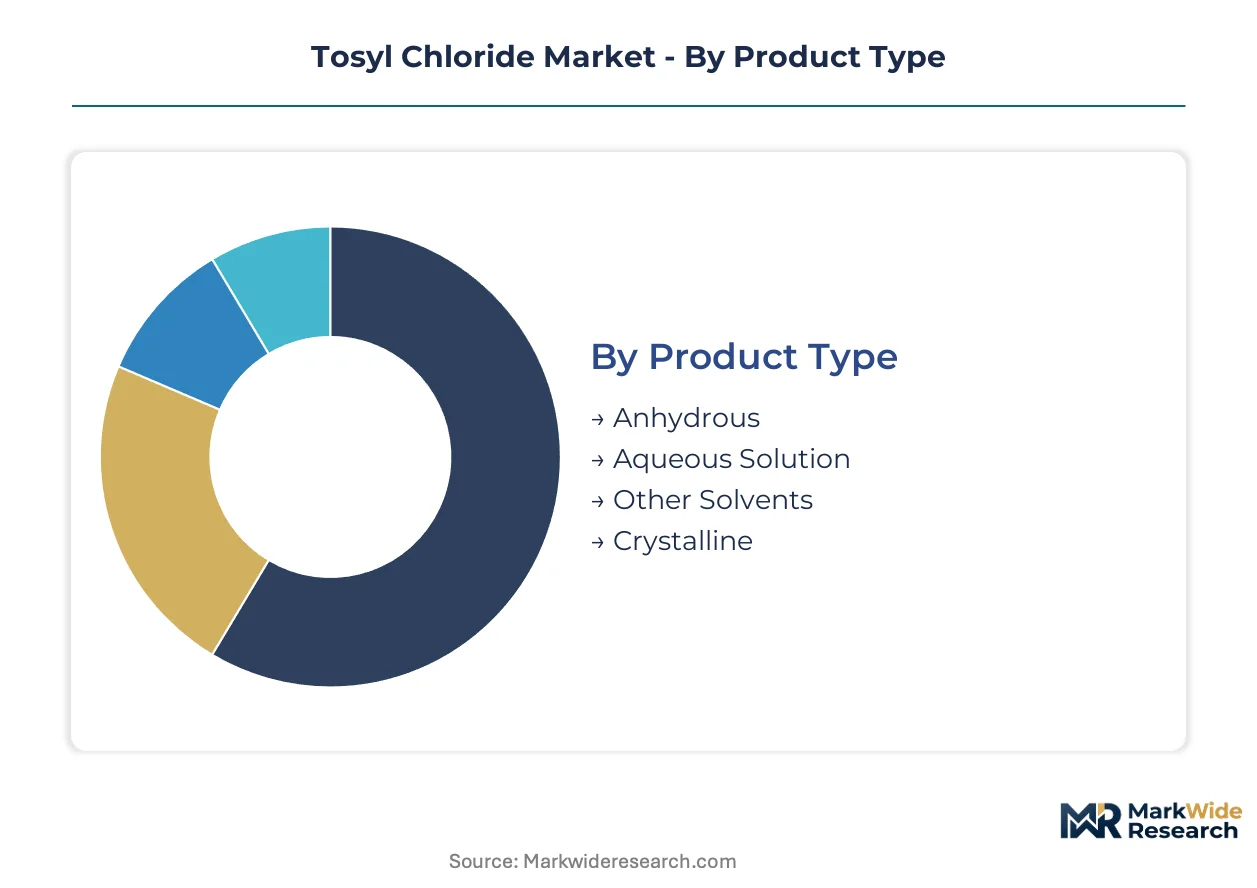
Tosyl chloride procurement patterns diverge sharply across purity specifications and end-use requirements. Pharmaceutical-grade anhydrous material commands fundamentally different logistics, certification, and pricing architectures than industrial-grade aqueous formulations.
Product Type:
Mature commodity formats coexist with emerging specification-driven variants as end-users segment procurement by moisture sensitivity and handling protocols.
- Anhydrous:Water-free specification exceeding 98% purity enables GMP-compliant pharmaceutical synthesis where hydrolytic degradation risks invalidate standard grades. South Korean MFDS-registered API manufacturers anchor demand for validated cold-chain documentation and locked residual moisture certificates.
- Aqueous Solution:Industrial-grade formulations serve cost-sensitive dye intermediates and agrochemical manufacturing where moisture tolerance eliminates anhydrous handling premiums. Brazilian ANVISA-registered formulators in crop protection channels drive volume procurement through direct technical sales relationships.
- Other Solvents:Alternative carrier systems accommodate specialized solubility requirements in continuous flow reactor applications.
- Crystalline:Solid-phase presentation supports precise dosing in automated synthesis platforms and reduces shipping weight penalties.
Anhydrous retains volume leadership; crystalline formats hold the steepest expansion curve as microreactor adoption accelerates.
End User:
Customer type determines certification burden, contract structure, and supplier qualification intensity across divergent procurement workflows.
- Pharmaceutical Companies:CDSCO-registered Indian drug substance producers build captive intermediate capabilities requiring REACH-aligned dossier transparency and locked purity specifications. Quality agreement templates with incoming testing waivers reduce procurement friction for pre-qualified suppliers.
- Chemical Manufacturers:Specialty compounders serving agrochemical and dye value chains prioritize specification flexibility over documentation depth.
- Research Institutions:Contract research organizations across Asia-Pacific manufacturing clusters scale medicinal chemistry services with small-batch, high-frequency ordering patterns.
- Industrial Applications:Bulk consumers in polymer and surfactant manufacturing tolerate wider purity bands in exchange for volume pricing.
Pharmaceutical companies retain volume leadership; research institutions hold the steepest expansion curve as outsourced discovery chemistry expands.
Application:
Functional role in synthesis determines reagent selection criteria, with protective group chemistry commanding distinct technical specifications.
- Synthetic Reagents:Direct sulfonating functionality supports complex molecule construction across multi-step organic synthesis. Singapore-based pharmaceutical contract manufacturers adopt microreactor platforms for on-demand tosylation, eliminating bulk storage liabilities while satisfying FDA inspectorate preferences for closed-system handling.
- Coupling Agents:Activation chemistry for amide bond formation serves peptide and nucleotide synthesis pipelines.
- Protective Groups:Tosylation of amine functional groups enables selective deprotection strategies in orthogonal synthesis schemes.
- Intermediates:Downstream building blocks for agrochemical active ingredients and specialty dyes.
Synthetic reagents retain volume leadership; protective group applications hold the steepest expansion curve as complex molecule manufacturing intensifies.
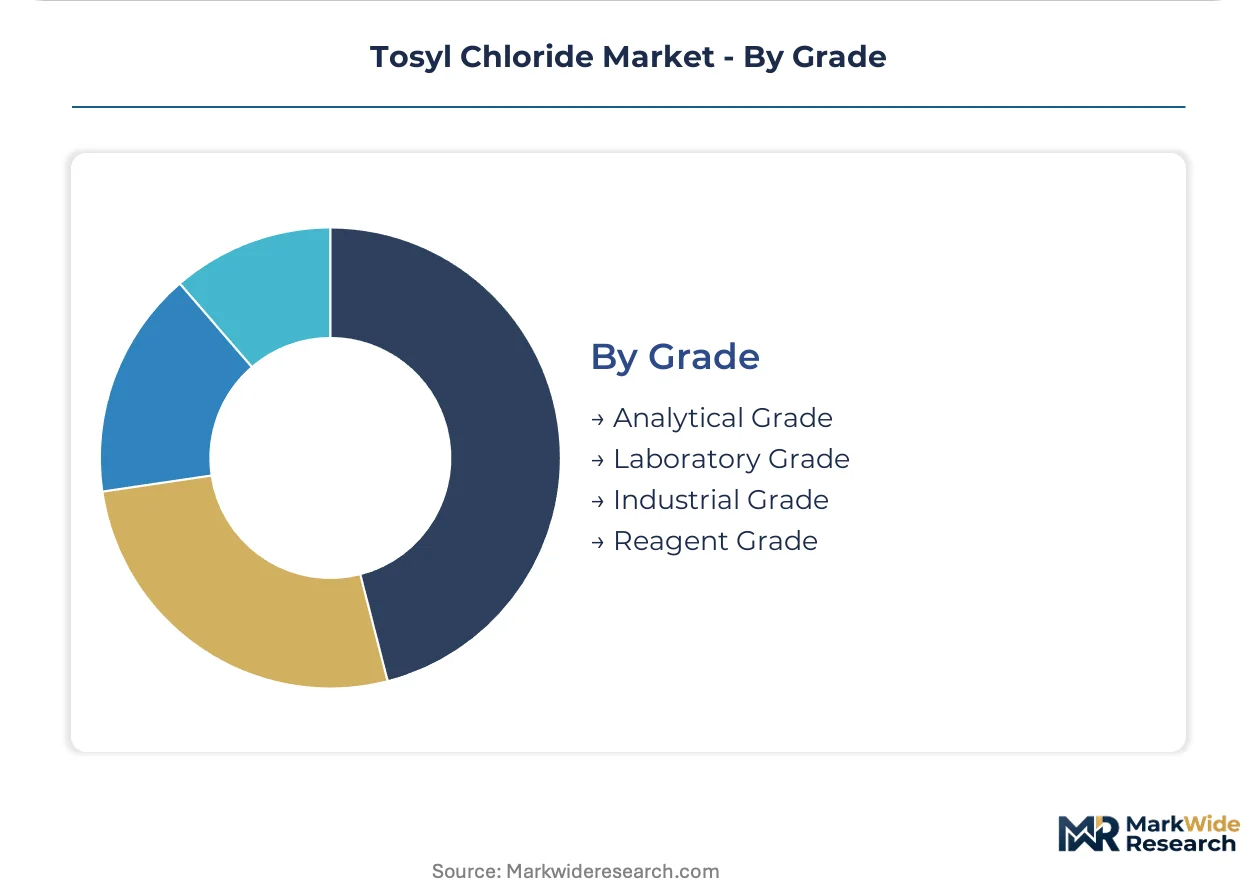
Grade:
Certification tier directly maps to end-use regulatory exposure and testing protocol requirements.
- Analytical Grade:Ultra-high purity with comprehensive certificate of analysis supports quantitative method development and reference standard preparation. Swissmedic-regulated environmental testing laboratories in Switzerland demand batch-specific impurity profiling and elemental analysis documentation.
- Laboratory Grade:R&D-scale consumption across discovery chemistry and route scouting exercises.
- Industrial Grade:Cost-optimized specification for non-regulated manufacturing with relaxed purity tolerances.
- Reagent Grade:General-purpose synthesis quality balancing purity and cost for scale-up activities.
Industrial grade retains volume leadership; analytical grade holds the steepest expansion curve as regulatory testing requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors Asia-Pacific chemical logistics, handling bulk sulfonating reagent flows that feed pharmaceutical manufacturing clusters across the Yangtze River Delta.
China
Domestic pharmaceutical intermediate production scales rapidly in Jiangsu and Zhejiang provinces. MEE dual carbon frameworks scrutinize chlorination process emissions at manufacturing assets. Nantong specialty chemical parks concentrate tosyl chloride capacity serving captive demand from nearby API producers.
United States
Contract research organizations expand medicinal chemistry outsourcing in Boston and San Diego biotech corridors. EPA hazardous chemical storage regulations govern warehouse configurations for moisture-sensitive reagents. Texas Gulf Coast petrochemical infrastructure supplies toluene feedstock to regional compounders.
Germany
REACH-registered importers secure preferential access to European pharmaceutical supply chains. ECHA substance dossier requirements exceed one-ton annual thresholds for active ingredient manufacturers. Ludwigshafen chemical complex maintains controlled logistics networks for GMP-compliant distribution.
India
CDSCO-registered drug substance producers build captive intermediate capabilities in Maharashtra and Gujarat. PLI scheme incentives accelerate domestic pharmaceutical manufacturing scale-up. Hyderabad and Mumbai pharmaceutical clusters drive specification-flexible reagent procurement.
Switzerland
Swissmedic-regulated contract manufacturers adopt microreactor platforms for on-demand tosylation. Basel pharmaceutical corridor demands validated cold-chain documentation for anhydrous handling. Singapore-based pharmaceutical services firms route European-bound reagent shipments through Swiss distribution nodes.
Tosyl Chloride Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying specification-grade material to downstream formulators. The vendor base organizes around three archetypes: integrated pharmaceutical intermediate producers, commodity chemical traders with documentation capabilities, and specialty distributors serving regulated end-use channels. Consolidation pressures favor entities with REACH-aligned dossier transparency and GMP-compliant logistics infrastructure. Dominant competitive moves include backward integration into toluene feedstock sourcing and geographic expansion toward Indian pharmaceutical manufacturing clusters.
Among Chinese specialty chemical producers, Jiangsu New Xinlong Medicine Technology and Nantong Volant-Chem Corp exemplify the integrated intermediate archetype, occupying positions that bridge chlorination assets and pharmaceutical customer specifications. BASF SE anchors the European documentation-heavy tier, representing the REACH-compliant importer model that secures preferential access to regulated supply chains. These three entities illustrate the competitive spectrum from captive production integration to logistics-controlled distribution.
| Leading Market Players |
|---|
| Jiangsu New Xinlong Medicine Technology |
| Nantong Volant-Chem Corp |
| Jiaxing Jinli Chemical |
| Jiaxing Anrui Material Technology |
| Yangzhou Juhechang Technology |
| Changzhou Xudong Chemical |
| Lanxi Sanyi Chemical |
| Zhejiang Jiahua Energy Chemical |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang province chlorination assets concentrate upstream tosyl chloride capacity, feeding margin pools downstream to REACH-registered European importers and GMP-certified pharmaceutical distributors who capture documentation premiums. Toluene feedstock volatility transmits directly into production economics, compressing margin predictability for non-integrated compounders while specification-flexible suppliers defend pricing power through purity-grade differentiation.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade anhydrous, industrial-grade aqueous, and laboratory-grade crystalline formats dominates transactional flows. Price differentiation hinges on certification depth—REACH dossier transparency and GMP-compliant cold-chain documentation command substantial premiums over commodity-grade material. Pricing pressure stems from sulfonyl fluoride substitution in moisture-sensitive applications, eroding share in high-value pharmaceutical synthesis. Research institutions and contract research organizations exhibit highest price sensitivity due to small-batch ordering patterns, while CDSCO-registered Indian API manufacturers prioritize specification-locked supply agreements over spot-market procurement.
Supply Chain Analysis
Contract manufacturing concentration sits with Singapore-based pharmaceutical services firms and Swissmedic-regulated Basel corridor operators adopting microreactor platforms for on-demand production. Geographic supply concentration centers on China, India, and Germany, with Jiangsu specialty chemical parks and Ludwigshafen chemical complex anchoring respective regional flows. Raw material dependencies draw from Texas Gulf Coast toluene infrastructure, European aromatic hydrocarbon trading hubs, and regional chlorination feedstock networks. Single-source vulnerability persists in anhydrous handling certification, where validated cold-chain providers remain scarce outside established pharmaceutical corridors. Distribution runs through direct technical sales to large pharmaceutical manufacturers, bypassing traditional intermediary markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tosyl chloride demand tracks pharmaceutical outsourcing cycles, with Asia-Pacific contract research organization expansion signaling recovery momentum after inventory destocking phases.
For Market Incumbents: Harden REACH-aligned dossier maintenance capabilities against ECHA substance data gap assessment burdens that mid-scale distributors struggle to resource. Deepen backward integration into toluene feedstock sourcing to insulate margin positions from aromatic hydrocarbon volatility. Prioritize GMP-compliant logistics infrastructure investments in Indian pharmaceutical corridors where CDSCO-registered producers consolidate supplier panels. For New Entrants and Emerging Players: Specification-flexible supply to Brazil's ANVISA-registered agrochemical formulators represents the most penetrable entry point outside saturated pharmaceutical channels. Continuous flow chemistry equipment partnerships with Swiss and Singapore-based contract manufacturers offer technology-leveraged positioning without chlorination asset ownership. Direct technical sales relationships with crop protection technical teams bypass entrenched commodity trader networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical distributors possessing REACH registration but lacking GMP logistics scale. Long-term viability over the next decade hinges on regulatory disclosure infrastructure rather than commodity volume positioning. Acquisition targets should demonstrate pre-submitted ECHA SCIP database capabilities and locked purity certificate systems. Watch for carbon border adjustment mechanism proposals as inflection signals for Asian producer cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Feedstock | Margin insulation from Texas Gulf Coast aromatic hydrocarbon price volatility strengthens cost predictability. |
| Microreactor Platform Adoption | Singapore-based contract manufacturers eliminate bulk storage liabilities while satisfying FDA inspectorate preferences. |
| REACH Dossier Transparency Investment | ECHA SCIP database submission capabilities unlock European generic drug manufacturer supplier panel consolidation. |
| GMP-Certified Cold-Chain Expansion | Validated anhydrous handling documentation scarcity outside established corridors creates defensive positioning. |
| Direct Technical Sales to Agrochemical Formulators | ANVISA-registered Brazilian crop protection channels bypass commodity trader markups in value chains. |
Research Methodology
Operator-level perspectives from plant managers at chlorination assets, procurement leads at CDSCO-registered API manufacturers, distribution channel partners in specialty chemical trading, and technical R&D directors at contract research organizations anchored the qualitative base. Secondary validation drew from customs and trade data, ECHA substance dossier filings, SEC 10-K disclosures from listed chemical houses, and ACC regional production reports. Bottom-up volume triangulation across purity grades and end-use segments converged with top-down macroeconomic scenario testing.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing around toluene feedstock volatility bands and regulatory disclosure cost trajectories. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub clustering. CAGRs derived from installed capacity utilization rates, pharmaceutical outsourcing contract visibility, and agrochemical active ingredient pipeline disclosures. Chlorination process emissions compliance costs under China's MEE dual carbon frameworks and REACH registration maintenance burdens shaped downside scenario parameters.
Practitioners should monitor ECHA substance restriction proposals, carbon border adjustment mechanism developments, and sulfonyl fluoride substitution rates in pharmaceutical applications for early signals of forecast revision. Quarterly review of CDSCO registration trends, Swissmedic inspection outcomes, and MEE enforcement intensity at Jiangsu chemical parks is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Superacids Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Triallyl Isocyanurate Market