
 Global Masterbatch Market | 2026-2036
Global Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Masterbatch Market Outlook
Automotive interior specifiers are unwinding legacy reliance on commodity black masterbatch as electric vehicle platforms demand lighter, laser-markable polymer systems. Clariant leverages its specialty additive portfolio to capture thermal-management compound demand from battery housing manufacturers. LyondellBasell Industries anchors global volume through backward integration into polypropylene resin and captive masterbatch compounding. Ampacet Corporation differentiates in North American food packaging with custom color-matching capabilities and rapid turnaround on short-run orders.
Masterbatch denotes concentrated mixtures of pigments, additives, or functional agents dispersed in a carrier resin, typically loaded at 15-50% active content before let-down during polymer processing. These compounds enable precise coloration, UV stabilization, flame retardancy, or barrier enhancement without direct handling of powdered additives. Color masterbatch commands the largest revenue share as brand owners enforce shelf-impact consistency across multi-sourced packaging films. Additive masterbatch represents the fastest-expanding category, driven by antioxidant and processing-aid demand in recycled-content resins where thermal history degrades base polymer performance.
The U.S. FDA maintains strict food-contact notification requirements for colorants and additives in packaging masterbatch, while the EU REACH framework restricts phthalate-based plasticizers and certain heavy-metal pigments across consumer goods applications. China's SAMR enforces GB standards for plastic food-contact materials that increasingly reference EU migration test protocols. Stakeholders must monitor evolving extended-producer-responsibility mandates and recycled-content quotas, as these policies will determine which carrier resins and additive packages qualify for premium specification tiers.
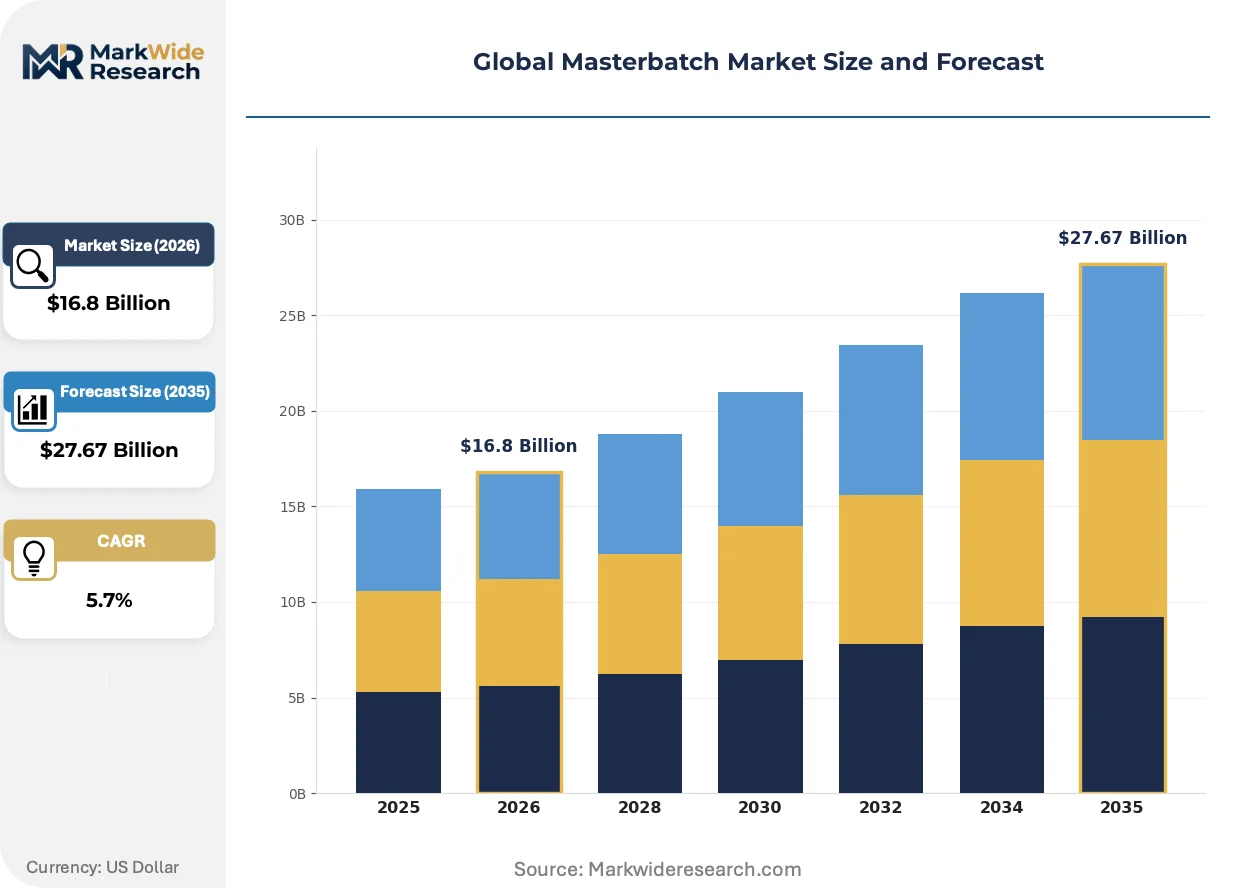
Market Dynamics
Electric vehicle battery thermal management is decomposing legacy masterbatch formulations as OEMs mandate polymer systems that dissipate heat while maintaining laser-markable surfaces for traceability compliance.
Growth Catalysts
- EU REACH migration limits:Tightened additive thresholds for food-contact plastics are forcing reformulation investments that favor specialized compounders with in-house regulatory laboratories over commodity suppliers.
- Recycled-content resin processing:Antioxidant masterbatch demand accelerates as mechanical recycling degrades polymer thermal stability, requiring processing aids to restore extrusion performance in post-consumer feedstocks.
- Vietnam packaging cluster expansion:Export-oriented flexible film converters are scaling masterbatch procurement to serve multinational brand owners relocating sourcing from China amid tariff diversification strategies.
Market Restraints
- Titanium dioxide feedstock volatility:White pigment masterbatch margins compress when ilmenite ore supply disruptions from South African mining operations spike raw material costs without immediate pass-through mechanisms.
- Carrier resin concentration:Polypropylene masterbatch supply chains concentrate among Middle Eastern and North American resin producers, creating vulnerability when regional ethylene crackers undergo unplanned maintenance.
- Heavy-metal pigment substitution:Cadmium and lead-based colorants face phased elimination under EU RoHS and REACH Annex XVII, forcing reformulation of long-shelf-life agricultural film colors where organic alternatives lack equivalent weathering resistance.
Strategic Opportunities
- Indonesia consumer goods manufacturing:Domestic plastics processing capacity for household products and personal care packaging remains underpenetrated by technical masterbatch suppliers capable of matching Japanese automotive-grade specifications.
- Near-infrared sorting compatibility:Black masterbatch formulations using perylene-based pigments instead of carbon black enable automated recycling stream identification, capturing value from extended-producer-responsibility mandates in France and Germany.
- Biopolymer carrier systems:Polylactic acid and polyhydroxyalkanoate-based masterbatches converge with compostable packaging demand to serve brand owners targeting home-compostable film certifications under TÜV Austria OK Compost HOME standards.
Industry Challenges
- Color-matching technician scarcity:Custom color formulation for short-run packaging orders requires spectrophotometry expertise and polymer rheology knowledge that vocational training programs in North America and Western Europe have not scaled to replace retiring workforce cohorts.
- Multi-jurisdiction food-contact certification:Simultaneous FDA notification, EU 10/2011 compliance, and China GB 4806.6 testing for a single masterbatch SKU extends commercialization timelines and fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Masterbatch Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Masterbatch, Additive Masterbatch, White Masterbatch, Black Masterbatch End Use Industry: Packaging, Automotive, Consumer Goods, Textiles Form: Granules, Pellets, Powders, Liquids Application: Injection Molding, Blow Molding, Film Extrusion, Rigid Packaging |
| Companies Covered | Clariant, LyondellBasell Industries, Avient Corporation, Kafrit Group, Plastika Kritis S.A., Ampacet Corporation, Tosaf Compounds Ltd., Penn Color Inc., Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Masterbatch Market Strategic Shifts
Masterbatch functionality is fragmenting from generic coloration toward engineered additive systems that solve specific processing constraints in recycled and bio-based polymer streams.
Laser-markable additive packages are decomposing conventional carbon black masterbatch dominance in automotive interior applications. Battery housing manufacturers specify these compounds to enable direct part marking for traceability without secondary labels. The shift compresses demand for commodity black formulations while expanding thermal-management compound development.
REACH Annex XVII restrictions on microplastic-containing products are compelling reformulation of flame-retardant masterbatches for construction films. Halogen-free phosphorus-nitrogen systems displace legacy brominated additives in European roofing membranes and tarpaulins. German and French building material distributors now require environmental product declaration documentation that captures additive migration risk.
Brand-owner consolidation in North American food packaging is compressing supplier bases and extending masterbatch contract durations. Converters favor compounders offering integrated color-matching services and inventory management programs over transactional pigment suppliers. This concentration is most visible in Chicago and Toronto metropolitan areas where flexible packaging headquarters cluster.
Global Masterbatch Market Segmentation
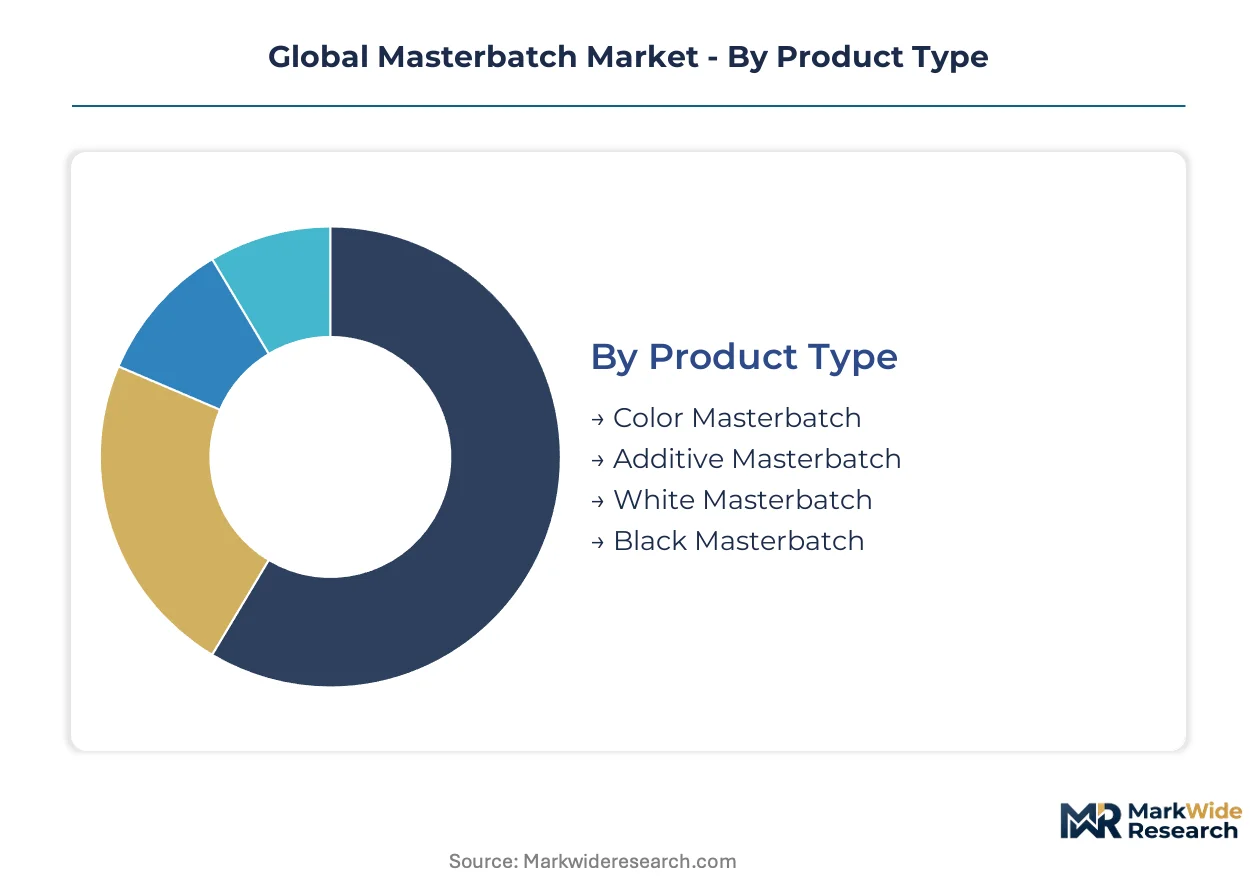
Masterbatch segmentation reflects divergent technical requirements across polymer processing methods and end-use compliance regimes. Formulators must match carrier resin compatibility, thermal stability thresholds, and migration limits to specific customer specifications.
Product Type:
Substitution pressure from liquid colorants and pre-colored compounds is reshaping solid masterbatch demand across high-volume packaging lines.
- Color Masterbatch:Pigment concentrates dispersed in polyolefin or styrenic carriers enable precise hue matching for brand-owner packaging specifications. Demand concentrates in Vietnam and Indonesia where flexible film converters serve multinational food brands relocating sourcing from China.
- Additive Masterbatch:Functional packages incorporating antioxidants, UV stabilizers, or flame retardants restore processing performance in mechanically recycled resins. Automotive battery housing manufacturers specify thermal-management compounds from specialty compounders with in-house regulatory laboratories.
- White Masterbatch:Titanium dioxide-loaded formulations face margin compression from ilmenite ore supply volatility.
- Black Masterbatch:Carbon black dominance erodes as laser-markable perylene pigments enable near-infrared sorting compatibility.
Color masterbatch anchors the volume base while additive masterbatch gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates specification-grade automotive compounds from commodity packaging formulations.
- Packaging:Food-contact films dominate procurement volumes with FDA notification and EU 10/2011 compliance requirements. Chicago and Toronto metropolitan packaging headquarters extend contract durations with integrated color-matching suppliers.
- Automotive:Electric vehicle platforms unwind legacy carbon black reliance in favor of laser-markable, thermally conductive polymer systems for battery traceability.
- Consumer Goods:Household product and personal care packaging in Indonesia remains underpenetrated by technical suppliers capable of Japanese automotive-grade specifications.
- Textiles:Fiber-grade masterbatches require low-denier compatibility and spun-dye processing stability.
Packaging commands the largest revenue position while automotive applications expand most quickly.
Form:
Processing equipment compatibility and dust containment requirements determine form selection across extrusion and molding operations.
- Granules:Irregular particles suit dry-blend feeding systems in legacy extrusion lines.
- Pellets:Cylindrical or spherical forms enable precise gravimetric dosing in automated compounding operations.
- Powders:Fine dispersions serve rotational molding and plastisol applications where rapid fusion is required.
- Liquids:Pumpable dispersions substitute for solid masterbatch in continuous film extrusion with color-change agility demands.
Pellet supply concentrates among backward-integrated resin producers while liquid systems capture share in short-run flexible packaging.
Application:
Customer type differentiation separates high-volume film extruders from precision injection molders with color-matching service requirements.
- Injection Molding:High-shear processing demands thermal stability and dispersion uniformity for thin-wall consumer electronics housings.
- Blow Molding:Parison formation requires melt strength optimization through processing-aid masterbatches in large-container applications.
- Film Extrusion:Multi-layer coextrusion lines in Southeast Asia specify food-grade masterbatches with low-gel specifications for export-oriented flexible packaging.
- Rigid Packaging:Thermoformed containers and closures require nucleating agents and impact modifiers in polypropylene formulations.
Film extrusion generates the highest absolute volume while rigid packaging climbs fastest on dairy and pharmaceutical container specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese flexible film converters supply multinational food brands across North America and Europe, with masterbatch procurement scaling to match export-oriented packaging volumes.
United States
Food-contact notification requirements under FDA jurisdiction drive reformulation investments among compounders serving Chicago and Toronto metropolitan packaging headquarters. The agency maintains strict additive migration thresholds for colorants in flexible films. Brand-owner consolidation in these clusters extends contract durations with integrated color-matching suppliers.
Germany
REACH Annex XVII restrictions on heavy-metal pigments and microplastic-containing products force halogen-free flame-retardant reformulation for construction films. ECHA enforcement of migration limits favors specialized compounders with in-house regulatory laboratories. Frankfurt and Düsseldorf building material distributors now require environmental product declaration documentation.
China
GB standards under SAMR jurisdiction increasingly reference EU migration test protocols for plastic food-contact materials. Mechanical recycling capacity expansion in the Yangtze River Delta accelerates antioxidant masterbatch demand to restore thermal stability in post-consumer feedstocks. Shanghai and Ningbo processors scale compounding operations for export-oriented consumer goods.
Vietnam
Flexible film converters in Ho Chi Minh City and Hanoi expand masterbatch procurement to serve multinational brand owners relocating sourcing from China amid tariff diversification strategies. Export-oriented packaging clusters concentrate procurement among technical compounders capable of FDA and EU 10/2011 compliance. Domestic plastics processing capacity scales for regional consumer goods manufacturing.
Indonesia
Household product and personal care packaging manufacturers in Jakarta and Surabaya remain underpenetrated by technical masterbatch suppliers capable of matching Japanese automotive-grade specifications. The domestic market offers expansion opportunity for compounders with specialty additive portfolios. Regional processing clusters scale capacity for ASEAN consumer goods distribution.
Global Masterbatch Market Competitive Environment
Player mix skews toward backward-integrated resin producers and specialty compounders with regulatory laboratory infrastructure. The vendor base separates into volume-driven commodity suppliers and specification-grade technical specialists. Three archetypes dominate: polyolefin resin majors with captive compounding operations, independent color specialists with custom formulation services, and additive-focused compounders serving recycled-content processing. Competitive moves concentrate on geographic expansion into Southeast Asian packaging clusters and portfolio diversification toward thermal-management compounds for electric vehicle applications.
Among European-headquartered specialists, Clariant and Kafrit Group exemplify the regulatory-intensive tier, occupying positions where REACH compliance and food-contact certification capabilities determine contract access. LyondellBasell Industries anchors the resin-integrated archetype, with backward integration into polypropylene resin supply creating structural advantages in carrier resin availability. These three represent distinct competitive positions: specialty additive expertise, independent technical compounding, and upstream resin control.
| Leading Market Players |
|---|
| Clariant |
| LyondellBasell Industries |
| Avient Corporation |
| Kafrit Group |
| Plastika Kritis S.A. |
| Ampacet Corporation |
| Tosaf Compounds Ltd. |
| Penn Color Inc. |
| Cabot Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-day pigment inventory cycles concentrate pricing leverage with Middle Eastern polypropylene resin producers who anchor carrier resin supply. This lead-time structure forces compounders to absorb titanium dioxide volatility or risk contract defaults with flexible film converters in Vietnam and Indonesia.
Pricing Analysis
Commodity carbon black formulations trade at legacy-generation discounts while laser-markable perylene pigment systems command next-generation premiums. Three-tier pricing structure across REACH-certified specialty, FDA-notified standard, and economy-grade uncertified tiers separates contract access. Price differentiation hinges on migration testing documentation and backward integration into resin supply. Pricing pressure stems from ilmenite ore cost spikes in South African mining regions. Brand-owner procurement teams in Chicago and Toronto metropolitan clusters exhibit lowest price sensitivity due to multi-jurisdiction compliance requirements.
Supply Chain Analysis
Just-in-time resin procurement dominates among Southeast Asian flexible film converters while European compounders maintain strategic stockpiles of titanium dioxide and antioxidant additives. Raw material sourcing draws from Saudi Arabian and North American ethylene crackers for polypropylene carriers, Chinese ilmenite processing for white pigments, and German specialty chemical production for laser-markable additives. Single-source vulnerability concentrates in Middle Eastern resin supply when regional crackers undergo unplanned maintenance. Distribution runs through regional compounding facilities co-located with plastics processing clusters in Ho Chi Minh City, Jakarta, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brand-owner consolidation across North American food packaging has shifted procurement leverage toward buyers capable of mandating integrated color-matching services and inventory management programs.
For Market Incumbents: Compound regulatory laboratory capabilities to defend against specialty additive entrants capturing electric vehicle thermal-management contracts. Deepen backward integration into polypropylene resin supply to offset Middle Eastern feedstock concentration risk. Prioritize certification investment for EU 10/2011 and FDA food-contact notification to maintain access to Chicago and Toronto metropolitan packaging headquarters. For New Entrants and Emerging Players: Lead with near-infrared sorting compatible black masterbatch formulations to capture extended-producer-responsibility value in France and Germany recycling streams. Target Indonesia's household product and personal care packaging segment where technical suppliers capable of Japanese automotive-grade specifications remain scarce. Deploy rapid-turnaround color-matching services as the primary go-to-market angle against incumbent commodity suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capability consolidation play because REACH compliance and multi-jurisdiction food-contact certification create durable moats against commodity entrants. Acquisition candidates center on independent compounders with in-house migration testing laboratories and established FDA notification track records. Watch for inflection when extended-producer-responsibility mandates in European Union member states accelerate demand for recyclable-design masterbatches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | LyondellBasell Industries anchors global volume through captive carrier resin supply. |
| Regulatory Laboratory Investment | Clariant captures battery housing contracts via REACH-compliant thermal-management compounds. |
| Near-Infrared Sorting Formulation Development | Perylene-based black masterbatches enable automated recycling identification in Germany. |
| Indonesia Manufacturing Footprint Expansion | Technical suppliers penetrate underpenetrated personal care packaging in Jakarta and Surabaya. |
| Biopolymer Carrier System Certification | Polylactic acid masterbatches qualify for TÜV Austria OK Compost HOME standards. |
Study Parameters
A standing panel of masterbatch plant managers, procurement leads at flexible film converters, distribution channel partners, and technical R&D directors provided ongoing calibration across the study period. Primary interview data triangulated against customs and trade records, American Chemistry Council and Cefic industry reports, SEC 10-K filings from resin-integrated compounders, and SAMR GB standard documentation. Bottom-up volume estimates from individual production facilities reconciled with top-down demand modeling across polymer processing methods.
Consistency checks validated volume and value outputs against external benchmarks including regional plastics processing capacity data and pigment import statistics. The analytical framework modeled masterbatch demand across product type, carrier resin grade, end-use industry, and regional production hub throughout the forecast period. CAGRs derived from segment-level growth trajectories incorporating electric vehicle platform adoption curves, recycled-content resin processing expansion, and Southeast Asian packaging cluster buildout.
Forecasts assume regulatory continuity in EU REACH, FDA food-contact notification, and China SAMR GB standards; material policy shifts would require re-modeling additive migration limits and heavy-metal pigment restrictions. Revision becomes warranted when titanium dioxide feedstock disruptions or unplanned ethylene cracker maintenance crosses thresholds that fragment carrier resin supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market