
 CBRN Protection Equipment Market | 2026-2036
CBRN Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
CBRN Protection Equipment Market Outlook
Emergency services procurement is recalibrating toward multi-threat protective ensembles that bridge chemical and biological defense. Honeywell International Inc. leverages its filtration engineering heritage to anchor government contract positions across North America. Drägerwerk AG & Co. KGaA sustains dominance in European respiratory protection through manufacturing scale and Bundeswehr supply relationships. Rheinmetall Defence competes on integrated system architectures that combine detection with individual protection for military end users.
CBRN protection equipment encompasses garments, respiratory devices, detection instruments, and decontamination apparatus engineered to shield personnel from chemical, biological, radiological, and nuclear agents, typically incorporating activated carbon layers, selective permeable membranes, or positive-pressure airflow systems rated against NATO AEP-45 standards. The equipment serves military, first responder, and industrial facilities where accidental or intentional agent release threatens operational continuity. Respirators and tactical suits command the largest value share given recurring replacement cycles and stringent shelf-life protocols, while detection equipment registers the fastest structural expansion as sensor miniaturization enables networked perimeter monitoring. Electronics integration across filtration and sensor platforms is reshaping procurement specifications, with biodegradability emerging as a secondary materials criterion for decontamination consumables.
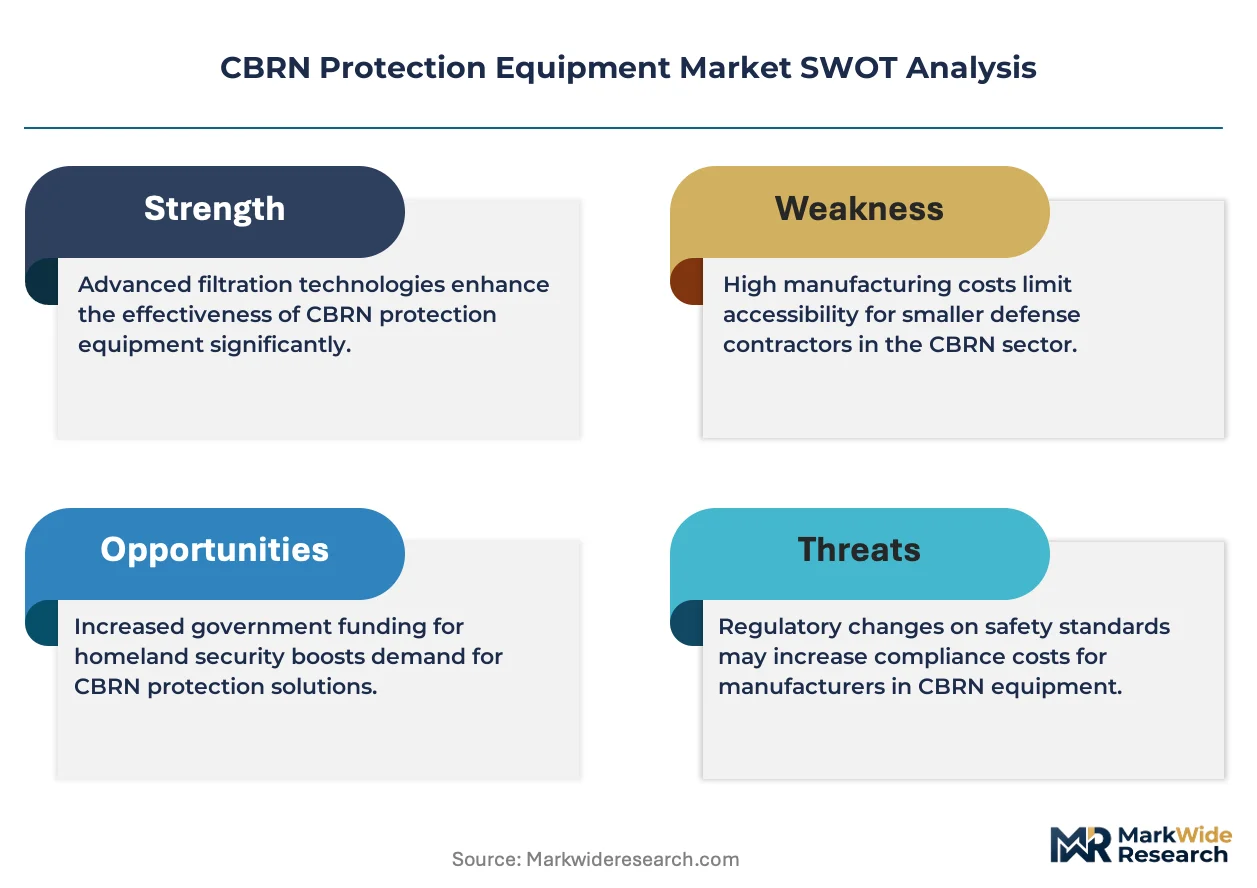
The EU Green Deal's chemical hazard provisions intersect with REACH substance restrictions to elevate barrier material compliance costs for manufacturers serving European defense ministries. The US EPA and OSHA jointly govern civilian industrial CBRN preparedness through facility risk management mandates that sustain aftermarket demand for detection and respiratory equipment. NATO standardization agreements on interoperability requirements directly influence product development roadmaps for cross-border military procurement. Stakeholders must monitor how evolving AI Act provisions on autonomous sensor networks reshape electronics integration strategies without compromising electromagnetic compatibility certifications.
Market Dynamics
Electronics integration across filtration and sensor platforms is compressing development cycles while NATO AEP-45 interoperability mandates force architecture standardization that favors systems-level suppliers over component specialists.
Growth Catalysts
- NATO Standardization Agreements:Cross-border military procurement frameworks require interoperable protective systems, creating pull-through demand for certified equipment across allied defense ministries.
- REACH substance restrictions:The EU's evolving chemical hazard provisions under the Green Deal accelerate R&D investment in barrier materials that satisfy dual environmental and agent-protection performance criteria.
- Sensor miniaturization:Networked perimeter monitoring capabilities expand addressable applications beyond individual protection into facility-scale detection architectures.
Market Restraints
- Activated carbon supply concentration:Specialized filtration media production clusters in limited geographic zones, exposing manufacturers to input cost volatility and single-source risk.
- EU AI Act electromagnetic compatibility requirements:Provisions governing autonomous sensor networks create certification friction for electronics-integrated platforms without established compliance pathways.
- Extended replacement cycles:Stringent shelf-life protocols for tactical suits and respirators compress recurring revenue windows relative to detection equipment categories.
Strategic Opportunities
- Biodegradable decontamination consumables:Secondary materials criteria emerging in European defense procurement specifications create first-mover advantage for formulation innovators.
- Industrial facility risk management mandates:Joint EPA-OSHA governance of civilian CBRN preparedness sustains aftermarket demand outside military procurement cycles.
- AI-enabled threat classification:Convergence of machine learning with spectral analysis is opening specification windows for upgraded detection platforms in critical infrastructure protection.
Industry Challenges
- Electromagnetic compatibility certification:Integrating smart sensors with legacy filtration hardware without compromising NATO AEP-45 ratings demands specialized engineering talent scarce across the supplier base.
- Dual-use export control alignment:Reconciling national defense procurement requirements with Wassenaar Arrangement restrictions complicates cross-border supply chain configuration for integrated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBRN Protection Equipment Market |
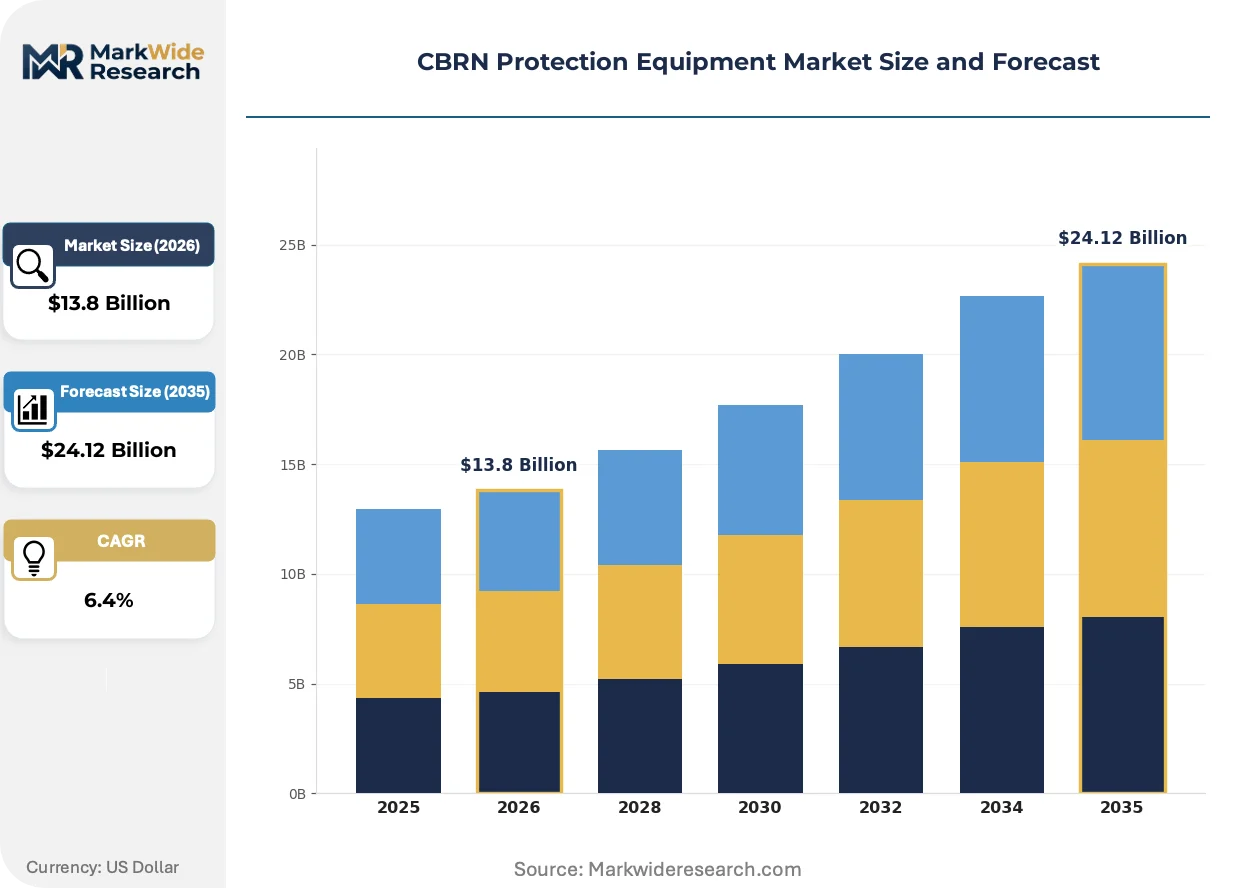
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tactical Suits, Respirators, Detection Equipment, Decontamination Units End User: Military, Emergency Services, Industrial, Government Agencies Technology: Filtration Systems, Sensor Technology, Biodegradable Materials, Electronics Integration Deployment: On-site Treatment, Stockpiling, Mobile Units, Perimeter Security |
| Companies Covered | 3M, Honeywell International Inc., Ansell Ltd, AirBoss of America Corp, Drägerwerk AG & Co. KGaA, MSA Safety Inc, Avon Protection Systems, Thales Group, Rheinmetall Defence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBRN Protection Equipment Market Strategic Shifts
Platform architectures are fragmenting into configurable subsystems that permit threat-specific reconfiguration without full ensemble replacement, compressing total cost of ownership calculations for procurement officers.
Membrane-based selective permeable barriers are modularizing protective garment construction. German and French defense modernization programs are adopting these platforms for chemical-biological defense bridging. This modularity is compressing inventory requirements while enabling mission-tailored protection profiles.
The EU AI Act's provisions on autonomous sensor networks are tightening electromagnetic compatibility certification timelines. Manufacturers serving European defense ministries must revalidate electronics integration strategies. Detection equipment categories face the steepest compliance cost escalation as networked perimeter systems proliferate.
Consolidated contracting vehicles are displacing discrete equipment purchases in NATO member procurement. Military end-users now specify integrated detection-protection-decontamination systems through single-source awards. This concentration is most visible in Bundeswehr and British Army modernization programs where platform-level accountability supersedes component sourcing.
CBRN Protection Equipment Market Segmentation
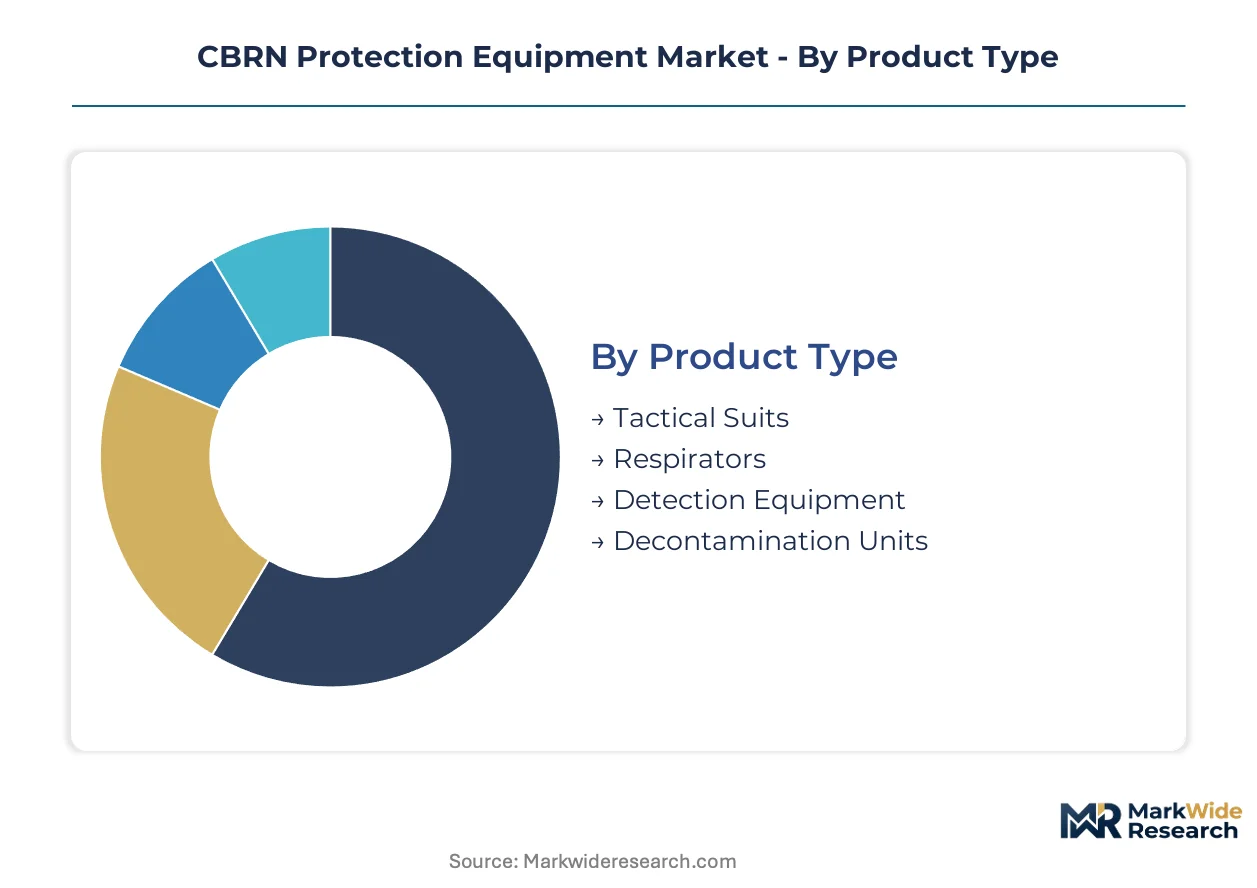
CBRN protection equipment procurement decisions hinge on threat-specific performance requirements, shelf-life economics, and interoperability mandates. Segment boundaries blur as platform-level contracts replace discrete equipment purchases. Understanding capital allocation across product categories and deployment modes reveals where procurement officers concentrate budget authority.
Product Type:
Capital intensity peaks in integrated system architectures that combine detection with individual protection, while consumable filtration media require lighter fixed asset bases but carry recurring working capital demands.
- Tactical Suits:Multi-layer ensembles incorporating activated carbon laminates and selective permeable membranes rated to NATO AEP-45 standards. German and French defense modernization programs are driving specification upgrades toward chemical-biological bridging capabilities. Replacement cycles compress revenue windows due to stringent shelf-life protocols.
- Respirators:Positive-pressure airflow systems and negative-pressure half-mask configurations utilizing specialized filtration cartridges. Demand concentrates in Bundeswehr resupply contracts and British Army procurement frameworks where interoperability certification is mandatory. REACH substance restrictions under the EU Green Deal are elevating barrier material compliance costs.
- Detection Equipment:Spectral analysis instruments and networked sensor platforms for agent identification.
- Decontamination Units:Mobile and fixed-site apparatus for personnel and equipment cleansing operations.
Most installed capacity flows through Respirators. Expansion is steepest in Detection Equipment.
End User:
Volume concentration varies sharply by procurement mechanism — military integrated system contracts dwarf discrete industrial purchases in per-transaction value, though industrial aftermarket frequency sustains steady demand baselines.
- Military:Integrated detection-protection-decontamination system procurement through consolidated contracting vehicles. NATO standardization agreements on interoperability requirements directly influence product development roadmaps. Single-source awards in Bundeswehr and British Army programs concentrate supplier relationships.
- Emergency Services:Multi-threat protective ensembles bridging chemical and biological defense for first responder deployment. Procurement is recalibrating toward configurable subsystems that permit threat-specific reconfiguration without full ensemble replacement.
- Industrial:Facility-scale detection and respiratory protection governed by joint EPA-OSHA risk management mandates.
- Government Agencies:Strategic stockpiling and critical infrastructure protection programs.
Contract value aggregates heaviest in Military. Procurement frequency runs highest in Emergency Services.
Technology:
Margin profiles diverge between mature filtration engineering and emerging electronics integration, where AI-enabled threat classification commands specification premiums.
- Filtration Systems:Activated carbon layers and selective permeable membranes engineered for agent-specific adsorption and permeation resistance. Production clusters in limited geographic zones expose manufacturers to input cost volatility.
- Sensor Technology:Miniaturized spectral analysis and networked perimeter monitoring capabilities. EU AI Act provisions on autonomous sensor networks are tightening electromagnetic compatibility certification timelines for European defense ministry suppliers.
- Biodegradable Materials:Decontamination consumables meeting secondary materials criteria in emerging European defense procurement specifications.
- Electronics Integration:Smart sensor fusion with legacy filtration hardware.
Revenue stability characterizes Filtration Systems. Technology investment concentrates in Sensor Technology.
Deployment:
Fixed asset requirements scale with system permanence — stockpiling demands warehousing infrastructure, while mobile units prioritize rapid deployment logistics over capital intensity.
- On-site Treatment:Fixed decontamination infrastructure integrated into military installations and critical facilities. German defense modernization programs emphasize hardened on-site capabilities.
- Stockpiling:Strategic reserves of respirators, suits, and detection consumables maintained by defense ministries and emergency management agencies. Shelf-life protocols drive recurring replacement procurement.
- Mobile Units:Rapidly deployable detection and decontamination platforms for incident response.
- Perimeter Security:Networked sensor arrays for facility-scale agent monitoring.
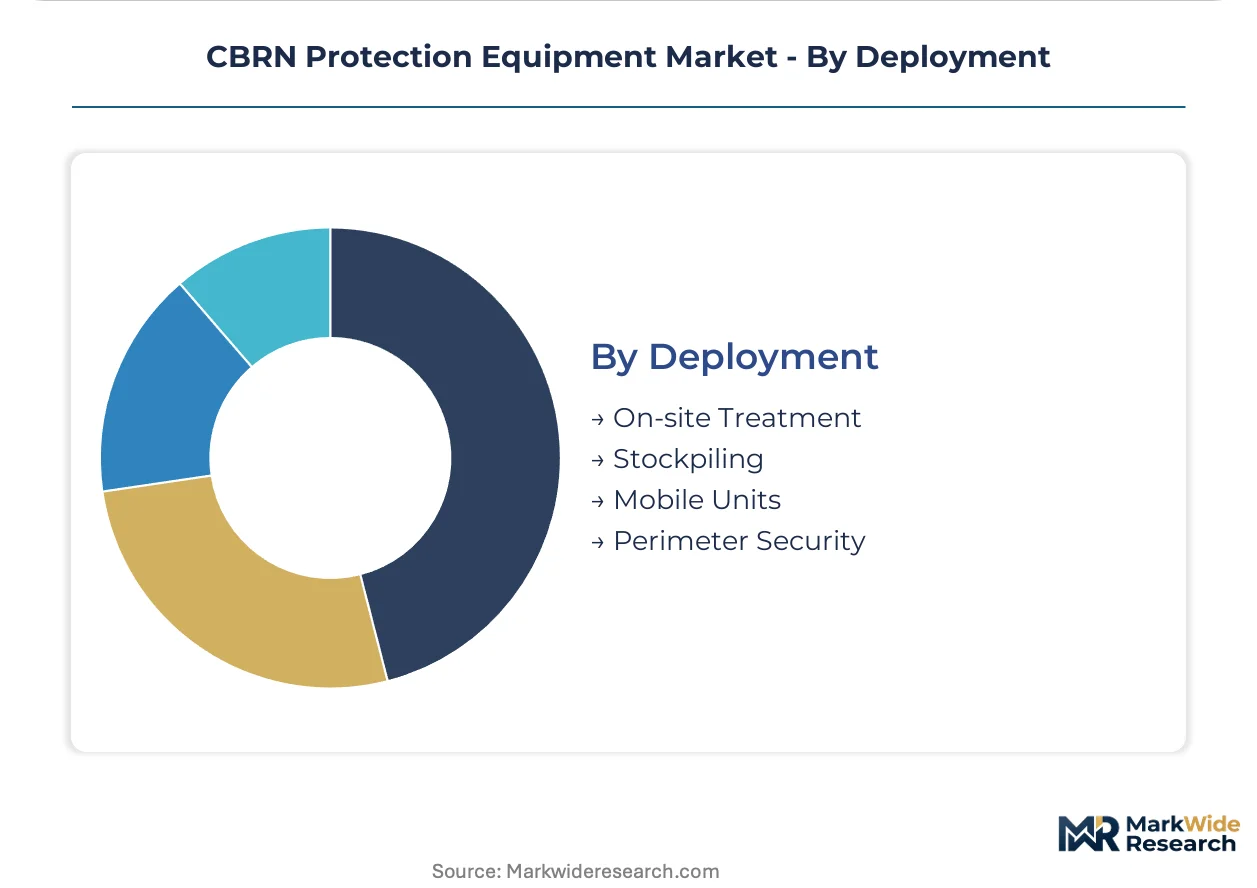
Inventory value accumulates in Stockpiling. Capability investment is accelerating in Perimeter Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined defense procurement certification, exploiting cost-of-compliance gaps between REACH-regulated European markets and alternative supply bases.
United States
Joint EPA-OSHA facility risk management mandates sustain aftermarket demand for detection and respiratory equipment across industrial installations. The Department of Defense drives integrated system procurement through consolidated contracting vehicles. Defense contractors cluster around Washington DC and Huntsville, Alabama, where CBRN readiness programs anchor specialized manufacturing capacity.
Germany
Bundeswehr modernization programs emphasize chemical-biological bridging capabilities in protective ensembles. REACH substance restrictions under the EU Green Deal elevate barrier material compliance costs for domestic manufacturers. Industrial concentration centers on Lübeck and Mülheim, where respiratory protection specialists maintain Bundeswehr supply relationships and filtration engineering heritage.
France
The ANSM enforces tightened certification timelines for respirator manufacturers under Chemical Weapons Convention implementation directives. Defense procurement specifies integrated detection-protection-decontamination systems through single-source awards. The Île-de-France region hosts system integrators serving NATO interoperability requirements, while Provence-Alpes-Côte d'Azur concentrates decontamination platform development.
United Kingdom
British Army procurement frameworks mandate interoperability certification for cross-border military equipment. The Health and Safety Executive governs civilian industrial preparedness through facility risk assessment protocols. Greater Manchester and the Midlands host protective equipment specialists aligned with NATO AEP-45 standardization agreements.
Italy
Emergency services procurement is recalibrating toward configurable subsystems for threat-specific reconfiguration. CE marking requirements intersect with defense ministry specifications for dual-use equipment. Lombardy anchors filtration component manufacturing, while Lazio concentrates government agency stockpiling operations for strategic reserves.
CBRN Protection Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with systems-level suppliers capturing consolidated military awards while component specialists serve industrial aftermarket channels. The supplier base organizes into three strategic archetypes: integrated platform architects, filtration engineering heritage houses, and detection technology innovators. Dominant competitive moves include backward integration into specialized filtration media production and strategic partnerships bridging hardware with AI-enabled threat classification software.
Within the integrated platform tier, Rheinmetall Defence and Thales Group exemplify systems-level accountability that supersedes component sourcing in NATO procurement. Honeywell International Inc. anchors the filtration engineering heritage archetype through government contract positions. Drägerwerk AG & Co. KGaA occupies a distinctive position linking respiratory protection manufacturing scale with European defense ministry relationships.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Ansell Ltd |
| AirBoss of America Corp |
| Drägerwerk AG & Co. KGaA |
| MSA Safety Inc |
| Avon Protection Systems |
| Thales Group |
| Rheinmetall Defence |
| Others |
Value Chain & Pricing Dynamics
Bundeswehr and British Army consolidated contracting vehicles concentrate procurement authority among systems-level suppliers, anchoring contract-based long-term offtake pricing with volume-scale discounts and NATO AEP-45 certification premiums. This buyer concentration compresses margins for component specialists while rewarding integrated platform architects with pricing power tied to single-source accountability.
Pricing Analysis
Distributor margins for respiratory protection equipment typically run 12-18% in European defense channels, while direct-to-military awards command 8-12% discounts reflecting procurement scale and bundling with detection systems. Three-tier pricing structure across NATO-certified premium, national-standard mid-tier, and economy respirator levels differentiates by electromagnetic compatibility grade and shelf-life protocol. Pricing pressure stems from REACH substance restrictions elevating barrier material compliance costs for manufacturers serving EU defense ministries. Industrial facility buyers exhibit highest price sensitivity due to joint EPA-OSHA risk management mandates driving commoditized respiratory procurement, while military end-users prioritize interoperability certification over unit cost.
Supply Chain Analysis
Freight costs for activated carbon filtration media have escalated as production clusters concentrate in Germany, the United States, and Japan, with specialized carbonization facilities tethered to coal tar pitch and coconut shell feedstock regions. Raw material dependencies center on activated carbon laminates, selective permeable membranes, and miniaturized spectral sensors drawing from semiconductor supply chains. Single-source vulnerability in coconut shell activated carbon exposes manufacturers to tropical weather disruption and agricultural commodity cycles. Distribution runs through defense procurement agencies and industrial safety distributors, with consolidated military awards bypassing traditional channel layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in CBRN protection equipment rests on biodegradable decontamination consumables capturing specification premiums and sensor miniaturization reducing per-unit electronics costs across networked perimeter deployments.
For Market Incumbents: Cement Bundeswehr and British Army supply relationships through backward integration into specialized filtration media production, insulating against activated carbon supply concentration. Deepen NATO AEP-45 certification investment to defend against emerging sensor-technology entrants from semiconductor-adjacent suppliers. Prioritize electromagnetic compatibility pre-certification for EU AI Act compliance to accelerate European defense ministry revalidation timelines. For New Entrants and Emerging Players: Capture aftermarket demand in industrial facility risk management governed by EPA-OSHA mandates, where procurement frequency sustains steady baselines outside military consolidation. Target biodegradable decontamination consumables in German and French defense modernization programs, where secondary materials criteria create first-mover specification windows. Lead with AI-enabled threat classification software partnerships rather than hardware manufacturing scale. For Investors and Strategic Acquirers: Defense contractors with CBRN readiness program mandates are the most active acquirer in this space, seeking detection-technology innovators to complete integrated system portfolios. Five-to-ten-year viability favors platform architects over component specialists as consolidated contracting vehicles displace discrete purchases. Monitor EU AI Act electromagnetic compatibility certification timeline compression as inflection indicator for electronics-integrated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Media | Captive activated carbon supply secures Bundeswehr contract positions against input volatility. |
| AI-Enabled Threat Classification Partnership | Machine learning spectral analysis opens specification windows in critical infrastructure protection. |
| Biodegradable Decontamination Formulation | EU Green Deal secondary materials criteria create premium tier in European defense procurement. |
| Electromagnetic Compatibility Pre-Certification | EU AI Act compliance acceleration differentiates detection platforms for ANSM-regulated markets. |
| Consolidated System Contracting Vehicle | Single-source detection-protection-decontamination awards concentrate supplier relationships in NATO procurement. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific defense procurement jurisdictions, with primary inputs from each region combined with secondary validation. Defense procurement officers, respiratory protection R&D directors, filtration media plant managers, and industrial safety distributors provided structured inputs. Secondary sources include NATO standardization agreement documentation, EPA facility risk management filings, ECHA REACH substance restriction updates, and customs trade data for activated carbon imports. Bottom-up equipment shipment data triangulates against top-down defense budget allocation analysis.
Rate-of-change decomposition separates volume growth from specification upgrade pricing effects across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, and deployment mode, with additional granularity on NATO interoperability certification tier and national defense modernization program alignment. CAGRs derive from equipment replacement cycle analysis, procurement pipeline tracking, and threat environment scenario weighting. Forecast inputs incorporate sensor miniaturization cost curves and REACH compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; detection equipment carries tighter precision than decontamination consumables due to consolidated contracting visibility. Forecasts reflect documented assumptions on NATO procurement continuity, EU regulatory stability, and activated carbon supply geography. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Global Armor Materials Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Aircraft Carrier Arresting Systems Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
Manpack Military Antennas Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Rocket Solid Propulsion Market