
 All-In-One Solar Storage Battery Market | 2026-2036
All-In-One Solar Storage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
All-In-One Solar Storage Battery Market Insights
Residential homeowners are redrawing the customer map for all-in-one solar storage batteries as commercial developers lose relative share. Tesla leverages its Supercharger ecosystem and software stack to anchor premium residential installations across California and Texas. LG Energy Solution sustains manufacturing scale through dedicated lithium-ion cell lines in Michigan and Poland. BYD competes on integrated photovoltaic-plus-battery system costs, extending its dominance in utility-scale deployments into residential channels.
An all-in-one solar storage battery combines photovoltaic input management, DC-AC inversion, battery cells, and energy management software within a single enclosure, typically rated between 5 kWh and 20 kWh usable capacity with 6,000-plus cycle life at 80 percent depth of discharge. Its primary purpose is to store daytime solar generation for evening self-consumption, peak shaving, or backup power during grid outages. Lithium-ion systems occupy the dominant margin pool as nickel manganese cobalt and lithium iron phosphate chemistries mature, while flow batteries remain confined to commercial and utility installations where extended duration discharge matters more than capital cost. The residential end-user segment leads volume growth as homeowners seek energy independence, though utilities represent the largest absolute capacity deployment through grid-tied hybrid installations.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection rules that determine payback periods for residential storage paired with rooftop solar. Europe's F-Gas Regulation and CE marking requirements under the EU Battery Directive impose material disclosure and recyclability standards that filter non-compliant suppliers from the market. China's GB standards and dual carbon goals from the Ministry of Ecology and Environment accelerate domestic lithium-ion production while restricting lead acid alternatives in new construction. Stakeholders must monitor how evolving net metering tariffs and time-of-use rate structures reshape the economic case for behind-the-meter storage against front-of-the-meter alternatives.
Market Dynamics
Lithium iron phosphate cell chemistry improvements are compressing footprint requirements while extending cycle life, fundamentally altering the economics of residential installations and displacing earlier nickel manganese cobalt configurations in suburban North American deployments.
Growth Catalysts
- Net metering reforms:The US Federal Energy Regulatory Commission and state-level public utility commissions are accelerating payback calculations for behind-the-meter storage paired with rooftop solar.
- Grid instability concerns:Homeowners in Germany, Australia, and the United States are prioritizing backup power resilience amid increasing weather-related outages and aging transmission infrastructure.
- Suburban homeowner demand:Residential end-users in North American suburbs are replacing early commercial adopters as the fastest-expanding buyer cohort for integrated photovoltaic-plus-battery systems.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for lithium iron phosphate cells fluctuate with Chinese mining output and refining capacity constraints.
- Supply concentration risk:Cell manufacturing and cathode precursor processing concentrate in China's Jiangsu and Fujian provinces, creating single-source dependencies.
- Interconnection queue delays:US state public utility commission backlogs extend project commissioning timelines for grid-tied residential installations.
Strategic Opportunities
- Underpenetrated Australian regions:Queensland and Western Australia exhibit low solar-plus-storage penetration relative to South Australia despite comparable irradiance profiles.
- Virtual power plant aggregation:Utilities in California and Texas are enrolling residential battery fleets into grid services markets through software-enabled dispatch contracts.
- EU Battery Directive compliance:Material disclosure and recyclability standards under Europe's regulatory framework filter non-compliant suppliers and create first-mover advantages for certified manufacturers.
Industry Challenges
- Electrochemical engineering talent scarcity:Battery management system firmware development and thermal runaway mitigation expertise outpaces university program output.
- CE marking certification timelines:European conformity assessment procedures for lithium-ion energy storage systems extend product launch schedules.
- Legacy electrical contractor training gaps:Residential installers require re-certification for DC-coupled storage integration with existing photovoltaic arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-In-One Solar Storage Battery Market |
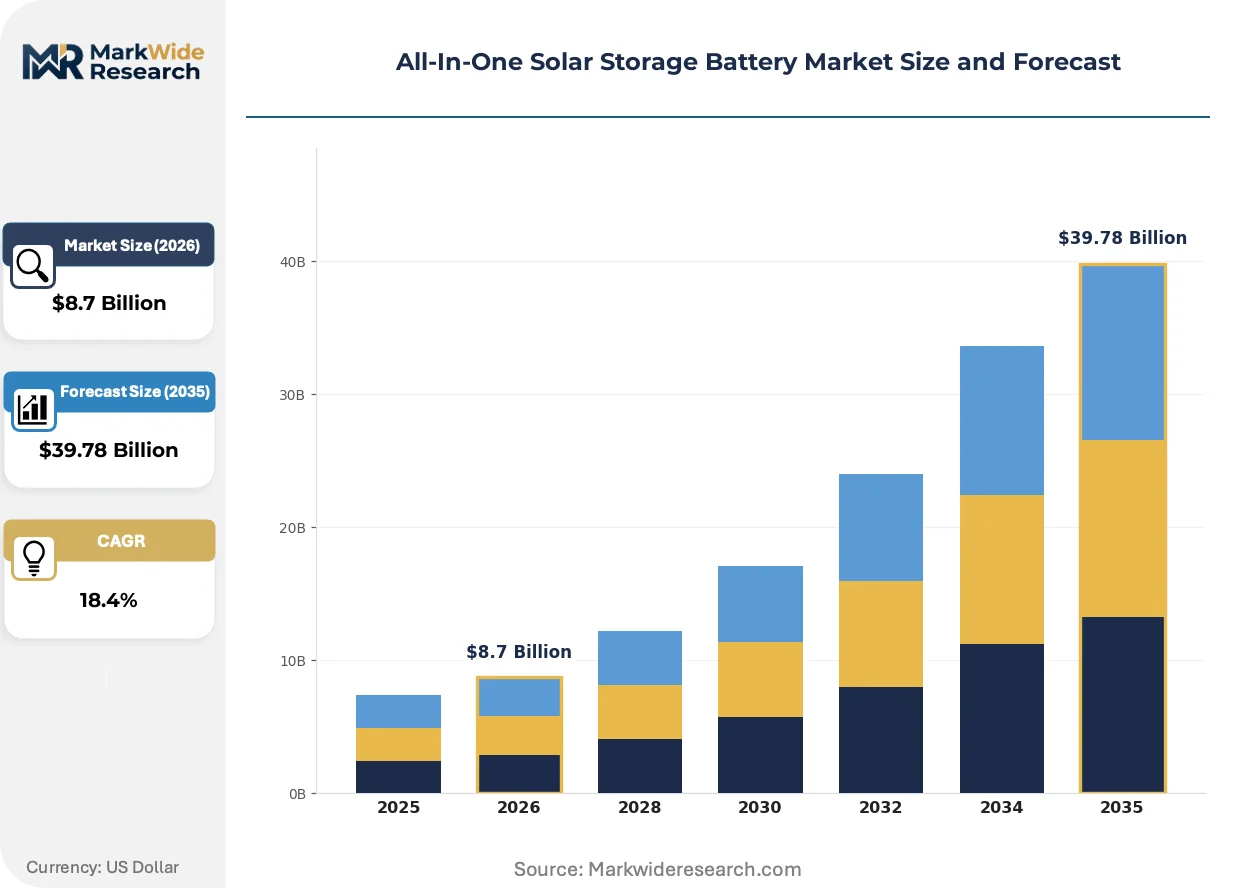
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-Ion, Flow Batteries, Nickel Cadmium End User: Residential, Commercial, Industrial, Utilities Installation: Grid-Tied, Off-Grid, Hybrid, Portable Capacity: 1 kWh, 5 kWh, 10 kWh, 20 kWh |
| Companies Covered | Tesla, LG Energy Solution, Sonnen, Huawei, BYD, Panasonic, SENEC, Enphase Energy, Pylontech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-In-One Solar Storage Battery Market Trends and Innovations
Software-defined energy management is displacing hardware-centric system architectures, enabling remote firmware updates and dynamic operating mode switching that reshape how residential batteries deliver value beyond kilowatt-hour storage capacity.
Lithium iron phosphate chemistry is bifurcating the residential storage market between premium long-cycle-life systems and cost-optimized alternatives. Suburban homeowners in California and Texas are adopting the chemistry for its thermal stability and extended warranty terms. The technology is bifurcating vendor strategies between integrated photovoltaic-plus-battery offerings and standalone retrofit units.
Europe's F-Gas Regulation is tightening refrigerant containment standards for thermal management subsystems within outdoor-rated battery enclosures. Manufacturers are redesigning cooling loops and sealing specifications to maintain CE marking eligibility. German and Polish assembly facilities are absorbing the compliance costs through dedicated production lines.
Homeowner procurement patterns are fragmenting across direct-to-consumer online channels, traditional electrical contractor networks, and solar installer bundling. The contractor channel is losing share to integrated rooftop solar vendors who package storage as a standard inclusion. This shift is most visible in suburban Texas markets where Tesla's direct sales model bypasses conventional distribution.
All-In-One Solar Storage Battery Market Segmentation
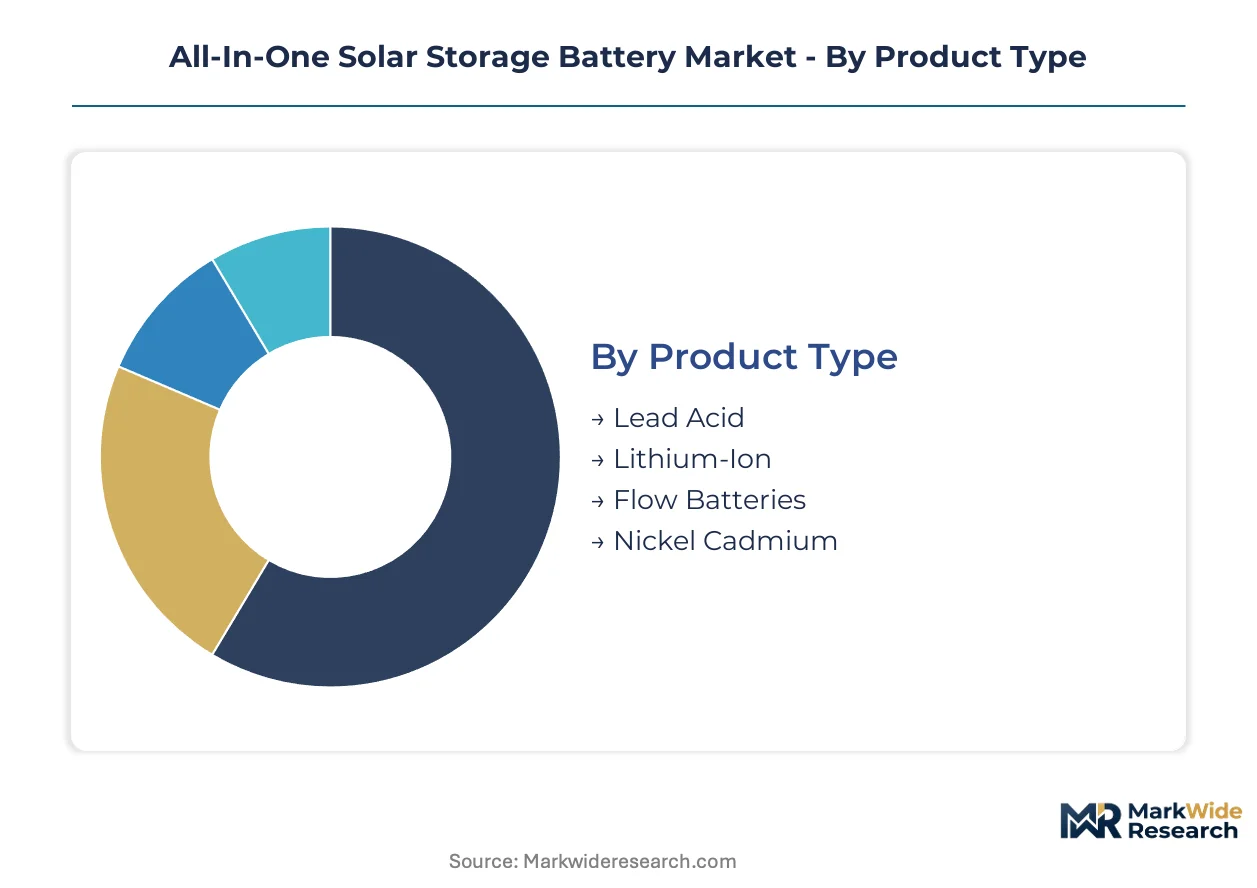
Segmentation in all-in-one solar storage batteries reveals how cell chemistry, deployment configuration, and customer scale interact with regulatory frameworks to determine margin pools and payback periods. Manufacturers align product architectures with specific interconnection rules and tariff structures rather than pursuing universal designs.
Product Type:
FERC interconnection standards and EU Battery Directive material disclosure requirements create divergent compliance burdens across electrochemical systems, filtering supplier participation by certification capacity.
- Lithium-Ion:Lithium iron phosphate and nickel manganese cobalt configurations dominate residential installations through 6,000-plus cycle life ratings and compact form factors. Suburban homeowners in Germany and Australia prioritize these systems for backup resilience amid net metering reforms and grid instability concerns.
- Flow Batteries:Vanadium redox and zinc-bromine systems enable extended duration discharge for commercial and utility installations where capital cost tolerance exceeds energy density requirements. Utilities in California and Texas deploy these for grid-scale hybrid installations where discharge duration outweighs footprint constraints.
- Lead Acid:Flooded and valve-regulated designs persist in cost-sensitive off-grid applications with lower cycle life requirements.
- Nickel Cadmium:Aerospace-derived chemistry occupies niche industrial backup roles requiring extreme temperature tolerance.
Established volume favors lithium-ion; emerging adoption favors flow batteries.
End User:
Customer scale determines software integration depth and grid services revenue potential, with residential fleets offering virtual power plant aggregation that utilities cannot replicate with centralized assets.
- Residential:Single-family homeowners in suburban North America drive procurement through direct-to-consumer channels and solar installer bundling. Tesla's Supercharger-integrated software stack and LG Energy Solution's Michigan-manufactured cell lines anchor premium positioning in California and Texas markets.
- Utilities:Grid-tied hybrid installations represent the largest absolute capacity deployment through front-of-the-meter procurement. China's dual carbon goals from the Ministry of Ecology and Environment accelerate domestic lithium-ion production for utility-scale absorption.
- Commercial:Behind-the-meter peak shaving for retail and office facilities with 50-500 kWh requirements.
- Industrial:Manufacturing facilities with high power quality demands and outage cost exposure.
Revenue concentration sits with utilities; margin expansion concentrates in residential.
Installation:
Grid interconnection architecture shapes inverter specifications and firmware capabilities, with hybrid systems commanding premium pricing for operating mode flexibility.
- Hybrid:Dual-mode systems switch between grid-tied export and islanded backup through software-defined energy management. Australian homeowners in Queensland and Western Australia adopt these for net metering optimization despite lower regional penetration rates.
- Grid-Tied:Export-focused configurations without backup capability dominate utility-scale and commercial deployments where outage resilience is not valued.
- Off-Grid:Standalone systems with dedicated solar arrays serve remote residential and agricultural applications.
- Portable:Mobile power stations for recreational and emergency use with sub-5 kWh capacities.
Deployment scale favors grid-tied; value capture is climbing fastest in hybrid.
Capacity:
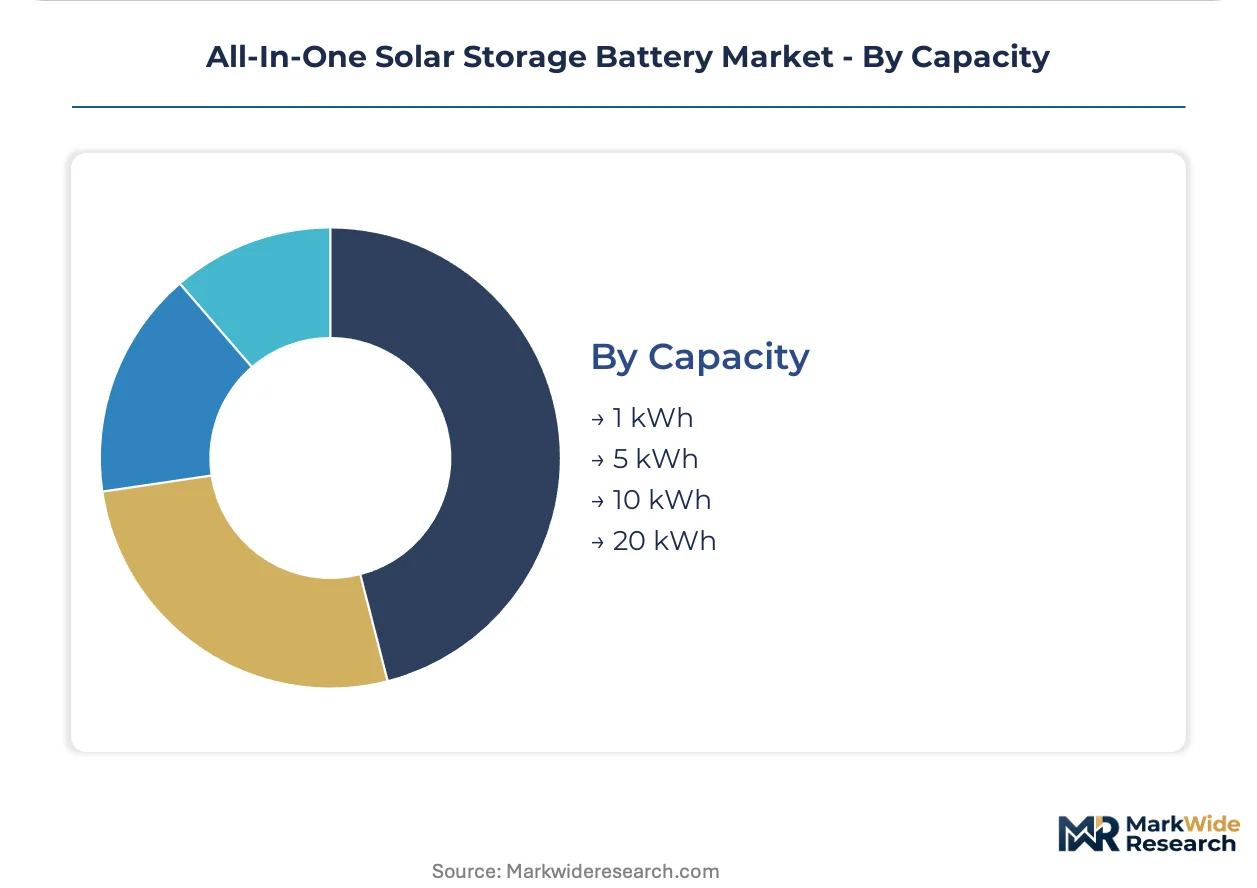
Kilowatt-hour ratings align with rooftop solar array sizing and household load profiles, with 10 kWh emerging as the suburban standard for evening self-consumption coverage.
- 10 kWh:Usable capacity rated for 80 percent depth of discharge matches typical suburban household evening loads across German and Australian deployments. CE marking certification timelines from European conformity assessment procedures filter non-compliant suppliers from this segment.
- 5 kWh:Entry-level systems for smaller homes and apartment installations with constrained roof space.
- 20 kWh:Premium tier for large homes with electric vehicle charging integration and extended backup requirements.
- 1 kWh:Supplementary capacity for portable applications and retrofit expansions.
Unit economics favor 10 kWh; steepest expansion trajectory appears in 20 kWh for electrified homes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban homeowners in the United States, Germany, and Australia now constitute the fastest-expanding buyer archetype for all-in-one solar storage batteries, displacing earlier commercial and utility-led procurement patterns that dominated market formation through the mid-2020s.
United States
Net metering reforms in California and Texas are compressing payback periods for behind-the-meter residential installations. FERC interconnection standards and state-level public utility commission rulings determine grid-tied system economics. Tesla's direct sales model bypasses conventional distribution channels across suburban Texas markets while LG Energy Solution operates dedicated lithium-ion cell lines in Michigan.
Germany
Grid instability concerns and aging transmission infrastructure accelerate homeowner demand for backup power resilience. The EU Battery Directive's material disclosure and recyclability standards under CE marking requirements filter non-compliant suppliers from market participation. Assembly facilities in Bavaria and North Rhine-Westphalia absorb compliance costs through dedicated lithium iron phosphate production lines.
Australia
Queensland and Western Australia exhibit low solar-plus-storage penetration relative to South Australia despite comparable irradiance profiles. State-level net metering optimization policies drive hybrid system adoption. Virtual power plant aggregation programs in Victoria and New South Wales enroll residential battery fleets into grid services markets through software-enabled dispatch contracts.
China
Dual carbon goals from the Ministry of Ecology and Environment accelerate domestic lithium-ion production while restricting lead acid alternatives in new construction. GB standards for energy storage systems shape product certification requirements. Manufacturing clusters in Jiangsu and Fujian provinces concentrate cell production and cathode precursor processing capacity.
All-In-One Solar Storage Battery Market Competitive Landscape
Player mix skews toward integrated energy conglomerates with captive cell manufacturing and software-defined energy management capabilities. Market structure concentrates around three to five vertically positioned suppliers controlling premium residential channels while mid-tier assemblers compete on system cost. Strategic archetypes include Supercharger-network-anchored ecosystem players, dedicated lithium-ion cell manufacturers with regional assembly footprints, and photovoltaic-plus-battery integrated system specialists. Dominant competitive moves encompass backward integration into cathode precursor processing and geographic expansion through certified regional assembly facilities.
Within the integrated ecosystem tier, Tesla leverages its Supercharger infrastructure and software stack to anchor premium residential positioning across California and Texas markets. LG Energy Solution sustains manufacturing scale through dedicated cell lines in Michigan and Poland, representing the dedicated cell manufacturer archetype. BYD competes on integrated photovoltaic-plus-battery system costs, extending its utility-scale dominance into residential channels as the integrated system specialist.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| Sonnen |
| Huawei |
| BYD |
| Panasonic |
| SENEC |
| Enphase Energy |
| Pylontech |
| Others |
Pricing and Supply Chain Analysis
CE marking certification timelines under Europe's F-Gas Regulation and EU Battery Directive gate supplier qualification while simultaneously stratifying price tiers, as manufacturers absorbing extended conformity assessment timelines capture premium positioning while uncertified competitors face exclusion from German and Australian procurement channels.
Pricing Analysis
Lithium iron phosphate systems command a 15-20% premium over prior-generation nickel manganese cobalt configurations, while next-generation solid-state prototypes remain pre-commercial. Pricing stratifies across premium, standard, and economy tiers based on cycle life warranty terms and software integration depth. Cost compression in the standard tier intensifies because BYD and Pylontech are scaling integrated photovoltaic-plus-battery production. Commercial installers exhibit the highest price sensitivity, while suburban homeowners in California and Texas prioritize thermal stability and extended warranty coverage over upfront system cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam and Shanghai-Los Angeles trade lanes elevate inbound logistics costs for European and North American assembly facilities. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode precursor processing anchored in China's Jiangsu and Fujian provinces. The industry draws from lithium carbonate, electrolyte solvents, and copper foil as critical inputs. Single-source vulnerability in Chinese refining capacity creates supply chain risk. Distribution runs through certified electrical contractor networks, direct-to-consumer online channels, and solar installer bundling partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The all-in-one solar storage battery market sits in early-cycle expansion as suburban homeowner penetration in North American, German, and Australian markets remains below saturation thresholds despite accelerating net metering reforms.
For Market Incumbents: Fortify manufacturing scale through captive lithium iron phosphate cell lines in Michigan and Poland, matching LG Energy Solution's regional assembly footprint. Deepen software-defined energy management capabilities to defend against Tesla's Supercharger-integrated ecosystem threat. Prioritize CE marking certification investment to maintain European market access amid tightening F-Gas Regulation compliance timelines.
For New Entrants and Emerging Players: Lead with underpenetrated Australian regions—Queensland and Western Australia—where solar irradiance matches South Australia but storage attachment rates lag significantly. Target hybrid system configurations for net metering optimization as the most penetrable product segment. Pursue virtual power plant aggregation partnerships with utilities in California and Texas as the primary go-to-market angle.
For Investors and Strategic Acquirers: FERC interconnection standard reforms reshape the acquisition landscape by accelerating payback calculations for behind-the-meter residential installations. Frame long-term viability around 5-10 year grid services revenue streams from software-enabled dispatch contracts. Target vertically positioned suppliers with certified regional assembly facilities and captive cell manufacturing. Watch state-level public utility commission rulings on time-of-use rate structures as the critical inflection signal for residential storage economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Processing | Captive supply of lithium iron phosphate materials reduces exposure to Chinese refining concentration in Jiangsu province. |
| Virtual Power Plant Software Platform Development | Enables utilities in Texas and California to monetize residential battery fleets through grid services dispatch contracts. |
| CE Marking Certification Acceleration | Maintains European market eligibility under tightening EU Battery Directive material disclosure and recyclability standards. |
| Regional Assembly Facility Expansion | Locates production in Michigan and Poland to satisfy domestic content preferences and shorten delivery timelines. |
| Direct-to-Consumer Channel Establishment | Bypasses traditional electrical contractor networks following Tesla's suburban Texas market penetration model. |
Research Methodology
The analysis maps lithium-ion, flow battery, and emerging solid-state sub-sectors, each validated through utility planning officers, residential solar installers, battery management system firmware engineers, and grid operator dispatch coordinators. Primary interviews with EPC contractors and IPP project developers combined with secondary validation from FERC filings, EIA storage deployment databases, IEA renewable integration reports, and state public utility commission interconnection queue data. Bottom-up unit economics modeling and top-down regulatory scenario analysis provide cross-verification.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models cell chemistry, installation architecture, end-user scale, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from installed base growth trajectories and replacement cycle assumptions. Forecast inputs include net metering tariff evolution, lithium carbonate price volatility scenarios, and interconnection approval timeline distributions.
The analysis sits within stated boundaries; outcomes outside sustained lithium iron phosphate cost reduction and stable FERC interconnection standard interpretation would require recalibration. Forecasts reflect documented assumptions regarding suburban homeowner adoption curves and utility-scale procurement continuity. Specific risk factors that could revise projections include Chinese mining export restrictions, CE marking timeline extensions, and state-level net metering policy reversals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Smart Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Low Temperature Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Europe Battery Cell Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Modular Battery Pack Market
Batteries
Solid-State Car Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
FORTELION Battery Module Market
Batteries
Yacht Battery Market
Batteries
Residential Battery Market
Batteries
North America Battery Market