
 Zinc Ion Batteries Market | 2026-2036
Zinc Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Ion Batteries Market Insights
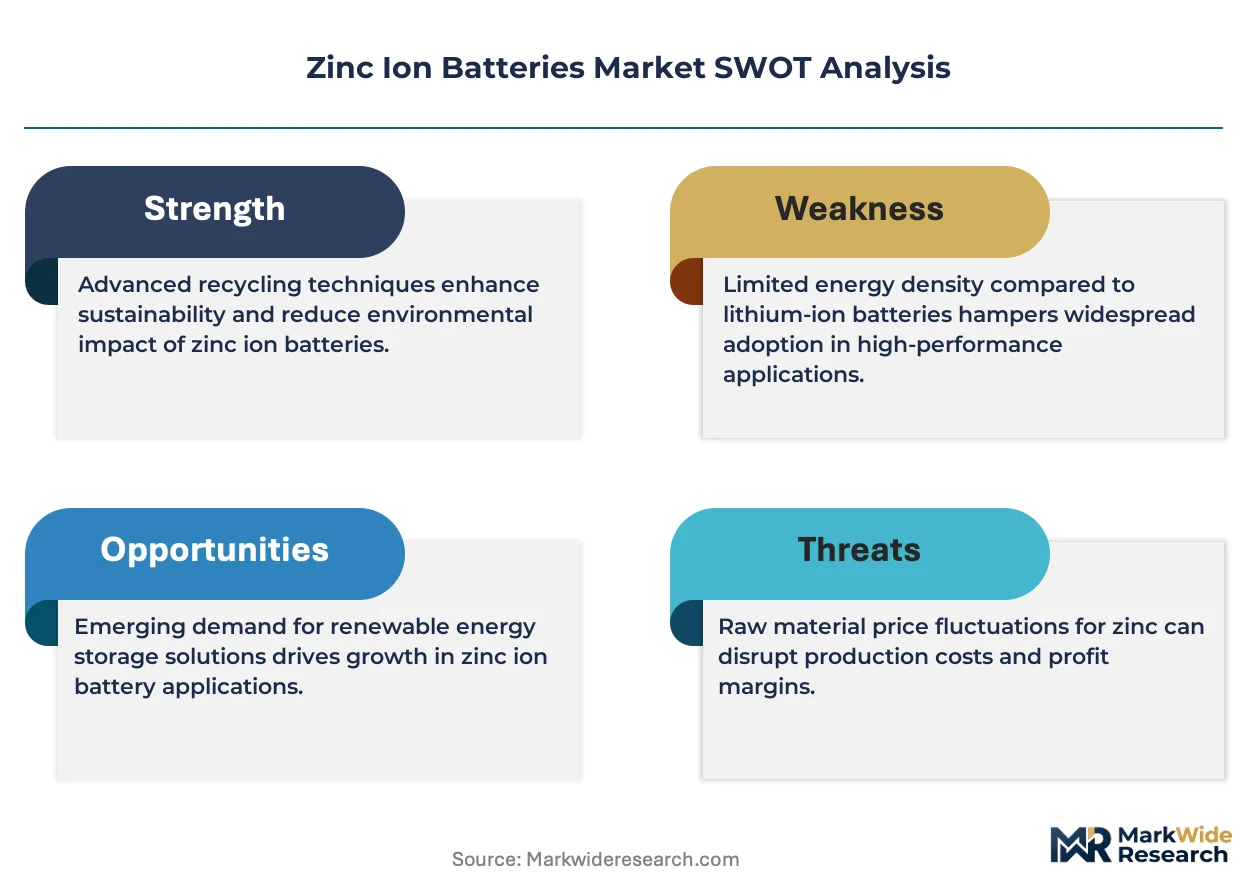
High-energy-density aqueous configurations is reorganizing competitive positioning in the zinc ion batteries space. ZincFive leverages vertical integration into nickel-zinc cell production to control cathode supply. Salient Energy anchors its position through R&D intensity in zinc-ion chemistry for residential storage. Enerpoly AB specializes in modular zinc-ion systems for commercial and industrial deployment.
Zinc ion batteries are rechargeable electrochemical cells employing zinc metal anodes paired with intercalation cathodes in mildly acidic or neutral aqueous electrolytes, typically delivering operating voltages between 1.6 and 2.0 volts with theoretical energy densities approaching 400 Wh/kg. Their primary commercial purpose centers on stationary energy storage and select mobility applications where safety, cost, and material abundance outweigh lithium-ion's gravimetric advantages. Rechargeable product types dominate current revenue pools given their suitability for daily cycling in grid storage and renewable energy end users, while solid-state technology variants represent the fastest-expanding segment as manufacturers seek to suppress dendrite formation and extend cycle life beyond ten thousand charge events.
The US EPA and FAA evaluate zinc-ion systems for stationary aviation backup and hazardous material transport classifications, shaping product certification pathways and deployment eligibility. China's SAMR enforces GB standards on electrochemical safety and recycling accountability, directly conditioning factory output for domestic and export markets. India's CEA and BIS are drafting performance benchmarks for non-lithium storage tied to renewable purchase obligations, creating incremental demand channels. Stakeholders must monitor how electrolyte chemistry patents and regional mineral processing subsidies redistribute manufacturing cost advantages across competing battery geographies.
Market Dynamics
Stationary energy storage operators are systematically replacing lithium-ion with aqueous zinc-ion systems, driven by China's dual carbon goals and stricter NMPA battery safety standards that favor non-flammable chemistries in grid-scale deployments.
Growth Catalysts
- China's dual carbon policy framework:National targets for carbon peak and neutrality are mandating domestic procurement of non-lithium storage, accelerating factory investments in aqueous zinc-ion production lines.
- Aviation backup power standards:The US FAA is evaluating zinc-ion systems for stationary aviation applications, creating a certification pathway that validates the chemistry for safety-critical infrastructure.
- Renewable purchase obligations:India's CEA is drafting storage mandates tied to solar and wind procurement, opening incremental demand channels for zinc-ion in grid balancing.
Market Restraints
- Zinc metal price volatility:Concentrated mining operations in Australia and Peru create input cost instability that compresses manufacturing margins during commodity spikes.
- Cathode material supply concentration:Manganese and vanadium processing clusters in South Africa and Russia expose cell producers to geopolitical supply disruptions.
- Energy density ceiling:Theoretical limits near 400 Wh/kg remain below lithium-ion performance, restricting zinc-ion to stationary applications where weight is non-critical.
Strategic Opportunities
- India's renewable storage mandates:Draft CEA regulations for non-lithium performance benchmarks create first-mover advantages for compliant zinc-ion suppliers.
- Solid-state electrolyte convergence:Integration of ceramic separators with aqueous zinc chemistry promises dendrite suppression beyond ten thousand cycles.
- Commercial and industrial direct sales:Bypassing traditional utility procurement channels through modular system offerings reduces customer acquisition costs.
Industry Challenges
- Electrolyte formulation expertise gap:Limited talent pools in mildly acidic aqueous chemistry constrain R&D velocity for next-generation cell designs.
- Multi-jurisdiction certification timelines:Sequential approvals from China's SAMR, US FAA, and EU battery directives extend product launch cycles.
- Legacy grid integration protocols:Existing inverter and energy management systems require firmware modifications to optimize zinc-ion charge profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Ion Batteries Market |
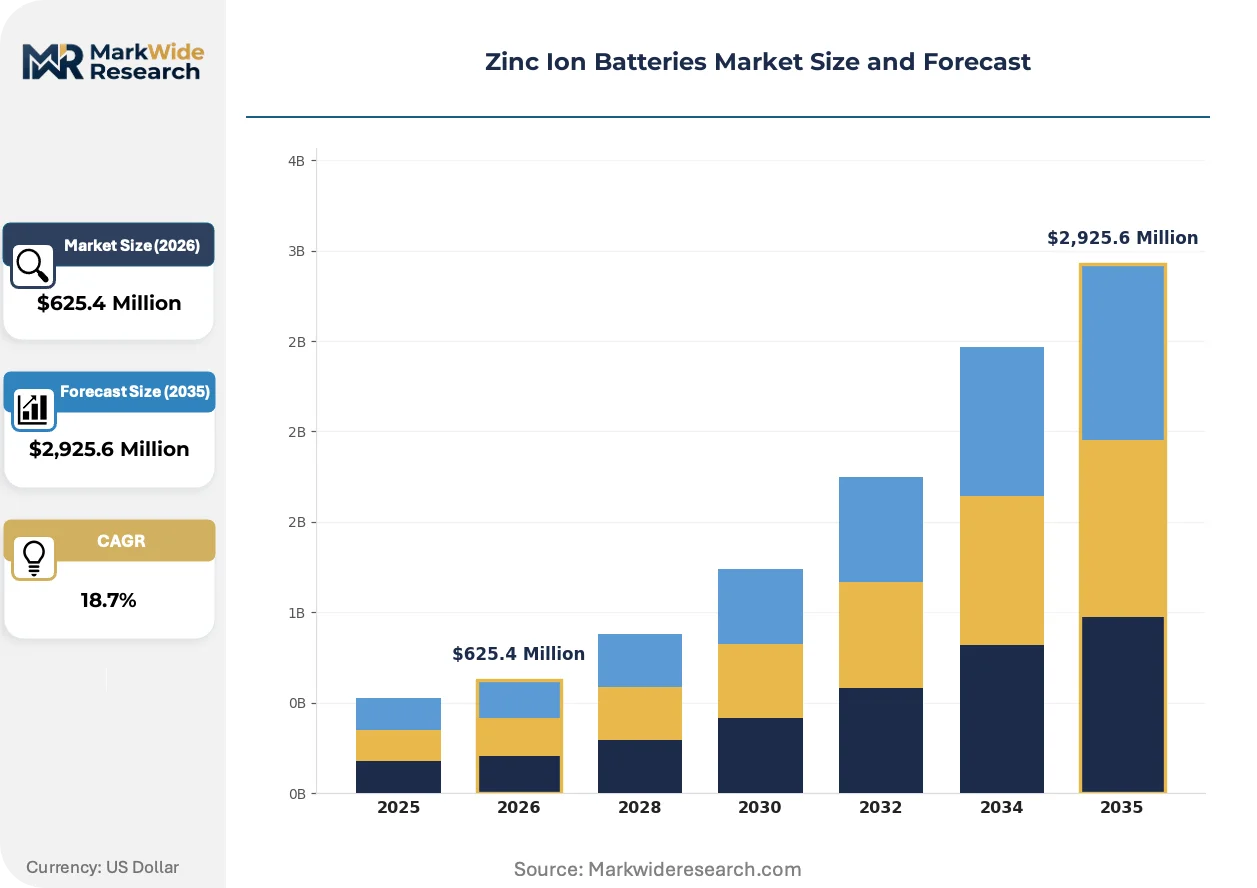
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $2,925.6 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Primary, Hybrid, Backup End User: Consumer Electronics, Renewable Energy, Automotive, Industrial Application: Energy Storage Systems, Electric Vehicles, Portable Devices, Grid Storage Technology: Liquid Electrolyte, Solid State, Polymer, Aqueous |
| Companies Covered | ZincFive, Salient Energy, Enerpoly AB, Æsir Technologies, Eastman Kodak Company, FDK Corporation, Primus Power, ZeniPower (Zhuhai Zhi Li) Battery Co., Ltd., Shenzhen BetterPower Battery Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Ion Batteries Market Trends and Innovations
Solid-state separator technology is fragmenting the zinc-ion landscape into distinct performance tiers, while regulatory pressure on lithium-ion safety accelerates chemistry diversification in stationary storage procurement.
Ceramic-polymer composite separators are fragmenting the competitive map in zinc-ion cell manufacturing. Grid-scale developers in Germany and California are piloting these configurations for daily cycling applications exceeding fifteen years. The technology is fragmenting vendor rankings by separating firms with captive separator R&D from those dependent on commodity components.
China's SAMR enforcement of GB electrochemical safety standards is compressing factory output timelines for export markets. Manufacturers must now validate thermal runaway suppression before domestic sale, conditioning design choices for international product lines. South Korean producers near Gwangju are accelerating GB-compliant production to maintain access to Chinese raw material supply.
Utility procurement departments are consolidating supplier rosters around chemistry-agnostic performance guarantees rather than technology specifications. Long-term service contracts with guaranteed cycle life are displacing equipment-only sales in North American and European tenders. This compression is most visible in California and Germany, where independent power producers now bundle zinc-ion storage with renewable offtake agreements.
Zinc Ion Batteries Market Segmentation
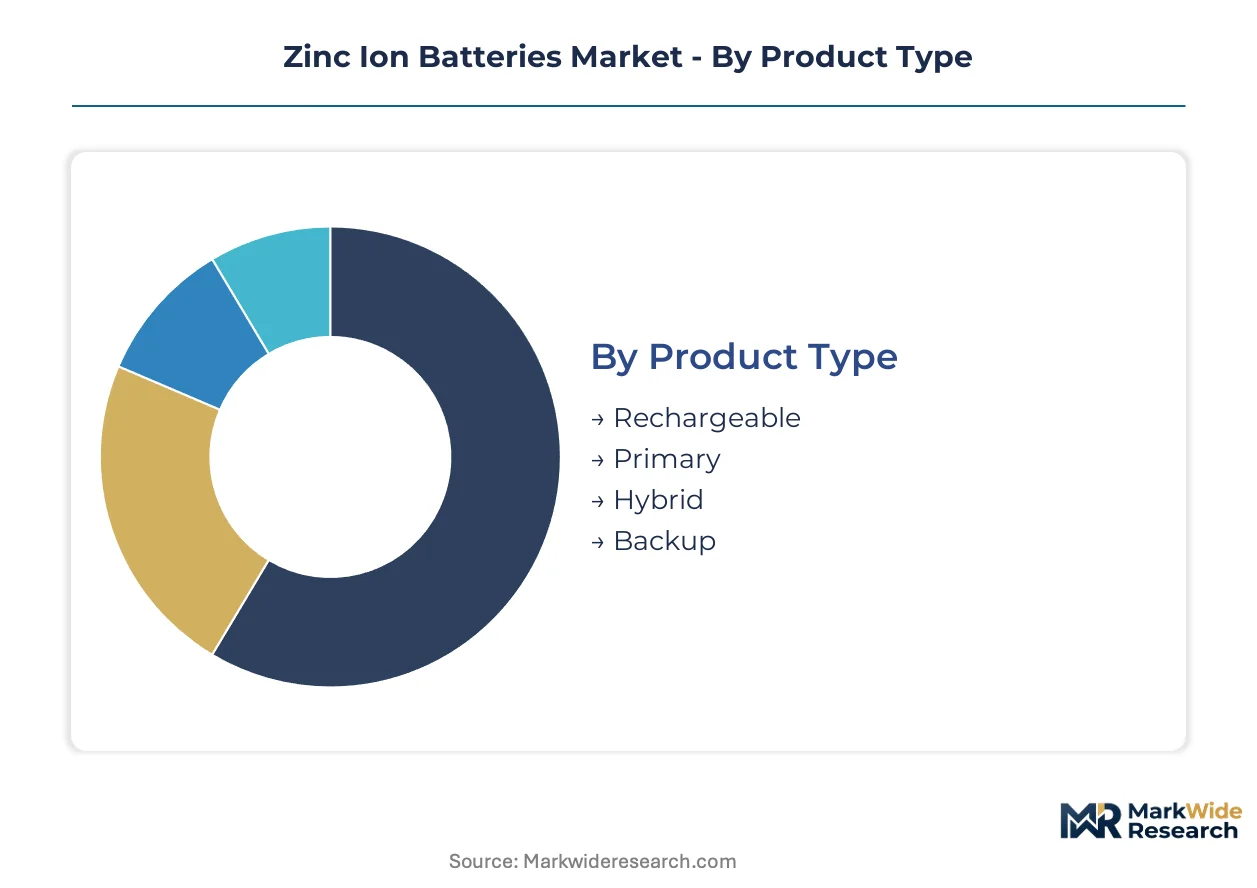
Zinc-ion chemistry fragments into distinct performance tiers where substitution pressure from lithium-ion varies sharply by segment. Manufacturers prioritize segments where aqueous safety profiles outweigh energy density trade-offs.
Product Type:
Rechargeable formats face intense substitution pressure from lithium-ion in mobility applications, while primary and backup configurations exploit zinc-ion's inherent safety advantages in stationary deployments.
- Rechargeable:Electrochemical cells designed for thousands of deep-discharge cycles with zinc metal anodes and intercalation cathodes. Demand concentrates in grid-scale storage installations across Germany and California, driven by utility procurement departments bundling long-term service contracts with renewable offtake agreements.
- Primary:Single-use zinc cells optimized for low-rate discharge applications requiring extended shelf stability. Deployment clusters in aviation backup power systems evaluated by the US FAA, where non-flammable aqueous chemistry satisfies safety-critical infrastructure standards.
- Hybrid:Dual-chemistry configurations combining zinc-ion with complementary storage technologies for load-leveling applications.
- Backup:Standby power systems engineered for infrequent cycling with immediate response capability. Industrial facilities in India leverage these configurations under draft CEA storage mandates tied to renewable purchase obligations.
Rechargeable retains volume leadership; backup holds the steepest expansion curve.
End User:
Cost tier segmentation reveals divergent margin structures, with industrial and renewable energy buyers accepting premium pricing for cycle-life guarantees while consumer electronics demands aggressive cost-down trajectories.
- Consumer Electronics:Portable device manufacturers specify zinc-ion for low-power applications where thermal runaway risks outweigh gravimetric penalties. South Korean producers near Gwangju supply GB-compliant cells for Chinese OEM export programs.
- Renewable Energy:Solar and wind developers integrate zinc-ion for daily cycling applications exceeding fifteen years. Procurement concentrates with independent power producers in California bundling storage with renewable offtake agreements.
- Automotive:Limited to auxiliary power and stationary charging infrastructure where weight constraints relax. India's CEA drafting performance benchmarks for non-lithium storage creates incremental demand channels for compliant suppliers.
- Industrial:Commercial and industrial direct sales bypass traditional utility procurement through modular system offerings. Manufacturing facilities prioritize electrolyte safety profiles under China's NMPA battery safety standards.
Industrial commands the highest margin tier; renewable energy expands most quickly.
Application:
Application segmentation tracks customer type differentiation, with utility buyers demanding chemistry-agnostic performance guarantees and commercial purchasers prioritizing modular deployment speed.
- Energy Storage Systems:Containerized battery installations for commercial and industrial load management. Germany's grid-scale developers pilot ceramic-polymer composite separators for daily cycling configurations.
- Electric Vehicles:Restricted to low-speed mobility and auxiliary systems where energy density ceilings near 400 Wh/kg prove acceptable. Solid-state electrolyte convergence promises dendrite suppression for extended cycle life.
- Portable Devices:Consumer electronics integration exploiting aqueous safety in confined spaces. China's SAMR enforcement of GB electrochemical standards compresses factory output timelines for export markets.
- Grid Storage:Utility-scale deployments replacing lithium-ion in stationary applications. China's dual carbon goals mandate domestic procurement of non-lithium storage, accelerating aqueous zinc-ion production line investments.
Grid storage dominates procurement volumes; electric vehicles climb the fastest.
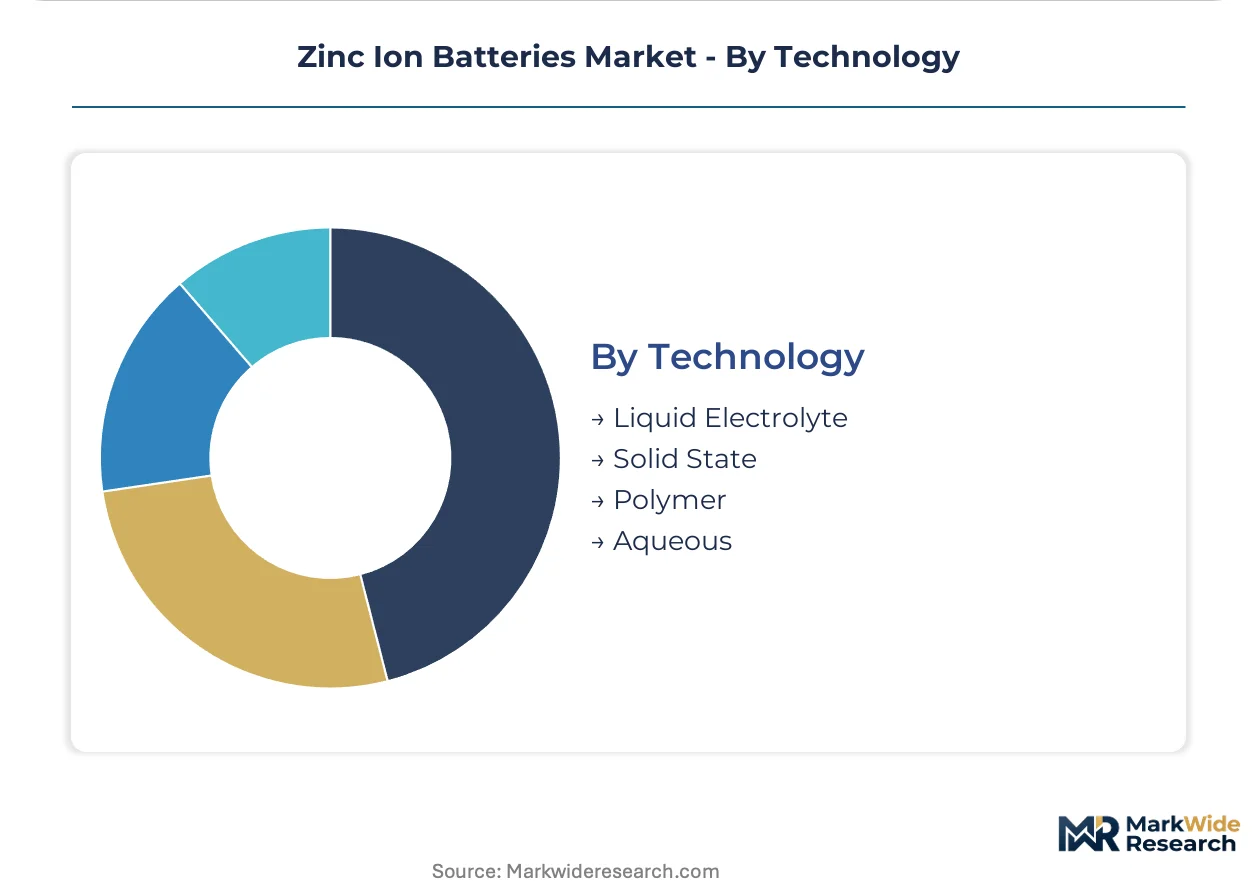
Technology:
Technology segmentation reflects supply concentration in electrolyte formulation expertise, with aqueous and liquid electrolyte variants benefiting from established manufacturing infrastructure while solid-state configurations require captive R&D investment.
- Liquid Electrolyte:Mildly acidic or neutral aqueous solutions enabling zinc ion transport between electrodes. Established production clusters in South Korea's battery materials corridor near Ulsan supply GB-compliant output for Chinese raw material access.
- Solid State:Ceramic-polymer composite separators suppressing dendrite formation beyond ten thousand cycles. Fragmenting vendor rankings separate firms with captive separator R&D from commodity-dependent competitors.
- Polymer:Gel electrolyte configurations balancing ionic conductivity with mechanical flexibility. Limited talent pools in polymer electrolyte chemistry constrain R&D velocity for next-generation cell designs.
- Aqueous:Water-based electrolyte systems delivering inherent non-flammability for safety-critical infrastructure. US EPA and FAA evaluation pathways validate deployment eligibility for stationary aviation backup applications.
Liquid electrolyte retains manufacturing scale leadership; solid state holds the steepest technology trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory investments cluster in East Asian manufacturing corridors where electrolyte formulation expertise and cathode material processing concentrate. China's dual carbon mandates and South Korea's battery materials infrastructure anchor supply-side capacity. Regulatory divergence across North America, Europe, and Asia-Pacific fragments certification pathways.
China
Grid-scale procurement mandates under NMPA battery safety standards and dual carbon goals accelerate aqueous zinc-ion production line investments. SAMR enforcement of GB electrochemical standards compresses factory output timelines for export markets. Manufacturing concentrates in the Yangtze River Delta near Shanghai and the Pearl River Delta near Shenzhen.
United States
Utility procurement departments in California bundle zinc-ion storage with renewable offtake agreements exceeding fifteen-year service contracts. The FAA evaluates systems for stationary aviation backup power, validating chemistry for safety-critical infrastructure. Independent power producers in Texas and the Southwest pilot containerized installations for grid balancing.
Germany
Grid-scale developers pilot ceramic-polymer composite separators for daily cycling configurations tied to renewable integration targets. REACH and RoHS compliance requirements condition electrolyte formulation choices for EU market access. Industrial clusters in Bavaria and North Rhine-Westphalia host pilot manufacturing for GB-compliant export production.
India
Draft CEA storage mandates tied to renewable purchase obligations create first-mover advantages for compliant zinc-ion suppliers. BIS performance benchmarks for non-lithium storage shape procurement specifications for solar and wind developers. Manufacturing activity concentrates in Gujarat and Maharashtra near port infrastructure for raw material import.
South Korea
Battery materials corridors near Gwangju and Ulsan supply GB-compliant output to maintain access to Chinese raw material supply. MFDS and KTL certification pathways align with SAMR standards for dual-market product lines. R&D intensity in zinc-ion chemistry for residential storage anchors the domestic competitive position.
Zinc Ion Batteries Market Competitive Landscape
Concentration sits with vertically integrated specialists controlling cathode supply and captive separator R&D capabilities. The vendor base separates into three tiers: diversified materials conglomerates with battery divisions, pure-play zinc-ion developers, and contract manufacturers serving white-label demand. Strategic moves center on backward integration into nickel-zinc cell production and ceramic-polymer composite separator development.
Within the pure-play developer tier, ZincFive and Salient Energy exemplify divergent positioning archetypes. ZincFive occupies a position consistent with upstream control over cathode supply chains. Salient Energy anchors the R&D-intensive vector for residential storage applications. Enerpoly AB represents the modular systems specialist archetype targeting commercial and industrial deployment channels. These three firms illustrate how electrolyte chemistry patents and regional mineral processing subsidies redistribute manufacturing cost advantages.
| Leading Market Players |
|---|
| ZincFive |
| Salient Energy |
| Enerpoly AB |
| Æsir Technologies |
| Eastman Kodak Company |
| FDK Corporation |
| Primus Power |
| ZeniPower (Zhuhai Zhi Li) Battery Co., Ltd. |
| Shenzhen BetterPower Battery Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cathode material lead times from South African manganese processors compress margin buffers for cell manufacturers, concentrating pricing power with suppliers who control electrolyte formulation patents and GB-compliant production lines.
Pricing Analysis
China's SAMR enforcement of GB electrochemical safety standards dictates the pricing tier structure across export and domestic markets. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates vendors by thermal runaway validation status. Cost compression in the economy tier is intensifying because of zinc metal price volatility from Australian and Peruvian mining concentration. Industrial grid-scale buyers show least price sensitivity due to fifteen-year service contract bundling, while consumer electronics OEMs demand aggressive cost-down trajectories.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane extend inbound logistics costs for European manufacturers dependent on Chinese electrolyte precursor supply. Manufacturing concentrates in China, South Korea, and Germany, with raw material sourcing drawing from Australian zinc concentrate, South African manganese, and Russian vanadium processing clusters. Single-source vulnerability in ceramic-polymer composite separator supply creates chokepoint exposure for solid-state cell producers. Distribution runs through direct sales to utility procurement departments and EPC contractor channels for commercial and industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited talent pools in mildly acidic aqueous chemistry create a persistent capability gap that constrains R&D velocity and fragments competitive positioning between firms with captive expertise and commodity-dependent assemblers.
For Market Incumbents: Secure electrolyte formulation patents and backward integration into nickel-zinc cathode production to defend against emerging solid-state specialists. Expand GB-compliant manufacturing capacity in South Korea's Gwangju-Ulsan corridor to maintain Chinese raw material access. Invest in ceramic-polymer composite separator R&D to separate from commodity-dependent competitors. For New Entrants and Emerging Players: Differentiate on modular system architecture for commercial and industrial direct sales channels bypassing traditional utility procurement. Target India's Gujarat and Maharashtra manufacturing clusters under draft CEA renewable storage mandates. Pursue white-label contract manufacturing partnerships with established cell producers to accelerate market entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates with underutilized battery divisions and stranded zinc-ion R&D assets. Five-to-ten year viability hinges on solid-state electrolyte convergence and dendrite suppression beyond ten thousand cycles. Watch FAA certification pathway progress for stationary aviation backup as inflection signal validating chemistry for safety-critical infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Production | ZincFive's upstream control over nickel-zinc supply secures margin protection against manganese price spikes. |
| GB Standards Compliance Investment | SAMR thermal runaway validation opens Chinese domestic procurement and conditions export market access. |
| Solid-State Electrolyte R&D Partnership | Ceramic-polymer composite development separates vendors with captive separator technology from commodity assemblers. |
| Modular System Direct Sales Channel | Enerpoly AB's commercial and industrial bypass of utility procurement reduces customer acquisition costs. |
| India CEA Mandate Pre-Positioning | First-mover compliance with BIS non-lithium storage benchmarks captures renewable purchase obligation demand. |
Research Methodology
Cross-validation between primary interviews with zinc-ion cell engineering directors and secondary analysis of SAMR GB standard filings anchors the qualitative findings on regulatory compliance pathways. The research combined discussions with utility procurement managers, EPC contractors, electrolyte chemistry specialists, and aviation backup power certification leads against trade data from China's customs administration, FERC interconnection queues, and CEA draft storage mandate documents. Bottom-up cell production capacity estimates and top-down grid-scale deployment projections triangulate volume figures.
Sensitivity analysis on zinc metal price bands and cathode material availability scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, application, and technology tier alongside regional regulatory cluster differentiation. CAGRs derive from installed base growth curves and replacement cycle assumptions. Forecast inputs incorporate China's dual carbon procurement mandates and FAA certification timeline probabilities.
Material uncertainties — electrolyte patent litigation outcomes, manganese supply disruptions from South African logistics constraints, and multi-jurisdiction certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions on technology convergence timelines and regional subsidy durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bangladesh Lead Acid Battery Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Molten Salt Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Global Battery Market
Batteries
United Kingdom SLI Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Inverter Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
United States Household Battery Market