
 France Rechargeable Battery Market | 2026-2036
France Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
France Rechargeable Battery Market Insights
High-energy-density nickel-manganese-cobalt formulations is reorganizing procurement priorities across French automotive supply chains. Automotive Cells Company leverages its gigafactory partnership with Stellantis and Mercedes-Benz to anchor cathode supply security in northern France. Verkor competes through a vertically integrated model spanning active material synthesis to cell finishing near Dunkirk. Saft Groupe SAS specializes in defense and aerospace-qualified lithium-ion systems, sustaining premium pricing through IEC certification leadership.
France rechargeable batteries are electrochemical storage devices engineered for multiple charge-discharge cycles, typically achieving 500–5,000 cycles depending on cathode chemistry and depth of discharge, with energy densities ranging from 150–300 Wh/kg for lithium-ion variants. Their primary purpose is to decouple energy generation from consumption across mobility, grid stabilization, and portable electronics. Lithium-ion chemistry dominates installed capacity due to its superior gravimetric energy density and declining cost curve. Electric vehicle application captures the fastest expansion trajectory as OEMs shift platform architectures to 800-volt systems requiring advanced thermal management. Prismatic form factor leads in automotive contracts because its steel-aluminum housing integrates efficiently into pack-level structural designs.
EU Green Deal carbon-border adjustments and France's national battery strategy under Bpifrance financing condition market access on localized supply chains and recycled content quotas. ECHA REACH compliance for nickel and cobalt sourcing, plus CE marking under the EU Batteries Regulation, shapes cell import protocols and end-of-life obligations for producers. ANSM and CNIL oversight extends to data-enabled battery management systems in medical and connected mobility contexts. Stakeholders must monitor how the EU Critical Raw Materials Act reallocates refining capacity toward European shores and whether French gigafactories secure offtake agreements before Asian competitors establish European module assembly.
Market Dynamics
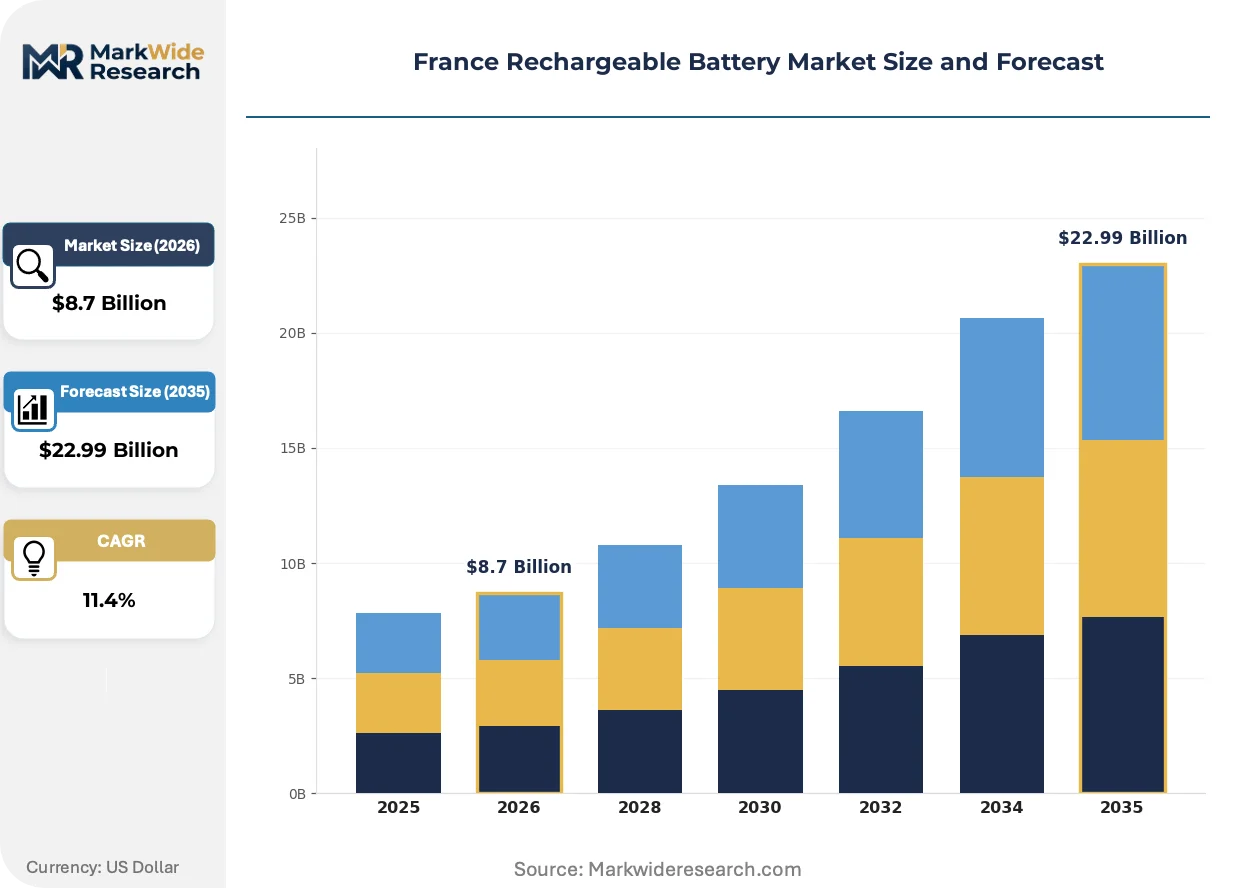
France's rechargeable battery sector is restructuring around the EU Batteries Regulation's recycled content mandates and the geographic concentration of gigafactory investment in Hauts-de-France, where cathode-active-material supply security now determines competitive viability.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Battery imports face escalating carbon-intensity scrutiny, accelerating localized cathode refining capacity near Dunkirk and Douvrin.
- 800-volt EV platform architectures:Stellantis and Renault are specifying high-nickel NMC cells requiring advanced thermal management, pulling demand toward prismatic form factors with steel-aluminum housings.
- Bpifrance national battery strategy:Conditional financing ties market access to domestic supply chain localization, channeling capital toward active material synthesis and cell finishing investments.
Market Restraints
- Nickel and cobalt price volatility:Cathode raw material cost swings compress cell producer margins, particularly for high-nickel formulations specified by automotive OEMs.
- Asian precursor supply concentration:Hydrometallurgical refining and pCAM production remain concentrated in Indonesian and Chinese facilities, creating transit risk for European gigafactories.
- ECHA REACH compliance timelines:Extended substance authorization protocols delay new electrolyte salt and binder chemistries from reaching commercial cell lines.
Strategic Opportunities
- Stationary energy storage underpenetration:Grid-scale BESS deployment in southern France lags behind mobility applications, creating offtake potential for second-life automotive cells.
- EU Critical Raw Materials Act refining incentives:Strategic project status unlocks accelerated permitting and offtake guarantees for nickel sulfate and cobalt hydroxide facilities.
- Solid-state electrolyte convergence with silicon anodes:Pre-lithiation techniques paired with sulfide-based ceramics promise energy density gains for premium aerospace contracts.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and formation protocol expertise concentrates among a limited pool of specialists, inflating compensation at Verkor and ACC.
- IEC 62660 certification timelines:Automotive qualification cycles extend 18-24 months, delaying revenue recognition for new cell formats targeting Stellantis platform integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Rechargeable Battery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead-acid, Lithium Polymer Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment Form Factor: Cylindrical, Prismatic, Coin, Pouch End User: Manufacturers, Retailers, End Consumers, Utilities |
| Companies Covered | Saft Groupe SAS, Automotive Cells Company (ACC), Verkor, Forsee Power, Leclanché, AESC Group Ltd., LG Energy Solution Ltd., GS Yuasa Corporation, i-TEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Rechargeable Battery Market Trends and Innovations
Cell chemistry and manufacturing process innovation is accelerating across France's battery corridor, driven by OEM specifications for faster charging and regulatory pressure on carbon footprints.
High-nickel NMC cathode formulations are bifurcating the automotive supply chain into two distinct procurement tiers: premium cells with nickel content exceeding 80% for 800-volt platforms, and cost-optimized LFP alternatives for entry-level urban vehicles. Stellantis has committed to NMC811 for its STLA Medium architecture, while Renault sources LFP for its R5 platform. This chemistry split is compressing supplier margins on mid-range NMC variants and forcing cathode houses to dual-track R&D investments.
France's transposition of the EU Batteries Regulation mandates recycled content quotas rising from 6% lithium and nickel in 2031 to 85% lead and 65% lithium by 2036. Industrial consequence: gigafactories must secure binding offtake agreements with mechanical and hydrometallurgical recyclers before cell production ramps. ACC has partnered with Redwood Materials for black mass processing, while Verkor is developing in-house pyrometallurgical capacity near its Dunkirk site. Automotive OEMs face the steepest compliance burden, as their high-volume contracts trigger extended producer responsibility obligations.
Automotive procurement departments are consolidating cell supply agreements around multi-year framework contracts with price-volume flexibility clauses, displacing spot-market purchasing for cathode-active materials. Tier-1 suppliers including Forsee Power and Blue Solutions are responding by offering battery-as-a-service models that bundle cell hardware with predictive maintenance software. This shift is most visible in the Hauts-de-France region, where Stellantis and Renault have centralized purchasing authority for their northern French assembly plants.
France Rechargeable Battery Market Segmentation
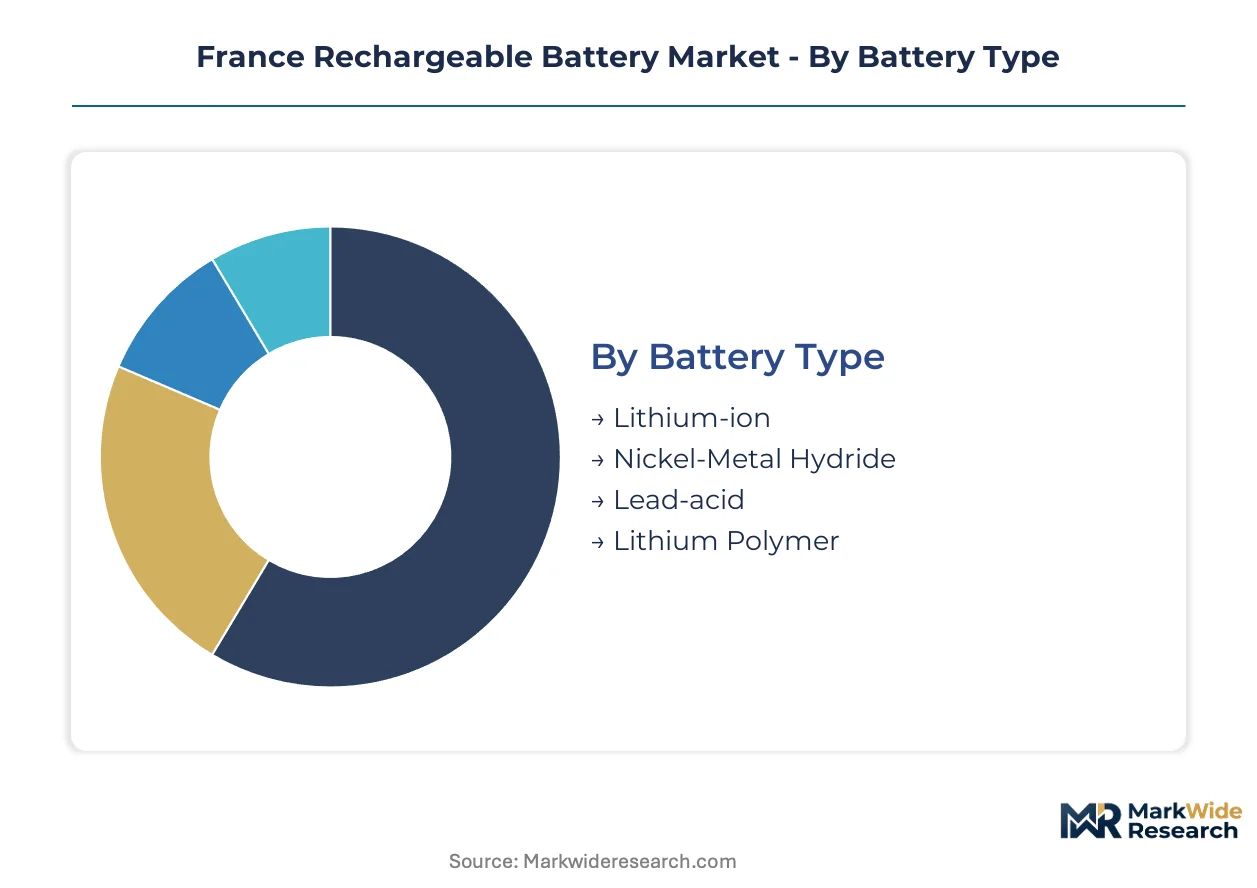
Segmentation in the France rechargeable battery market reflects divergent regulatory pressures across chemistry classes and the geographic clustering of gigafactory investment in Hauts-de-France. Understanding these divisions clarifies how EU Batteries Regulation mandates and OEM platform specifications reshape procurement patterns.
Battery Type:
EU Green Deal carbon-border adjustments and ECHA REACH substance authorization create tiered compliance burdens that segment battery chemistry economics.
- Lithium-ion:Dominant chemistry achieving 150–300 Wh/kg energy density through layered oxide cathodes. Demand concentrates in Douvrin and Dunkirk gigafactories supplying Stellantis and Renault 800-volt platforms, where high-nickel NMC formulations face escalating recycled content quotas under France's transposed EU Batteries Regulation.
- Lithium Polymer:Pouch-cell architecture enables thin-form-factor designs with gel electrolyte configurations. Adoption clusters in aerospace-qualified systems near Bordeaux and Toulouse, where ANSM certification requirements for connected medical devices sustain premium pricing through specialized IEC 62660 testing protocols.
- Nickel-Metal Hydride:Mature chemistry retaining position in hybrid-electric vehicle auxiliary systems. Toyota and Stellantis hybrid platforms in Valenciennes sustain residual demand despite lithium-ion displacement.
- Lead-acid:Flooded and VRLA variants persist in industrial backup power and automotive starter applications. Stationary energy storage in southern France retains this chemistry for cost-sensitive grid stabilization contracts.
Established volume favors Lithium-ion; emerging adoption favors Lithium Polymer.
Application:
Cost tier differentiation separates mass-market mobility contracts from premium industrial specifications.
- Electric Vehicles:800-volt platform architectures from Stellantis and Renault pull high-nickel NMC demand toward prismatic form factors with steel-aluminum housings. Bpifrance conditional financing ties cell supply security to localized cathode refining in Hauts-de-France.
- Consumer Electronics:Cylindrical and pouch cells power portable device ecosystems with shorter qualification cycles. Paris-region contract manufacturers prioritize energy density over cycle life for smartphone and laptop integration.
- Renewable Energy Storage:Grid-scale BESS deployment in Occitanie and Provence-Alpes-Côte d'Azur lags mobility applications, creating offtake potential for second-life automotive cells under France's extended producer responsibility framework.
- Industrial Equipment:Forklift and material-handling systems in Lyon and Marseille logistics hubs specify robust thermal management for high-duty-cycle operations.
Procurement scale concentrates in Electric Vehicles; margin sustainability concentrates in Industrial Equipment.
Form Factor:
Automotive structural integration requirements drive geometry selection for pack-level engineering.
- Prismatic:Steel-aluminum housings integrate efficiently into structural battery pack designs. Stellantis STLA Medium architecture specifications cement this form factor's dominance in northern French automotive supply chains.
- Cylindrical:Standardized 2170 and 4680 formats enable automated winding and high-speed production. Tesla's Berlin-adjacent supply relationships influence secondary sourcing patterns for French energy storage integrators.
- Pouch:Flexible polymer laminates suit space-constrained aerospace and medical applications. Saft Groupe SAS leverages this geometry for defense-qualified systems requiring custom aspect ratios.
- Coin:Compact diameter-to-height ratios serve wearable electronics and IoT sensor networks. Precision manufacturing in Grenoble microelectronics cluster sustains niche production.
Automotive contract value flows to Prismatic; miniaturization applications sustain Coin.
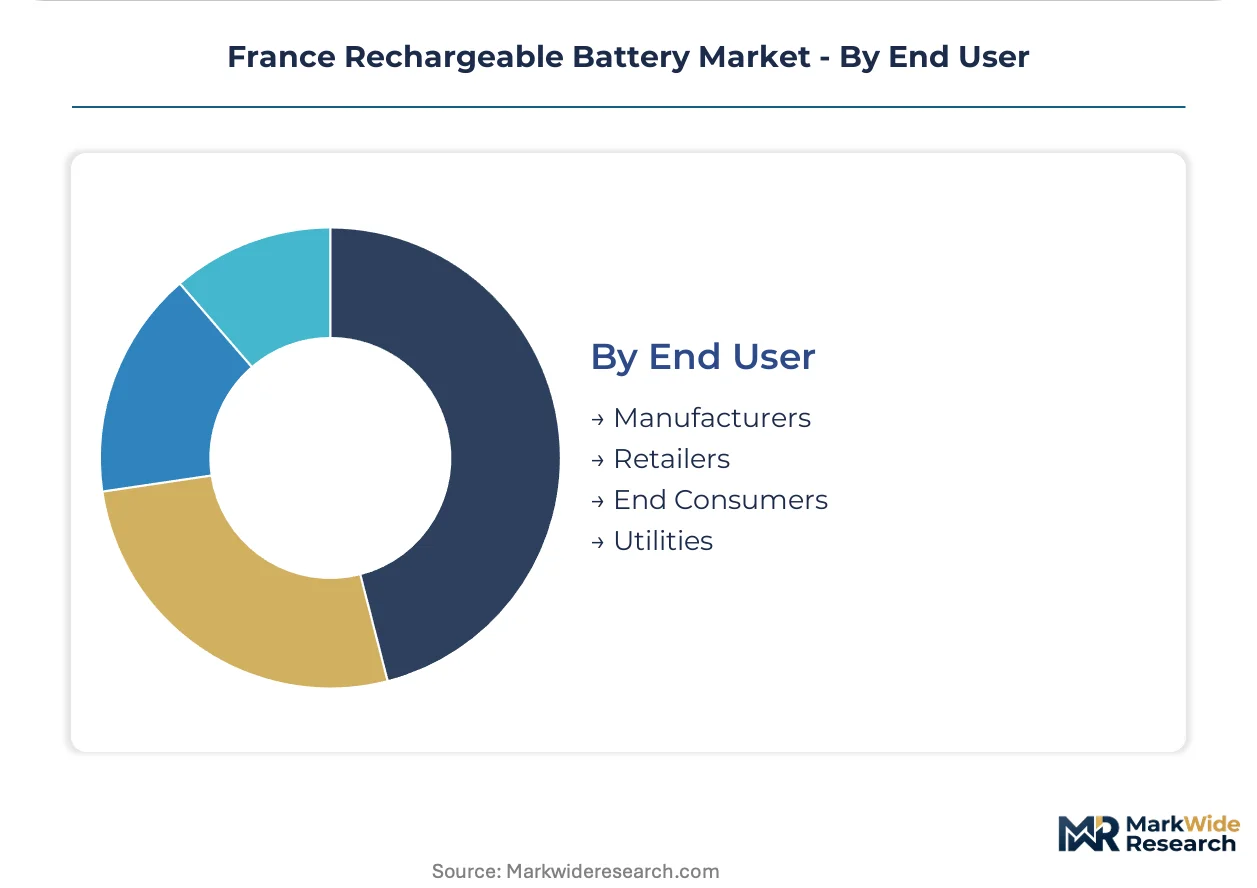
End User:
Customer type determines financing structure and extended responsibility obligations under French battery strategy implementation.
- Manufacturers:Tier-1 cell producers and pack integrators face steepest EU Batteries Regulation compliance burdens. Binding offtake agreements with mechanical recyclers precede production ramp at ACC and Verkor facilities.
- Utilities:Électricité de France and regional grid operators procure stationary storage under long-term service contracts. Southern France solar-plus-storage projects specify performance guarantees spanning 15–20 year asset lifetimes.
- Retailers:Consumer-facing distribution channels face separate collection and recycling obligations for portable batteries. Darty and Fnac storefronts serve as compliance points for household cell return programs.
- End Consumers:Individual purchasers of replacement automotive batteries trigger producer responsibility transfer at point of sale. Leasing structures through battery-as-a-service models shift accountability back to Manufacturers.
Regulatory complexity concentrates with Manufacturers; volume fragmentation characterizes End Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cathode-active-material refining capacity clusters in northern France, while southern regions lag in grid-scale storage deployment. Hauts-de-France anchors production investment through Bpifrance conditional financing tied to localized supply chains.
Hauts-de-France
Douvrin and Dunkirk host ACC and Verkor gigafactories supplying Stellantis and Renault 800-volt platforms. EU Green Deal carbon-border adjustments accelerate cathode refining investment near port infrastructure. The Dunkirk industrial zone attracts hydrometallurgical precursor facilities under EU Critical Raw Materials Act strategic project status.
Île-de-France
Paris-region contract manufacturers concentrate consumer electronics cell assembly for smartphone and laptop integration. ANSM and CNIL oversight shapes data-enabled battery management systems for medical and connected mobility applications. Research clusters in Saclay and Paris-Saclay University feed electrochemical engineering talent into national battery strategy programs.
Auvergne-Rhône-Alpes
Grenoble's microelectronics cluster sustains precision manufacturing for coin-cell formats serving wearable electronics and IoT sensor networks. The region's materials science institutes support solid-state electrolyte R&D convergence with silicon anodes. Saint-Étienne and Lyon logistics hubs specify robust thermal management for industrial forklift battery systems.
Provence-Alpes-Côte d'Azur
Solar-plus-storage deployment in this region lags mobility applications, creating offtake potential for second-life automotive cells. Électricité de France procures stationary storage under long-term service contracts with 15–20 year performance guarantees. The Mediterranean port infrastructure positions the region for future black mass import processing under extended producer responsibility frameworks.
France Rechargeable Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium qualification capabilities separate from scale-driven manufacturing. The market consolidates around gigafactory operators with binding automotive offtake agreements, while specialized producers retain niche positions through certification barriers. Two strategic archetypes dominate: vertically integrated cell producers with cathode synthesis capabilities, and pack integrators offering battery-as-a-service financing models. Competitive moves concentrate on securing recycled content agreements ahead of EU Batteries Regulation deadlines and locking in multi-year framework contracts with price-volume flexibility clauses.
Within the domestic gigafactory tier, Automotive Cells Company and Verkor anchor cathode supply security through northern French production footprints. Saft Groupe SAS occupies a specialized position serving defense and aerospace-qualified systems where IEC certification leadership sustains premium positioning. These three French entities exemplify how regulatory compliance and geographic concentration reshape procurement priorities across automotive supply chains.
| Leading Market Players |
|---|
| Saft Groupe SAS |
| Automotive Cells Company (ACC) |
| Verkor |
| Forsee Power |
| Leclanché |
| AESC Group Ltd. |
| LG Energy Solution Ltd. |
| GS Yuasa Corporation |
| i-TEN |
| Others |
Pricing and Supply Chain Analysis
Gigafactory scale economies in Hauts-de-France compress unit costs while anchoring price floors through Bpifrance conditional financing requirements. ACC and Verkor capacity utilization rates directly determine cathode-active-material procurement leverage and cell-level margin structures across French automotive supply chains.
Pricing Analysis
EU Batteries Regulation recycled content mandates dictate the pricing tier structure across French cell production. Three-tier pricing stratifies across aerospace-qualified IEC 62660 systems, automotive NMC811 contracts with binding offtake clauses, and cost-optimized LFP alternatives for urban mobility platforms. Cost compression in mid-range NMC variants intensifies because OEM procurement departments consolidate around multi-year framework contracts with price-volume flexibility clauses. Grid-scale stationary storage buyers exhibit highest price sensitivity due to competing lead-acid alternatives, while defense and aerospace contracts sustain premium positioning through ANSM certification barriers.
Supply Chain Analysis
Inventory lead times for nickel sulfate and cobalt hydroxide stretch 12-16 weeks from Indonesian and Chinese hydrometallurgical facilities to Dunkirk port infrastructure. French gigafactory output draws from concentrated precursor supply in Indonesia, China, and South Korea, with cathode-active-material synthesis tethered to EU Critical Raw Materials Act strategic project status for permitting acceleration. Single-source vulnerability concentrates in pCAM production, where Asian refining dominance creates transit risk for European cell finishing. Distribution runs through Tier-1 pack integrators offering battery-as-a-service models that bundle predictive maintenance software with hardware supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery management system software and predictive maintenance subscriptions expand faster than cell hardware sales, transforming procurement economics toward recurring-revenue structures. Service-attach models now capture margin premiums that hardware commoditization erodes.
For Market Incumbents: Secure binding offtake agreements with mechanical and hydrometallurgical recyclers ahead of EU Batteries Regulation deadlines. Lock in multi-year framework contracts with price-volume flexibility clauses to defend against Asian competitor module assembly expansion. Prioritize in-house pyrometallurgical capacity development near production sites to control recycled content quotas.
For New Entrants and Emerging Players: Lead with second-life automotive cell offerings targeting underpenetrated grid-scale BESS deployment in southern France. Stationary energy storage in Provence-Alpes-Côte d'Azur presents the most penetrable segment given EDF procurement patterns and 15-20 year performance guarantee structures. Position around battery-as-a-service financing models that shift extended producer responsibility back to manufacturers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pack integrators offering predictive maintenance software and performance guarantee contracts. Long-term viability over the next decade hinges on securing EU Critical Raw Materials Act strategic project status for refining investments. Monitor binding offtake agreement announcements between gigafactories and recyclers as the primary inflection indicator for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Refining Capacity Buildout | EU Green Deal carbon-border adjustments accelerate localized nickel sulfate production near Dunkirk port infrastructure. |
| Battery-as-a-Service Launch | Forsee Power and Blue Solutions bundle predictive maintenance software to displace spot-market cathode purchasing. |
| Recycling Partnership Formation | ACC's Redwood Materials agreement secures black mass processing ahead of 2031 recycled content quotas. |
| Solid-State R&D Convergence | Sulfide-based ceramics paired with silicon anodes target premium aerospace contracts through energy density gains. |
| 800-Volt Platform Supply Agreement | Stellantis STLA Medium architecture specifications cement prismatic cell dominance in northern French supply chains. |
Research Methodology
Desk research of EU regulatory filings, Bpifrance financing disclosures, and ECHA REACH substance databases preceded structured interviews with gigafactory operations directors, OEM platform engineers, cathode house procurement leads, and grid-scale storage project developers. Primary fieldwork combined with secondary validation against customs trade data, SEC filings from listed battery producers, and IEA energy storage deployment statistics. Bottom-up cell production capacity modeling triangulated against top-down automotive platform demand forecasts.
Variance decomposition separates volume drivers from price elasticity effects across the projection horizon. Segmentation dimensions include battery chemistry class, form factor geometry, application vertical, and end-user financing structure. CAGRs derive from installed capacity ramp schedules, OEM platform launch timelines, and regulatory mandate phase-in curves. Forecast inputs incorporate EU Critical Raw Materials Act strategic project designations and EDF stationary storage procurement patterns.
Forecasts assume regulatory continuity in EU Batteries Regulation implementation and France's national battery strategy; material policy shifts around recycled content quotas or carbon-border adjustment mechanisms would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Consumer Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
Secondary Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Portable Battery Station Market
Batteries
Europe SLI Battery Market
Batteries
South Asia Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Advanced Batteries Market
Batteries
North America Consumer Battery Market