
 East Europe Battery Market | 2026-2036
East Europe Battery Market Size, Share, and Industry Trends Forecast 2026-2036
East Europe Battery Market Foresight
Electric vehicle procurement is pivoting toward regional cell sourcing as automotive OEMs reduce Asian import dependence. LG Energy Solution leverages its Polish manufacturing base to anchor supply contracts with European EV assemblers. CATL competes through cost-engineered LFP cell architectures tailored for utility-scale storage. RUSNANO Group sustains domestic cathode material development despite technology transfer constraints.
East Europe batteries encompass electrochemical energy storage devices spanning lithium-ion, lead-acid, nickel-metal hydride, and solid-state chemistries, with lithium-ion cells utilizing nickel-manganese-cobalt cathodes and graphite-silicon composite anodes to achieve energy densities above 250 Wh/kg for traction applications. The primary industrial purpose centers on decoupling electricity generation from consumption while enabling mobile powertrains. Lithium-ion product types dominate value generation due to EV and grid-storage pull, while solid-state formats represent the fastest-expanding technology node as manufacturers resolve dendrite suppression and ceramic electrolyte scaling. Energy Storage Systems applications capture expanding margin pools as Poland and Hungary deploy grid-balancing assets.
EU Green Deal carbon-border adjustments and REACH chemical compliance are reshaping cell material qualification requirements across East Europe. Poland's national environmental regulator and Hungary's energy authority enforce battery passport traceability aligned with EU Battery Regulation delegated acts. ECHA substance restrictions on nickel and cobalt compounds are forcing cathode reformulation toward lower-cobalt high-manganese chemistries. Stakeholders must monitor how EU AI Act quality-management rules apply to automated cell inspection lines before committing capital to new production capacity.
Market Dynamics
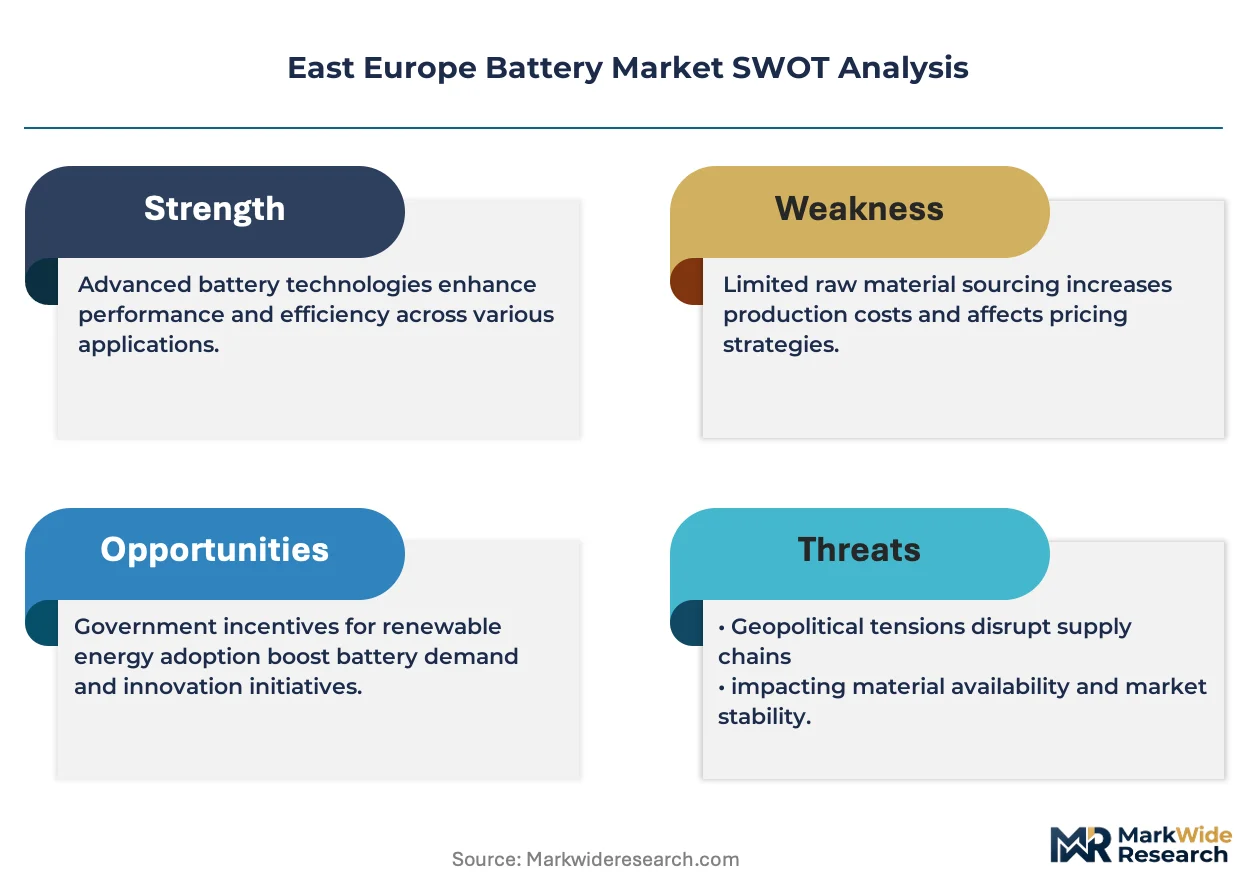
Poland's emerging gigafactory corridor is redrawing cell manufacturing geography as automotive OEMs execute supply-chain regionalization strategies. The EU Green Deal's carbon-border adjustments are forcing cathode material qualification protocols that favor localized production over Asian imports.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates adoption of water-based electrode drying processes in Polish and Hungarian cell plants.
- Utility-scale storage:Grid-balancing procurement by Poland's transmission system operator and Hungary's MAVIR creates offtake certainty for lithium-ion system integrators.
- Lithium iron phosphate chemistry:Cost-engineered LFP cathodes displace nickel-manganese-cobalt formulations in Eastern European stationary storage deployments.
Market Restraints
- Cobalt and nickel compound restrictions:ECHA substance limitations under REACH force costly cathode reformulation and qualification timelines.
- Graphite anode supply concentration:Synthetic graphite precursor dependence on Chinese processing creates input cost volatility and carbon-intensity compliance risks.
- Solid-state electrolyte manufacturing scale:Ceramic sulfide and oxide electrolyte production remains below commercial throughput thresholds for automotive volume contracts.
Strategic Opportunities
- Romania's underdeveloped EV charging infrastructure:Battery-swapping networks for commercial fleets present first-mover deployment potential in Bucharest and Cluj-Napoca corridors.
- EU Battery Regulation passport mandates:Digital traceability compliance creates service revenue pools for software-integrated cell management platforms.
- Silicon anode and solid-state convergence:Composite anode architectures paired with polymer-ceramic hybrid electrolytes enable next-generation energy density positioning.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and manufacturing process engineering expertise concentrates in Western European and Asian labor markets, constraining Polish and Hungarian facility staffing.
- EU AI Act quality-system alignment:Automated optical inspection and predictive maintenance algorithms in cell production lines require conformity assessment procedures not yet harmonized across national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Europe Battery Market |
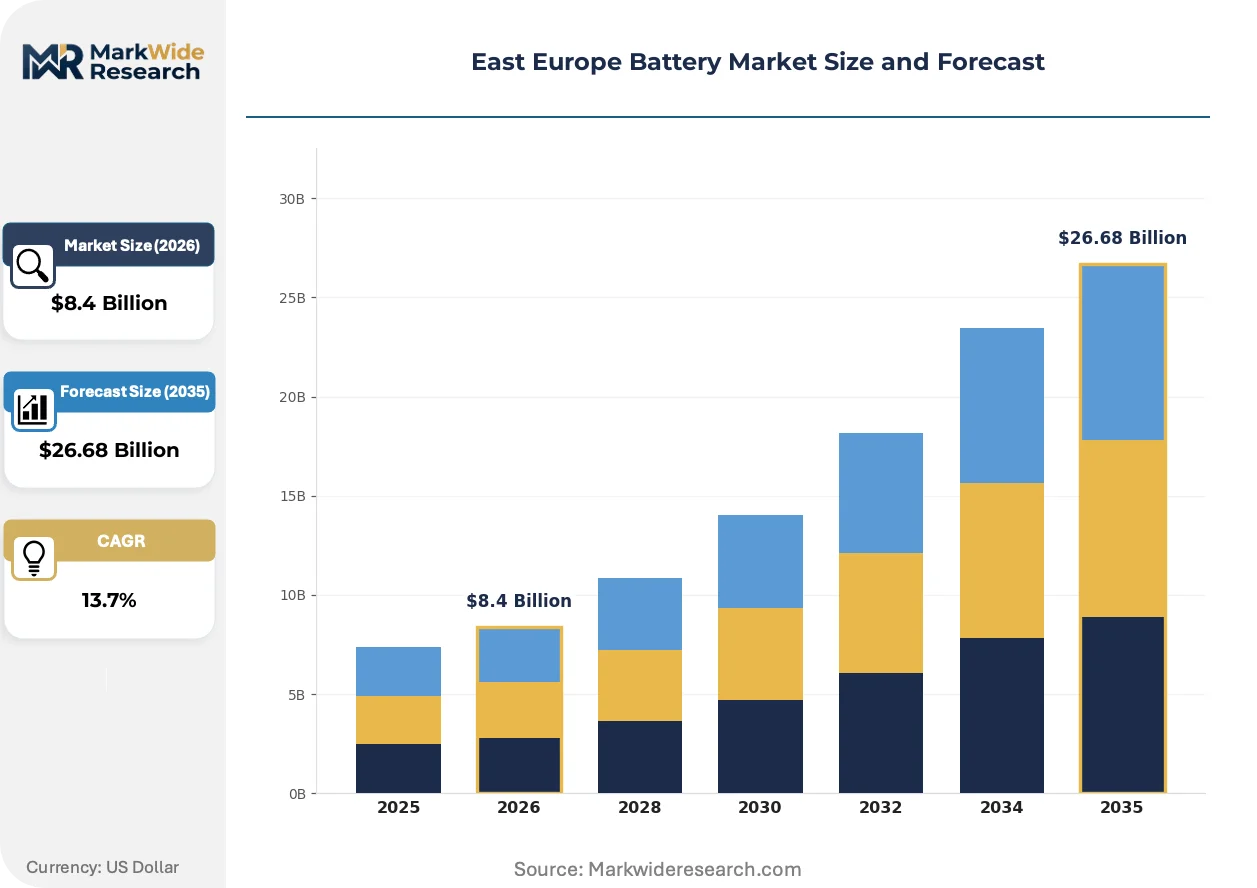
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Applications End User: Automotive Manufacturers, Electronics Companies, Utility Providers, Industrial Equipment Technology: Rechargeable, Supercapacitors, Fuel Cells, Hybrid Systems |
| Companies Covered | Duracell Inc, VARTA Microbattery GmbH, AKTEX Inc, RUSNANO Group, EAS Batteries GmbH, Contemporary Amperex Technology Co Ltd, CEZ Group, LG Energy Solution, CATL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Europe Battery Market Shifts & Advancements
Electrode manufacturing and pack integration processes are undergoing simultaneous automation and chemistry diversification. These shifts compress capital deployment timelines while expanding the addressable application set beyond automotive traction.
Solid-state battery architectures utilizing ceramic-polymer hybrid electrolytes are converging with silicon-dominant anode designs to achieve energy densities exceeding conventional liquid-electrolyte limits. Polish research institutes and Hungarian automotive suppliers are piloting these configurations for premium EV programs. The structural consequence compresses the performance gap between incumbent lithium-ion and next-generation formats, accelerating platform transition decisions by regional OEMs.
EU Battery Regulation delegated acts on carbon footprint declaration are forcing supply-chain documentation upgrades across East European cell plants. Industrial consequence includes mandatory renewable energy sourcing certificates for production facilities and recycled content thresholds for active materials. Polish environmental regulators and Hungary's energy authority are enforcing these provisions most aggressively on gigafactory entrants seeking operating permits.
Fleet operators in Poland and Romania are consolidating procurement decisions under centralized energy-management departments, displacing fragmented site-level purchasing. Large logistics and public transit authorities now negotiate multi-year cell supply agreements directly with manufacturers, bypassing traditional distributor channels. This concentration is most visible in Warsaw and Bucharest metropolitan electrification programs where municipal bus and delivery van operators aggregate demand across hundreds of vehicles.
East Europe Battery Market Segmentation
East Europe's battery market segmentation reveals distinct compliance pathways under EU Battery Regulation delegated acts. Each product category and application carries specific carbon-footprint declaration requirements and recycled-content thresholds that reshape procurement decisions across Polish and Romanian industrial clusters.
Product Type:
Lithium-ion cells require EU Battery Regulation carbon-footprint certification before market entry, while solid-state formats face additional pre-market scrutiny under ECHA substance restrictions for ceramic electrolyte precursors.
- Lithium-ion:Nickel-manganese-cobalt and lithium iron phosphate cathode architectures dominate Polish gigafactory output. Polish automotive OEMs and Hungarian bus manufacturers anchor procurement volumes under long-term supply agreements with LG Energy Solution and CATL.
- Lead-acid:Mature chemistry with minimal regulatory burden under existing EU recycling directives. Romanian industrial backup power and Polish forklift fleets sustain replacement demand despite energy density limitations.
- Nickel-metal Hydride:Hybrid vehicle auxiliary power units in Czech automotive plants retain niche demand. Toyota and Hyundai assembly lines in the region specify NiMH for mild-hybrid applications where lithium-ion cost premiums prove prohibitive.
- Solid-state:Ceramic-polymer hybrid electrolyte designs piloted at Warsaw research institutes. Dendrite suppression and manufacturing scale constraints delay commercial volume, though Hungarian automotive suppliers target premium EV programs for technology introduction.
Leading the category by volume: Lithium-ion. Expanding most quickly: Solid-state.
Application:
Application segments diverge sharply on margin structure, with utility-scale storage commanding project-finance premiums and automotive traction facing OEM cost-down pressures.
- Electric Vehicles:Passenger cars, commercial vans, and municipal buses across Poland and Romania drive cathode material demand. Poland's PESA and Solaris anchor electric bus procurement, while Dacia's Mioveni plant scales EV assembly for European export.
- Energy Storage Systems:Grid-balancing assets deployed by Poland's transmission system operator and Hungary's MAVIR create offtake certainty. LFP chemistry dominates stationary applications due to cost engineering and cycle-life requirements.
- Consumer Electronics:Polish contract manufacturers supply smartphone and laptop battery packs for Western European brands. REACH compliance on nickel and cobalt compounds forces cathode reformulation toward lower-cobalt alternatives.
- Industrial Applications:Forklift fleets, backup power systems, and material-handling equipment across Romanian logistics hubs sustain lead-acid replacement cycles. Polish warehouse automation projects are pivoting toward lithium-ion for operational efficiency gains.
Highest margin capture: Energy Storage Systems. Fastest volume climb: Electric Vehicles.
End User:
End-user concentration determines contract structure, with automotive manufacturers consolidating procurement under centralized energy-management departments.
- Automotive Manufacturers:Volkswagen, Stellantis, and Hyundai-Kia assembly plants in Poland, Czech Republic, and Slovakia negotiate direct cell supply agreements. Multi-year contracts bypass traditional distributor channels and specify carbon-intensity thresholds aligned with EU Green Deal requirements.
- Electronics Companies:Polish contract manufacturers and Hungarian consumer electronics assemblers source cylindrical and prismatic cells for portable device integration. Battery passport traceability mandates from the EU Battery Regulation impose documentation burdens on mid-tier suppliers.
- Utility Providers:Poland's PSE and Hungary's MAVIR procure containerized storage for grid-balancing services. Regulatory frameworks under national energy authorities enforce technical specifications for frequency response and ramp-rate capabilities.
- Industrial Equipment:Romanian logistics operators and Polish manufacturing facilities specify motive power batteries for forklifts and automated guided vehicles. Fleet electrification programs in Bucharest and Warsaw metropolitan areas aggregate demand across hundreds of units.
Dominant procurement volume: Automotive Manufacturers. Steepest demand trajectory: Utility Providers.
Technology:
Technology segments map to distinct capital-deployment timelines, with rechargeable formats absorbing near-term investment and fuel cells requiring infrastructure co-development.
- Rechargeable:Lithium-ion and emerging solid-state architectures constitute the commercial core. Polish gigafactory investments by LG Energy Solution and SK On concentrate manufacturing capacity for European automotive offtake.
- Supercapacitors:Rapid charge-discharge devices for regenerative braking and grid-frequency regulation. Hungarian automotive suppliers integrate supercapacitor modules alongside lithium-ion packs for hybrid transit buses.
- Fuel Cells:Hydrogen proton-exchange membrane systems for heavy-duty trucking corridors. Czech and Slovak hydrogen valley initiatives pilot fuel-cell deployment along Danube logistics routes.
- Hybrid Systems:Combined battery-supercapacitor or battery-fuel-cell architectures for mission-critical applications. Polish rail electrification projects evaluate hybrid storage for catenary-free tram segments.
Technology commanding capital deployment: Rechargeable. Gaining share fastest: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Europe's battery production capacity is expanding faster than regional consumption, creating an export-oriented manufacturing base serving Western European automotive demand. Poland and Hungary dominate cell fabrication while Romania and Czech Republic concentrate on pack assembly and materials processing. This geographic specialization reflects divergent labor costs, regulatory enforcement intensity, and proximity to German OEM assembly plants.
Poland
LG Energy Solution's Kobierzyce gigafactory and emerging SK On investments anchor lithium-ion cell production for Volkswagen and Hyundai-Kia programs. Poland's General Environmental Protection Inspectorate enforces EU Battery Regulation carbon-footprint declarations with particular rigor for new facility permits. The Silesian-Małopolska corridor clusters cathode active material plants alongside cell manufacturing, creating integrated supply-chain density around Wrocław and Kraków.
Hungary
CATL's Debrecen facility and Samsung SDI's Göd plant supply cylindrical and prismatic cells for BMW and Mercedes-Benz electrification platforms. Hungary's Energy and Climate Policy Directorate mandates renewable energy certificates for production facilities under national transposition of EU Green Deal provisions. The Budapest-Debrecen logistics axis supports just-in-time delivery to German automotive assembly plants across the nearby border.
Romania
Dacia's Mioveni assembly plant and emerging commercial fleet electrification in Bucharest generate concentrated demand for LFP battery packs. Romania's National Environmental Protection Agency implements REACH substance restrictions with inspection protocols focused on nickel and cobalt compound handling. The Pitești automotive cluster is attracting pack integrators serving both domestic OEM demand and export markets into Southeast Europe.
Czech Republic
Hyundai's Nošovice plant and Škoda Auto's Mladá Boleslav operations anchor hybrid and EV battery procurement from neighboring Polish and Hungarian cell plants. The Czech Trade Inspection Authority enforces EU Battery Regulation passport traceability requirements on automotive suppliers. The Moravian-Silesian Region is developing hydrogen valley infrastructure that complements battery-electric systems for heavy-duty trucking corridors toward Slovakia.
Slovakia
Stellantis' Trnava facility and Jaguar Land Rover's Nitra plant source lithium-ion cells from Polish gigafactories under long-term supply agreements. Slovakia's Ministry of Environment administers ECHA chemical compliance with particular attention to cathode material precursor imports. The Žilina-Košice industrial belt is positioning for battery recycling infrastructure to process end-of-life cells from regional automotive production.
East Europe Battery Market Competitive Landscape
Top-tier vendors anchor automotive-grade cell production, while mid-tier fabricators concentrate on industrial motive power and consumer electronics packs. The vendor base separates into three distinct strata: multinational gigafactory operators, regional pack integrators, and specialty chemistry developers. Consolidation pressure is intensifying as EU Battery Regulation compliance costs favor scale. Dominant competitive moves include backward integration into cathode materials and strategic partnerships with automotive OEMs for dedicated capacity allocation.
Within the multinational gigafactory tier, LG Energy Solution and CATL exemplify divergent strategic positioning. LG Energy Solution leverages its Polish manufacturing base to anchor European automotive supply contracts. CATL competes through cost-engineered LFP architectures tailored for utility-scale storage applications. RUSNANO Group occupies a distinct position within the specialty materials tier, sustaining domestic cathode development despite technology transfer constraints. These three entities collectively illustrate the competitive spectrum spanning integrated cell manufacturing, chemistry-specific cost leadership, and national industrial policy alignment.
| Leading Market Players |
|---|
| Duracell Inc |
| VARTA Microbattery GmbH |
| AKTEX Inc |
| RUSNANO Group |
| EAS Batteries GmbH |
| Contemporary Amperex Technology Co Ltd |
| CEZ Group |
| LG Energy Solution |
| CATL |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers and private-equity-rolled-up specialists dominate Polish and Hungarian cell manufacturing, concentrating pricing power among gigafactory operators while fragmenting margin capture across mid-tier pack integrators in Romania and Czech Republic. This ownership pattern enforces contract-based long-term offtake structures for automotive OEMs and project-based procurement for utility-scale storage, with EU Battery Regulation carbon-footprint certification costs filtering weaker participants from premium-tier supply.
Pricing Analysis
Cost-down pressure on automotive-grade cells accelerates because Volkswagen and Stellantis procurement departments consolidate volume under multi-year agreements with LG Energy Solution and CATL. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with EU Battery Regulation passport compliance commanding tier-one positioning. Price erosion runs through consumer electronics packs as Polish contract manufacturers face REACH compliance burdens without offsetting brand premiums. Fleet operators in Bucharest and Warsaw metropolitan areas exhibit highest price sensitivity, while German automotive OEMs prioritize carbon-intensity thresholds over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, BMW, and Hyundai-Kia assembly plants, bypassing traditional distributor networks for cell procurement. Raw material dependencies rest on Chinese synthetic graphite processing, Chilean and Australian lithium carbonate, and Indonesian nickel laterite, creating single-source vulnerability for anode precursors. Geographic supply concentration centers on Poland and Hungary for cell fabrication, with Romania and Czech Republic specializing in pack assembly and module integration. Distribution runs through just-in-time logistics corridors toward German automotive clusters, with Budapest-Debrecen and Wrocław-Kraków axes serving as primary fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation compliance costs and carbon-border adjustment mechanisms are forcing consolidation across East European cell manufacturing, eliminating sub-scale pack integrators unable to fund certification infrastructure.
For Market Incumbents: Extend cathode active material backward integration into Poland's Silesian-Małopolska corridor to secure supply-chain density around Wrocław and Kraków. Add dedicated capacity for solid-state pilot lines at Warsaw research institutes before Hungarian automotive suppliers lock in premium EV program allocations. ECHA substance restrictions on nickel and cobalt compounds threaten incumbent cathode formulations without reformulation investment. For New Entrants and Emerging Players: Capture battery-swapping network deployment in Bucharest and Cluj-Napoca corridors where Romania's underdeveloped EV charging infrastructure creates first-mover white space. Target commercial fleet operators consolidating procurement under centralized energy-management departments, bypassing fragmented site-level purchasing through direct software-integrated cell management platform contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier pack integrators with existing EU Battery Regulation passport traceability infrastructure in Czech Republic and Slovakia. Long-term viability over the next decade hinges on positioning for battery recycling infrastructure at end-of-life processing nodes. Watch for inflection signals in silicon anode and solid-state convergence timelines as Polish research institute pilot data releases.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Backward Integration | Poland's Silesian-Małopolska corridor secures supply-chain density against Chinese import volatility. |
| Solid-State Pilot Line Capacity Addition | Warsaw research institutes anchor premium EV program positioning before Hungarian supplier lock-in. |
| Battery Passport Traceability Platform Launch | Software-integrated cell management captures EU Battery Regulation compliance service revenue pools. |
| Battery Swapping Network Deployment | Bucharest and Cluj-Napoca corridors exploit Romania's charging infrastructure gaps for fleet operators. |
| End-of-Life Recycling Infrastructure Buildout | Slovakia's Žilina-Košice belt processes regional automotive cell waste under ECHA substance protocols. |
Research Methodology
Regulatory filings from ECHA, EU Battery Regulation delegated acts, and national environmental inspectorate permits formed the secondary backbone for compliance pathway mapping. Primary interviews with cell manufacturing process engineers, automotive OEM procurement leads, utility storage project developers, and cathode material R&D directors combined with customs and trade data, IEA battery deployment statistics, and SEC filings from listed cell manufacturers. Bottom-up cell production capacity estimates triangulated against top-down automotive EV production forecasts across the analysis window.
Historical trendline analysis of lithium-ion gigafactory investment flows and solid-state pilot program announcements established baseline growth trajectories. The analytical framework modeled segmentation across product type, application, end user, and technology dimensions, with additional granularity on carbon-intensity certification tiers. CAGRs derived from production capacity expansion timelines and offtake contract volumes, incorporating EU Green Deal carbon-border adjustment implementation schedules and F-Gas Regulation phase-down curves as scenario inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state electrolyte manufacturing scale breakthroughs and ECHA substance restriction enforcement intensity. Forecasts reflect documented assumptions on cathode chemistry transition rates and renewable energy certificate sourcing compliance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Myanmar Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Battery Separators Market
Batteries
Nimh Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
United States SLI Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
North America Industrial Battery Market
Batteries
Leisure Battery Market
Batteries
Printed Batteries Market
Batteries
Drone Power Sources Market