
 Austria Data Center Market | 2026-2036
Austria Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Data Center Market Insights
Managed disaster recovery services is pivoting from a bolt-on offering to a core procurement criterion for Austrian enterprise buyers. A1 Telekom Austria leverages its national fiber backbone to anchor edge deployments across provincial business parks. Digital Realty Trust competes through interconnection density at its Vienna campus, while Raiffeisen Rechenzentrum differentiates via financial-sector compliance specialization that domestic banks require.
Austria data centers constitute purpose-built facilities housing compute, storage, and network infrastructure with redundant power architectures typically delivering 99.999% uptime availability for mission-critical workloads. Colocation and hyperscale facility types command the majority of deployed square meters, though liquid cooling technology is gaining structural relevance as GPU-intensive AI training clusters exceed 30 kW per rack thermal thresholds. Infrastructure as a Service generates the deepest margin pools among service types, while Platform as a Service segments show the fastest adoption velocity among mid-market enterprises seeking managed Kubernetes environments without capital-intensive buildouts.
Austria's Federal Ministry for Climate Action implements the EU Energy Efficiency Directive through mandatory power usage effectiveness reporting for facilities exceeding 500 kW capacity, while national building codes administered by regional authorities enforce seismic and fire suppression standards that shape construction costs and site selection. The EU AI Act, enforced through Austria's national regulator, will impose algorithmic transparency requirements that expand audit-ready colocation demand. Stakeholders must monitor whether grid expansion timelines in Lower Austria and Styria keep pace with hyperscale power commitments before committing to greenfield development schedules.
Market Dynamics
GPU-intensive AI training clusters exceeding 30 kW per rack thermal thresholds are forcing wholesale infrastructure redesign across Austrian facilities, compressing legacy air-cooled architectures and accelerating liquid cooling capital deployment timelines.
Growth Catalysts
- EU Green Deal alignment:Mandatory renewable power sourcing mandates drive hyperscale operators toward 100% carbon-neutral energy contracts, expanding grid-interconnected greenfield development in Vienna's metropolitan corridor.
- Cloud-native financial services:Austrian banks and insurance carriers are expanding colocation footprints to satisfy algorithmic transparency requirements under the EU AI Act, creating audit-ready infrastructure demand.
- Liquid cooling technology:Direct-to-chip and immersion systems are capturing rack deployment share as thermal densities render traditional CRAH units economically unviable for AI training workloads.
Market Restraints
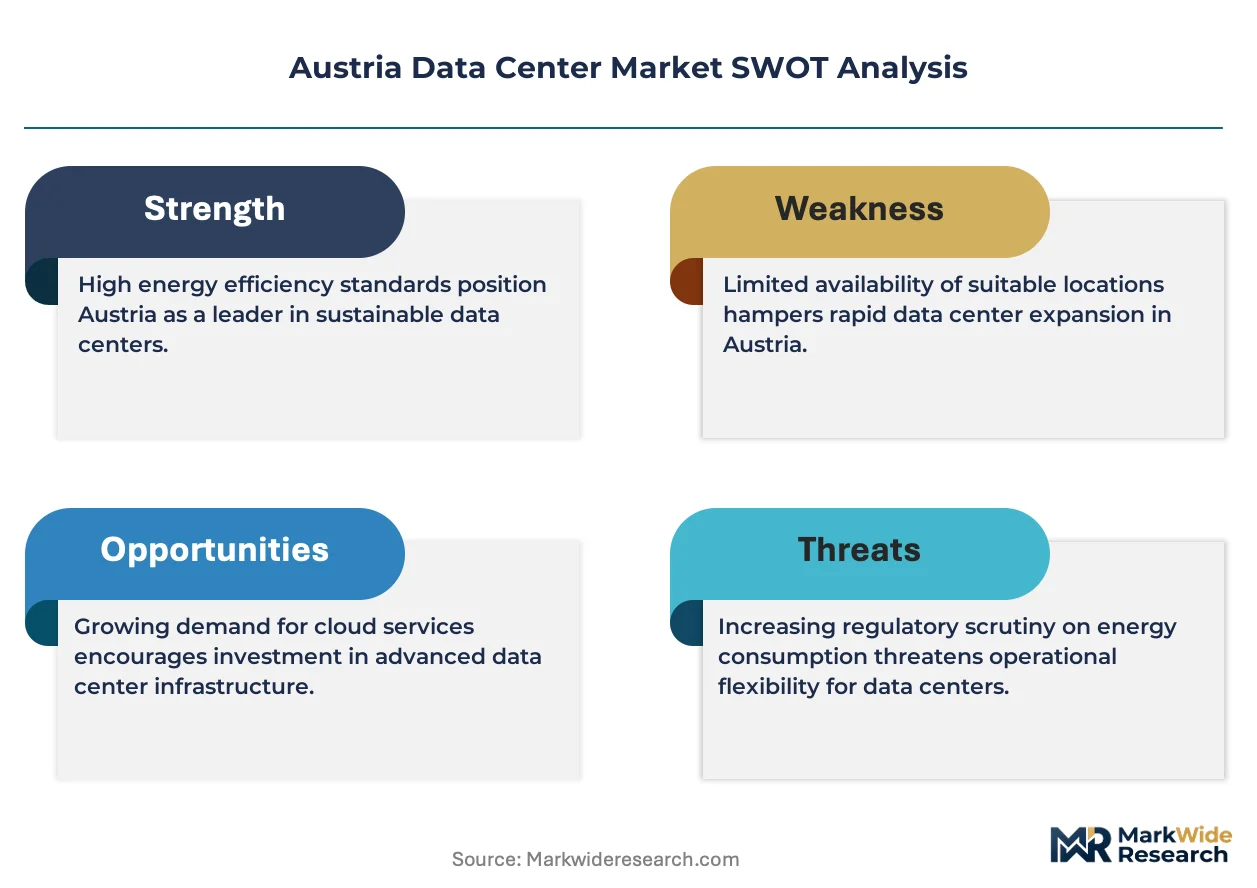
- Grid interconnection bottlenecks:Transmission expansion timelines in Lower Austria and Styria lag hyperscale power commitment schedules, delaying greenfield project commissioning.
- Seismic and fire suppression compliance:Regional building code variations administered by provincial authorities inflate construction costs and constrain site selection flexibility.
- Specialized engineering labor scarcity:Austria's technical universities produce insufficient graduates in thermal engineering and high-voltage electrical systems to match facility deployment velocity.
Strategic Opportunities
- Provincial edge deployment:A1 Telekom Austria's national fiber backbone enables low-latency compute positioning across business parks in Salzburg, Tyrol, and Carinthia outside Vienna's saturated core.
- Managed Kubernetes platforms:Mid-market enterprises seek Platform as a Service environments without capital-intensive buildouts, opening margin-rich recurring revenue streams.
- Disaster recovery specialization:Procurement criteria now mandate colocation providers offer geographically separated synchronous replication, elevating multi-site operators.
Industry Challenges
- Legacy workload migration complexity:Austrian enterprises operate heterogeneous on-premise estates that resist seamless lift-and-shift to cloud-native architectures, extending sales cycles.
- PUE reporting compliance burden:Facilities exceeding 500 kW capacity face mandatory power usage effectiveness documentation to Austria's Federal Ministry for Climate Action, requiring instrumentation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Data Center Market |
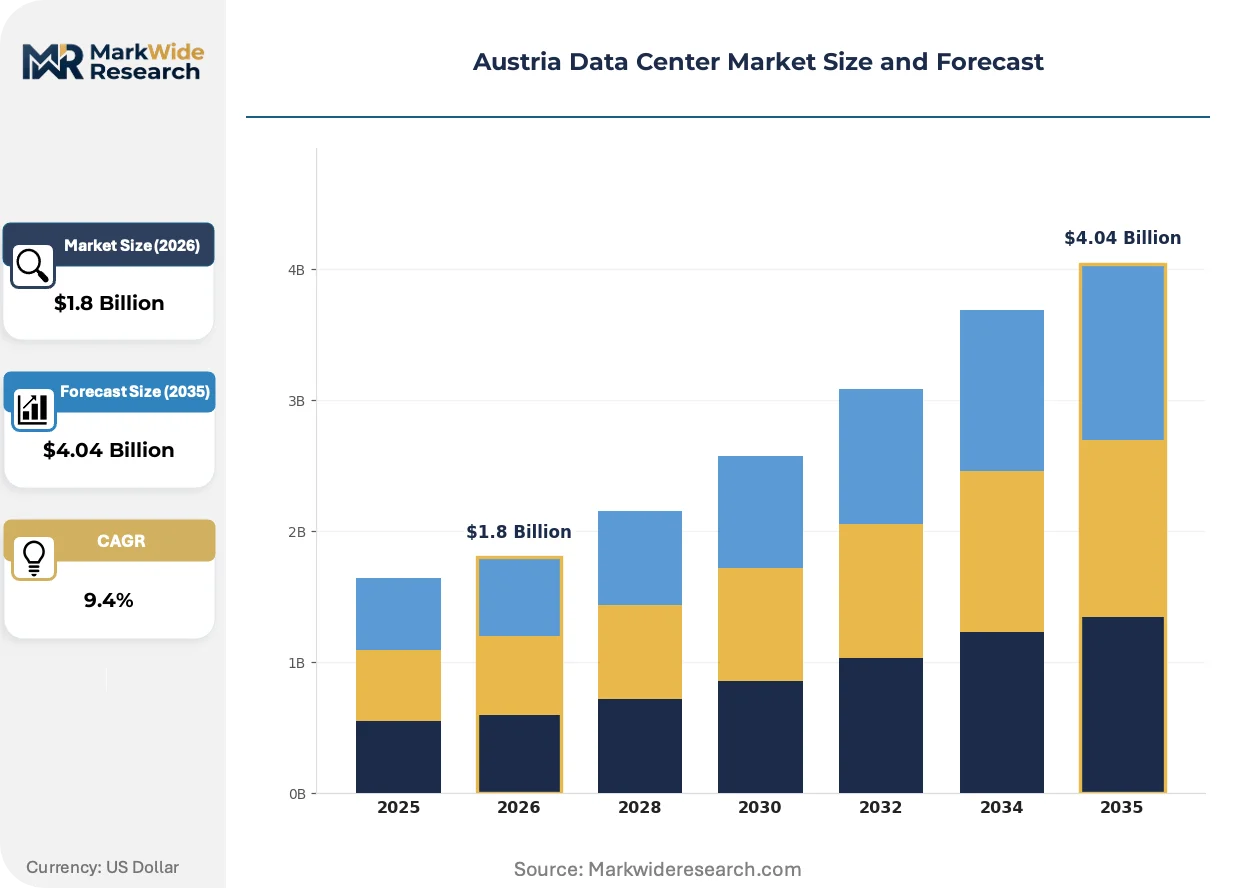
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Colocation, Wholesale, Hyperscale, Edge Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Containment Power Source: Renewable Energy, Grid Power, Diesel Generation, Fuel Cells |
| Companies Covered | Digital Realty Trust, NTT Corporation, A1 Telekom Austria, AtlasEdge, Microsoft, Google, Raiffeisen Rechenzentrum, GRZ IT Center, Magenta Telekom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Data Center Market Trends and Innovations
Direct liquid cooling systems are absorbing capital allocation previously directed toward mechanical refrigeration, while regulatory transparency mandates and procurement model evolution reshape competitive positioning across Austrian data center operators.
Immersion cooling tanks utilizing dielectric fluids are absorbing rack-level thermal loads that conventional CRAH infrastructure cannot economically address. Hyperscale cloud providers and AI training clusters in Vienna's metropolitan corridor are specifying these systems for new deployments. This technology is absorbing engineering talent and vendor relationships that previously supported air-cooled mechanical infrastructure, compressing incumbent equipment supplier margins.
The EU AI Act, enforced through Austria's national regulator, imposes algorithmic transparency and audit trail requirements on financial services infrastructure. Colocation providers must demonstrate physical access controls, environmental monitoring, and chain-of-custody documentation that exceed prior standards. Domestic banks and insurance carriers are responding by consolidating vendor relationships with operators holding financial-sector compliance certifications.
Enterprise buyers are unbundling disaster recovery from primary colocation contracts and evaluating managed DR services as standalone procurement categories. Mid-market manufacturers and logistics firms in Styria and Upper Austria are displacing tape-based backup with synchronous replication to secondary sites. This pattern concentrates demand among operators offering dual-campus architectures within the country.
Austria Data Center Market Segmentation
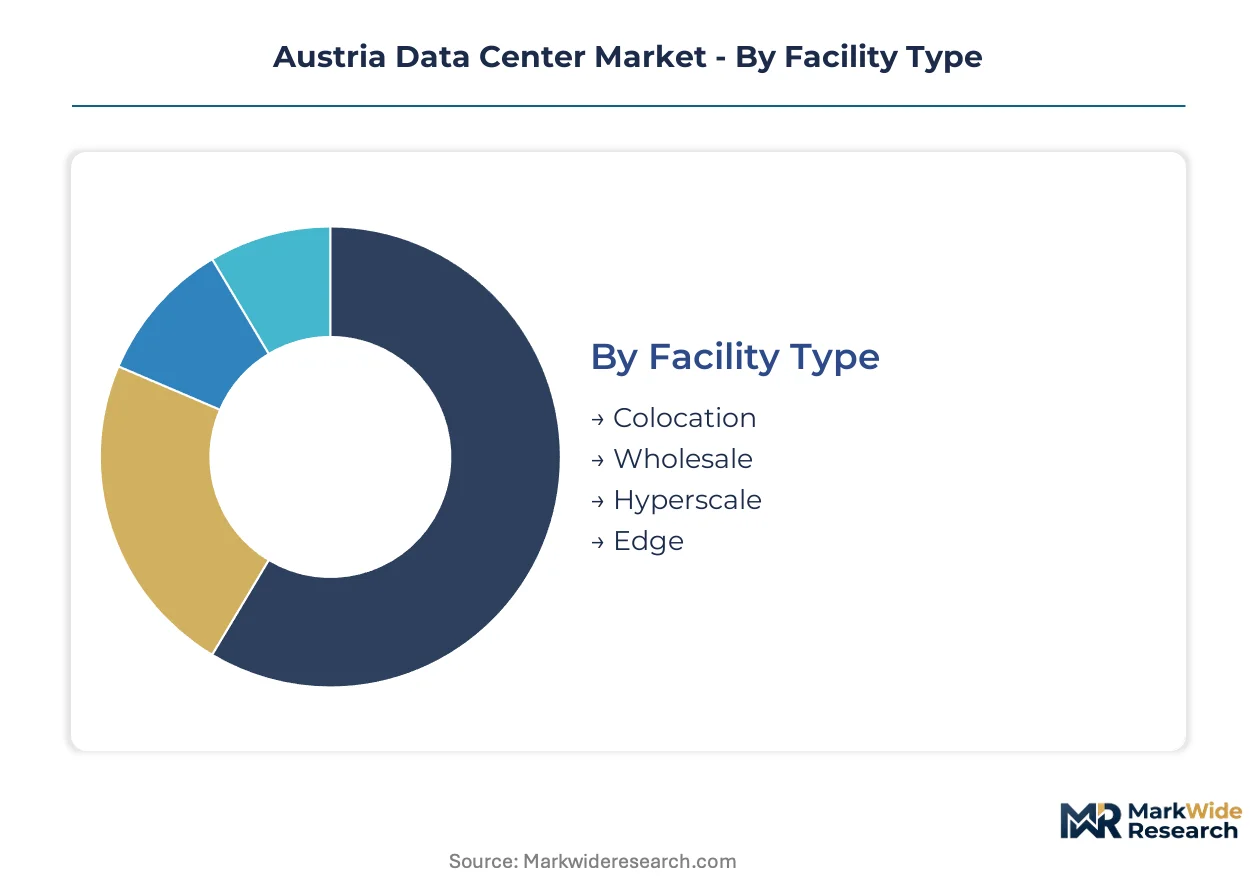
Austrian buyers exhibit divergent infrastructure requirements across facility scale, service model, thermal architecture, and power sourcing. Procurement patterns cluster around compliance mandates for financial services, AI training density thresholds, and EU Green Deal renewable obligations.
Facility Type:
Scale requirements separate enterprise buyers from hyperscale operators and distributed edge deployers.
- Colocation:Multi-tenant facilities deliver rack-by-rack leasing with shared power and cooling infrastructure. Austrian banks and insurance carriers concentrate demand in Vienna's metropolitan corridor to satisfy EU AI Act audit requirements for physical access controls and environmental monitoring.
- Hyperscale:Single-tenant campuses exceed 10 MW design capacity with dedicated substations and liquid cooling architectures. Cloud providers anchor deployments in Vienna's fiber-dense corridor where grid interconnection and renewable energy contracting converge.
- Wholesale:Partial building or dedicated suite arrangements serve mid-market enterprises seeking operational control without capital-intensive construction. Regional manufacturers in Styria and Upper Austria lease wholesale footprints for disaster recovery positioning.
- Edge:Micro-facilities below 1 MW position compute within 10 milliseconds of end-users. A1 Telekom Austria deploys edge nodes across Salzburg, Tyrol, and Carinthia business parks leveraging its national fiber backbone.
Colocation leads volumes today; edge is gaining share fastest.
Service Type:
Capital intensity preferences distinguish buyers seeking infrastructure abstraction versus platform management.
- Infrastructure as a Service:Bare-metal compute and storage provisioning with self-managed software stacks. Mid-market enterprises in Vienna's logistics sector adopt IaaS to defer data center construction capital while retaining workload control.
- Platform as a Service:Managed Kubernetes and container orchestration environments eliminate operational overhead. Austrian software vendors and fintech startups drive adoption velocity here, seeking scalable deployment without DevOps staffing.
- Software as a Service:Application-level hosting with vendor-managed infrastructure beneath. Enterprise resource planning and customer relationship management workloads migrate to SaaS colocation to satisfy Federal Ministry for Climate Action PUE reporting mandates.
- Disaster Recovery:Geographically separated synchronous replication and failover orchestration. Procurement now evaluates DR as standalone category rather than bolt-on, elevating operators with dual-campus Austrian presence.
Infrastructure as a Service dominates revenue contribution; Platform as a Service climbs the fastest.
Cooling Technology:
Thermal density thresholds force technology selection based on rack-level power deployment.
- Liquid Cooling:Direct-to-chip and immersion systems absorb GPU-intensive AI training loads exceeding 30 kW per rack. Hyperscale operators in Vienna specify dielectric fluid tanks as conventional CRAH units become economically unviable for dense clusters.
- Air Cooling:Computer room air handlers and perimeter cooling serve legacy enterprise workloads below 15 kW per rack. Established colocation facilities retain air-cooled architectures for general-purpose compute where thermal density permits.
- Evaporative Cooling:Adiabatic systems reduce mechanical refrigeration energy in moderate climates. Regional data centers in Lower Austria leverage evaporative designs to meet EU Energy Efficiency Directive targets.
- Containment:Hot-aisle and cold-aisle isolation improves air-cooled efficiency without full liquid conversion. Retrofit deployments extend legacy infrastructure viability for mixed-density environments.
Air cooling retains installed base leadership; liquid cooling expands most quickly.
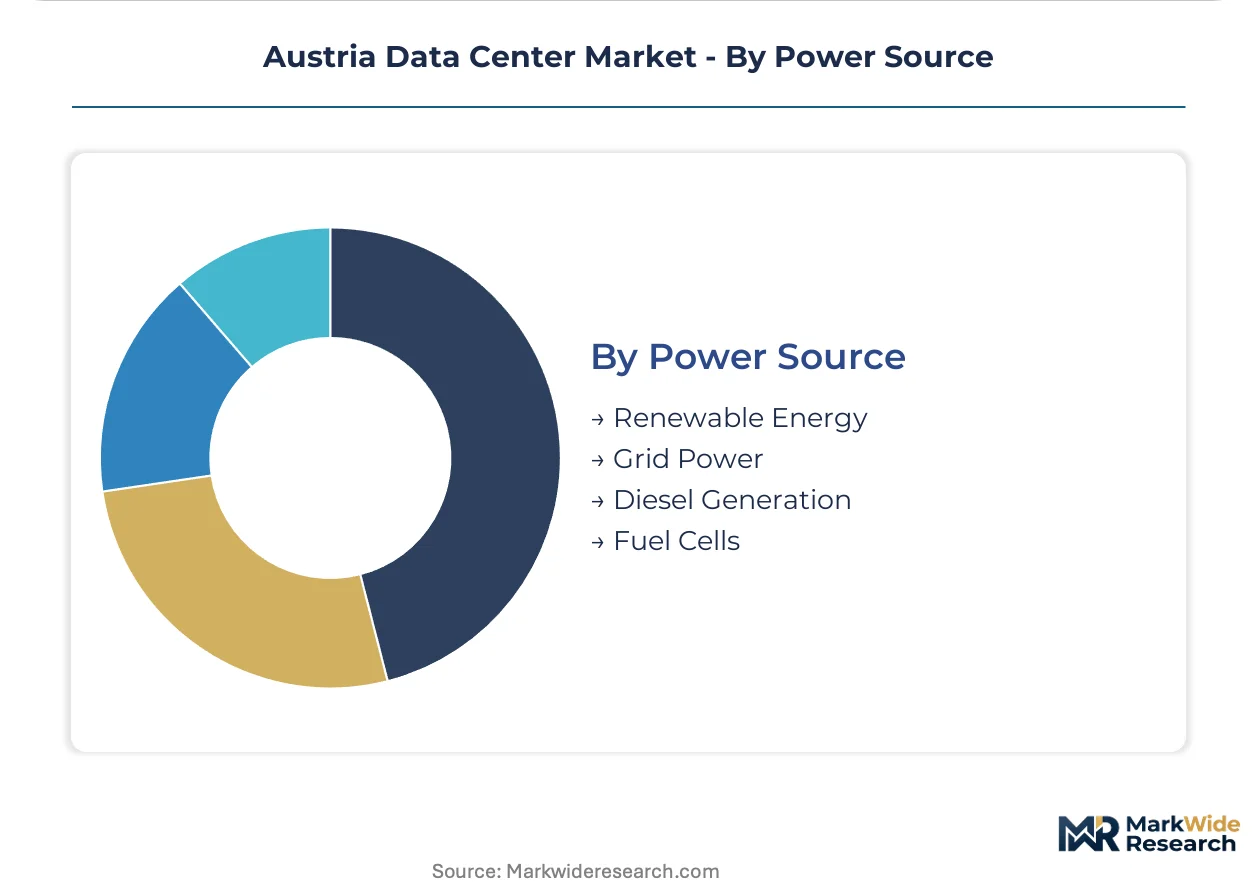
Power Source:
Carbon accounting obligations and grid reliability expectations shape sourcing portfolios.
- Renewable Energy:Wind, hydro, and solar power purchase agreements satisfy EU Green Deal mandates for carbon-neutral operations. Hyperscale operators contract 100% renewable supply through Vienna's metropolitan grid interconnection points.
- Grid Power:Utility electricity serves as primary feed with varying carbon intensity by Austrian federal state. Lower Austria and Styria expansion timelines lag demand, constraining greenfield site selection.
- Diesel Generation:Backup gensets provide emergency power during grid outages with Tier III and Tier IV uptime compliance. Provincial building codes govern fuel storage and emissions, inflating construction costs.
- Fuel Cells:Hydrogen and natural gas fuel cells offer extended runtime with lower emissions than diesel. Pilot deployments emerge at financial sector facilities seeking to eliminate generator maintenance and fuel logistics.
Grid power anchors current supply; renewable energy contracts are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands Europe's largest data center capacity while Austria accelerates faster on renewable power sourcing mandates. France and the Netherlands compete for hyperscale investment through interconnection density. Switzerland and Poland represent contrasting models: premium financial compliance versus cost-optimized scale deployment.
Germany
Hyperscale cloud providers and automotive AI training clusters drive Frankfurt's Rhine-Main corridor demand. The German Federal Network Agency enforces strict grid stability standards that shape power interconnection timelines. Bavaria's Munich tech cluster hosts GPU-intensive workloads requiring liquid cooling retrofits.
France
Financial services compliance and sovereign cloud requirements concentrate demand in Paris's metropolitan zone. ANSM and CNIL administer algorithmic transparency rules that elevate audit-ready colocation specifications. Ile-de-France's Saclay plateau attracts AI research facilities needing dense compute infrastructure.
Netherlands
Amsterdam's fiber-dense metro serves as Europe's primary internet exchange hub, attracting interconnection-focused operators. Dutch environmental regulations restrict data center construction in Amsterdam proper, shifting greenfield development to peripheral North Holland municipalities. Microsoft's hyperscale campus in Middenmeer exemplifies this peripheral migration pattern.
Switzerland
Swiss banking secrecy evolution and FINMA compliance standards sustain premium colocation pricing in Zurich and Geneva. Alpine hydroelectric abundance supports carbon-neutral power claims that attract financial sector tenants. Basel's pharmaceutical research corridor generates specialized HPC demand for molecular simulation workloads.
Poland
Cost arbitrage and EU structural fund availability position Warsaw as Central Europe's emerging hyperscale destination. Polish building codes permit faster construction timelines than Western European counterparts. Krakow's academic research institutions anchor initial GPU cluster deployments before commercial scaling.
Austria Data Center Market Competitive Landscape
Top-tier vendors anchor hyperscale campuses with dedicated substations, while regional specialists compete on compliance certification depth. The Austrian market exhibits tiered concentration: global operators with Vienna metro presence, domestic telecom incumbents with fiber backbone advantages, and financial-sector specialists with regulatory accreditation. Three archetypes dominate: interconnection-dense platform operators, compliance-certified banking infrastructure providers, and edge-deploying telecom-anchored networks. Capacity expansion and renewable power contracting constitute the dominant competitive moves.
Among global platform operators, Digital Realty Trust occupies a position exemplifying interconnection-centric campus development, while NTT Corporation represents the multinational carrier-neutral archetype with regional European integration. A1 Telekom Austria anchors the domestic telecom-anchored tier, leveraging national fiber infrastructure for distributed edge positioning. Raiffeisen Rechenzentrum sits within the financial-sector specialization archetype, occupying a compliance-focused niche that domestic banking regulation sustains.
| Leading Market Players |
|---|
| Digital Realty Trust |
| NTT Corporation |
| A1 Telekom Austria |
| AtlasEdge |
| Microsoft |
| Raiffeisen Rechenzentrum |
| GRZ IT Center |
| Magenta Telekom |
| Others |
Pricing and Supply Chain Analysis
Thermal engineering talent scarcity in Vienna's metropolitan corridor widens pricing spreads between liquid-cooled hyperscale deployments and air-cooled legacy facilities, compressing margins for operators unable to source specialized labor at scale.
Pricing Analysis
Capacity additions in Vienna's metropolitan corridor are reshaping price floors for colocation rack rates as hyperscale commitments absorb premium grid interconnection slots. Three-tier pricing structure across financial-grade compliance, standard enterprise, and economy wholesale levels separates buyers by audit-stringency requirements. Price differentiation rests on renewable power sourcing guarantees and liquid cooling availability. Cost compression in economy tiers intensifies because regional manufacturers negotiate volume discounts for disaster recovery positioning.
Supply Chain Analysis
Regional distribution centers for critical power equipment anchor in Germany, the Netherlands, and Switzerland, creating hub-and-spoke patterns for Austrian facility construction. Supply draws from German switchgear manufacturers, Dutch cooling system specialists, and Swiss precision electrical components. Single-source vulnerability concentrates in liquid cooling dielectric fluids produced by a narrow supplier base. Distribution runs through Vienna's logistics corridor for just-in-time delivery to active construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Austrian data center procurement has shifted toward premium specifications for EU AI Act compliance, elevating late-cycle quality over volume expansion.
For Market Incumbents: Anchor renewable power contracting positions before Lower Austria and Styria grid expansion bottlenecks tighten interconnection premiums. Defend against hyperscale self-build threats by deepening financial-sector compliance certifications that domestic banking regulation sustains. Prioritize liquid cooling engineering talent retention as GPU cluster deployments accelerate thermal density requirements. For New Entrants and Emerging Players: The mid-market wholesale gap between premium colocation and economy rack rates offers entry positioning for regional manufacturers seeking operational control without capital-intensive construction. Target Styria and Upper Austria for disaster recovery specialization where synchronous replication demand outstrips dual-campus supply. Pursue managed Kubernetes platform partnerships with Austrian software vendors lacking DevOps staffing. For Investors and Strategic Acquirers: Valuations sit cheapest among edge-deploying telecom-anchored networks with underutilized fiber backbone assets. Long-term viability centers on renewable power sourcing scalability and regulatory compliance depth rather than pure capacity scale. Monitor grid interconnection timeline announcements in Lower Austria as the inflection signal for greenfield development feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | Direct-to-chip systems absorb GPU-intensive AI training loads that Vienna's hyperscale operators now specify. |
| Renewable Power Purchase Agreement | 100% carbon-neutral contracts satisfy EU Green Deal mandates and attract financial sector tenants. |
| Financial Compliance Certification | EU AI Act audit requirements elevate Raiffeisen Rechenzentrum's regulatory accreditation as a competitive moat. |
| Provincial Edge Node Deployment | A1 Telekom Austria leverages national fiber backbone for low-latency compute in Salzburg and Tyrol business parks. |
| Dual-Campus Disaster Recovery Architecture | Geographically separated synchronous replication meets standalone procurement criteria for Styria manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center operators, thermal engineering contractors, and financial services infrastructure procurement officers alongside secondary validation through SEC hyperscaler filings, EIA power grid data, and EU regulatory documentation. Bottom-up facility deployment tracking and top-down energy demand modeling triangulated market sizing.
Segment-weighting approaches distributed value across colocation, hyperscale, wholesale, and edge facility types, with service model splits for Infrastructure as a Service, Platform as a Service, and disaster recovery offerings. Cooling technology and power source dimensions captured liquid cooling adoption velocity and renewable energy contracting trends across the analysis window. CAGRs derived from facility pipeline tracking and power commitment schedules, with grid interconnection timeline risk factors incorporated.
Caveats apply where grid expansion delays in Lower Austria and Styria or EU AI Act enforcement stringency could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Thailand Data Center Market