
 Data Center Solutions Market | 2026-2036
Data Center Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Solutions Market Analysis
Market Context with Strategic Players
Enterprise procurement channels for data center infrastructure is narrowing as hyperscalers bypass traditional distributors and contract directly with original equipment manufacturers. Amazon Web Services leverages its scale to secure custom silicon and power infrastructure at favorable terms. Microsoft Corporation anchors its expansion through long-term leases with Equinix and Digital Realty across primary metros. Google LLC differentiates through vertically integrated energy procurement and proprietary cooling designs that reduce operational expenditure.
Technical Definition and Structural Segments
Data center solutions encompass integrated hardware, software, and services for housing, powering, cooling, and interconnecting compute and storage resources, typically operating within temperature ranges of 18°C to 27°C per ASHRAE guidelines and achieving power usage effectiveness ratios below 1.3 in leading facilities. Edge computing deployments represent the fastest-expanding technology segment as latency-sensitive applications proliferate in manufacturing and autonomous systems. Colocation services command premium pricing in supply-constrained European and Asian metros where land and power permits face extended approval cycles. Servers and networking equipment absorb the majority of capital expenditure, though power supplies and thermal management solutions capture expanding margin pools as density requirements intensify.
Regulatory Framework and Outlook
EPA energy efficiency mandates and EU F-Gas Regulation restrictions on synthetic refrigerants are accelerating liquid cooling adoption and reshaping equipment specifications across North America and Europe. India's BIS certification requirements and PLI scheme incentives for domestic electronics manufacturing are redirecting supply chain investments toward Chennai and Hyderabad production corridors. NTT Global Data Centers and Huawei Technologies navigate divergent compliance regimes as they expand in OECD and non-OECD markets respectively. Stakeholders must monitor evolving carbon disclosure rules and local content requirements that increasingly determine facility siting and vendor qualification decisions.
Market Dynamics
AI training workloads are compressing server refresh cycles and forcing wholesale infrastructure redesigns as thermal density thresholds breach air-cooling limits across hyperscale facilities.
Growth Catalysts
- EPA Energy Efficiency Standards:Mandates for power usage effectiveness below 1.3 in federal procurement are accelerating liquid-cooled server deployments across US government and enterprise data centers.
- Edge Computing Proliferation:Autonomous manufacturing systems and industrial IoT in Germany and Japan are driving micro-data center installations for sub-10 millisecond latency requirements.
- India PLI Scheme Incentives:Domestic electronics manufacturing subsidies are redirecting server and networking equipment production toward Chennai and Hyderabad corridors.
Market Restraints
- Power Infrastructure Bottlenecks:Transmission interconnection queues exceeding 36 months in Northern Virginia and Singapore are delaying hyperscale campus energization.
- Fluorinated Gas Restrictions:EU F-Gas Regulation phase-downs are eliminating synthetic refrigerant options for legacy cooling retrofits before liquid alternatives achieve cost parity.
- Specialized Engineering Talent Scarcity:Liquid cooling system design and thermal-fluid dynamics expertise concentrates among a limited pool of contractors in OECD markets.
Strategic Opportunities
- Sovereign Cloud Facilities:Data localization mandates in Germany, India, and UAE are creating certified facility requirements that domestic operators can capture.
- Direct Liquid Cooling Convergence:Integration of immersion cooling with high-performance computing workloads opens margin expansion in research and financial services segments.
- Utility-Scale Energy Procurement:Long-term power purchase agreements with renewable generators are emerging as a differentiated channel for facility operators securing below-grid pricing.
Industry Challenges
- ASHRAE Compliance Integration:Legacy raised-floor facilities face complex retrofit engineering to meet revised thermal guidelines while maintaining operations.
- Supply Chain Reconfiguration Friction:Relocation of critical component manufacturing from established Asian hubs to India and Southeast Asia is disrupting qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Solutions Market |
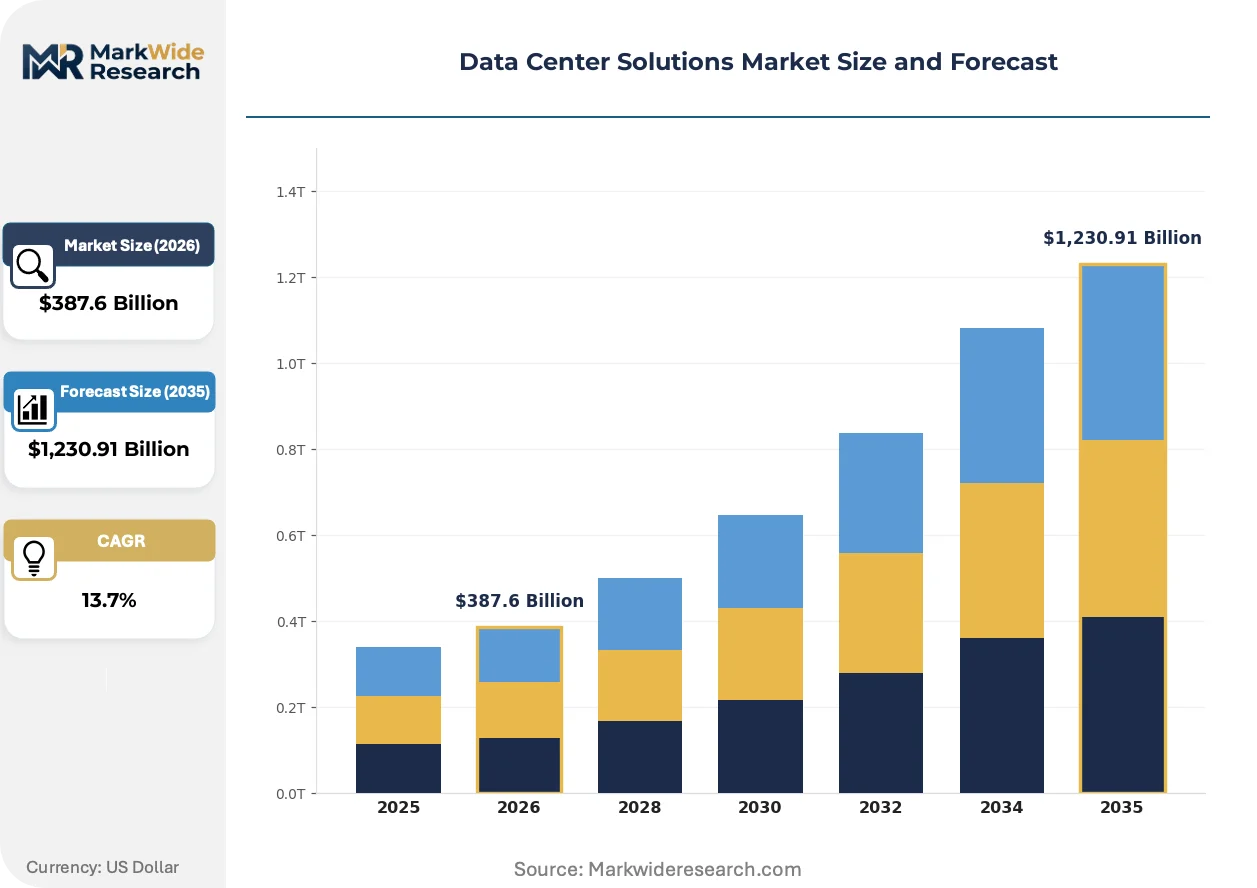
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,230.91 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Storage Systems, Networking Equipment, Power Supplies Technology: Virtualization, Cloud Computing, Edge Computing, Hyper-Converged Infrastructure Deployment: On-Premises, Cloud-Based, Hybrid, Colocation End User: IT Companies, Telecommunications, Government, Healthcare Providers |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, Equinix, Digital Realty, Huawei Technologies, Dell Technologies, NTT Global Data Centers, CyrusOne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Solutions Market Emerging Trajectories
Computational virtualization is collapsing the boundary between hardware and software infrastructure layers, enabling workload portability that challenges traditional capital deployment models.
Software-defined power distribution is virtualizing electrical infrastructure management across hyperscale facilities. Cloud operators in Northern Virginia and Frankfurt are adopting intelligent rack-level power delivery that enables dynamic workload balancing. This architecture is virtualizing the traditional electrical hierarchy and compressing margins for conventional uninterruptible power supply vendors.
EU F-Gas Regulation restrictions on synthetic refrigerants are prohibiting hydrofluorocarbon-based cooling systems in new European data center construction. Equipment manufacturers are accelerating natural refrigerant and liquid cooling platform development to maintain market access. German and Dutch facility operators are responding with direct evaporative and immersion cooling retrofits that exceed baseline efficiency requirements.
Enterprise procurement patterns are fragmenting as mid-market buyers bypass traditional systems integrators for direct OEM relationships. Colocation providers in Singapore and Mumbai are unbundling managed services and offering bare-metal infrastructure to capture price-sensitive demand. This disintermediation is most visible in financial services and SaaS verticals where technical staffing permits self-managed deployments.
Data Center Solutions Market Segmentation
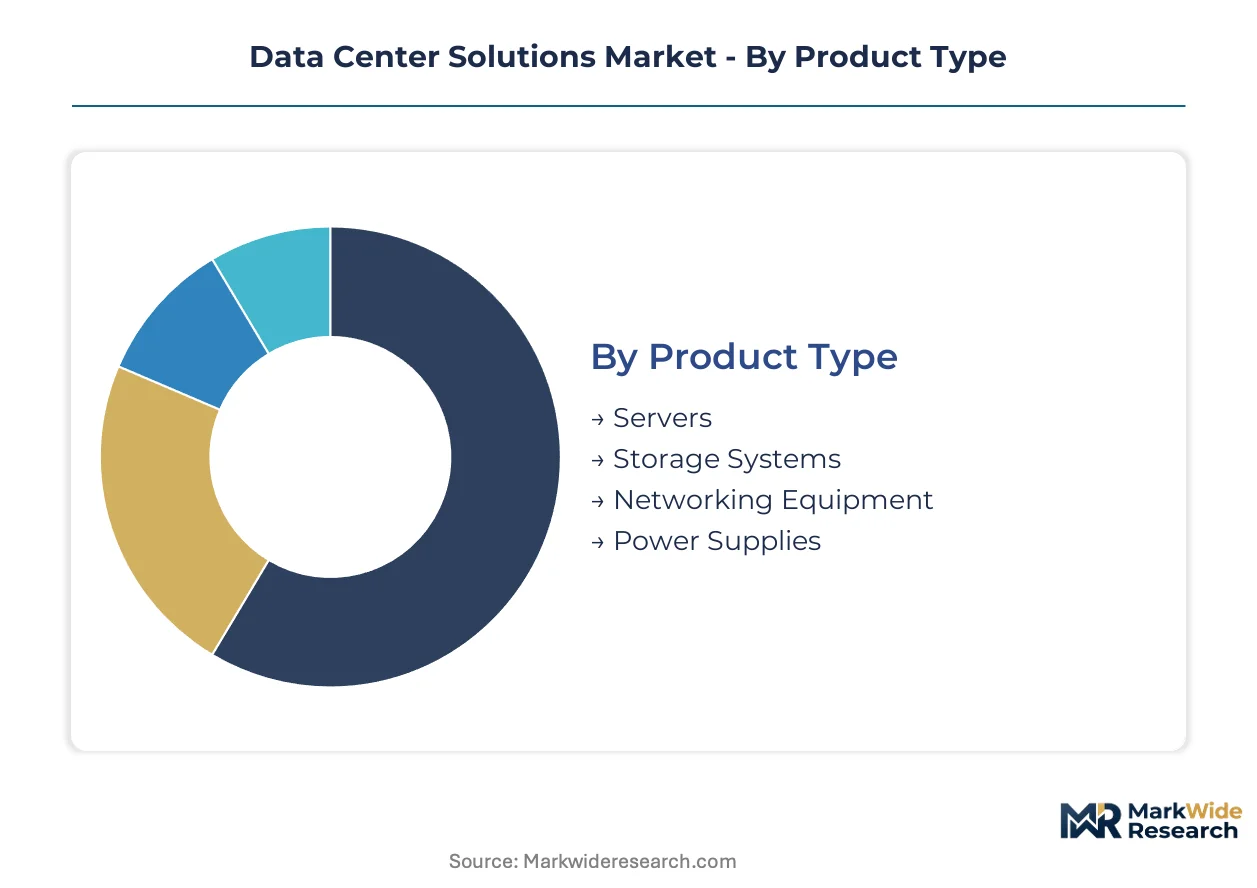
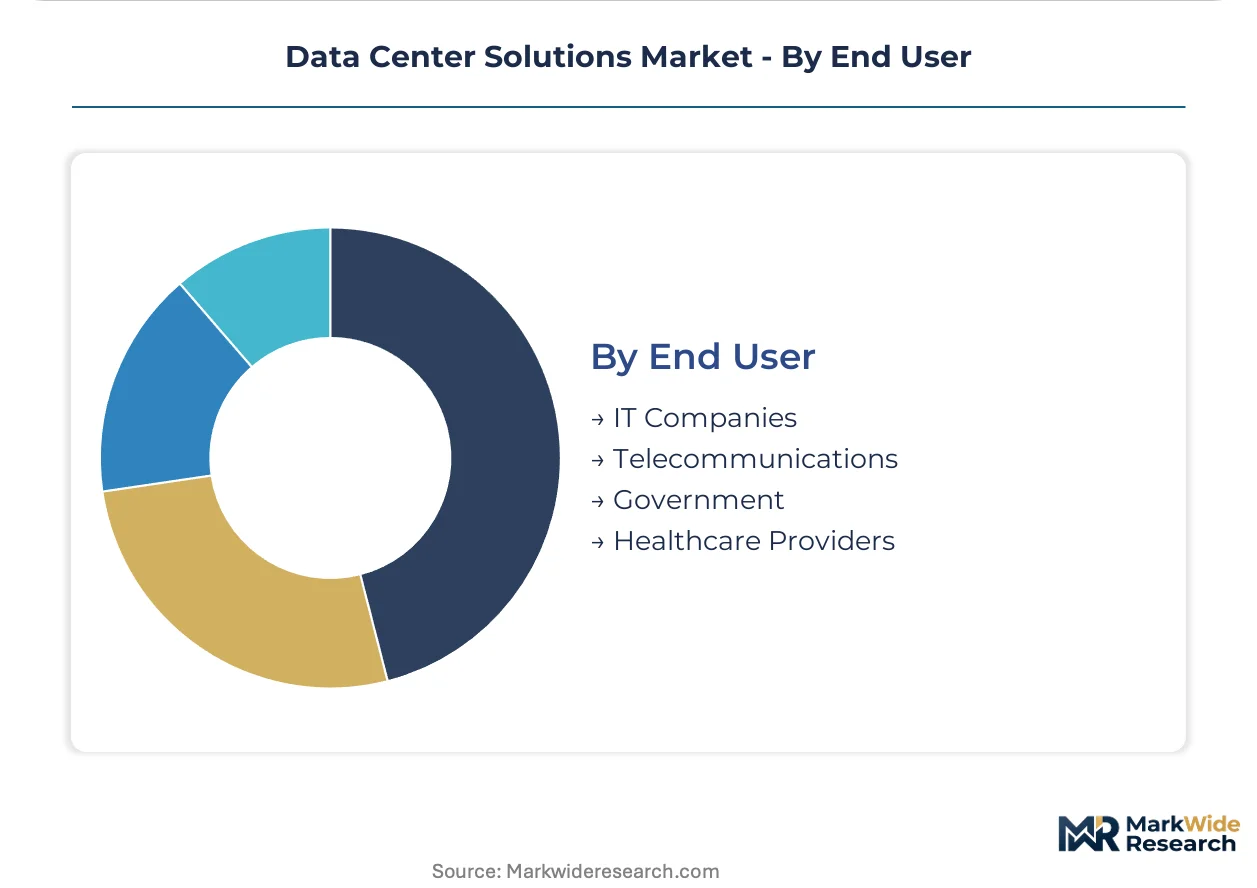
Segmentation in data center solutions reveals divergent procurement patterns across infrastructure layers. Product and technology choices determine service intensity, refresh cycles, and vendor relationships throughout facility lifecycles.
Product Type:
After-sales service intensity varies sharply across hardware categories, with thermal management and power systems requiring continuous monitoring while storage assets follow predictable replacement schedules.
- Servers:Rack-mounted and blade configurations dominate hyperscale deployments, with liquid-cooled variants capturing expanding share in AI training environments. Northern Virginia and Frankfurt operators prioritize high-density units that breach traditional air-cooling thresholds.
- Storage Systems:All-flash arrays and software-defined storage platforms absorb capital allocation as data retention mandates tighten. Healthcare providers in Germany and financial institutions in Singapore drive demand for encrypted, low-latency tiers.
- Networking Equipment:Spine-leaf architectures and 400G switching fabrics enable east-west traffic patterns in distributed computing environments.
- Power Supplies:Intelligent rack-level distribution units with embedded metering support dynamic workload balancing across multi-tenant facilities.
By volume, servers lead procurement activity. By growth pace, power supplies are ahead as density requirements reshape electrical infrastructure specifications.
Technology:
Cost tier stratification separates commodity virtualization from premium edge deployments, with mid-market buyers gravitating toward converged platforms that bundle management overhead.
- Virtualization:Hypervisor abstraction enables workload portability across heterogeneous hardware pools, compressing capital deployment timelines for enterprise IT departments.
- Cloud Computing:Public and private cloud orchestration layers dominate new capacity planning, with sovereign cloud variants capturing regulated industry demand in India and the UAE.
- Edge Computing:Micro-data centers and containerized deployments address sub-10 millisecond latency requirements in autonomous manufacturing and industrial IoT applications across Germany and Japan.
- Hyper-Converged Infrastructure:Integrated compute-storage-networking stacks simplify procurement for mid-market buyers lacking specialized engineering resources.
Cloud computing commands the largest installed base. Edge computing is expanding most quickly as latency-sensitive applications proliferate beyond core metro facilities.
Deployment:
Customer type determines deployment architecture, with regulated enterprises favoring controlled environments while digital-native firms pursue consumption-based models.
- On-Premises:Enterprise-owned facilities retain relevance for classified workloads and specialized compliance requirements in government and defense segments.
- Cloud-Based:Hyperscale public cloud absorbs the majority of net new capacity, with AWS, Microsoft Azure, and Google Cloud capturing workload migration from legacy data centers.
- Hybrid:Orchestrated workload placement across on-premises and cloud environments addresses data sovereignty and performance optimization requirements simultaneously.
- Colocation:Multi-tenant facilities in supply-constrained Singapore and Mumbai metros command premium pricing for certified infrastructure and interconnection density.
Cloud-based deployment leads by volume. Hybrid architectures are gaining share fastest as enterprises balance agility with control requirements.
End User:
Application-specific demands reshape infrastructure specifications, with latency, compliance, and scale requirements diverging sharply across verticals.
- IT Companies:SaaS providers and technology vendors drive hyperscale capacity absorption, with custom silicon and direct liquid cooling investments compressing operational expenditure.
- Telecommunications:5G network densification and edge computing requirements are redirecting carrier capital toward distributed micro-data center footprints.
- Government:Federal procurement mandates under EPA efficiency standards are accelerating liquid-cooled server deployments across US government data centers.
- Healthcare Providers:HIPAA compliance and medical imaging storage requirements prioritize encrypted, geographically redundant infrastructure with guaranteed availability.
IT companies dominate procurement volume. Healthcare providers are expanding fastest as telemedicine and AI diagnostics reshape data infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Singapore exceeds that in Northern Virginia by substantial margins as transmission interconnection queues stretch beyond three years in the American hub while Asian supply constraints persist.
United States
Federal procurement mandates and hyperscale AI training clusters drive demand concentration in Northern Virginia and Dallas-Fort Worth. EPA energy efficiency standards for power usage effectiveness below 1.3 accelerate liquid-cooled server deployments across government and enterprise facilities. Northern Virginia's data center alley faces 36-month utility interconnection delays despite sustained campus expansion by AWS and Microsoft.
Germany
Sovereign cloud certification requirements and automotive edge computing applications reshape infrastructure procurement in Frankfurt and Berlin corridors. EU F-Gas Regulation phase-downs prohibit synthetic refrigerants in new construction, forcing natural refrigerant and immersion cooling retrofits. Frankfurt's financial services cluster commands premium colocation pricing as land and power permits face extended approval cycles.
India
Data localization mandates and domestic electronics manufacturing incentives redirect supply chain investments toward Chennai and Hyderabad production corridors. BIS certification requirements and PLI scheme subsidies for server and networking equipment accelerate local assembly capacity. Mumbai's financial district and Bangalore's technology corridor absorb expanding hyperscale and colocation demand.
Singapore
Submarine cable interconnection density and regional financial services demand sustain premium pricing despite moratorium-lifted capacity constraints. Land scarcity and power infrastructure bottlenecks limit new entrant supply while incumbent operators expand through vertical development. The Jurong and Tanjong Kling industrial estates concentrate liquid-cooled facility investments serving ASEAN latency requirements.
Japan
Autonomous manufacturing systems and industrial IoT applications drive micro-data center proliferation for sub-10 millisecond latency in Osaka and Nagoya industrial zones. METI efficiency guidelines and carbon neutrality commitments reshape thermal management specifications. Tokyo's financial district and Fukuoka's emerging technology corridor anchor hybrid cloud and edge computing deployments.
Data Center Solutions Market Vendor Landscape
Hyperscale cloud operators and specialized colocation providers split the market between vertically integrated infrastructure stacks and multi-tenant facility services. Consolidation concentrates capacity planning authority among AWS, Microsoft Azure, and Google Cloud as direct OEM procurement displaces traditional distribution channels. Three archetypes dominate: cloud-native vertical integrators, neutral-host colocation specialists, and equipment-integrated solution vendors. Competitive moves center on long-term renewable energy procurement and liquid cooling technology partnerships.
Within the cloud-native tier, Amazon Web Services and Microsoft Corporation exemplify scale-driven vertical integration into custom silicon and power infrastructure. Equinix and Digital Realty occupy positions as neutral-host specialists with interconnection density advantages in supply-constrained metros. NTT Global Data Centers and Huawei Technologies represent geographically divergent expansion patterns across OECD and non-OECD compliance regimes respectively.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| Equinix |
| Digital Realty |
| Huawei Technologies |
| Dell Technologies |
| NTT Global Data Centers |
| CyrusOne |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese semiconductor foundries determines both the customization-premium spread for AI-optimized servers and the geographic concentration of supply chain investments. Buyers face extended lead times for liquid-cooled configurations while standard rack units flow through established distribution channels.
Pricing Analysis
The customization-premium spread separates configured-to-order liquid-cooled deployments from standard air-cooled rack units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because hyperscalers negotiate direct OEM contracts that bypass distributor margins. Mid-market colocation providers exhibit highest price sensitivity, while sovereign cloud operators in Germany and UAE accept substantial premiums for certified infrastructure.
Supply Chain Analysis
Supplier-financing facilities from Taiwanese and South Korean component manufacturers extend payment terms for qualified hyperscale buyers. Manufacturing concentration in Taiwan, China, and South Korea feeds from advanced packaging substrates, high-bandwidth memory modules, and precision cooling components. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure for leading-edge server chips. Distribution runs through direct OEM relationships for top-tier cloud operators and authorized distributor networks for enterprise and mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Certification requirements and interconnection density create switching costs that protect incumbent positions.
For Market Incumbents: Build switching-cost moats through long-term interconnection contracts and sovereign cloud certifications that lock in regulated enterprise workloads. Deepen backward integration into custom silicon design to defend margin position against emerging ARM-based entrants. Prioritize liquid cooling R&D partnerships as air-cooling limits force infrastructure redesigns. For New Entrants and Emerging Players: Build out sovereign cloud facilities in India and UAE where data localization mandates create certified infrastructure gaps. Target price-sensitive mid-market colocation in supply-constrained Singapore and Mumbai metros. Pursue bare-metal infrastructure positioning to capture financial services and SaaS verticals with self-managed deployment capabilities. For Investors and Strategic Acquirers: Neutral-host colocation specialists with interconnection density in constrained metros represent the most compelling acquisition archetype. Long-term viability hinges on renewable energy procurement positioning and liquid cooling technology access. Monitor utility interconnection queue lengths as inflection indicator for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Deployment | Immersion cooling partnerships with NVIDIA and AMD capture AI training workload premiums in Northern Virginia. |
| Renewable Energy Procurement | Long-term power purchase agreements with offshore wind developers secure below-grid pricing for Frankfurt facilities. |
| Sovereign Cloud Certification | BIS and MeitY compliance investments unlock government and financial services demand across Indian metros. |
| Custom Silicon Development | In-house ARM-based processor design reduces dependency on Intel and AMD for hyperscale compute deployments. |
| Edge Computing Infrastructure | Containerized micro-data centers address sub-10 millisecond latency requirements in German automotive zones. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, EPA regulatory dockets, and EU F-Gas Regulation implementation guidance. Data center operators, thermal engineering contractors, and enterprise IT procurement officers provided operational perspectives. Customs records and interconnection pricing databases supplied trade flow validation. Bottom-up facility-level capacity estimates triangulate against top-down market sizing across the analysis window.
Forecast inputs span product type segmentation by thermal density tier, deployment model by sovereignty requirements, and end-use vertical by latency sensitivity. Cloud computing, edge computing, and colocation service lines anchor the segmentation framework. CAGRs derive from facility pipeline tracking and equipment shipment analysis. Power usage effectiveness trajectories and liquid cooling penetration curves inform infrastructure investment projections throughout the modeling period.
Stress conditions across utility interconnection timelines, F-Gas Regulation phase-down schedules, and PLI scheme incentive continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale expansion rates and sovereign cloud mandate enforcement. Macroeconomic contraction, regulatory delay, or breakthrough cooling technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Vietnam Data Center Market