
 Global Sodium Acetate Market | 2026-2036
Global Sodium Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Acetate Market Foresight
The capital-intensity divergence between integrated acetic acid producers and standalone sodium acetate converters is rotating competitive advantage toward backward-linked manufacturers. BASF SE leverages captive acetic acid supply to sustain margin resilience across European pharmaceutical and food additive contracts. Changshu Nanhu Chemical anchors Asia-Pacific volume through integrated coastal production, while Niacet Corporation specializes in high-purity grades for North American pharmaceutical excipient demand.
Sodium acetate is the sodium salt of acetic acid, available primarily as anhydrous (NaC₂H₃O₂) or trihydrate (NaC₂H₃O₂·3H₂O) forms, manufactured through neutralization of acetic acid with sodium carbonate or sodium hydroxide followed by crystallization and drying. It functions as a pH buffering agent, food preservative, concrete accelerator, and pharmaceutical excipient across industrial and consumer applications. The trihydrate segment dominates commercial volume due to lower production energy requirements, though anhydrous grades command premium positioning in pharmaceutical and thermoplastic processing applications where moisture sensitivity dictates specification. Food additive demand within the application dimension tracks expanding processed food output, while pharmaceutical-grade requirements tighten around compendial compliance.
FDA excipient guidelines, REACH substance registration, and FSSAI food additive standards collectively elevate purity documentation burdens and restrict market access for uncertified producers. These frameworks shift procurement criteria toward suppliers with validated manufacturing records and multi-jurisdiction regulatory filings. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs, as divergence in heavy metal and impurity limits threatens to fragment specification requirements and complicate global sourcing strategies.
Market Dynamics
Integrated acetic acid producers are consolidating feedstock control, forcing standalone sodium acetate converters into margin compression as captive supply chains lock in pharmaceutical and food-grade contracts. This backward-linkage advantage is redrawing competitive boundaries across manufacturing tiers.
Growth Catalysts
- REACH substance registration:European chemical compliance is filtering out uncertified suppliers and concentrating procurement among validated manufacturers with multi-jurisdiction filings.
- Intravenous fluid formulations:Pharmaceutical firms are expanding sodium acetate adoption for parenteral nutrition and dialysis solutions, tightening purity specifications across compendial grades.
- China:Domestic chemical manufacturing scale and food processing output are concentrating volume demand in coastal production clusters.
Market Restraints
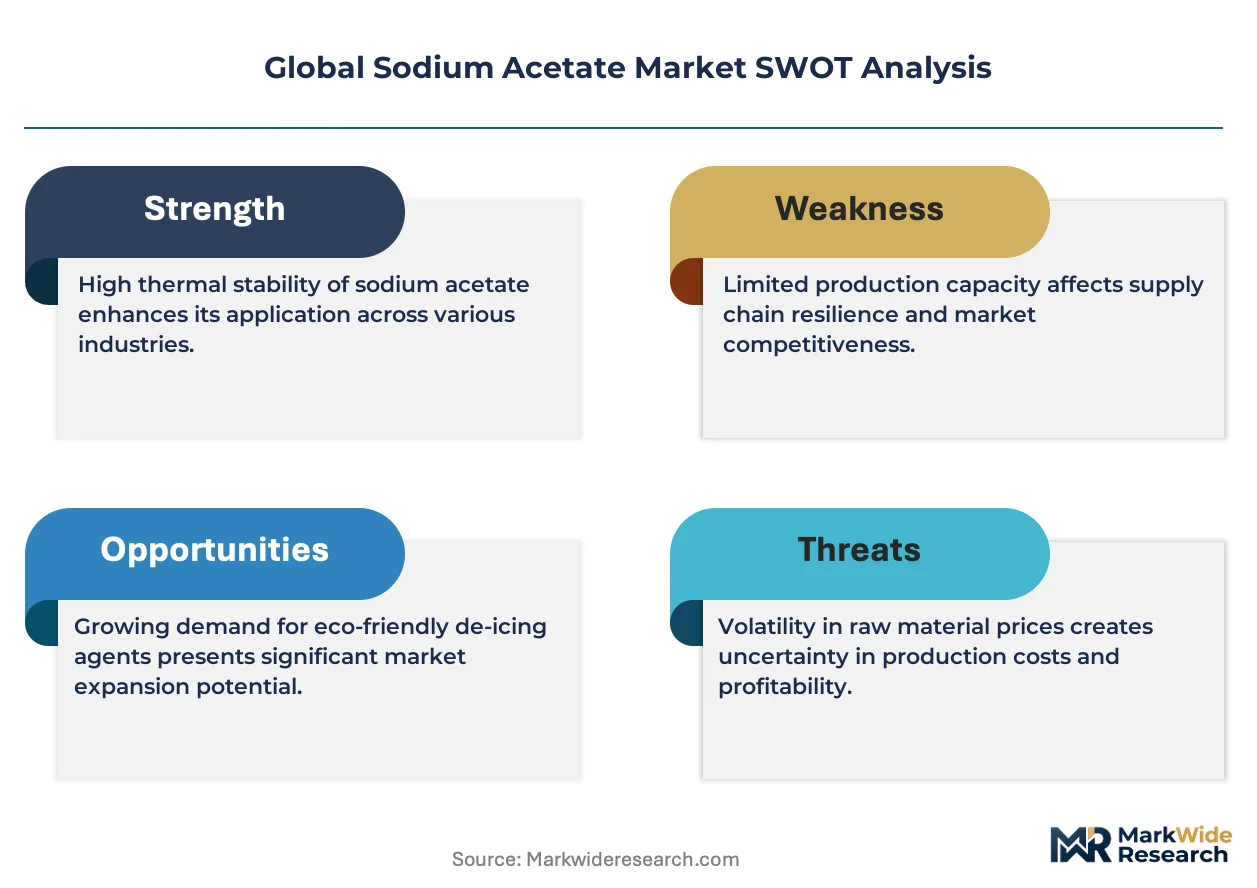
- Acetic acid price volatility:Feedstock cost swings compress margins for non-integrated converters lacking captive supply.
- Supplier concentration in East Asia:Heavy reliance on Chinese and Korean bulk chemical producers creates geographic supply risk.
- Formic acid substitution:Lower-cost organic salts are displacing sodium acetate in select concrete acceleration and de-icing applications.
Strategic Opportunities
- India FSSAI food additive standards:Evolving domestic safety frameworks are creating qualification windows for exporters with pre-validated manufacturing records.
- Biodegradable thermoplastics:Sodium acetate is miniaturizing into novel polymer processing applications as a nucleating agent for polylactic acid blends.
- Direct-to-pharma distribution:Bypassing traditional chemical distributors for excipient supply contracts is capturing margin from qualified manufacturers.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent USP, EP, and JP heavy metal limits complicate global sourcing and batch certification workflows.
- Crystallization engineering talent:Specialized process control expertise for anhydrous grade production remains concentrated among legacy European and Japanese firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Acetate Market |
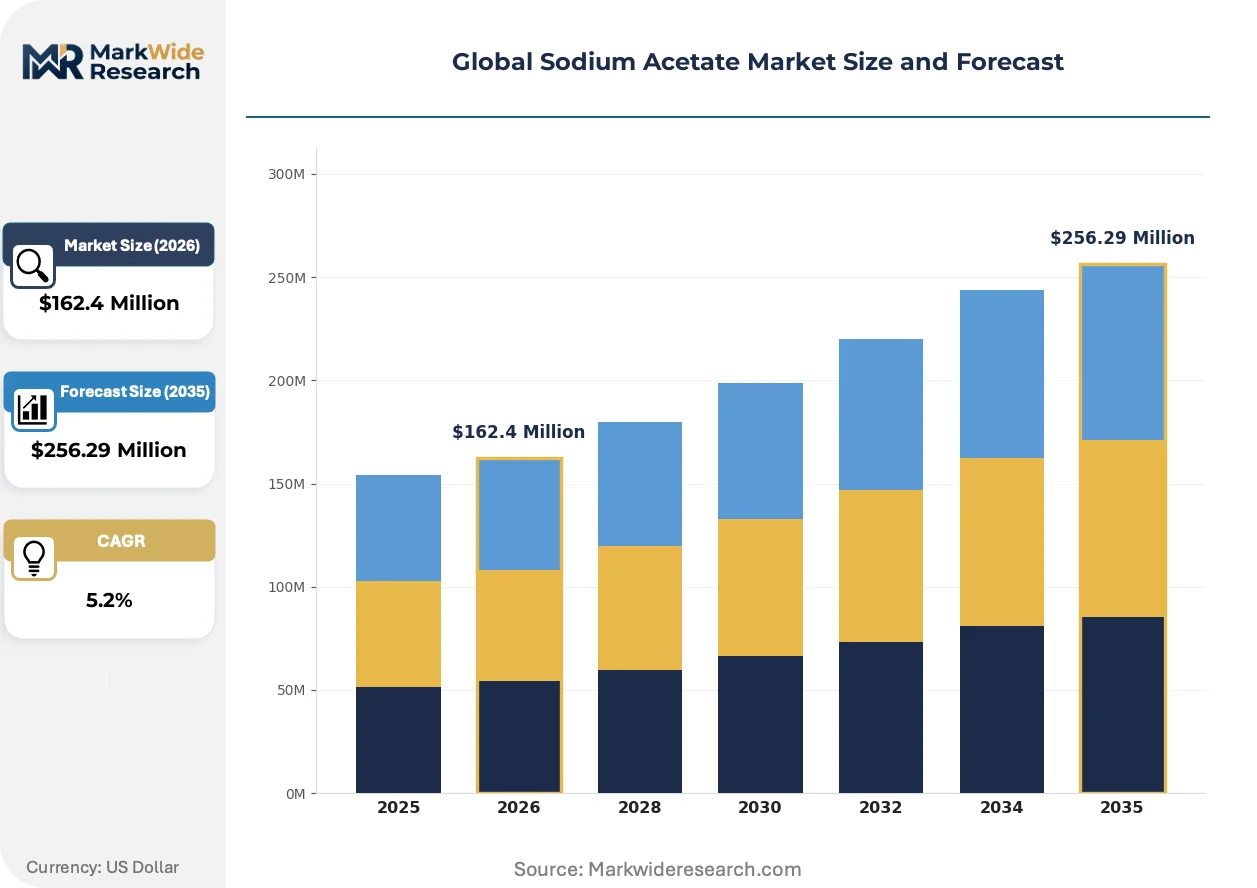
| Market Size in 2026 | $162.4 Million |
| Market Size in 2035 | $256.29 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Trihydrate, Powder, Granular, Flake Application: Food Additive, Textile Printing, Concrete Sealant, Thermoplastic Processing, Pharmaceuticals End User Industry: Chemical Manufacturing, Construction, Apparel Production, Food Processing, Pharmaceutical Firms Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Cardboard Boxes |
| Companies Covered | BASF SE, Merck KGaA, Eastman Chemical Company, Lonza, Changshu Nanhu Chemical, CABB, American Elements, Niacet Corporation, Tokyo Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Acetate Market Shifts & Advancements
Continuous crystallization technology and regulatory data integrity mandates are compressing batch-to-batch variation while expanding real-time quality verification across pharmaceutical supply chains.
Membrane-based purification is miniaturizing impurity profiles in high-purity sodium acetate production. Pharmaceutical excipient manufacturers in Germany and Switzerland are adopting these systems to meet tightening EMA guidelines on elemental impurities. The technology is compressing validation timelines for new supplier qualification.
EMA's revised excipient risk assessment guidelines are forcing documented supply chain transparency down to the acetic acid origin. European formulators must now maintain audit trails through multiple chemical conversion tiers. This is accelerating consolidation among suppliers with integrated production and captive feedstock.
Specification-driven procurement is fragmenting buyer segments into compendial-grade and technical-grade pools. Large pharmaceutical compounders in the United States are unbundling excipient sourcing from general chemical purchasing, creating dedicated supplier panels with multi-year qualification investments. This shift is most visible in parenteral and ophthalmic formulation supply chains.
Global Sodium Acetate Market Segmentation
Sodium acetate procurement splits sharply between commodity bulk buyers seeking lowest unit cost and specification-driven formulators demanding compendial documentation. Substitution threats from formic acid salts and citrate buffers concentrate in lower-purity segments, reshaping where manufacturers invest crystallization and purification capacity.
Product Type:
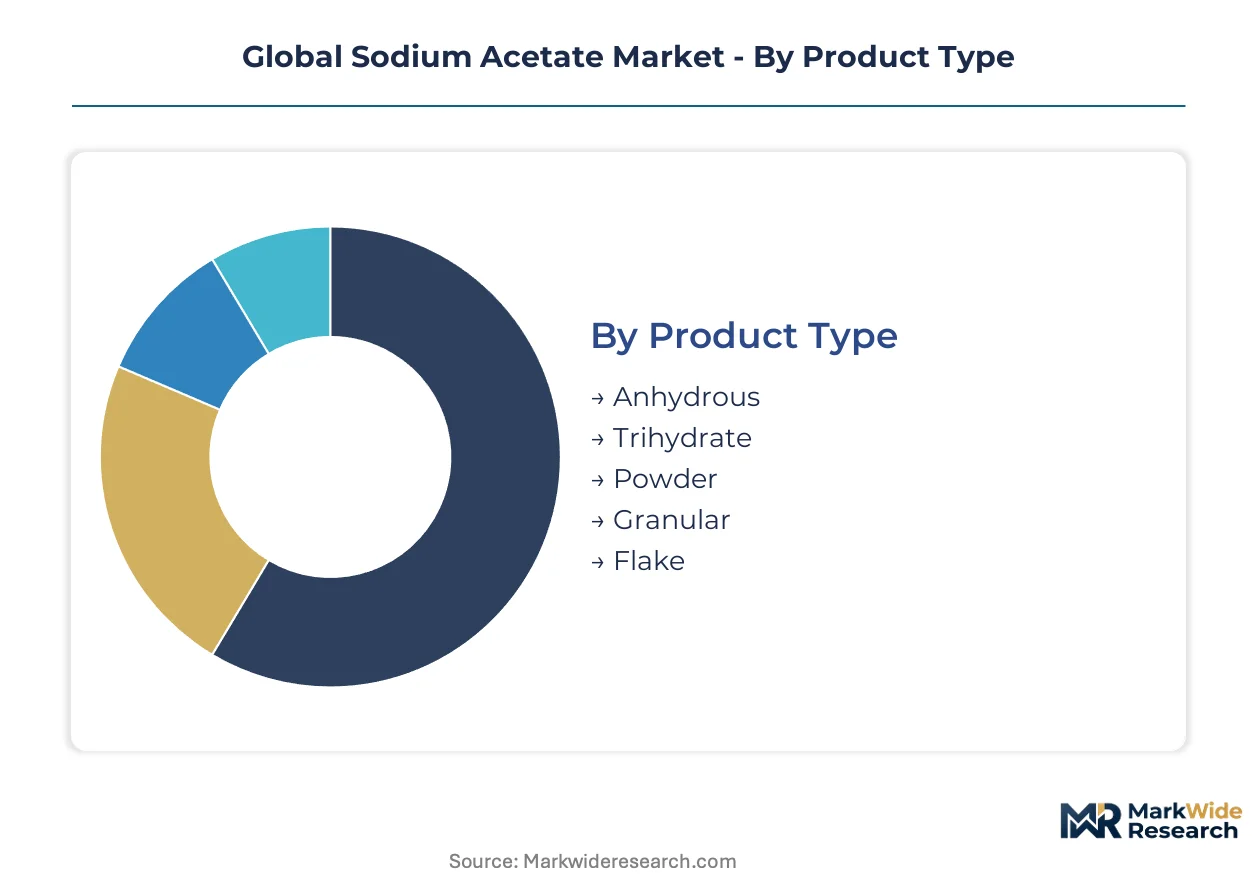
Trihydrate crystalline forms face the most acute substitution pressure from cheaper organic salts in concrete and de-icing applications, while anhydrous grades defend their position through moisture-critical pharmaceutical and polymer specifications.
- Anhydrous:The water-free crystalline form (NaC₂H₃O₂) demands higher drying energy and specialized crystallization control. Pharmaceutical excipient demand in Germany and Switzerland concentrates here, driven by parenteral formulation moisture limits and EMA guidelines on elemental impurities.
- Trihydrate:The hydrated crystalline form (NaC₂H₃O₂·3H₂O) dominates commercial volume through lower production energy requirements. Food processing demand in China absorbs the largest share, though formic acid displacement in concrete acceleration threatens margin in construction-grade contracts.
- Powder:Finely milled particulate format for rapid dissolution in aqueous systems. Textile printing houses in India favor this grade for dye bath pH adjustment.
- Granular:Free-flowing crystalline particles optimized for mechanical handling. Bulk chemical distributors stock this format for industrial blending operations.
- Flake:Thin crystalline sheets produced through drum flaking. Concrete sealant formulators in the United States specify flakes for controlled dissolution rates.
Trihydrate anchors the volume base while anhydrous gains share at the steepest rate.
Application:
Cost tier stratification separates commodity industrial uses from premium compendial grades, with purity documentation requirements determining viable supplier pools.
- Food Additive:pH buffering and preservative functions in processed foods. FSSAI compliance in India and SAMR standards in China are tightening impurity documentation for imported material.
- Textile Printing:Dye bath pH stabilization and color fixation. Apparel production clusters in Bangladesh and Vietnam drive regional demand concentration.
- Concrete Sealant:Acceleration of cement hydration and surface hardening. Formic acid substitution pressure is most severe here, compressing sodium acetate to specification-critical architectural applications.
- Thermoplastic Processing:Nucleating agent for polylactic acid and biodegradable polymer blends. German compounders are piloting sodium acetate in sustainable packaging formulations.
- Pharmaceuticals:Excipient for intravenous fluids, dialysis solutions, and ophthalmic preparations. USP, EP, and JP monograph compliance creates the highest barrier to supplier entry.
Food additive volume dominates current offtake while thermoplastic processing climbs fastest among emerging applications.
End User Industry:
Customer type fragmentation splits procurement between price-sensitive bulk chemical buyers and qualification-heavy pharmaceutical formulators.
- Chemical Manufacturing:Intermediate production and reagent supply. Integrated acetic acid producers in China and South Korea capture backward-linked margin here.
- Construction:Concrete admixture and sealant formulation. This segment faces the steepest substitution threat from formic acid salts in cost-driven emerging markets.
- Apparel Production:Textile dyeing and finishing operations. Bangladesh's garment export sector concentrates regional demand.
- Food Processing:Preservative and pH control in packaged foods. China's domestic food manufacturing scale absorbs the largest national volume.
- Pharmaceutical Firms:Parenteral and ophthalmic excipient supply. Multi-year qualification investments and audit trail requirements lock in supplier relationships.
Food processing anchors the volume base while pharmaceutical firms expand specification premiums fastest.
Packaging Type:
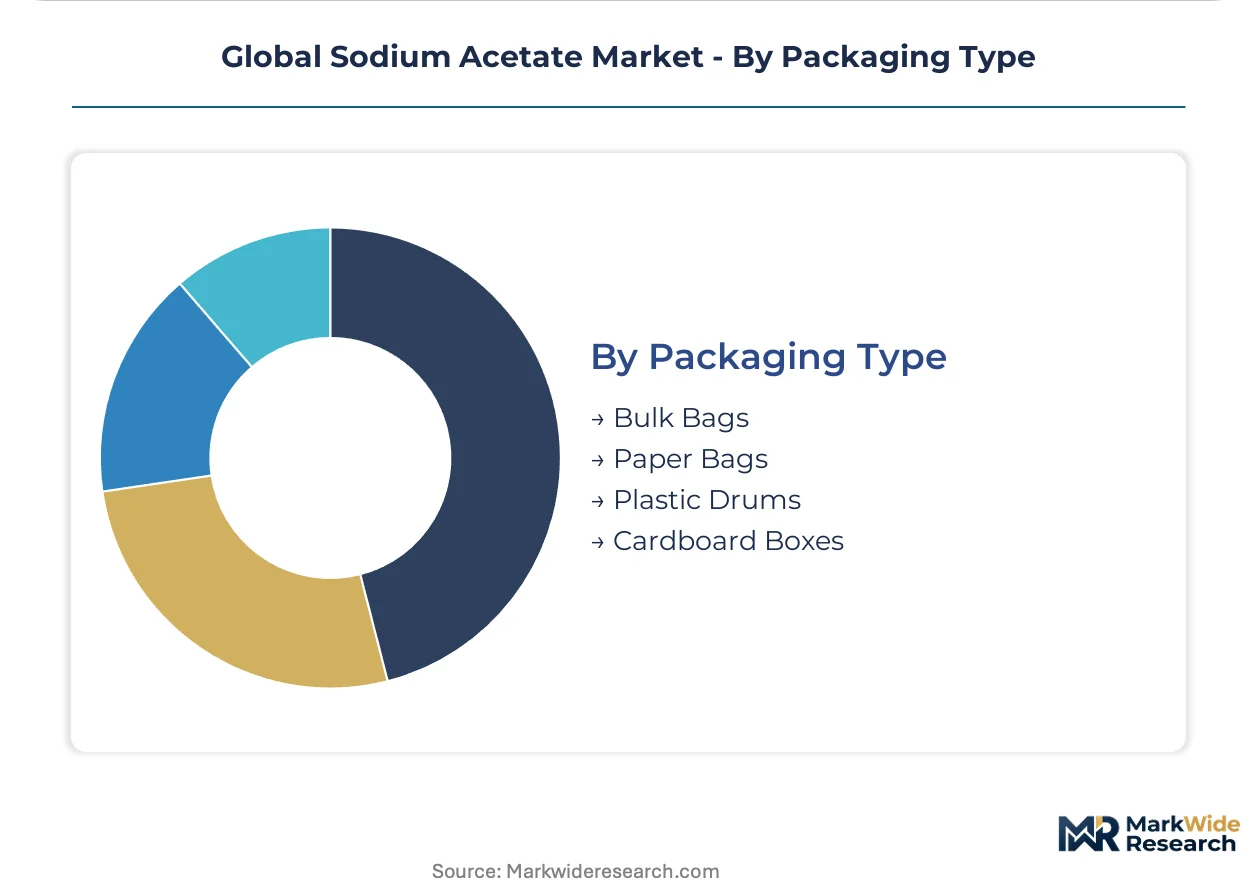
Supply concentration in coastal Chinese production clusters dictates bulk packaging dominance for export logistics.
- Bulk Bags:Flexible intermediate bulk containers for tanker and railcar transfer. Chemical manufacturing buyers in the United States and Germany standardize on this format.
- Paper Bags:Multi-wall kraft construction for food-grade and technical-grade material. FSSAI-compliant exporters to India favor this format for customs inspection accessibility.
- Plastic Drums:Sealed containment for moisture-sensitive anhydrous grades. Pharmaceutical excipient shipments to Swiss and German compounders require this packaging tier.
- Cardboard Boxes:Retail and laboratory-scale distribution. Lowest volume share but highest per-kilogram packaging cost.
Bulk bags anchor the volume base while plastic drums expand fastest on pharmaceutical grade growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical corridors while Chinese coastal producers dominate volume throughput at compressed margins. This asymmetry shapes procurement strategies across compendial-grade and technical-grade segments.
China
Domestic food processing scale and chemical manufacturing expansion absorb the largest national sodium acetate volume. SAMR standards on food additive impurities are tightening documentation requirements for coastal exporters. Changshu clusters in Jiangsu province anchor trihydrate production for processed food and textile dyeing applications.
Germany
Pharmaceutical excipient demand and biodegradable polymer compounding drive premium-grade consumption. EMA guidelines on elemental impurities and excipient risk assessment mandate documented supply chain transparency. BASF SE leverages Ludwigshafen acetic acid integration to serve Swiss and domestic parenteral formulation contracts.
United States
Intravenous fluid manufacturers and concrete sealant formulators split demand across purity tiers. FDA excipient guidelines and USP monograph compliance create qualification barriers for imported material. Niacet Corporation in New York State anchors North American pharmaceutical-grade supply through validated manufacturing records.
India
Textile printing houses and food processors in Gujarat and Maharashtra drive technical-grade offtake. FSSAI food additive standards are evolving toward pre-validated supplier requirements for imported sodium acetate. Mumbai-Pune industrial corridors concentrate dye bath pH adjustment demand from apparel export clusters.
Switzerland
Specialty pharmaceutical compounders and precision chemical distributors command premium positioning for anhydrous grades. Swissmedic alignment with EMA excipient guidelines reinforces multi-jurisdiction certification requirements. Basel pharmaceutical corridors source through German integrated producers to maintain audit trail integrity.
Global Sodium Acetate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sodium acetate value chain. The market structures around three tiers: integrated acetic acid producers with captive feedstock, standalone crystallization specialists with purification expertise, and regional bulk distributors serving commodity applications. Strategic moves concentrate on backward integration into acetic acid supply and direct-to-pharma distribution partnerships that bypass traditional chemical wholesalers.
Within the integrated producer archetype, BASF SE and Changshu Nanhu Chemical exemplify divergent geographic positioning—European pharmaceutical corridors versus Asian-Pacific volume markets. Niacet Corporation occupies a specialist position in North American excipient supply. These three anchors illustrate how feedstock control, regulatory validation depth, and end-market focus separate competitive outcomes across manufacturing tiers.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Eastman Chemical Company |
| Lonza |
| Changshu Nanhu Chemical |
| CABB |
| American Elements |
| Niacet Corporation |
| Tokyo Chemical Industry |
| Others |
Supply & Pricing Matrix
Changshu coastal capacity utilization above 85 percent compresses unit costs for trihydrate bulk grades while simultaneously elevating price floors for anhydrous pharmaceutical specifications. This scale asymmetry funnels buyer procurement toward integrated acetic acid producers who internalize feedstock volatility, leaving standalone converters exposed to margin erosion during acetic acid price spikes.
Pricing Analysis
The customization-premium spread widens sharply between compendial-grade anhydrous sodium acetate and technical-grade trihydrate bulk deliveries. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects divergent certification burdens with USP and EP compliance commanding substantial premia over SAMR-aligned food additive specifications. Pricing pressure stems from formic acid substitution in concrete acceleration applications, compressing sodium acetate to moisture-critical architectural sealant niches. Bulk chemical distributors serving construction and textile dyeing applications exhibit highest price sensitivity, while parenteral formulation compounders in Germany and Switzerland absorb premia for validated audit trails.
Supply Chain Analysis
Inventory strategy bifurcates between just-in-time pharmaceutical excipient procurement with multi-year qualification locks and strategic stockpiling by bulk chemical distributors buffering acetic acid price volatility. Supply concentrates in Chinese coastal clusters around Changshu and Jiangsu province, with secondary sourcing from South Korean integrated acetic acid producers and German pharmaceutical-grade specialists. Raw material flows draw from petrochemical acetic acid, sodium carbonate, and sodium hydroxide feedstocks. Single-source vulnerability concentrates in East Asian bulk chemical production exposed to shipping chokepoint risk. Distribution runs through validated chemical distributors for pharmaceutical tiers and direct mill procurement for textile and concrete applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation services and multi-jurisdiction filing support are expanding faster than base chemical production, creating attach-rate opportunities for suppliers who bundle compliance advisory with material supply.
For Market Incumbents: Fortify backward integration into acetic acid supply to neutralize feedstock volatility exposure that threatens standalone converters. Deepen EMA and FDA excipient master file holdings to defend against emerging Asian producers seeking qualification. Lock in direct-to-pharma distribution partnerships that bypass traditional chemical wholesalers and capture documentation-service margin. For New Entrants and Emerging Players: Technical documentation gaps in FSSAI pre-validation services for Indian food additive importers represent immediate white-space opportunity. Target thermoplastic nucleating agent applications in German sustainable packaging compounders where specification requirements remain fluid and incumbent relationships are unformed. Pursue membrane purification technology licensing from Swiss and German engineering specialists as qualification shortcut. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated acetic acid producers with captive pharmaceutical-grade crystallization capability over standalone commodity converters. Long-term viability across the analysis window hinges on regulatory filing depth rather than scale alone. Acquisition screening should prioritize targets with validated USP-EP-JP cross-compendial dossiers. The signal to watch is EMA excipient risk assessment guideline expansion forcing origin documentation to acetic acid source.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive feedstock supply locks margin resilience against price volatility in Jiangsu and Ludwigshafen corridors. |
| Membrane Purification Technology Adoption | German and Swiss manufacturers compress EMA elemental impurity compliance timelines through advanced separation systems. |
| Direct-to-Pharma Distribution Partnerships | Bypassing traditional chemical distributors captures documentation-service margin in parenteral formulation supply chains. |
| Multi-Jurisdiction Regulatory Filing Investment | Pre-validated USP-EP-JP master files accelerate supplier qualification for intravenous fluid manufacturers. |
| Continuous Crystallization Scale-Up | Real-time quality verification technology reduces batch-to-batch variation for ophthalmic preparation compounders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC chemical company filings, and EMA excipient guideline documentation. Primary interviews engaged plant managers at integrated acetic acid facilities, procurement leads at parenteral formulation manufacturers, distribution channel partners in Indian textile corridors, and technical R&D directors at biodegradable polymer compounders. Bottom-up volume triangulation against top-down value estimates validated segmentation splits across grade tiers and end-use applications.
Segmentation dimensions modeled span product type (anhydrous, trihydrate, powder, granular, flake), application category (pharmaceutical excipient, food additive, concrete sealant, textile printing, thermoplastic processing), and end-user industry vertical. CAGRs were derived through trend extrapolation of historical volume flows adjusted for substitution dynamics and regulatory compliance cost trajectories. Forecast inputs incorporated acetic acid price correlation models and pharmacopeial harmonization probability assessments across USP, EP, and JP monograph revisions.
Material uncertainties — acetic acid feedstock cost volatility, formic acid substitution acceleration in construction applications, and pharmacopeial heavy metal limit divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding REACH and FDA excipient guideline stability and continued EMA supply chain transparency mandate expansion. Revision becomes warranted when formic acid price differentials exceed specification-switching thresholds in concrete acceleration applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
1,4 Butanediol Derivatives Market
Additives
Dipotassium Guanylate Market
Additives
Global Ester Gum Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
China Sodium Reduction Ingredient Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Sodium Potassium Tartrate Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Lactic Acid Ester Market
Additives
Refinery Process Additives Market
Additives
China Citric Acid Market
Additives
Antiblock Agents Market
Additives
Global Pour Point Depressant Market
Additives
Canada Water Enhancer Market
Additives
Europe Citric Acid Market
Additives
Global Performance Additives Market