
 Lactic Acid Ester Market | 2026-2036
Lactic Acid Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid Ester Market Intelligence
Capacity concentration among key fermentation-based producers in Europe and China is hardening the supply landscape for high-purity grades. CORBION NV leverages its backward integration into lactic acid production to maintain cost leadership. Stepan differentiates with its portfolio of specialty ester blends for industrial cleaning and solvent applications. Henan Jindan Lactic Acid Technology Co., Ltd. anchors its position through large-scale manufacturing capacity aimed at the coatings sector in Asia.
Lactic acid esters are organic compounds formed by reacting lactic acid with an alcohol like ethanol. These bio-based chemicals are characterized by high solvency power, low toxicity, and ready biodegradability, serving as green solvents. Within product types, ethyl lactate holds the dominant share due to its wide use in coatings and cleaners. The food & beverages sector remains a core end-use, employing specific esters as flavoring agents and preservatives.
The regulatory environment is defined by bodies like the US FDA, which classifies certain esters as Generally Recognized as Safe (GRAS) for food applications. Concurrently, the EU's REACH framework promotes the substitution of hazardous solvents, benefiting bio-based alternatives. Navigating feedstock price volatility and aligning product portfolios with evolving environmental mandates are critical strategic imperatives for all stakeholders.
Market Dynamics
The market's primary structural force is the tension between regulatory mandates favoring green chemistry and the concentrated supply landscape for high-purity grades. This dynamic shapes pricing, availability, and the strategic focus of producers in Europe and China.
Growth Catalysts
- EU REACH Framework:This regulation promotes substituting hazardous solvents, directly benefiting bio-based alternatives like lactic acid esters in industrial applications across the European Union.
- Food-Grade Status:The US FDA's Generally Recognized as Safe (GRAS) classification for specific esters drives their use as flavoring agents and preservatives in the food and beverage industry.
- Manufacturing Hubs:Concentrated demand from electronics and coatings producers in industrial centers within China creates a significant and localized market pull for bio-based solvents.
Market Restraints
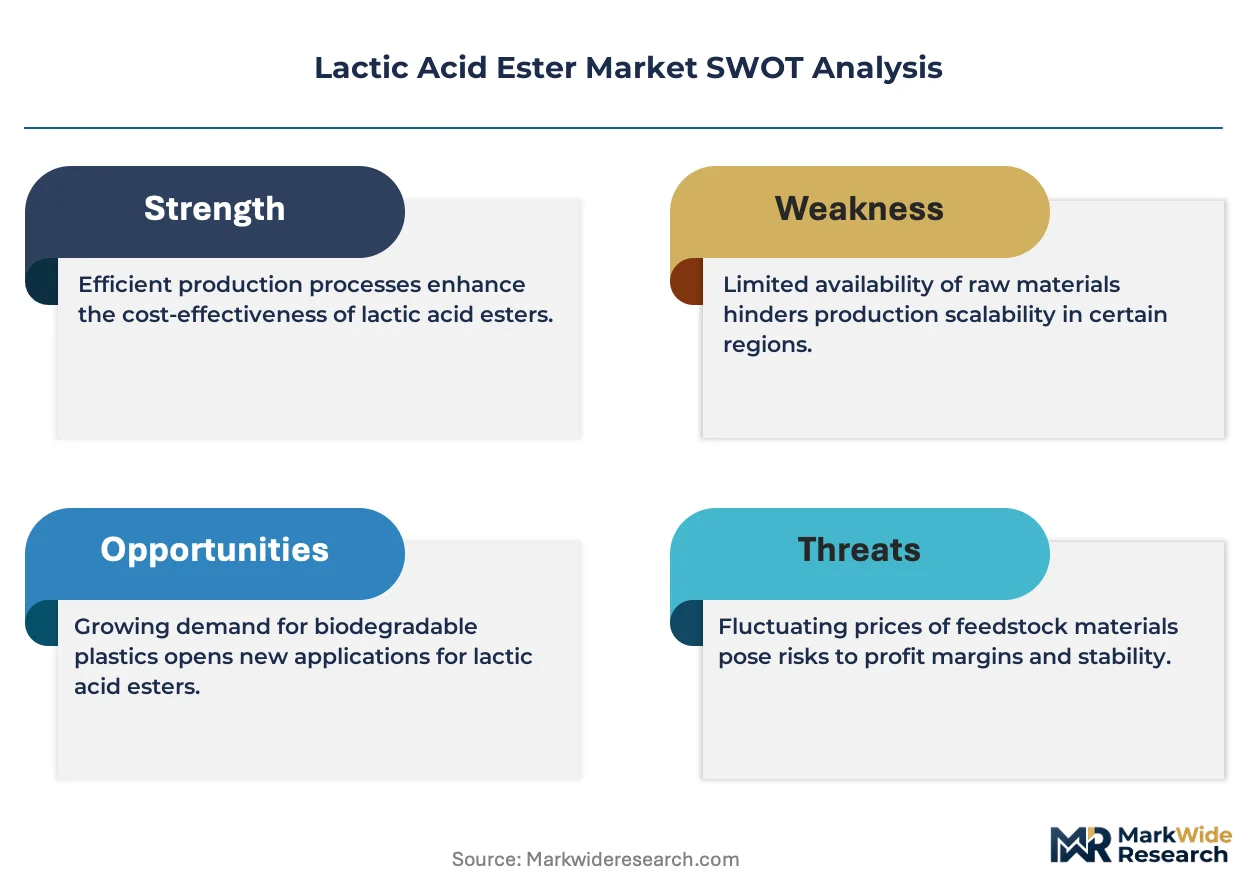
- Feedstock Volatility:The cost structure is highly sensitive to price fluctuations in agricultural inputs such as corn and sugarcane, impacting final product pricing and margins.
- Supply Concentration:A limited number of producers in Europe and China control the supply of high-purity grades, creating potential bottlenecks and exercising significant pricing power.
- Performance Gaps:Certain high-performance coatings and resins require solvency characteristics that some lactic acid esters cannot match compared to established petrochemical alternatives.
Strategic Opportunities
- Precision Cleaning Formulations:Developing customized ester blends for the semiconductor and electronics industries offers a high-value application beyond general-purpose solvents.
- Southeast Asian Industrialization:Expanding into markets like Vietnam and Indonesia, where manufacturing growth is outpacing local green chemical production, presents a key geographic opportunity.
- Bio-Preferred Programs:Leveraging government procurement initiatives, such as the US EPA's BioPreferred Program, can create dedicated demand channels for certified bio-based products.
Industry Challenges
- Capital Investment Hurdles:Constructing new fermentation plants requires significant upfront capital and long lead times, slowing down capacity expansion in response to demand signals from end-users.
- Regulatory Approval Cycles:The lengthy and data-intensive process for securing food-contact approvals from bodies like the US FDA or the EFSA delays the introduction of new ester formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid Ester Market |
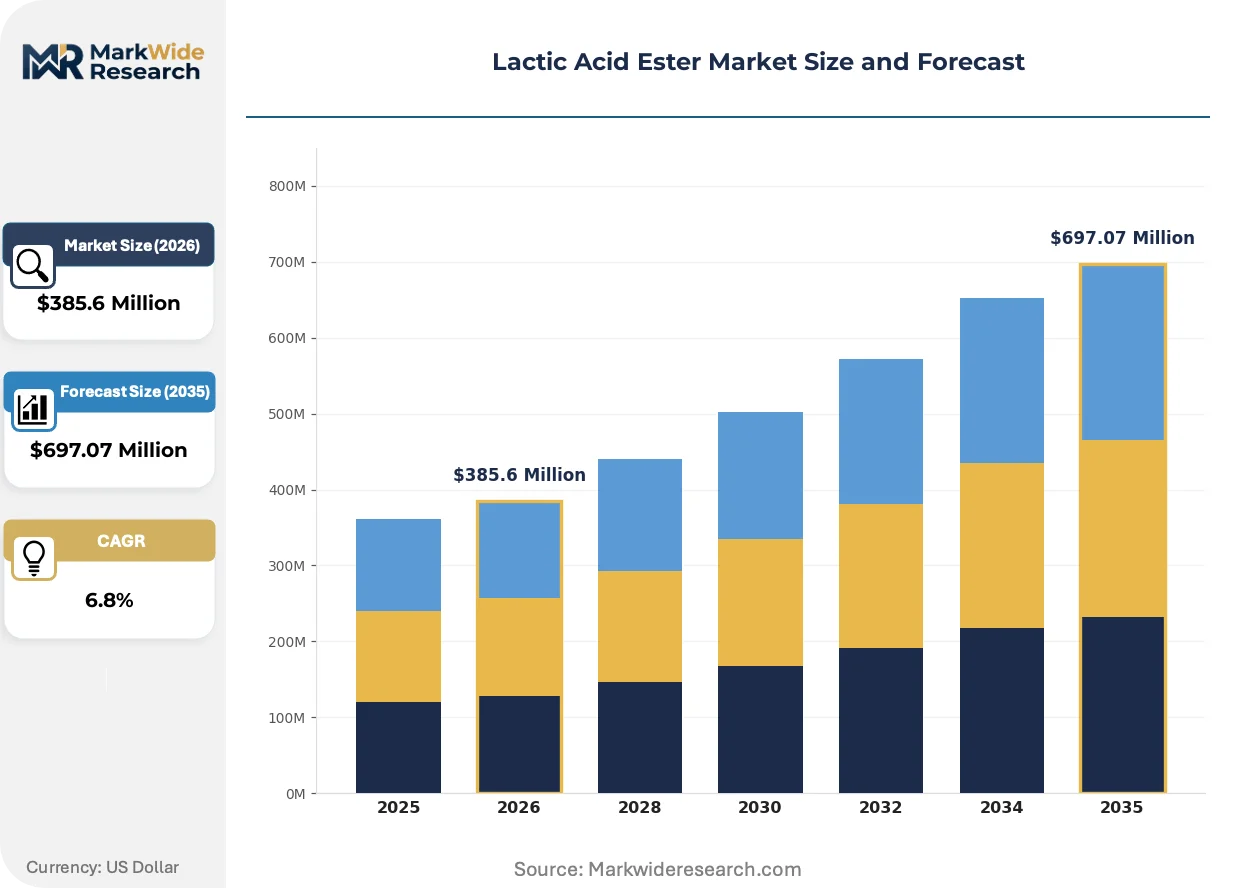
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Lactate, Butyl Lactate, Methyl Lactate, Propyl Lactate End Use Industry: Food & Beverages, Pharmaceuticals, Cosmetics, Coatings Application: Solvent, Flavoring Agent, Surfactant, Food Preservative Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | CORBION NV, Stepan, Henan Jindan Lactic Acid Technology Co., Ltd., Musashino Chemical Laboratory Ltd., Zhengzhou Tianrun Lactic Acid Co., Ltd., Galactic, Vertec Biosolvents Inc., Godavari Biorefineries Limited, Shenzhen eSUN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid Ester Market Strategic Shifts & Innovations
Product innovation is shifting from commodity-grade solvents toward specialized blends tailored for high-performance applications. This evolution is driven by a combination of stricter environmental regulations and more sophisticated end-user requirements for both performance and sustainability documentation.
Specialty ester blending allows for the precise tuning of properties like solvency, evaporation rate, and odor profile. Industrial cleaning and agrochemical formulation sectors are steadily adopting these customized solutions to replace traditional, single-component solvents. This approach is absorbing market share from less differentiated products by offering superior performance in niche applications.
The European Union's REACH regulation continues to compel the substitution of hazardous chemicals, including many traditional industrial solvents. This creates a direct compliance-driven need for safer, bio-based alternatives like ethyl lactate. The coatings, inks, and adhesives industries are most affected, accelerating reformulation efforts to align with ECHA's evolving list of restricted substances.
Demand is evolving from simple volume-based purchasing to requiring documented proof of bio-based content and biodegradability. This change disrupts distribution channels that compete solely on price, favoring suppliers who can provide comprehensive technical and sustainability data. This trend is most visible in consumer-facing product segments like personal care and home cleaning, particularly in European markets.
Lactic Acid Ester Market Segmentation
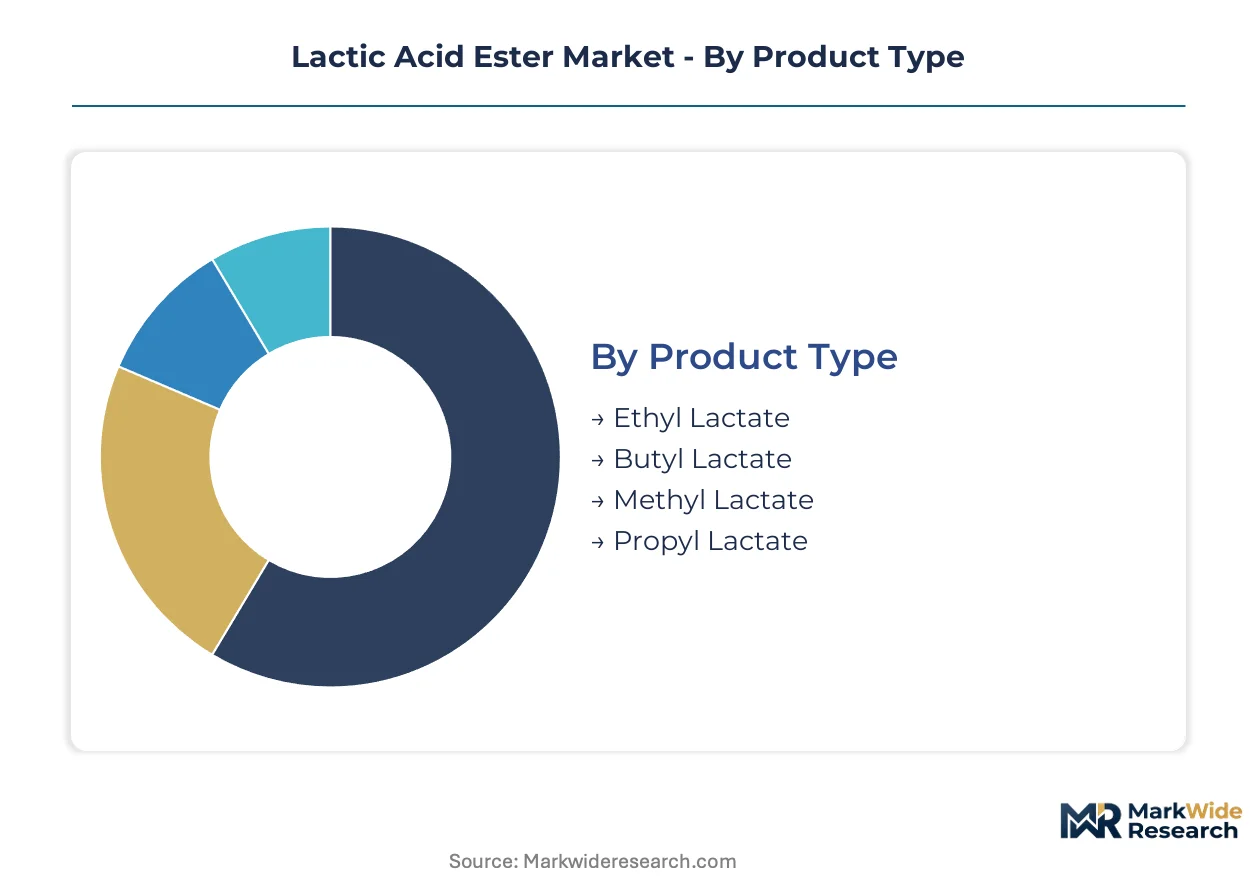
The lactic acid ester market categorizes its diverse product offerings and end-use applications to delineate distinct demand patterns. This segmentation highlights the varying regulatory requirements and performance specifications across different industry verticals. Understanding these divisions is crucial for strategic market positioning and product development.
Product Type:
The various lactic acid ester product types face differing certification burdens, particularly concerning food-contact approvals from bodies like the US FDA and Europe's EFSA. Each ester's unique chemical profile dictates its suitability for specific industrial and consumer applications. Producers must navigate these regulatory pathways to commercialize new formulations.
- Ethyl Lactate:This ester, formed from ethanol and lactic acid, offers high solvency power and rapid biodegradability, making it a preferred green solvent. Demand concentrates in coatings and industrial cleaning sectors across China and Germany, driven by stringent environmental regulations like REACH.
- Butyl Lactate:Characterized by a slower evaporation rate than ethyl lactate, this ester finds utility in specialized coatings and ink formulations requiring extended open times. Industrial manufacturing hubs in Japan and South Korea drive its demand, particularly for electronics and automotive finishes.
- Methyl Lactate:This lighter ester serves as a solvent in agrochemical formulations and as a component in certain personal care products, valued for its lower boiling point.
- Propyl Lactate:Utilized in niche solvent applications and as a specialty chemical intermediate, this ester offers a balance of solvency and evaporation characteristics.
Ethyl Lactate sits at the top of the volume ranking, with Butyl Lactate climbing the fastest.
End Use Industry:
The end-use industries for lactic acid esters dictate the required performance attributes, purity levels, and regulatory compliance standards for each product. Different sectors prioritize distinct chemical properties, influencing formulation and manufacturing processes. Producers tailor their offerings to meet specific industry demands.
- Food & Beverages:This sector uses specific lactic acid esters as flavoring agents, acidulants, and preservatives, benefiting from their GRAS classification by the US FDA. Demand is strong in the processed food markets of India and Brazil, driven by consumer preference for natural ingredients.
- Coatings:Lactic acid esters serve as green solvents in paint, varnish, and ink formulations, replacing hazardous petrochemical alternatives to meet environmental mandates. Chinese manufacturing centers for automotive and industrial coatings represent a significant demand concentration.
- Pharmaceuticals:Esters find application as excipients, solvents for active pharmaceutical ingredients, and intermediates in drug synthesis, demanding high purity and regulatory approval.
- Cosmetics:These compounds function as emollients, humectants, and solvents in personal care products, valued for their mildness and biodegradability in European markets.
The Food & Beverages sector represents the fastest-growing end-use, while the Coatings industry commands the largest overall volume.
Application:
The application segments define the specific functional roles that lactic acid esters perform within various products and processes. Each application leverages distinct chemical properties, such as solvency, taste enhancement, or antimicrobial action. This differentiation drives specialized product development and market positioning.
- Solvent:Lactic acid esters act as bio-based solvents across industries, offering high solvency power, low toxicity, and biodegradability as replacements for petrochemicals. Industrial cleaning and specialty coatings in Germany and the Netherlands are significant demand centers, driven by REACH regulations.
- Flavoring Agent:Specific esters impart fruity or creamy notes to food and beverage products, enhancing sensory profiles and consumer appeal. The prepared food sectors of the United States and Canada exhibit substantial demand, supported by GRAS designations.
- Surfactant:Lactic acid esters can function as emulsifiers or dispersing agents in formulations, improving product stability and performance in personal care.
- Food Preservative:Certain esters provide antimicrobial properties, extending the shelf life of food products and reducing spoilage in packaged goods.
The Solvent application holds the largest market share, while Flavoring Agent applications show significant innovation in new product development.
Distribution Channel:
The distribution channels for lactic acid esters vary based on customer type, order volume, and the technical support required. Different channels optimize access to diverse customer segments, from large industrial buyers to smaller niche formulators. Strategic channel selection impacts market penetration and logistical efficiency.
- Direct Sales:This channel involves direct transactions between producers and large industrial end-users, facilitating bulk orders and specialized technical support for high-purity grades. Major chemical manufacturers in Belgium and France prefer direct procurement for consistent supply.
- Distributors:Intermediaries manage inventory and logistics for a diverse customer base, including smaller formulators and regional manufacturers, offering localized access and technical expertise. This channel is critical for reaching dispersed industrial clients across Southeast Asia and Latin America.
- Online Retail:E-commerce platforms cater to smaller volume buyers and research institutions, offering convenience and a broader product catalog for specialty chemicals.
- Retail Stores:Limited to consumer-facing products containing lactic acid esters, such as household cleaners or personal care items, reaching general public consumers.
Direct Sales offer efficiency for large-volume transactions, while Distributors are expanding their reach into emerging industrial markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between regions creates a complex supply dynamic, with production often migrating to areas offering more favorable compliance costs. Stringent environmental mandates in Europe encourage bio-based solvent adoption, while large manufacturing sectors in Asia drive demand for specific ester grades. This creates a global market where local regulations heavily influence product availability and pricing.
China
Strong demand from electronics and coatings producers drives significant lactic acid ester consumption in China's industrial centers. The country's dual carbon goals promote the adoption of greener chemicals, accelerating the shift from petrochemical solvents. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta regions represent major localized markets for bio-based solutions.
Germany
Germany leads European demand for green solvents, propelled by the EU's REACH framework mandating the substitution of hazardous chemicals. Industrial cleaning and specialty coatings sectors actively seek bio-based alternatives like ethyl lactate. Chemical clusters around the Rhine-Ruhr area and Bavaria are key centers for product development and application.
United States
The US FDA's GRAS classification for specific lactic acid esters supports their widespread use as flavoring agents and preservatives in food and beverages. The US EPA's BioPreferred Program also incentivizes the procurement of bio-based products, creating dedicated demand channels. Processed food manufacturers in the Midwest and California represent substantial end-users.
India
India's expanding processed food markets show strong demand for lactic acid esters as natural ingredients, flavoring agents, and preservatives. The Food Safety and Standards Authority of India (FSSAI) regulates food additives, influencing ester formulations. Industrial growth in states like Maharashtra and Gujarat also contributes to solvent applications.
Japan
Japanese industrial manufacturing hubs drive demand for specialized esters like butyl lactate, particularly in electronics and automotive finishes. METI initiatives encourage sustainable chemical production and usage across various industries. Major automotive and electronics manufacturers in the Kanto region and Aichi Prefecture are significant consumers.
Lactic Acid Ester Market Key Industry Players
European producers anchor one tier, emphasizing high-purity, fermentation-based grades for regulated markets, while Asian specialists hold significant capacity for large-scale industrial applications. The market structure features a mix of globally integrated chemical companies and regional players focused on specific applications or geographies. Portfolio diversification into specialty blends and strategic partnerships for feedstock supply are dominant competitive moves.
CORBION NV exemplifies a vertically integrated approach, leveraging its backward integration into lactic acid production to achieve cost leadership. Stepan occupies a position among specialty chemical manufacturers, differentiating its offerings with tailored ester blends for industrial cleaning and solvent applications. Henan Jindan Lactic Acid Technology Co., Ltd. represents the large-scale manufacturing archetype, anchoring its position through significant capacity aimed at the coatings sector in Asia.
| Leading Market Players |
|---|
| CORBION NV |
| Stepan |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Musashino Chemical Laboratory Ltd. |
| Zhengzhou Tianrun Lactic Acid Co., Ltd. |
| Galactic |
| Vertec Biosolvents Inc. |
| Godavari Biorefineries Limited |
| Shenzhen eSUN |
| Others |
Cost & Logistics Intelligence
Agricultural commodity price volatility, particularly for corn and sugarcane, cascades through the lactic acid ester supply chain, directly influencing the cost structure and final product pricing tiers. This sensitivity to upstream input costs shapes procurement strategies and producer margins across different ester grades.
Pricing Analysis
Direct-to-OEM discounts characterize the pricing model for large industrial buyers, often structured through long-term contract-based offtake agreements. Price differentiation stems from high-purity grades, certified for food-contact applications by bodies like the US FDA, and the volume scale of purchases. Pricing softness affects commodity-grade ethyl lactate due to intense competition among Asian producers. The coatings sector exhibits high price sensitivity for bulk solvents, whereas pharmaceutical and personal care formulators prioritize purity and certification over cost.
Supply Chain Analysis
Single-source vulnerability sits with fermentation-based lactic acid producers in Europe and China, who control the supply of high-purity grades. The supply chain draws from agricultural inputs like corn and sugarcane, and chemical intermediates such as ethanol. Geographic supply concentration for key esters exists in China for industrial volumes and in Europe for specialized applications. Commodity price volatility for these raw materials represents a significant structural risk. Distribution runs through direct sales channels for major industrial clients and a network of regional distributors for smaller formulators across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lactic acid ester market operates as a stable compounder, driven by the sustained global shift toward bio-based chemicals and stricter environmental mandates like the EU's REACH framework.
For Market Incumbents:Extend product differentiation by investing in specialized ester blends for high-performance applications, such as precision cleaning in the semiconductor industry. Backward integration into lactic acid production, exemplified by CORBION NV, offers a strong defense against feedstock volatility and secures cost leadership. Consolidate market share in regulated European markets by ensuring comprehensive REACH compliance and sustainability documentation for bio-based content, countering threats from less differentiated products.
For New Entrants and Emerging Players:Capture white-space opportunities in rapidly industrializing Southeast Asian markets like Vietnam and Indonesia, where local green chemical production lags. Focus on developing custom ester formulations that offer superior performance in niche applications, such as agrochemical formulations, leveraging specific solvency and evaporation profiles. A go-to-market angle emphasizing documented sustainability credentials and technical support can penetrate segments where petrochemical alternatives face regulatory pressure.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialty blend formulators possessing strong R&D capabilities and regional distribution networks in emerging markets. The long-term viability of this market hinges on regulatory tailwinds favoring green chemistry and consumer preference for natural ingredients in food and personal care. A signal to watch is the expansion of bio-preferred procurement programs beyond the US EPA's initiative, indicating broader governmental support for bio-based materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases supply for the burgeoning coatings and electronics manufacturing sectors in China. |
| Backward Integration into Lactic Acid | Secures raw material supply and enhances cost control for ester production. |
| Specialty Ester Blending R&D | Develops high-performance solutions for niche applications like precision cleaning. |
| Strategic Partnerships for Distribution | Expands market reach into underpenetrated industrial hubs in Southeast Asia. |
| Investment in Bio-Certification | Aligns product portfolios with evolving environmental mandates and consumer preferences in Europe. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. This analysis involved detailed conversations with R&D directors, procurement leads at downstream OEMs, plant managers, and regulatory affairs specialists across key geographies. Secondary data sources included trade association reports, customs and trade data, company annual filings, and regulatory submissions to the US FDA and ECHA, enabling comprehensive bottom-up and top-down triangulation.
Historical market performance established the baseline for projecting future trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-use industry, application, and distribution channel, alongside regional production hubs. Compound Annual Growth Rates were derived from historical data, factoring in projected market drivers and restraints, with specific inputs like feedstock price trends and regulatory policy shifts integrated into the forecast model.
Feedstock price volatility, evolving regulatory frameworks, and technological breakthroughs are the dominant revision risks for the Lactic Acid Ester Market. Forecasts reflect a comprehensive set of assumptions regarding market dynamics and competitive landscapes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Flame Retardant Masterbatches Market
Additives
Inorganic Filler Market
Additives
Anti-Block Additives Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Refining Additives Market
Additives
Low Melt Inclusions Market
Additives
Monocalcium Phosphate Market
Additives
Saudi Arabia Feed Additives Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Biofuel Additives Market
Additives
Additives for Metalworking Fluids Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Plastic Fillers Market
Additives
North America Phosphate Esters Market
Additives
Global Isosorbide Market
Additives
Global Matting Agents Market