
 Carboxymethylcellulose (CMC) Market | 2026-2036
Carboxymethylcellulose (CMC) Market Size, Share, and Industry Trends Forecast 2026-2036
Carboxymethylcellulose (CMC) Market Outlook
Pharmaceutical formulators is unwinding legacy reliance on synthetic polymer alternatives in favor of plant-derived cellulose ethers. Ashland Inc. leverages its pharmaceutical excipient specialization to sustain premium positioning in controlled-release applications. Daicel Corporation anchors supply security through backward integration into purified cotton linter supply chains. Nouryon competes on food-grade certification breadth across European and North American dairy stabilizer markets.
Carboxymethylcellulose denotes a cellulose ether produced by alkali-catalyzed reaction of cellulose with monochloroacetic acid, yielding a water-soluble polymer with degrees of substitution typically between 0.7 and 1.2 that functions as a thickener, binder, and film-former across industrial and consumer formulations. Sodium CMC dominates volume throughput in food and beverage stabilization, where its pseudoplastic rheology controls viscosity under shear conditions. Pharmaceutical-grade material commands the densest margin pool due to USP-NF and EP compliance burdens, while industrial-grade supply faces commoditization pressure from Asian cellulose derivative producers.
FDA excipient guidelines, EPA industrial discharge standards for cellulose ether plants, and REACH substance registration requirements collectively elevate compliance costs for pharmaceutical-grade manufacturers seeking multi-regional market access. ISO 9001 and EXCiPACT certification frameworks now function as baseline qualifiers rather than differentiators in tender evaluations for European and North American pharmaceutical customers. Stakeholders must monitor evolving monograph revisions from pharmacopeial authorities and corresponding capacity reallocation among grade-dedicated production lines.
Market Dynamics
Pharmaceutical-grade CMC supply is bifurcating from industrial-grade streams as USP-NF and EP compliance burdens harden into non-negotiable tender qualifiers, forcing capacity reallocation toward dedicated production lines and purified raw material sourcing.
Growth Catalysts
- Controlled-release tablet demand:Oral solid dosage formulators are expanding CMC adoption as a matrix material for extended-release formulations, displacing synthetic polymer alternatives in chronic disease therapeutic categories.
- REACH substance registration:ECHA compliance requirements for pharmaceutical-grade cellulose ethers are tightening purity benchmarks, creating competitive moats for manufacturers with pre-registered supply chains across European markets.
- India pharmaceutical manufacturing:Domestic formulators and contract manufacturers are scaling CMC procurement volumes to serve export markets and local generic drug production.
Market Restraints
- Purified cotton linter concentration:Pharmaceutical-grade CMC production depends on captive supply chains into cotton linter purification, with processing capacity concentrated among Asian specialty cellulose producers.
- Substitution by hydroxypropyl methylcellulose:HPMC is displacing CMC in certain controlled-release applications where thermal gelation properties provide superior release kinetics.
- EPA industrial discharge standards:Cellulose ether plant wastewater treatment requirements elevate compliance costs for North American manufacturers relative to jurisdictions with less stringent effluent mandates.
Strategic Opportunities
- Biologics formulation expansion:Protein stabilizer applications in monoclonal antibody and vaccine formulations represent an emerging demand vertical with premium pricing potential.
- Clean-label food stabilization:FSSAI enforcement of additive disclosure requirements is accelerating CMC adoption in Indian processed foods as a recognizable, plant-derived ingredient.
- EXCiPACT certification expansion:Third-party pharmaceutical excipient certification is creating market access pathways for qualified manufacturers into European and North American tender evaluations.
Industry Challenges
- Pharmacopeial monograph revision cycles:USP-NF and EP updates to cellulose ether specifications require reformulation validation and analytical method redevelopment, compressing product lifecycle planning horizons.
- Cross-grade contamination risk:Shared production infrastructure between food-grade, pharmaceutical-grade, and industrial-grade CMC creates audit complexity and batch segregation protocols that extend lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carboxymethylcellulose (CMC) Market |
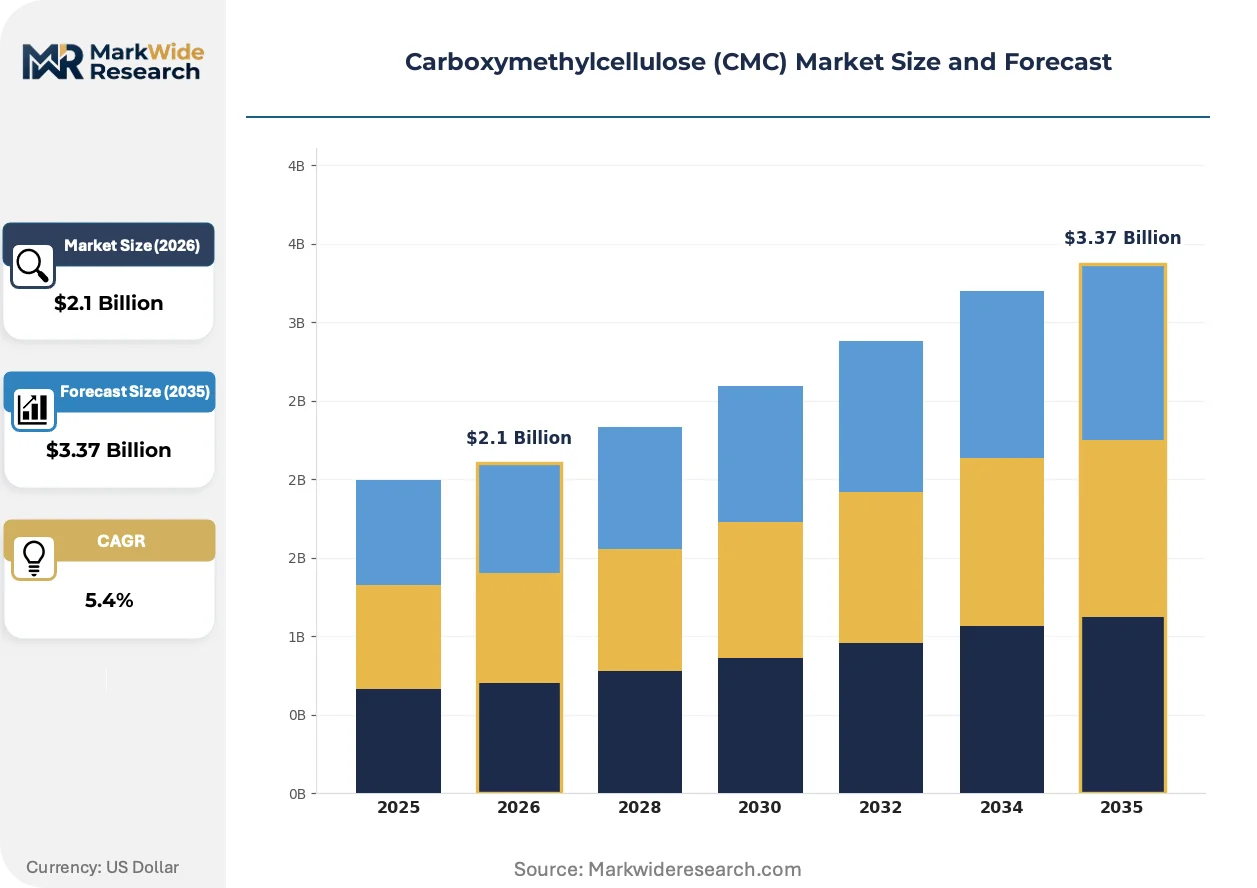
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium CMC, Calcium CMC, Methyl CMC, Others End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Textiles Formulation: Powder, Solution, Granules, Bulk Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Others |
| Companies Covered | Dow Chemical Company, Daicel Corporation, Ashland Inc., DKS Co. Ltd, Nippon Paper Industries, Nouryon, Lamberti S.p.A., Jungbunzlauer Suisse AG, CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carboxymethylcellulose (CMC) Market Strategic Shifts
Manufacturing technology is compressing particle size distributions and substitution uniformity, enabling performance specifications that unlock formulation applications previously reserved for synthetic polymers.
Microcrystalline cellulose co-processing technology is miniaturizing CMC particle morphology to achieve enhanced compaction properties in direct-compression tablet manufacturing. High-shear granulation operators in generic pharmaceutical production are adopting these grades to eliminate wet granulation steps. The structural consequence is displacement of conventional CMC in volume tablet applications where processing efficiency determines supplier selection.
EMA's revised excipient risk assessment guidelines are mandating enhanced impurity profiling for cellulose ethers used in parenteral and ophthalmic dosage forms. Manufacturers must now submit nitrosamine and elemental impurity data packages as standard regulatory documentation. Parenteral-grade CMC suppliers are responding by investing in dedicated production suites with isolated purification trains.
Formulators are consolidating supplier relationships around excipient providers with dual USP-NF and EP certification, compressing vendor panels from multi-source to single or dual-source arrangements. This concentration is displacing spot-market purchasing in favor of multi-year supply agreements with volume commitments and audit rights. The shift is most visible in European generic pharmaceutical procurement, where quality agreement standardization reduces regulatory inspection exposure.
Carboxymethylcellulose (CMC) Market Segmentation
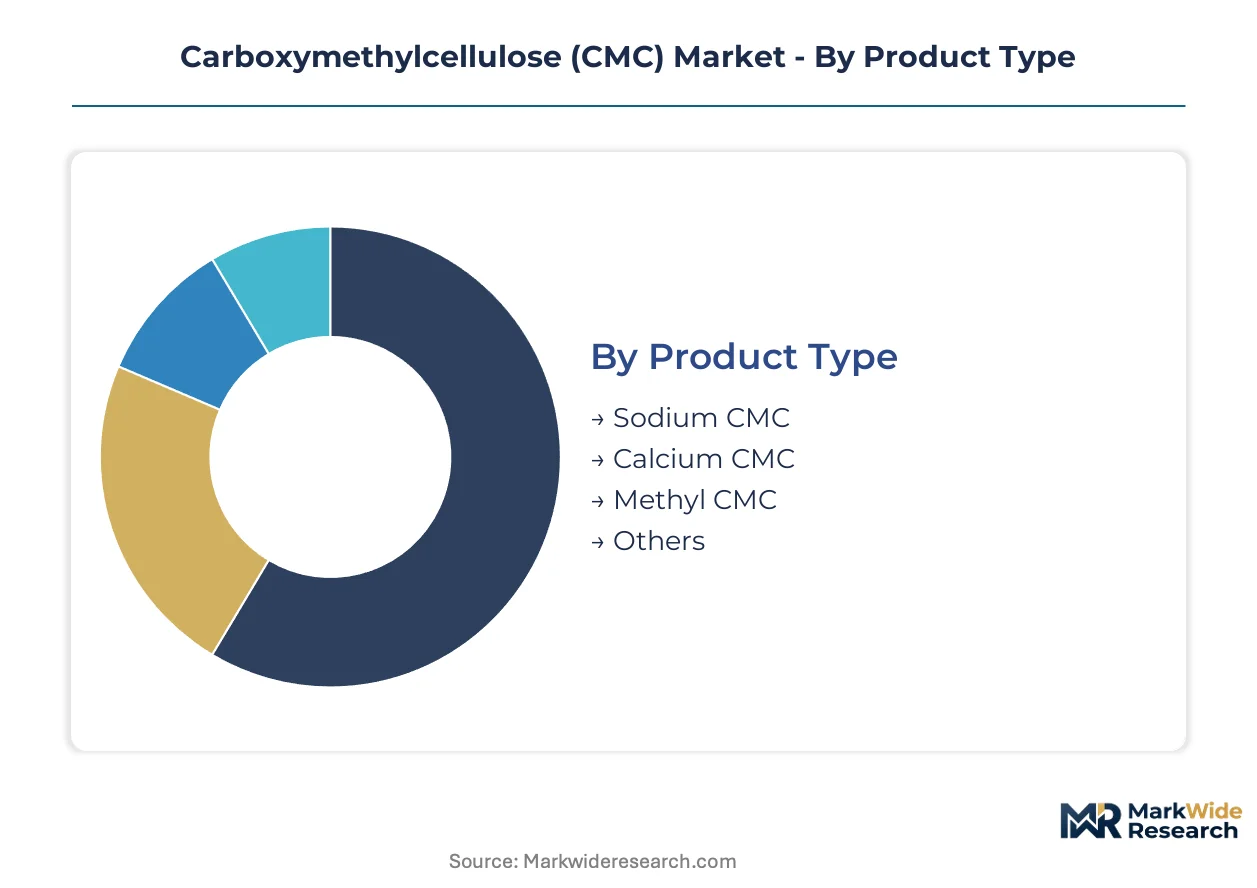
Segmentation in the CMC market reveals how substitution pressures and regulatory compliance reshape competitive boundaries across product types and end-use applications. Manufacturers align capacity investments with grade-specific purity requirements rather than pursuing horizontal coverage across all segments.
Product Type:
Substitution pressure from hydroxypropyl methylcellulose and other cellulose ethers varies sharply across product chemistries, with degree-of-substitution specifications determining functional interchangeability in target formulations.
- Sodium CMC:The sodium salt form dominates commercial volumes through water solubility across pH ranges and pseudoplastic rheology that controls viscosity under shear. Food and beverage stabilizers in India are scaling procurement of high-viscosity grades as FSSAI disclosure requirements favor recognizable plant-derived thickeners over synthetic alternatives.
- Calcium CMC:Calcium counterion variants exhibit reduced water solubility and modified gelation profiles suited to controlled-release tablet matrices where ionic interactions modulate drug release kinetics. Pharmaceutical formulators in Germany are evaluating calcium grades for osteoporosis therapeutic categories where calcium loading provides dual functionality.
- Methyl CMC:Methyl-substituted derivatives offer modified hydrophobicity and film-forming characteristics for specialty coating applications.
- Others:Cross-linked and mixed-ether variants serve niche rheology modification requirements in industrial formulations.
Sodium CMC retains volume leadership; pharmaceutical-grade calcium variants hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity-grade supply for food applications from premium-certified streams for pharmaceutical and cosmetic formulations, with compliance burdens determining margin capture.
- Food & Beverage:Dairy stabilizers, bakery emulsions, and beverage suspensions consume standard-viscosity grades where pseudoplastic flow behavior prevents phase separation. European dairy processors under EFSA additive regulations are consolidating procurement around suppliers with dual ISO 22000 and FSSC 22000 certification to reduce audit complexity.
- Pharmaceuticals:Tablet binders, controlled-release matrices, and ophthalmic formulations demand USP-NF and EP compliance with tight endotoxin and nitrosamine specifications. Parenteral-grade supply is concentrating among manufacturers with dedicated purification trains and EXCiPACT certification for European tender access.
- Cosmetics:Personal care emulsions and toothpaste binders utilize medium-viscosity grades with cosmetic directive compliance.
- Textiles:Sizing and printing applications consume industrial-grade material with performance specifications focused on film tensile strength and wash-off characteristics.
Food and beverage retains volume leadership; pharmaceutical applications hold the steepest expansion curve.
Formulation:
Customer type preferences—direct-compression tablet manufacturers versus wet granulation operators versus food processors—determine formulation selection based on process integration requirements.
- Powder:Dry particulate forms enable flexible reconstitution and blending across pharmaceutical and food manufacturing. High-shear granulation operators in Indian generic pharmaceutical production are adopting microcrystalline cellulose co-processed powders to eliminate wet granulation steps and compress cycle times.
- Solution:Pre-hydrated liquid concentrates serve continuous manufacturing lines where dosing precision and batch-to-batch consistency outweigh freight cost premiums. Beverage manufacturers in the United States are specifying solution formats for automated dosing systems in high-throughput carbonated soft drink production.
- Granules:Agglomerated forms improve flow properties for direct-compression tableting and reduce dust exposure in handling.
- Bulk:Unpackaged material in tanker or tote quantities serves integrated manufacturing facilities with on-site dispersion equipment.
Powder retains volume leadership; solution formats for continuous manufacturing hold the steepest expansion curve.
Grade:
Supply concentration in purified cotton linter sourcing creates tiered access barriers, with pharmaceutical-grade production captive to backward-integrated specialty cellulose producers.
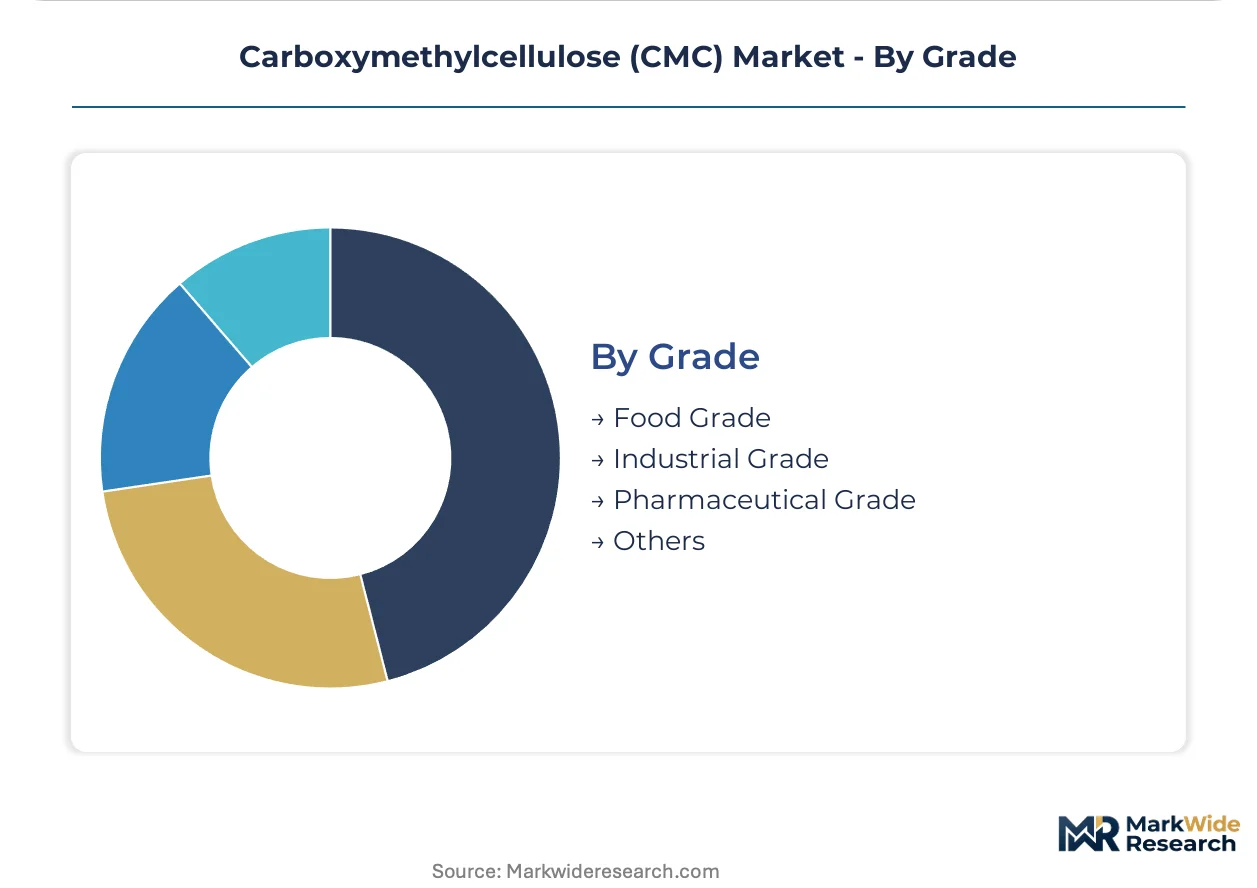
- Food Grade:FSSC 22000 and Halal certification frameworks govern supply to processed food manufacturers where clean-label positioning drives ingredient selection. Indian packaged food companies under FSSAI enforcement are accelerating CMC adoption as a recognizable, plant-derived stabilizer alternative to modified starches and synthetic gums.
- Pharmaceutical Grade:USP-NF, EP, and JP compliance with elemental impurity and nitrosamine profiling mandates dedicated production infrastructure and analytical validation. EMA's revised excipient risk assessment guidelines are forcing capacity reallocation toward isolated purification trains and enhanced impurity testing protocols.
- Industrial Grade:Technical specifications for viscosity and purity serve textile sizing, paper coating, and construction applications with commoditized pricing.
- Others:Cosmetic-grade and agricultural-grade variants occupy intermediate regulatory positions with specialized certification requirements.
Industrial grade retains volume leadership; pharmaceutical grade holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Purified cotton linter processing capacity clusters among Asian specialty cellulose producers, while pharmaceutical-grade formulation demand concentrates in Western European and North American markets. Regulatory divergence between FDA excipient guidelines and REACH compliance requirements fragments supply chain configurations across jurisdictions.
United States
Generic pharmaceutical manufacturers in New Jersey and Pennsylvania are scaling CMC procurement for controlled-release tablet production. FDA excipient guideline revisions are tightening nitrosamine and elemental impurity specifications for parenteral-grade material. The Boston-Cambridge biotech corridor is driving demand for protein stabilizer applications in monoclonal antibody formulations.
Germany
European generic drug producers in the Rhine-Main region are consolidating supplier relationships around dual USP-NF and EP certified providers. EMA's revised excipient risk assessment guidelines mandate enhanced impurity profiling for cellulose ethers in ophthalmic dosage forms. The Frankfurt pharmaceutical cluster is evaluating calcium CMC grades for osteoporosis therapeutic categories.
India
Domestic formulators in Maharashtra and Gujarat are expanding CMC volumes to serve export markets and local generic drug production. FSSAI enforcement of additive disclosure requirements is accelerating adoption in processed foods as a plant-derived stabilizer alternative. The Hyderabad-Visakhapatnam pharmaceutical belt is scaling contract manufacturing capacity for oral solid dosage exports.
China
Purified cotton linter supply chains anchor pharmaceutical-grade CMC production in Shandong and Jiangsu provinces. NMPA alignment with ICH Q3D guidelines is elevating elemental impurity testing burdens for domestic excipient manufacturers. The Yangtze River Delta specialty chemicals corridor is investing in dedicated production suites for parenteral-grade material.
Japan
Pharmaceutical formulators in the Kansai region are adopting high-substitution CMC grades for advanced controlled-release matrices. PMDA pharmacopeial harmonization initiatives are compressing specification gaps between JP and USP-NF monographs. The Osaka pharmaceutical cluster is consolidating procurement around suppliers with EXCiPACT certification for European market access.
Carboxymethylcellulose (CMC) Market Competitive Environment
Concentration sits with backward-integrated specialty cellulose producers and pharmaceutical excipient specialists. The vendor base stratifies across three tiers: multinational chemical conglomerates with diversified polymer portfolios, regional cellulose ether specialists with captive raw material sourcing, and Asian commodity producers competing on industrial-grade volume. Two dominant competitive moves are reshaping positioning: capacity reallocation toward pharmaceutical-grade dedicated production lines, and strategic partnerships between formulators and certified suppliers to secure multi-year supply agreements with audit rights.
Among the multinational chemical conglomerates, Dow Chemical Company and Nouryon occupy positions representing diversified polymer portfolio breadth across food, pharmaceutical, and industrial applications. Daicel Corporation and Ashland Inc. exemplify the pharmaceutical excipient specialist archetype, with the former anchoring supply security through in-house purified cotton linter sourcing and the latter sustaining premium positioning in controlled-release applications. DKS Co. Ltd represents the regional Asian specialist tier competing on industrial-grade volume throughput.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Daicel Corporation |
| Ashland Inc. |
| DKS Co. Ltd |
| Nippon Paper Industries |
| Nouryon |
| Lamberti S.p.A. |
| Jungbunzlauer Suisse AG |
| CP Kelco |
| Others |
Value Chain & Pricing Dynamics
USP-NF and EP certification regimes gate both supply qualification and price differentiation simultaneously, compressing vendor panels to dual-certified manufacturers while amplifying margin capture for pharmaceutical-grade streams. Buyers face procurement bifurcation: food-grade spot markets trade on viscosity specifications alone, while pharmaceutical tenders embed multi-year agreements with audit rights and volume commitments.
Pricing Analysis
USP-NF dictates the pricing tier structure across pharmaceutical-grade supply, separating parenteral-certified manufacturers from oral-grade providers through endotoxin and nitrosamine testing burdens. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EXCiPACT-accredited suppliers commanding 40-60% premiums over uncertified competitors. Cost compression in industrial-grade streams is intensifying because Asian cellulose derivative producers are expanding purified cotton linter processing capacity. Generic pharmaceutical manufacturers exhibit highest price sensitivity, while biologics formulators prioritize supply security over unit cost.
Supply Chain Analysis
Strategic stockpiling of purified cotton linter dominates inventory strategy among pharmaceutical-grade manufacturers, insulating against harvest volatility and geopolitical disruption in raw material sourcing. Supply concentrates in China, India, and Germany, with Shandong and Jiangsu provinces anchoring purified linter purification capacity. Production draws from cotton linter, caustic soda, and monochloroacetic acid feedstocks, with captive backward integration common among tier-one suppliers. Single-source vulnerability runs through Asian specialty cellulose producers controlling pharmaceutical-grade linter purification. Distribution runs through direct mill-to-plant arrangements for pharmaceutical volumes and distributor networks for food-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects through EXCiPACT certification interoperability, enabling qualified manufacturers to access European and North American tender evaluations through standardized quality agreements rather than bilateral regulatory negotiations.
For Market Incumbents: Fortify supply security through backward integration into purified cotton linter sourcing or binding offtake agreements with Asian specialty cellulose producers. HPMC substitution in controlled-release matrices threatens CMC positioning in chronic disease therapeutic categories; invest in microcrystalline cellulose co-processing technology to defend tablet binder market share against synthetic polymer displacement. For New Entrants and Emerging Players: Parenteral-grade supply shortages present white-space entry points, as EMA's revised excipient risk assessment guidelines force capacity reallocation among incumbent manufacturers. Target Indian pharmaceutical contract manufacturing expansion, where domestic formulators scaling export production seek dual-certified suppliers with shorter lead times than European alternatives. Pursue EXCiPACT certification as primary go-to-market credential for European tender access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pharmaceutical excipient specialists lacking backward integration into purified linter supply chains. Five-to-ten-year viability hinges on regulatory certification durability rather than commodity volume positioning. Monitor USP-NF and EP monograph revision cycles as inflection signals: specification tightening accelerates consolidation toward manufacturers with dedicated purification trains and analytical method redevelopment capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purified Cotton Linter | Captive raw material sourcing insulates Daicel Corporation and Ashland Inc. from harvest volatility and supply disruption. |
| EXCiPACT Certification Expansion | Third-party pharmaceutical excipient qualification creates market access pathways for qualified manufacturers into European tender evaluations. |
| Microcrystalline Cellulose Co-Processing Investment | Enhanced compaction properties enable displacement of wet granulation steps in high-shear generic pharmaceutical production. |
| Parenteral-Grade Dedicated Production Suites | Isolated purification trains with enhanced impurity profiling satisfy EMA's revised excipient risk assessment guidelines for ophthalmic applications. |
| Long-Term Supply Agreements with Audit Rights | Multi-year contracts with volume commitments reduce regulatory inspection exposure for European generic pharmaceutical procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, USP-NF monograph revisions, and trade customs data. Primary interviews engaged pharmaceutical formulators, excipient procurement managers, regulatory affairs directors, and plant managers at cellulose ether manufacturing facilities. Bottom-up volume estimates triangulate against top-down market sizing derived from downstream demand modeling across food, pharmaceutical, and industrial applications.
Segmentation dimensions modeled include product type chemistry, end-use industry vertical, formulation format, and grade-tier certification requirements across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns and forward-looking capacity expansion announcements. Forecast inputs incorporate REACH substance registration timelines, FSSAI enforcement trajectories in India, and NMPA alignment with ICH Q3D guidelines in China.
Underlying assumptions cover sustained pharmaceutical manufacturing expansion in India, stable cotton harvest yields for linter supply, and continued regulatory harmonization between USP-NF and EP monographs, with deviation risk concentrated in pharmacopeial specification revisions and EPA industrial discharge standard tightening. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Lubricating Oil Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Canada Water Enhancer Market
Additives
Epoxy Type Stabilizers Market
Additives
Choline Chloride Market
Additives
Drilling Fluid Additives Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Flux Injection System Market
Additives
Global Synthetic Tackifier Market
Additives
Lecithin and Phospholipids Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Carboxymethyl Cellulose Market
Additives
Saudi Arabia Feed Additives Market
Additives
Global Formulation Additives Market
Additives
Wax Additives Market