
 Refinery Process Additives Market | 2026-2036
Refinery Process Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Refinery Process Additives Market Outlook
Organometallic cobalt and manganese antiknock compounds is rebalancing toward non-metallic octane boosters as refiners face tighter metal-content specifications. BASF leverages its catalysts portfolio to anchor hydroprocessing additive supply across European refineries. Dorf Ketal Chemicals specializes in corrosion inhibitor packages for Middle Eastern sour crude operations. Clariant competes on reforming catalyst regeneration services that extend additive life cycles.
Refinery process additives comprise specialty chemicals formulated at active concentrations between 10 ppm and 5,000 ppm to modify interfacial properties, catalytic activity, or hydrocarbon flow behavior during crude distillation, conversion, and finishing. These formulations typically contain polyamine backbones, phosphate esters, or polyalphaolefin bases engineered to perform across temperature ranges from ambient to 450°C in hydrotreater environments. Corrosion inhibitors dominate value pools in hydroprocessing applications where hydrogen sulfide and ammonium bisulfide create aggressive aqueous phases. Octane boosters represent the fastest-growing product category as refiners phase out tetraethyl lead and methylcyclopentadienyl manganese tricarbonyl in response to automotive industry specifications for ultra-low-sulfur gasoline.
The EPA Tier 3 program mandates 10 parts per million gasoline sulfur ceilings, forcing refiners to increase hydrotreater severity and consume higher volumes of hydrogen sulfide scavengers and corrosion inhibitors. REACH registration requirements in Europe constrain the import of unregistered antifoam chemistries, creating compliance barriers for non-EU additive suppliers. Stakeholders must monitor how the EU Green Deal's carbon border adjustments affect the cost structure of imported refinery chemicals from regions with divergent emissions accounting standards.
Market Dynamics
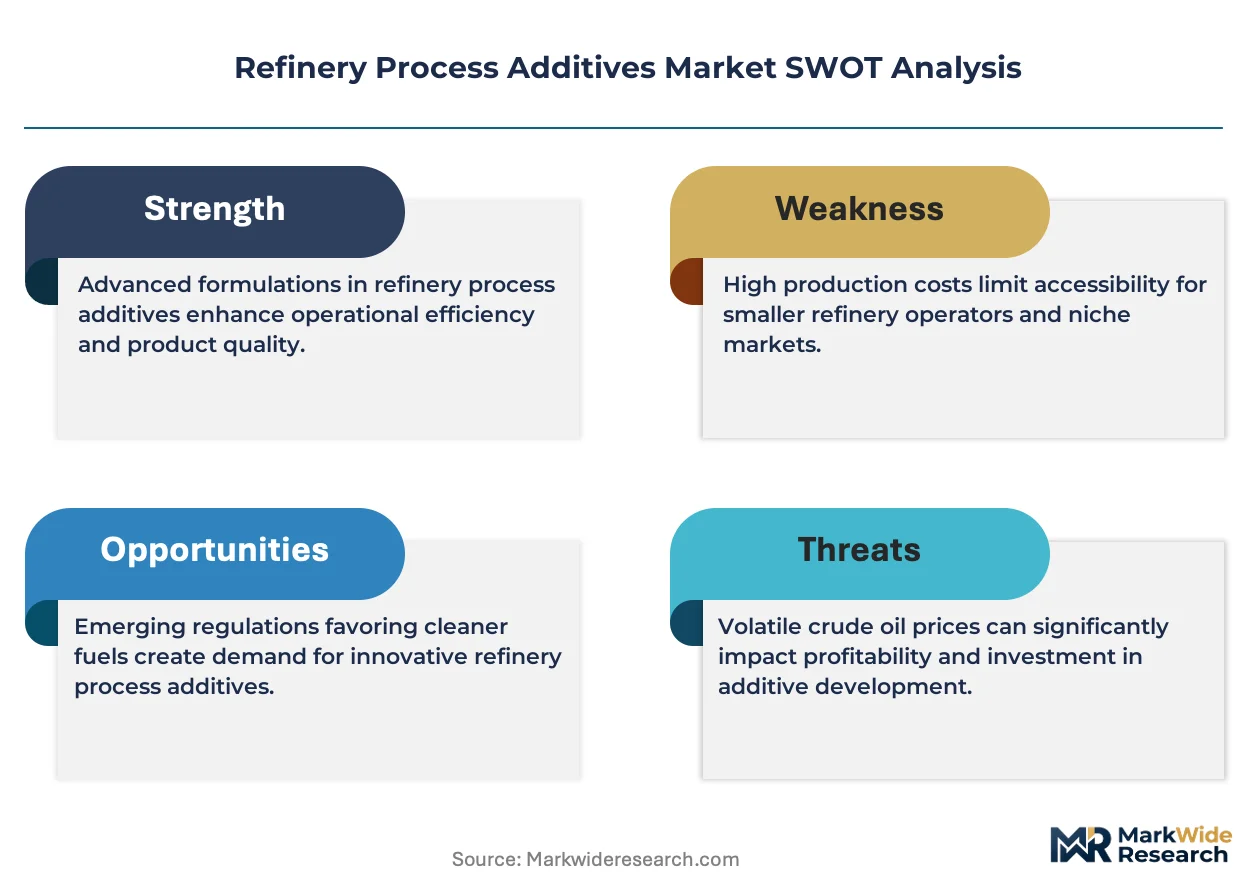
Refinery process additives markets face structural recalibration as hydroprocessing severity intensifies to meet ultra-low-sulfur fuel mandates, forcing additive consumption patterns toward corrosion inhibitors and hydrogen sulfide scavengers at the expense of traditional octane boosters.
Growth Catalysts
- EPA Tier 3 sulfur ceilings:The 10 ppm gasoline sulfur mandate compels refiners to increase hydrotreater severity, directly expanding demand for corrosion inhibitors and hydrogen sulfide scavengers in finishing units.
- Asia-Pacific heavy crude upgrading:State-owned refiners in China are expanding hydroprocessing capacity to process heavier crude slates, creating sustained pull for hydroprocessing additives across catalytic cracking and hydrotreating units.
- Non-metallic octane boosters:Automotive industry specifications for ultra-low-sulfur gasoline are accelerating the phase-out of tetraethyl lead and methylcyclopentadienyl manganese tricarbonyl, redirecting formulation demand toward organometallic-free alternatives.
Market Restraints
- REACH registration barriers:ECHA registration requirements constrain import of unregistered antifoam chemistries, creating compliance friction for non-EU additive suppliers seeking European market access.
- Raw material concentration:Polyamine backbone supply concentrates among specialty chemical producers in Germany and the Netherlands, exposing formulators to input cost volatility and supply disruption risk.
- Technical performance ceilings:Polyalphaolefin base stocks face thermal stability limitations above 450°C in high-severity hydrotreater environments, constraining additive efficacy in next-generation upgrading units.
Strategic Opportunities
- EU Green Deal carbon border adjustments:The emerging carbon border adjustment mechanism creates first-mover advantage for additive suppliers with verified low-carbon production processes and transparent emissions accounting.
- Reforming catalyst regeneration services:Clariant's service model demonstrates white space in extending additive life cycles through regeneration, creating recurring revenue streams distinct from commodity chemical sales.
- Middle Eastern sour crude processing:Dorf Ketal's corrosion inhibitor specialization for high-sulfur operations reveals underpenetrated demand in Saudi Arabian and Kuwaiti refineries processing increasingly sour feedstocks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in polyamine-phosphate ester compatibility and high-temperature stability testing remains concentrated among retiring cohorts at European and North American additive houses.
- Legacy system integration:Refinery distributed control systems require custom engineering to accommodate real-time additive injection monitoring, compling digitalization of additive dosing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinery Process Additives Market |
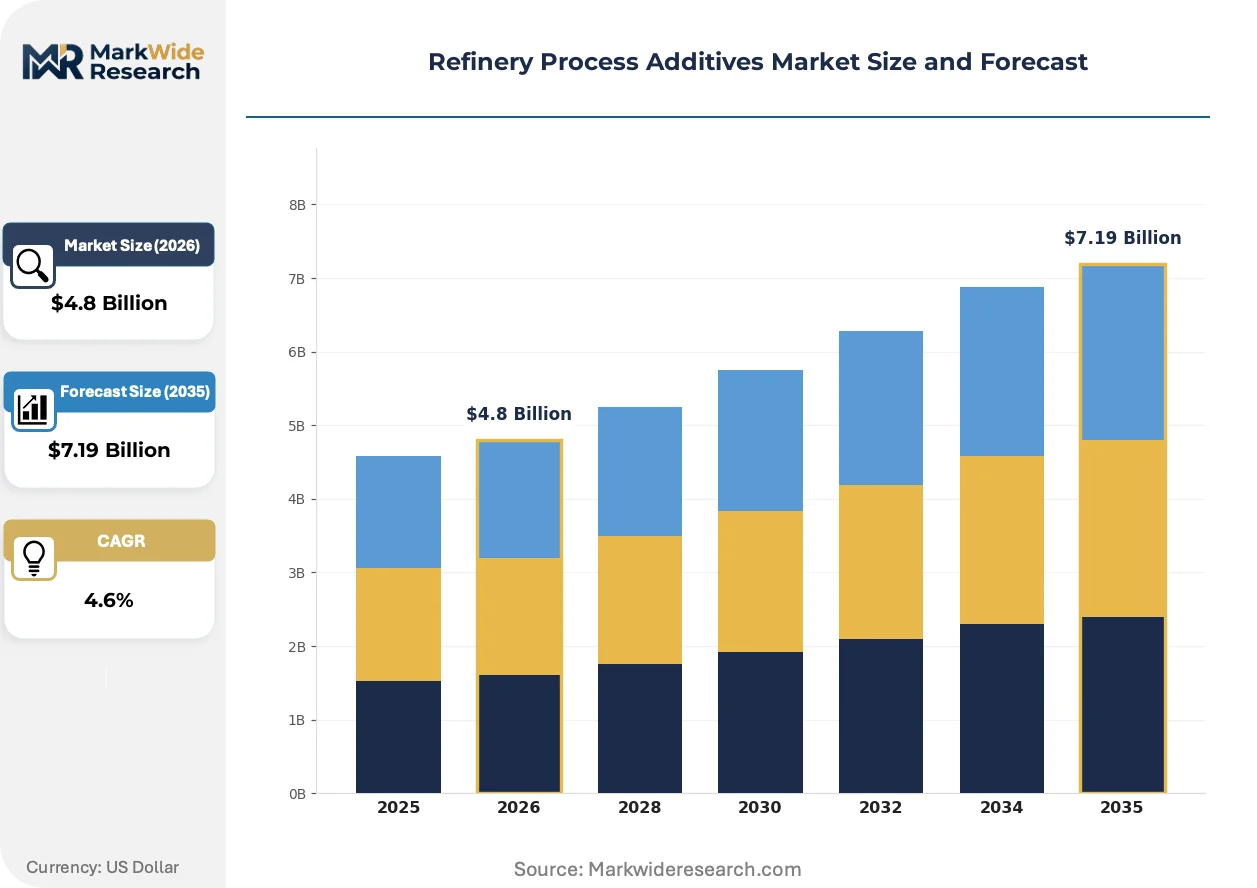
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Improvers, Corrosion Inhibitors, Anti-Foaming Agents, Octane Boosters Application: Crude Oil Processing, Fuel Additives, Lubricants, Diesel Fuel Treatment End User: Oil Refineries, Petrochemical Companies, Automotive Industry, Marine Sector Technology: Hydroprocessing, Catalytic Cracking, Reforming, Gas-to-Liquids |
| Companies Covered | Baker Hughes, Cestoil, BASF, Arkema, Dorf Ketal Chemicals, Ecolab, Grace Catalysts Technologies, Evonik Industries, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinery Process Additives Market Strategic Shifts
Additive chemistry is pivoting toward molecular architectures that withstand extreme hydroprocessing conditions while satisfying tightening metal-content specifications across multiple regulatory jurisdictions.
Ionic liquid catalyst modifiers are rewriting the economics of alkylation unit operations by enabling lower-temperature acid catalysis with reduced corrosion rates. US Gulf Coast refiners are piloting these formulations in sulfuric acid alkylation units, attracted by the prospect of extended run lengths between acid regeneration cycles. The technology is compressing capital requirements for alkylation capacity expansions by allowing retrofit of existing reactors rather than greenfield construction.
The EU F-Gas Regulation is forcing refrigerant-grade propylene and butylene producers to scrutinize additive packages for fluorinated compound contamination risks. Hydrocarbon processing units supplying feedstock to fluorocarbon refrigerant manufacturers now face downstream certification requirements that propagate through additive supply chains. European refiners are responding by demanding additive certificates of analysis with expanded fluorinated substance screening.
Refiner procurement patterns are consolidating annual additive contracts into multi-year framework agreements with embedded technical service obligations. This bundling displaces spot purchasing of commodity corrosion inhibitors and octane boosters, particularly visible among integrated oil companies operating across multiple US PADD districts. The shift compresses supplier margins on product sales while elevating profitability of on-site technical support and additive performance monitoring services.
Refinery Process Additives Market Segmentation
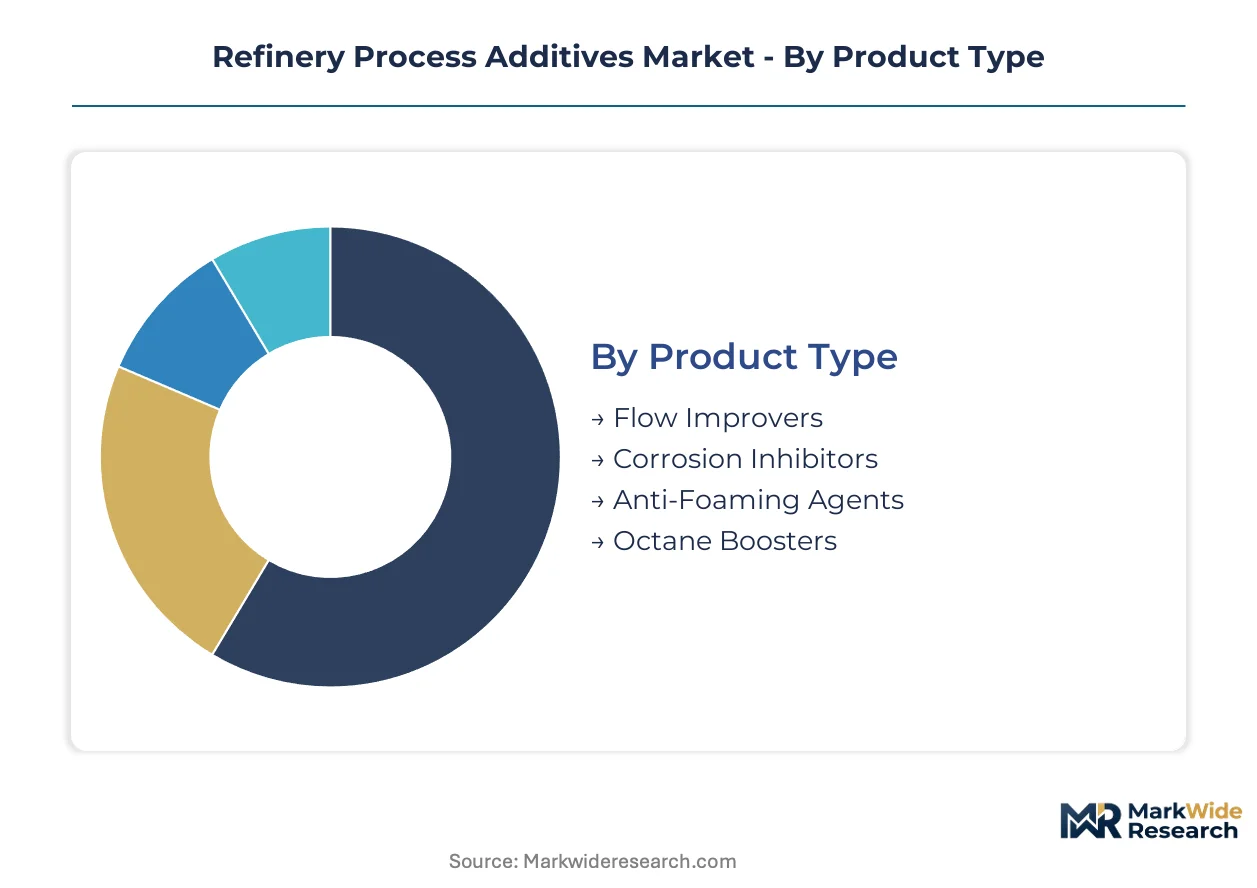
Refinery process additives demand fragments across multiple technical dimensions, with formulation chemistry and application severity determining procurement patterns. Certification requirements from EPA, REACH, and national standards bodies create divergent compliance burdens across segment categories.
Product Type:
REACH registration requirements in Europe constrain antifoam chemistries, while EPA Tier 3 sulfur ceilings reshape corrosion inhibitor specifications across US refineries.
- Corrosion Inhibitors:Polyamine-phosphate ester formulations dominate hydroprocessing applications where hydrogen sulfide and ammonium bisulfide generate aggressive aqueous phases. Demand concentrates in US Gulf Coast refineries upgrading hydrotreater severity to meet EPA Tier 3 mandates, forcing higher active concentrations in finishing units.
- Octane Boosters:Organometallic-free alternatives displace tetraethyl lead and methylcyclopentadienyl manganese tricarbonyl as automotive specifications tighten for ultra-low-sulfur gasoline. Chinese state-owned refiners anchor volume growth, upgrading catalytic cracking units to produce higher-octane reformate.
- Flow Improvers:Polyalphaolefin base stocks reduce pour point depression in cold-climate pipeline transport.
- Anti-Foaming Agents:Silicone and polyether-modified chemistries prevent entrainment in amine treating units.
Leading the category by volume: Corrosion Inhibitors. Growing fastest: Octane Boosters.
Application:
Application severity determines formulation economics, with hydrotreater environments demanding thermal stability above 450°C.
- Crude Oil Processing:Demulsifier and desalting additive packages separate water and solids from incoming feedstocks. Saudi Arabian and Kuwaiti refineries processing sour crudes drive specialized corrosion inhibitor demand.
- Fuel Additives:Sulfur scavengers and combustion improvers meet finished product specifications. European refiners face EU F-Gas Regulation downstream certification requirements for fluorinated compound screening.
- Lubricants:Viscosity index improvers and antioxidant packages extend base oil performance.
- Diesel Fuel Treatment:Cetane improvers and cold flow additives address seasonal operability.
Highest value concentration: Crude Oil Processing. Steepest expansion trajectory: Fuel Additives.
End User:
Procurement authority varies by vertical integration depth, with integrated majors bundling multi-year framework agreements.
- Oil Refineries:Direct additive consumption spans distillation, conversion, and finishing units. Integrated oil companies operating across multiple US PADD districts consolidate annual contracts into technical service-embedded agreements.
- Petrochemical Companies:Feedstock pretreatment additives protect steam cracker furnaces from heavy metals and asphaltenes.
- Automotive Industry:Downstream specifications propagate backward into refinery additive selection for gasoline and diesel quality.
- Marine Sector:IMO 2020 low-sulfur fuel compliance drives residual fuel stabilizer and combustion catalyst demand.
Dominant procurement volume: Oil Refineries. Gaining share fastest: Marine Sector.
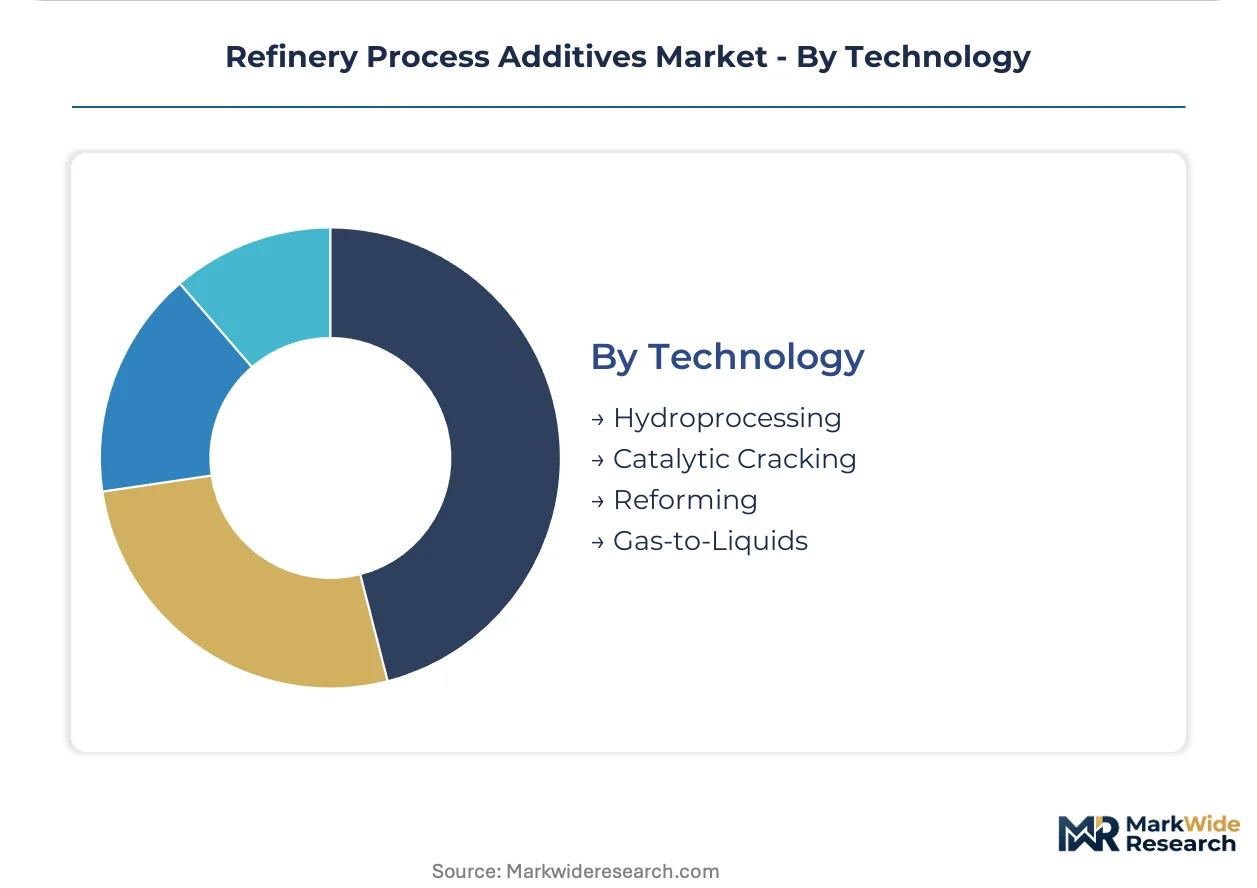
Technology:
Process severity and hydrogen partial pressure dictate additive degradation rates and injection frequency.
- Hydroprocessing:Hydrotreating and hydrocracking units consume hydrogen sulfide scavengers and high-temperature corrosion inhibitors. Asia-Pacific refiners expanding capacity to process heavier crude slates sustain demand pull across catalytic cracking and hydrotreating units.
- Catalytic Cracking:Fluid catalytic cracking additives include metal passivators and SOx reduction catalysts. Chinese refinery upgrades concentrate demand for FCC catalyst and additive packages.
- Reforming:Continuous catalyst regeneration units require chloride injection and sulfur guard systems.
- Gas-to-Liquids:Fischer-Tropsch wax upgrading employs specialty pour point depressants.
Maximum additive intensity: Hydroprocessing. Climbing the fastest: Catalytic Cracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates hydroprocessing additive demand as state-owned refiners upgrade catalytic cracking units to process heavier crude slates. The United States and Germany anchor corrosion inhibitor consumption through EPA Tier 3 and EU F-Gas regulatory enforcement. Saudi Arabia and India round out the five-country demand matrix through sour crude processing expansion and national refinery modernization programs.
China
Sinopec and PetroChina are expanding hydrotreating capacity across Shandong and Guangdong provinces to handle deteriorating crude quality from Middle Eastern suppliers. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emissions standards for refinery additive formulations. The Yangtze River Delta cluster around Shanghai concentrates specialty chemical production for domestic hydroprocessing additive supply.
United States
Gulf Coast refineries from Texas to Louisiana are increasing hydrotreater severity to meet EPA Tier 3 gasoline sulfur ceilings of 10 ppm. The Environmental Protection Agency mandates expanded monitoring of hydrogen sulfide scavenger efficacy in finishing units. The Houston Ship Channel industrial corridor anchors corrosion inhibitor formulation and technical service operations for PADD III refineries.
Germany
REACH registration requirements constrain antifoam chemistry imports while driving domestic polyamine backbone production for hydroprocessing additives. ECHA compliance obligations force non-EU suppliers to establish EU-registered formulation partnerships. The Rhine-Ruhr industrial region around Leverkusen and Ludwigshafen concentrates BASF's catalyst and additive manufacturing infrastructure.
Saudi Arabia
Saudi Aramco is processing increasingly sour crude at Jubail and Yanbu refineries, elevating demand for specialized corrosion inhibitor packages. The national hydrocarbon regulator imposes product quality specifications that propagate through additive procurement contracts. The Eastern Province industrial cities of Jubail and Ras Tanura concentrate sour crude upgrading capacity and associated chemical treatment demand.
India
Indian Oil Corporation and Reliance Industries are expanding catalytic cracking capacity to produce higher-octane gasoline for domestic automotive markets. The Bureau of Indian Standards implements fuel quality norms that tighten sulfur and metal-content specifications. The Gujarat refining corridor around Jamnagar and Vadodara anchors hydroprocessing additive consumption for heavy crude processing units.
Refinery Process Additives Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates holding concentrated positions in corrosion inhibitors and hydrogen sulfide scavengers while regional formulators capture spot demand in octane boosters. The vendor structure tieres across three archetypes: catalyst-anchored diversified majors, refinery-service specialists, and regional chemical distributors. M&A activity concentrates on hydroprocessing additive portfolios, and backward integration into polyamine backbone production represents the dominant capacity expansion vector.
Among European diversified majors, BASF and Clariant exemplify catalyst-anchored strategies that bundle additive supply with technical regeneration services. Dorf Ketal Chemicals occupies a position within the Middle Eastern specialist tier, representing corrosion inhibitor formulation expertise for sour crude operations. These three company anchors illustrate how geographic proximity to refinery clusters and regulatory compliance depth determine competitive positioning across the hydroprocessing additive value chain.
| Leading Market Players |
|---|
| Baker Hughes |
| Cestoil |
| BASF |
| Arkema |
| Dorf Ketal Chemicals |
| Ecolab |
| Grace Catalysts Technologies |
| Evonik Industries |
| Clariant |
| Others |
Value Chain & Pricing Dynamics
Integrated oil companies operating across multiple US PADD districts anchor procurement volume and enforce contract-based long-term offtake agreements that bundle technical service obligations with additive supply, compressing spot-market pricing power for commodity formulators.
Pricing Analysis
Volume concentrates in corrosion inhibitors while margins concentrate in specialty octane boosters with organometallic-free certification. Three-tier pricing structure across premium, standard, and economy levels differentiates by REACH registration status and thermal stability grade. Cost compression in standard-tier polyamine formulations is intensifying because German and Dutch backbone producers face energy input volatility. National oil companies in China and Saudi Arabia exhibit lowest price sensitivity due to operational criticality; independent refiners in India show highest sensitivity to per-unit additive costs.
Supply Chain Analysis
Catalyst regeneration services and spent additive recovery flows are emerging as reverse-logistics value pools, with Clariant's technical service model demonstrating embedded circularity in European reforming operations. Polyamine backbone production concentrates in Germany, the Netherlands, and Belgium, while active ingredient formulation clusters in the US Gulf Coast and China's Yangtze River Delta. Supply chain risk rests on single-source vulnerability for high-purity phosphate esters used in hydrotreater corrosion inhibitors. Distribution runs through refinery-integrated chemical terminals with direct injection system compatibility requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration and EPA Tier 3 certification create barrier-to-entry moats that protect incumbent positions from unregistered import competition.
For Market Incumbents: To counter formulation chemist scarcity as retiring European cohorts exit, anchor technical talent through university partnerships in Leverkusen and Ludwigshafen. Prioritize backward integration into polyamine backbone production to secure input cost control against Dutch and German supply volatility.
For New Entrants and Emerging Players: Capture white space in Middle Eastern sour crude corrosion inhibitor packages where Dorf Ketal's specialization reveals underpenetrated Saudi Aramco and Kuwait Petroleum demand. Target India's Gujarat refining corridor for hydroprocessing additive technical partnerships with Indian Oil Corporation and Reliance Industries.
For Investors and Strategic Acquirers: The window for entry favors catalyst-anchored diversified majors with verified low-carbon production processes ahead of EU Green Deal carbon border adjustment implementation. Monitor ECHA registration timelines for unregistered antifoam chemistries as inflection indicator for import competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamine Production | BASF's captive supply of backbone chemistries insulates European formulators from Dutch energy cost volatility. |
| REACH Registration Investment | Full ECHA compliance unlocks EU market access for corrosion inhibitor and antifoam product lines. |
| Catalyst Regeneration Service Expansion | Clariant's technical service model extends additive life cycles and creates recurring revenue distinct from commodity sales. |
| Middle Eastern Sour Crude Specialization | Dorf Ketal's corrosion expertise aligns with Saudi Aramco's increasingly sour feedstock processing at Jubail and Yanbu. |
| Multi-Year Framework Agreement Conversion | Integrated oil companies across US PADD districts consolidate spot purchasing into technical service-embedded contracts. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with refinery procurement managers, hydroprocessing unit engineers, and specialty chemical R&D directors with validation against ECHA registration databases, EPA compliance disclosures, and SEC 10-K chemical segment filings. Bottom-up additive consumption estimates by refinery unit type triangulated against top-down market value reconstructions.
Data-stream reconciliation across supply-side capacity announcements and demand-side refinery upgrade project tracking shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product chemistry class, application severity tier, end-user vertical integration depth, and regional regulatory cluster. CAGRs derived from intensity-factor modeling of additive consumption per barrel processed, with forecast inputs incorporating hydroprocessing capacity expansion timelines and sulfur specification phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation timing and polyamine supply chain restructuring. Practitioners should monitor ECHA substance evaluation list updates and EPA Tier 3 enforcement intensity for early signals of compliance cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Propyl Gallate Market
Additives
Metal Modifiers Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Global Cement and Concrete Additives Market
Additives
1,4 Butanediol Derivatives Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Sodium Metabisulfite Market
Additives
Allura Red AC Market
Additives
South America Sodium Reduction Agents Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Cosmetic Grade Color Additives Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Ammonium Acetate Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Electrolyte Additives for Lithium Ion Battery Market