
 France Patient Monitoring Market | 2026-2036
France Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
France Patient Monitoring Market Foresight
Remote monitoring subscription services is pivoting vendor revenue models from capital equipment to recurring per-bed fees. Medtronic leverages its cardiac monitoring platform to anchor hospital loyalty through long-term service contracts. Koninklijke Philips competes on integrated software ecosystems that unify telemetry data across ward levels. GE Healthcare sustains installed-base profitability through predictive maintenance contracts on legacy monitoring networks.
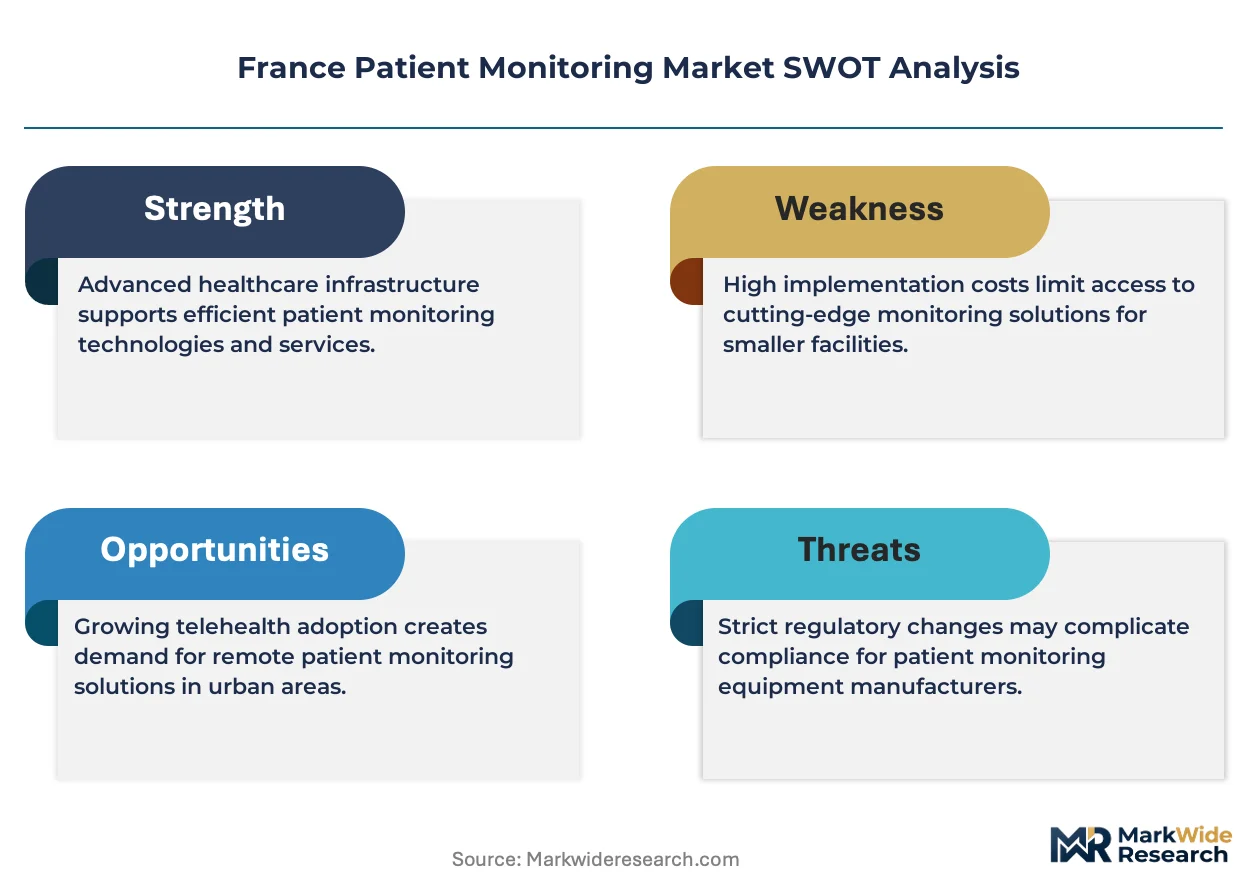
Patient monitoring encompasses devices and systems that acquire, process, and display physiological parameters including electrocardiogram waveforms, blood oxygen saturation via pulse oximetry, and invasive blood pressure through arterial catheters, serving to enable early detection of clinical deterioration in acute and ambulatory settings. Cardiac monitoring occupies the dominant revenue position due to post-acute cardiovascular disease management protocols, while wireless monitoring represents the fastest-expanding deployment mode as French hospitals replace tethered bedside units with wearable biosensors that permit patient mobility. Home healthcare emerges as a concentrated margin pool where reimbursement pathways for remote therapeutic monitoring are stabilizing.
ANSM enforces post-market surveillance obligations under the EU Medical Device Regulation, compelling manufacturers to maintain clinical follow-up registries for Class IIa and higher monitoring devices. The CNIL imposes strict health data localization and patient consent architectures on cloud-connected monitoring platforms, raising compliance costs for vendors operating centralized European data lakes. Stakeholders must weigh the capital requirements of MDR technical documentation against the recurring revenue potential of software-enabled monitoring services as purchasing authority shifts from biomedical engineering departments to chief information officers.
Market Dynamics
France's patient monitoring sector is experiencing a fundamental shift from capital-intensive bedside hardware to software-enabled service contracts, with purchasing authority migrating from biomedical engineering departments to hospital chief information officers who prioritize interoperability and cybersecurity compliance.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:The MDR's unified clinical evidence requirements streamline cross-border device approvals, enabling French manufacturers to access broader European hospital procurement frameworks without redundant conformity assessments.
- Paris-Ile-de-France hospital cluster consolidation:France's largest hospital network is standardizing remote monitoring platforms across 39 public hospitals, creating concentrated demand for scalable telemetry solutions.
- Wearable biosensor miniaturization:Advances in flexible electronics and low-power Bluetooth protocols enable continuous cardiac monitoring without restricting patient mobility, accelerating replacement of tethered bedside units in acute care wards.
Market Restraints
- ANSM post-market surveillance obligations:The French regulator mandates clinical follow-up registries for Class IIa and higher monitoring devices, imposing recurring documentation costs that disproportionately burden mid-tier manufacturers with limited regulatory affairs capacity.
- CNIL data localization requirements:France's data protection authority enforces strict health data residency and patient consent architectures, preventing vendors from leveraging centralized European cloud infrastructure and raising operational complexity.
- Semiconductor component concentration:Patient monitoring devices rely on specialized analog-to-digital converters and MEMS sensors sourced from a concentrated Asian supplier base, exposing French manufacturers to supply volatility and extended lead times.
Strategic Opportunities
- Auvergne-Rhône-Alpes regional health autonomy:France's second-largest metropolitan region outside Paris is developing independent digital health infrastructure, creating procurement opportunities for vendors outside the Ile-de-France supply chain.
- Home healthcare reimbursement stabilization:France's national health insurance fund (Assurance Maladie) is formalizing remote therapeutic monitoring tariff codes, unlocking predictable revenue streams for ambulatory monitoring services.
- AI-enabled arrhythmia detection convergence:Integration of machine learning algorithms with conventional ECG telemetry is creating differentiated product categories that command premium positioning in cardiac monitoring segments.
Industry Challenges
- Embedded systems cybersecurity certification:ANSM and CNIL jointly require IEC 62304 medical device software lifecycle compliance alongside ANSSI cybersecurity certification, extending product development timelines by 12-18 months for connected monitoring platforms.
- Interoperability with legacy hospital information systems:French public hospitals operate heterogeneous IT estates spanning multiple decades of procurement, forcing vendors to maintain costly backward compatibility layers for HL7 v2.x integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Patient Monitoring Market |
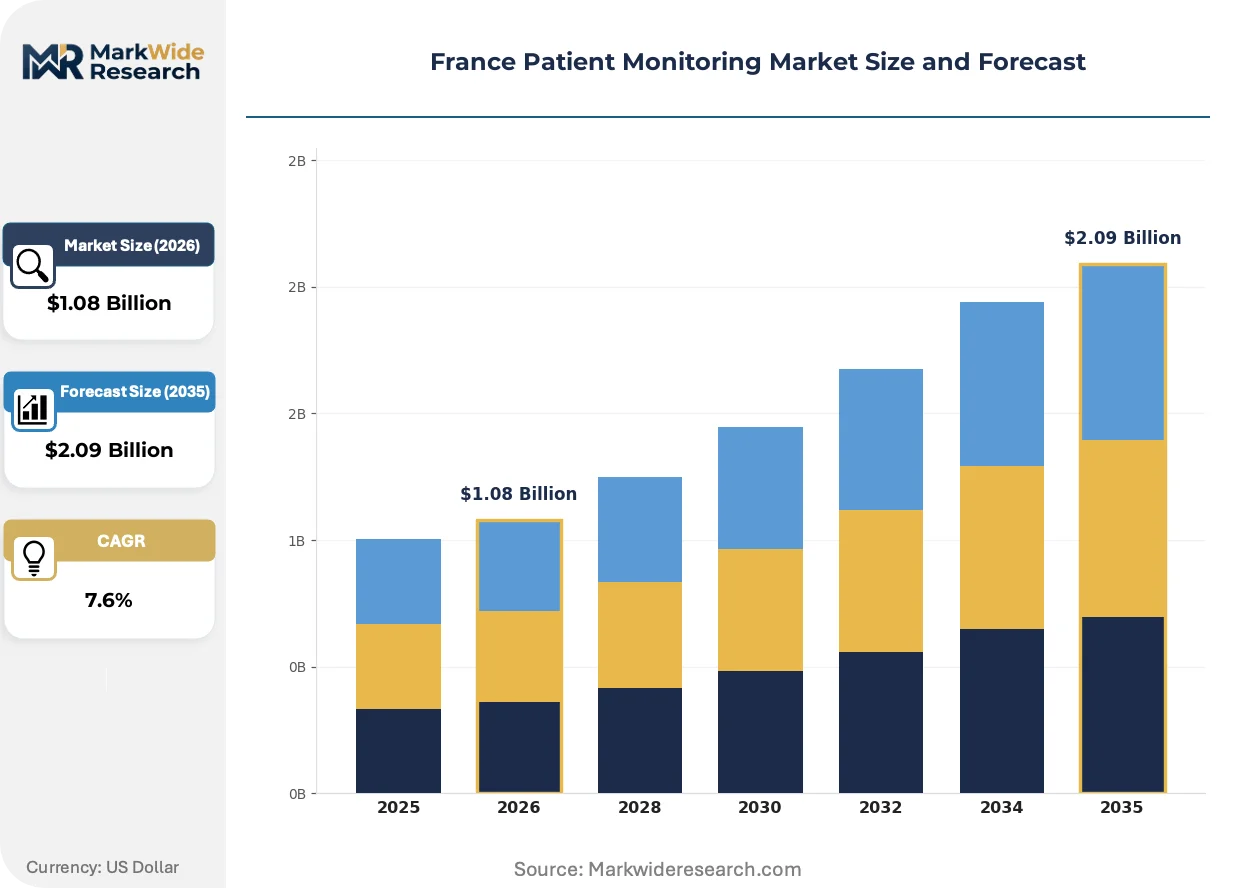
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.09 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vital Signs Monitor, Fetal Monitor, Cardiac Monitor, Respiratory Monitor, Temperature Monitor Application: Cardiology, Pulmonology, Obstetrics, Neurology, Intensive Care End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Diagnostic Laboratories, Rehabilitation Centers Deployment: Wired Monitoring, Wireless Monitoring, Invasive Monitoring, Non-Invasive Monitoring |
| Companies Covered | Medtronic, Koninklijke Philips, GE Healthcare, Siemens Healthineers, Abbott Laboratories, Draegerwerk AG, Masimo Corporation, Beckton, Dickinson & Company, Omron Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Patient Monitoring Market Shifts & Advancements
Wireless connectivity architectures and artificial intelligence integration are fundamentally restructuring how physiological data flows from patients to clinical decision-makers across French healthcare institutions.
Bluetooth Low Energy mesh networks for continuous vital sign transmission are electrifying the technical foundation of inpatient monitoring. French university hospitals in Lyon and Marseille are deploying these networks to eliminate telemetry dead zones during patient transport. The technology is electrifying vendor competitive dynamics by shifting differentiation from hardware specifications to software reliability and cybersecurity architecture.
The EU Medical Device Regulation's strengthened clinical evidence requirements are compressing market access timelines for novel monitoring algorithms. French manufacturers must now submit prospective clinical data for software-as-a-medical-device classifications, raising barriers for AI diagnostic modules. Cardiac monitoring segments face the most acute compliance burden due to the MDR's heightened scrutiny of life-sustaining device categories.
Hospital purchasing committees are consolidating vendor relationships to reduce cybersecurity audit overhead. French public hospitals are replacing fragmented point solutions with enterprise-wide platform contracts that bundle devices, software, and managed services. This concentration is most visible in the Provence-Alpes-Côte d'Azur region, where regional health agencies are centralizing procurement authority previously held by individual hospital biomedical departments.
France Patient Monitoring Market Segmentation
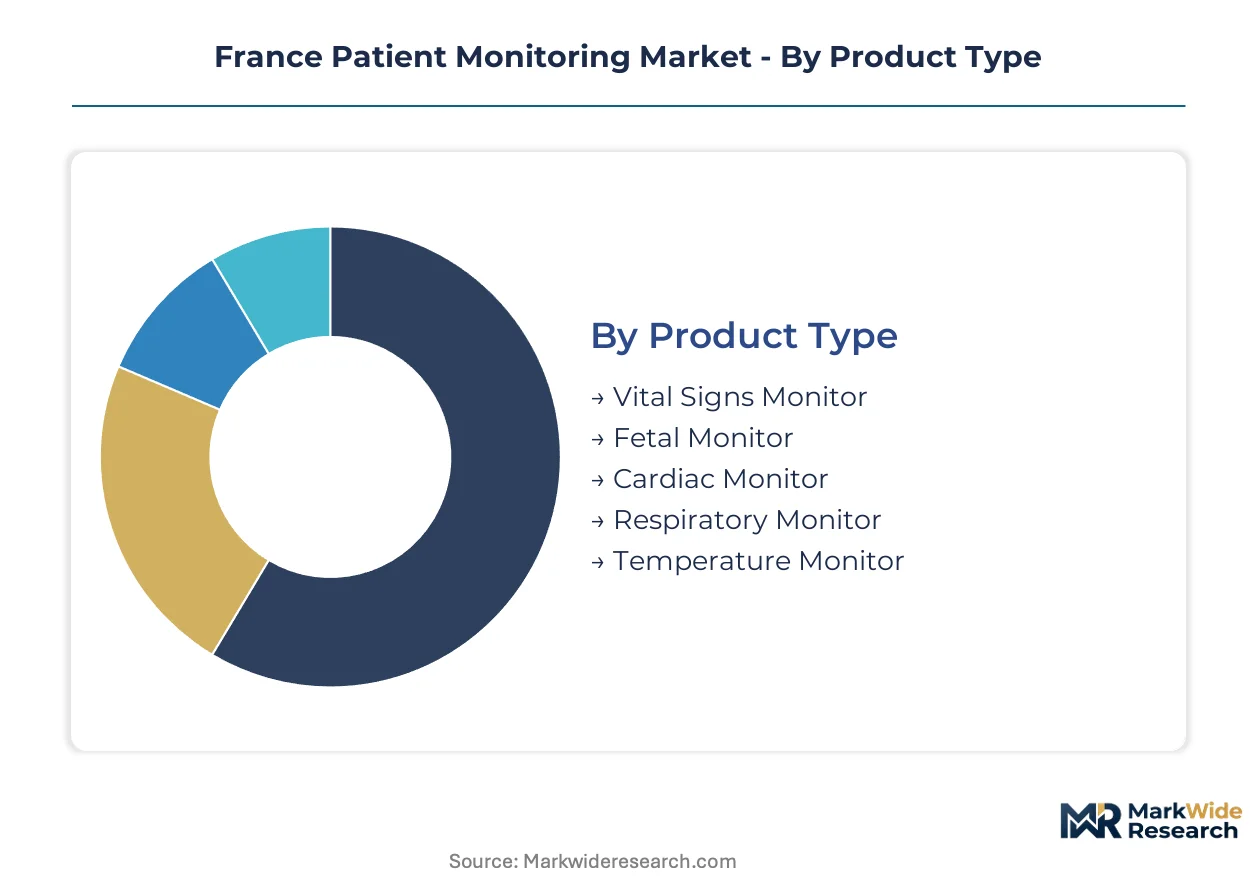
Segmentation in the France patient monitoring market reveals how purchasing authority, clinical workflow requirements, and reimbursement pathways fragment demand across distinct technical and operational dimensions. Understanding these divides helps vendors align product development with the specific compliance and interoperability pressures facing each buyer category.
Product Type:
Hospital procurement committees differentiate capital allocation based on whether devices anchor enterprise-wide platform contracts or address specialized departmental needs.
- Cardiac Monitor:Continuous electrocardiogram acquisition with arrhythmia detection algorithms dominates telemetry ward deployments. Paris-Ile-de-France hospital cluster standardization is driving consolidated purchasing of scalable cardiac monitoring platforms across 39 public hospitals.
- Vital Signs Monitor:Multi-parameter bedside units measuring heart rate, blood pressure, and pulse oximetry serve as the workhorse infrastructure in general wards. French regional health agencies are replacing aging installed bases with wireless-enabled models to support patient mobility initiatives.
- Fetal Monitor:Intrapartum cardiotocography systems track fetal heart rate and uterine contractions during labor. Obstetrics departments in university hospitals prioritize integrated documentation workflows.
- Respiratory Monitor:Capnography and respiratory rate sensors support ventilator weaning protocols in step-down units. Pulmonology services in Lyon and Marseille academic centers are expanding remote respiratory monitoring programs.
- Temperature Monitor:Continuous core temperature tracking via zero-heat-flux or invasive probes addresses perioperative hypothermia prevention. Surgical suites in Auvergne-Rhône-Alpes region hospitals are adopting automated temperature documentation.
Cardiac monitors lead volumes today; wireless-enabled vital signs monitors are gaining share fastest.
Application:
Clinical specialty requirements determine the sophistication of algorithmic analysis and the stringency of MDR clinical evidence obligations.
- Cardiology:Post-acute cardiovascular disease management protocols generate sustained demand for ambulatory ECG monitoring. ANSM mandates enhanced post-market surveillance for life-sustaining cardiac devices, elevating documentation burdens.
- Intensive Care:Multi-organ failure monitoring requires integration of hemodynamic, neurological, and respiratory parameters into unified dashboards. French ICU networks are consolidating vendor relationships to reduce cybersecurity audit overhead.
- Pulmonology:Sleep-disordered breathing and home ventilation monitoring are expanding with Assurance Maladie reimbursement formalization. Remote therapeutic monitoring tariff codes are stabilizing revenue predictability.
- Obstetrics:Maternal-fetal monitoring prioritizes alarm fatigue reduction and seamless electronic health record integration. Perinatal networks in Provence-Alpes-Côte d'Azur are standardizing telemetry platforms.
- Neurology:Continuous EEG and intracranial pressure monitoring serve stroke and trauma patient pathways. Specialized neurocritical care units in Parisian academic hospitals drive premium equipment specifications.
Cardiology commands the largest revenue pool; intensive care applications are expanding most quickly as regional health agencies centralize procurement.
End User:
Facility type determines reimbursement pathway clarity, capital budget scale, and the complexity of legacy information system integration.
- Hospitals:Public hospital biomedical engineering departments retain purchasing authority for devices, while chief information officers increasingly control software and service contracts. Heterogeneous IT estates spanning multiple decades force vendors to maintain costly HL7 v2.x backward compatibility.
- Home Healthcare:Remote therapeutic monitoring reimbursement stabilization is concentrating margin opportunity in ambulatory services. CNIL data localization requirements prevent centralized European cloud infrastructure, raising operational complexity for platform vendors.
- Ambulatory Surgical Centers:Same-day procedure monitoring demands compact, rapid-deployment vital signs systems. Ile-de-France outpatient surgery networks are standardizing pre-operative assessment protocols.
- Diagnostic Laboratories:Exercise stress testing and sleep study monitoring require specialized acquisition equipment. Cardiopulmonary testing volumes are recovering in regional hospital-affiliated labs.
- Rehabilitation Centers:Post-stroke and cardiac recovery monitoring supports functional outcome documentation. Auvergne-Rhône-Alpes regional autonomy is creating independent procurement frameworks outside Paris supply chains.
Hospitals dominate installed base value; home healthcare is climbing the fastest as reimbursement pathways mature.
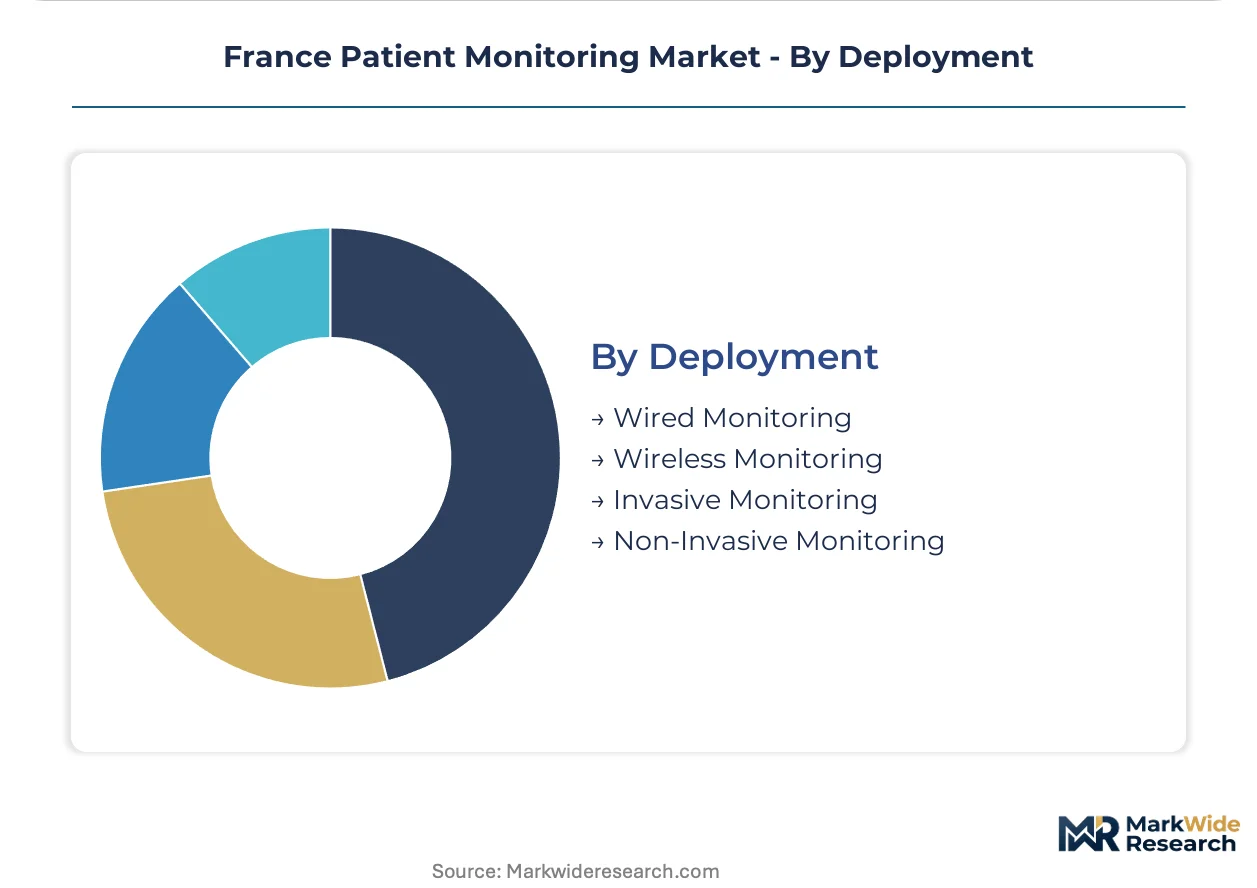
Deployment:
Connectivity architecture choices determine cybersecurity certification requirements and the feasibility of centralized data analytics.
- Wireless Monitoring:Bluetooth Low Energy mesh networks enable continuous vital sign transmission without patient mobility restriction. French university hospitals in Lyon and Marseille are deploying these to eliminate telemetry dead zones during transport.
- Non-Invasive Monitoring:Surface sensors for ECG, pulse oximetry, and blood pressure avoid procedural risk and infection concerns. General ward standardization is accelerating replacement of invasive alternatives.
- Wired Monitoring:Tethered bedside units retain role in high-acuity settings requiring guaranteed signal integrity. Legacy installed bases in older hospital wings sustain maintenance contract profitability.
- Invasive Monitoring:Arterial catheters and central venous pressure lines deliver precision hemodynamic data in shock management. Cardiac surgery and ICU settings maintain demand despite infection control protocols.
Non-invasive monitoring anchors current deployment volumes; wireless architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial health technology base contrasts with France's hospital-centric procurement consolidation, while both face converging EU Medical Device Regulation compliance timelines that reshape competitive access across continental Europe.
Germany
Precision engineering capabilities and Mittelstadt industrial networks sustain domestic manufacturing of monitoring sensors and embedded systems. The Federal Institute for Drugs and Medical Devices enforces MDR transition deadlines that compress approval timelines for software-enabled devices. Baden-Württemberg's Stuttgart-Karlsruhe corridor hosts specialized sensor fabricators supplying French hospital networks.
United Kingdom
NHS digital transformation programs accelerate demand for cloud-integrated monitoring platforms despite post-Brexit regulatory divergence. The Medicines and Healthcare products Regulatory Agency maintains transitional recognition of CE-marked devices while building independent assessment capacity. London's academic hospital trusts pilot AI-augmented telemetry systems that influence French procurement specifications.
Netherlands
Health technology distribution hubs and logistics infrastructure position Dutch intermediaries as gatekeepers for Benelux hospital supply chains. The Healthcare and Youth Inspectorate coordinates with French ANSM on post-market surveillance data sharing for cross-border device performance. Eindhoven's high-tech campus concentration drives wearable biosensor miniaturization that penetrates French home healthcare markets.
Switzerland
Swiss precision manufacturing and bilateral EU agreements preserve market access for monitoring device components despite non-member status. Swissmedic maintains MDR alignment through mutual recognition treaties that streamline French import certification. Basel-Zurich pharmaceutical-industrial clusters supply specialized hemodynamic sensors to Paris-Ile-de-France cardiac surgery centers.
Italy
Regional health system fragmentation creates patchwork procurement environments that contrast with France's national standardization. The Italian Medicines Agency enforces MDR clinical evidence requirements that parallel French ANSM surveillance obligations. Lombardy's Milan hospital network pursues independent digital health infrastructure investments that diverge from Paris cluster consolidation patterns.
France Patient Monitoring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform vendors capturing enterprise hospital contracts while component specialists penetrate departmental point solutions. The vendor base concentrates around three strategic tiers: integrated platform providers bundling devices with managed services, modular hardware specialists targeting replacement cycles, and software analytics firms licensing algorithmic modules to OEMs. Dominant competitive moves include long-term service contract anchoring to lock in hospital loyalty, and predictive maintenance offerings that monetize legacy installed bases.
Within the integrated platform tier, Medtronic and Koninklijke Philips occupy positions exemplifying contrasting approaches to hospital relationship depth—one leveraging cardiac monitoring specialization, the other competing on cross-ward software unification. GE Healthcare represents the installed-base monetization archetype through service contract structures on aging telemetry networks. These three anchors illustrate how vendor strategy diverges between platform consolidation and point-solution specialization across French public hospital procurement frameworks.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips |
| GE Healthcare |
| Siemens Healthineers |
| Abbott Laboratories |
| Draegerwerk AG |
| Masimo Corporation |
| Beckton, Dickinson & Company |
| Omron Healthcare |
| Others |
Supply & Pricing Matrix
Captive integration into European sensor fabrication anchors both supply security and pricing power for French patient monitoring vendors confronting ANSM certification costs. Manufacturers that control MEMS foundry relationships or maintain long-term analog-to-digital converter offtake agreements extract margin advantages over competitors exposed to Asian spot-market volatility. This structural positioning shapes how procurement committees evaluate total cost of ownership across hardware and service bundles.
Pricing Analysis
Capacity additions in Germany's Stuttgart-Karlsruhe corridor are reshaping price floors for specialized monitoring sensors, pressuring legacy premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified enterprise platforms from departmental point solutions and refurbished legacy units. Cost compression in the standard tier is intensifying because regional health agencies consolidate purchasing volumes. Ambulatory surgical centers exhibit the highest price sensitivity due to capital budget constraints, while Paris-Ile-de-France hospital clusters prioritize cybersecurity architecture over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for specialized analog-to-digital converters and MEMS accelerometers that enable wearable biosensor miniaturization. French assembly operations draw from Chinese flexible electronics substrates, German precision machining components, and Swiss hemodynamic sensor modules. Tariff exposure on semiconductor inputs threatens margin stability for mid-tier manufacturers lacking long-term supply agreements. Distribution runs through Dutch health technology logistics hubs that gatekeep Benelux hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's patient monitoring sector offers geographic-arbitrage value through regulatory compliance cost differentials between MDR-harmonized European markets and post-Brexit UK divergence paths. Vendors that front-load ANSM technical documentation investment capture accelerated access to German and Benelux procurement frameworks.
For Market Incumbents: Acquire AI-enabled arrhythmia detection algorithm portfolios to defend against software-as-a-medical-device entrants threatening cardiac monitoring margins. Consolidate cybersecurity certification capabilities to reduce hospital audit overhead and extend contract renewal cycles. Capacity addition in Auvergne-Rhône-Alpes regional manufacturing anchors supply resilience outside Paris-Ile-de-France concentration. For New Entrants and Emerging Players: Begin with home healthcare remote therapeutic monitoring services where Assurance Maladie reimbursement formalization creates predictable revenue streams outside hospital capital budget cycles. Target pulmonology ambulatory monitoring as the most penetrable clinical specialty given sleep-disordered breathing program expansion. Pursue white-label software companion development for established device OEMs lacking algorithmic differentiation. For Investors and Strategic Acquirers: Roll-up economics work for modular hardware specialists because regional health agency procurement consolidation favors vendors with backward-compatible HL7 integration capabilities across heterogeneous hospital IT estates. Five-to-ten year viability hinges on MDR software classification expertise as AI diagnostic modules face heightened clinical evidence requirements. Watch ANSM post-market surveillance registry completion rates as an inflection indicator for vendor regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates cross-border European hospital procurement access beyond French borders. |
| Hospital System Partnership | Locks in multi-year telemetry platform contracts across Paris-Ile-de-France cluster consolidation. |
| Software Companion Development | Captures recurring SaaS revenue streams alongside capital equipment sales cycles. |
| Cybersecurity Certification Program | Satisfies joint ANSM-CNIL-ANSSI compliance requirements extending product development timelines. |
| Reimbursement Strategy | Aligns remote therapeutic monitoring offerings with Assurance Maladie tariff code formalization. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down device shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineering directors, hospital chief information officers, GPO contracts managers, and ANSM regulatory affairs specialists combined with secondary validation from hospital procurement databases, GPO contract repositories, and EU MDR notified body filings. Supply-side triangulation against French customs records and Benelux distribution channel data anchors volume estimates.
Historical trendline analysis across installed base replacement cycles and software subscription renewal patterns informs projection methodology. Segmentation dimensions modeled include product type, clinical application, end-user facility category, deployment architecture, and regional health agency procurement cluster. CAGRs derive from weighted average growth assumptions across these segments, with specific inputs from wearable biosensor adoption trajectories and AI diagnostic module regulatory approval timelines.
Several conditions sit outside the modeled scope, including potential MDR implementation deadline extensions, ANSM staffing capacity constraints affecting approval velocity, and semiconductor supply disruptions beyond current lead time assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Real Time Health Monitoring Devices Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Patient Monitoring Accessories Market