
 Artificial Intelligence (AI) in Education Market | 2026-2036
Artificial Intelligence (AI) in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Education Market Analysis
Market Context
The United States is tilting toward massive cloud infrastructure expansion to support AI education workloads. Microsoft anchors its position through Azure-based learning analytics services integrated across institutional procurement channels. Google LLC competes by extending Workspace for Education with generative AI tutoring modules deployed at district scale. IBM Corporation differentiates through Watson-powered skills credentialing platforms targeting corporate training verticals.
Technical Definition and Structural Segments
Artificial Intelligence in Education encompasses machine learning algorithms, natural language processing engines, and predictive analytics models that personalize content delivery, automate assessment, and optimize administrative workflows within formal and informal learning environments. Natural Language Processing dominates application development for automated essay scoring and conversational tutoring agents, while Machine Learning sustains the fastest expansion in early-warning systems for at-risk student identification. Cloud-Based deployment captures the majority of new institutional contracts, though Hybrid models retain stronghold status in European markets with strict data residency mandates.
Regulatory Frame and Outlook
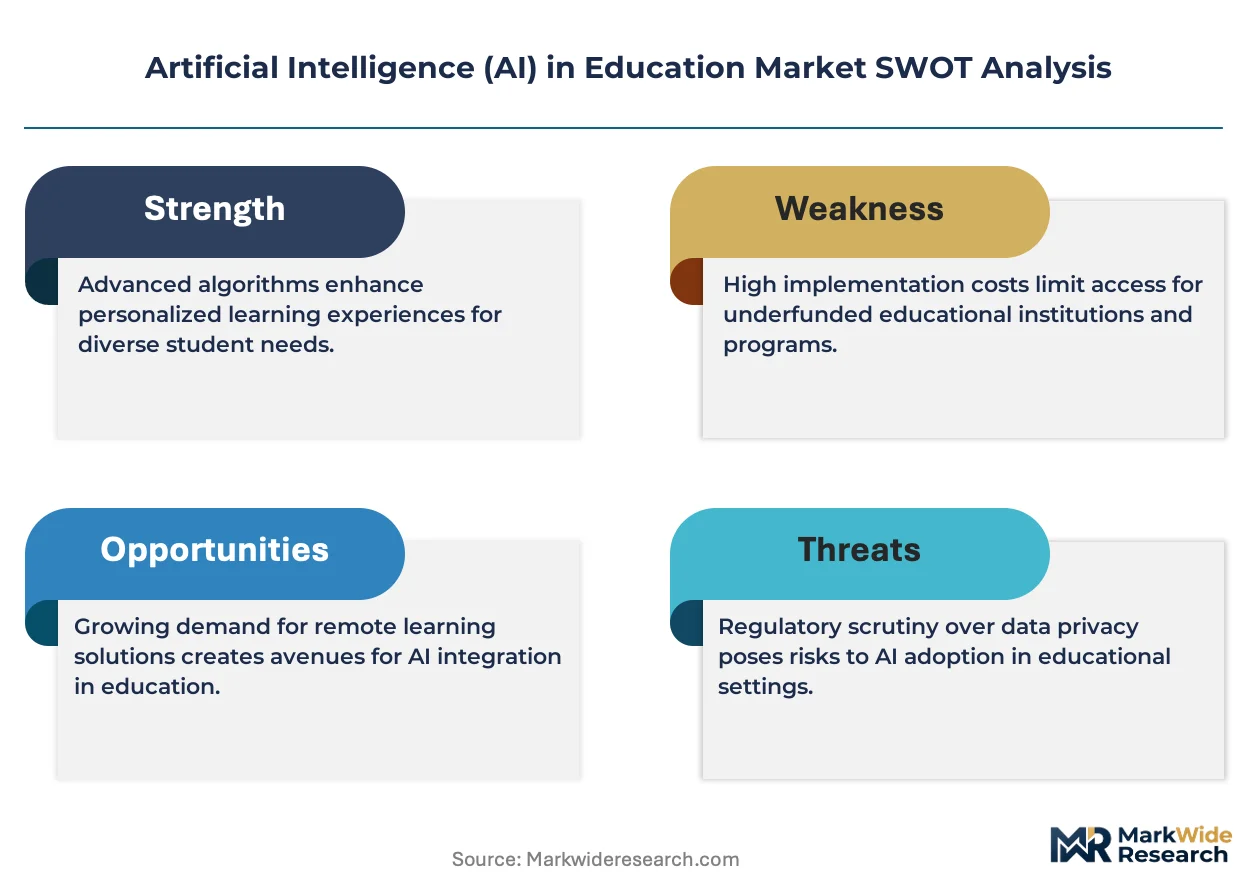
The EU AI Act imposes risk-classification requirements on AI tutoring systems, forcing vendors to demonstrate pedagogical efficacy and bias mitigation before CE-marketed deployment. In the United States, FERPA and state-level student privacy laws fragment procurement compliance, while India's BIS standards for educational software create additional certification layers for market entry. Stakeholders must monitor whether emerging algorithmic transparency mandates in multiple jurisdictions will consolidate vendor rankings around compliance-capable incumbents or open entry paths for specialized challengers.
Market Dynamics
The EU AI Act's risk-classification framework is compressing vendor certification timelines and forcing institutional procurement departments to rewrite evaluation criteria for adaptive learning platforms.
Growth Catalysts
- FERPA-aligned procurement mandates:United States K-12 districts now require AI tutoring vendors to demonstrate student data minimization protocols before contract award, accelerating demand for privacy-preserving machine learning architectures.
- Cloud infrastructure elasticity:Higher education institutions are migrating assessment automation workloads to serverless environments, reducing per-student computational costs for natural language processing engines.
- Skills-based hiring frameworks:Corporate training verticals in Germany and France are procuring AI credentialing platforms to validate micro-competencies, expanding addressable market beyond formal degree programs.
Market Restraints
- GPU supply concentration:Training infrastructure for large language models depends on Taiwan-based semiconductor fabrication, creating input cost volatility and procurement lead-time uncertainty for platform developers.
- GDPR data residency requirements:European institutions must maintain student interaction data within jurisdictional boundaries, fragmenting cloud deployment architectures and raising operational complexity.
- Pedagogical validation gaps:Limited longitudinal efficacy studies for AI tutoring systems delay institutional adoption cycles, particularly for high-stakes assessment applications.
Strategic Opportunities
- Vocational training integration:India's BIS certification pathway for educational software creates entry conditions for AI-powered apprenticeship matching platforms serving manufacturing and healthcare verticals.
- Multimodal assessment convergence:Synthesis of computer vision and speech recognition enables real-time proctoring and presentation skill evaluation, opening procurement channels in professional certification markets.
- State-level privacy legislation:California's Student Online Personal Information Protection Act and similar statutes in Illinois and Texas are mandating algorithmic transparency, creating compliance-service revenue streams for specialized vendors.
Industry Challenges
- Learning science expertise scarcity:Platform engineering teams lack sufficient instructional design capacity to align adaptive algorithms with evidence-based pedagogical frameworks, degrading product efficacy.
- Interoperability fragmentation:Legacy student information systems in United States school districts resist API integration with modern AI analytics layers, extending implementation timelines and inflating professional services costs.
Report Scope
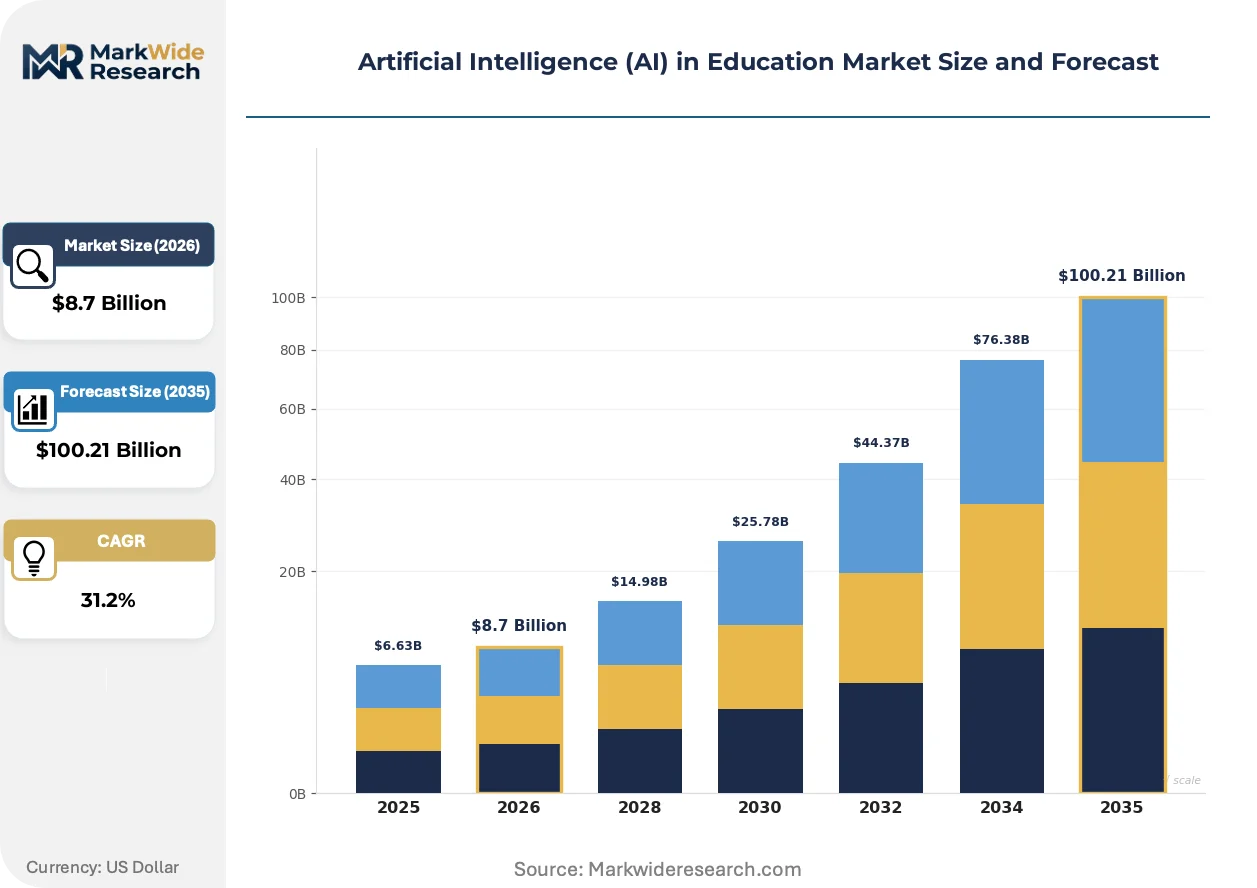
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Education Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $100.21 Billion |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Learning Management Systems, Intelligent Tutoring Systems, Virtual Learning Environments, Administrative Tools End User: Students, Educators, Institutions, Corporations Technology: Natural Language Processing, Machine Learning, Predictive Analytics, Computer Vision Deployment Model: Cloud-Based, On-Premise, Hybrid, Others |
| Companies Covered | Google LLC, IBM Corporation, Microsoft, Pearson, Amazon Web Services, Inc., DreamBox Learning, Inc., BridgeU, Carnegie Learning, Inc., Anthology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Education Market Emerging Trajectories
Generative AI architectures are compressing content production cycles while regulatory pressure is forcing transparency into algorithmic decision-making. Procurement patterns are simultaneously fragmenting across institutional tiers.
Immersive simulation environments powered by neural rendering are virtualizing laboratory and clinical training experiences for healthcare and STEM disciplines. Community colleges and vocational institutes in the United States are piloting these systems at scale to offset physical infrastructure constraints. This virtualization is compressing capital expenditure requirements for hands-on program expansion while raising questions about tactile skill transfer validity.
The EU AI Act's high-risk system classification for educational scoring applications is mandating conformity assessment procedures before CE-marketed deployment. Vendors must now submit technical documentation demonstrating bias mitigation and pedagogical efficacy to notified bodies. European higher education procurement offices are prioritizing pre-certified platforms, consolidating vendor selection around compliance-capable incumbents.
Subscription-based procurement of AI tutoring modules is displacing perpetual license arrangements in United States school districts. Chief technology officers are negotiating usage-based contracts tied to active student enrollments rather than upfront site licenses. This shift is most visible in Texas and Florida, where state funding volatility makes operational expenditure commitments preferable to capital outlays.
Artificial Intelligence (AI) in Education Market Segmentation
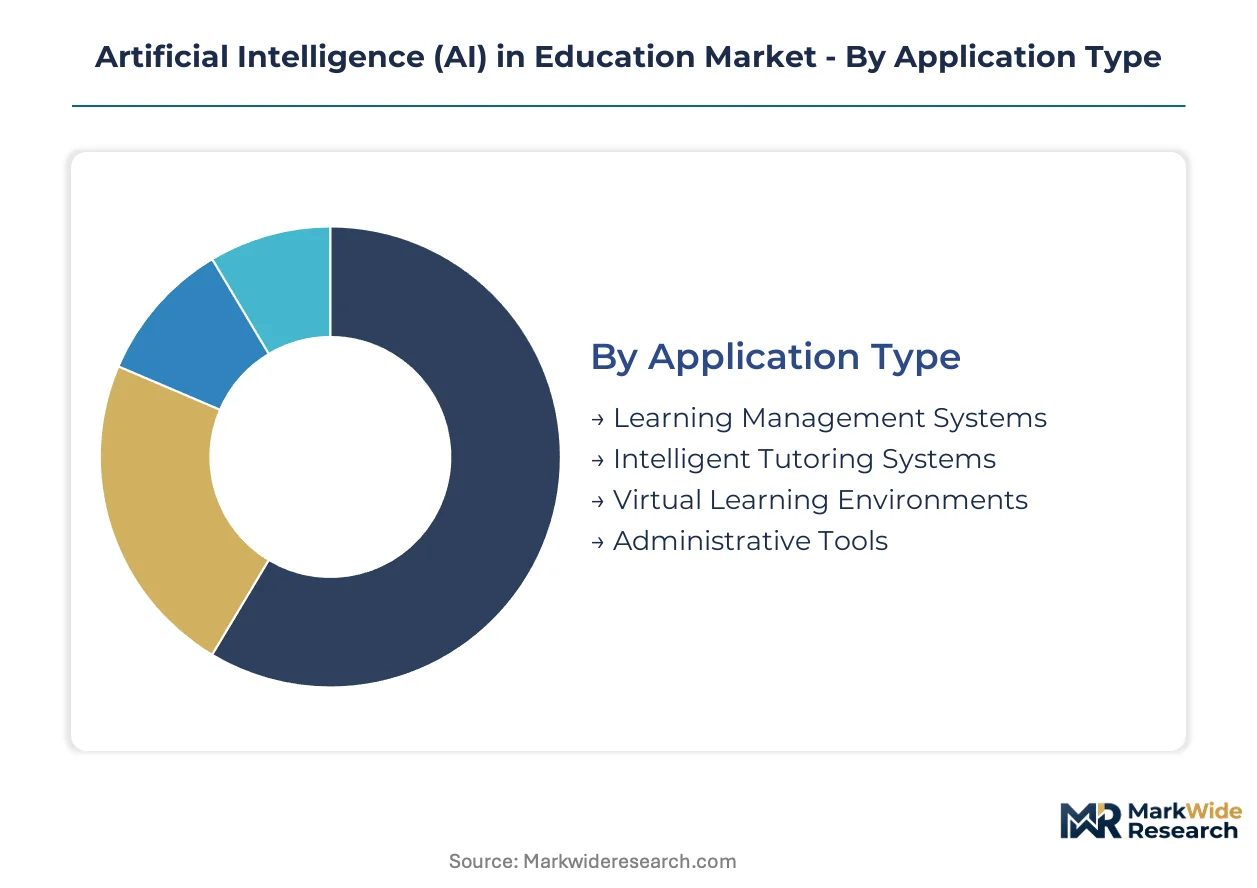
AI education platforms require continuous algorithm refinement and pedagogical calibration after deployment. Segmentation reveals which configurations demand intensive professional services versus self-sustaining architectures.
Application Type:
Post-deployment service intensity varies sharply across educational use cases, with adaptive systems requiring ongoing model retraining.
- Learning Management Systems:These platforms integrate content sequencing, progress tracking, and analytics dashboards into unified institutional workflows. United States higher education procurement channels concentrate demand here, driven by FERPA-aligned data governance requirements that mandate vendor-managed security updates.
- Intelligent Tutoring Systems:Conversational agents delivering personalized feedback through natural language interfaces demand substantial after-sales instructional design support. K-12 districts in Texas and Florida are expanding procurement of these systems, constrained by limited longitudinal efficacy validation for high-stakes applications.
- Virtual Learning Environments:Immersive simulation platforms for laboratory and clinical training.
- Administrative Tools:Enrollment forecasting and resource optimization algorithms for institutional operations.
By volume, Learning Management Systems leads. By growth pace, Intelligent Tutoring Systems is climbing the fastest.
End User:
Customer archetypes determine pricing architecture and contract structure across the procurement landscape.
- Students:Direct-to-learner subscription models for supplemental tutoring and skill credentialing.
- Educators:Classroom-facing tools for automated assessment and content generation.
- Institutions:Enterprise licensing for integrated campus-wide deployment with single sign-on infrastructure.
- Corporations:Watson-powered skills platforms and micro-credentialing systems for workforce development. German and French manufacturing verticals are driving procurement here, motivated by skills-based hiring frameworks that validate competency attainment outside formal degree pathways.
Institutions command the largest contract values. Corporations are gaining share fastest as workforce development budgets expand.
Technology:
Computational requirements and infrastructure dependencies differentiate technical approaches.
- Natural Language Processing:Engines for automated essay scoring and conversational tutoring dominate current application development. European procurement offices are prioritizing these systems under EU AI Act high-risk classification mandates that require demonstrated bias mitigation before CE-marketed deployment.
- Machine Learning:Predictive models for at-risk student identification and adaptive content recommendation. United States community colleges are deploying these systems most aggressively, compelled by retention metrics tied to state funding formulas.
- Predictive Analytics:Early-warning systems and enrollment forecasting for institutional planning.
- Computer Vision:Proctoring and presentation skill evaluation through multimodal assessment.
Natural Language Processing captures the most development investment. Machine Learning is expanding most quickly in operational deployment.
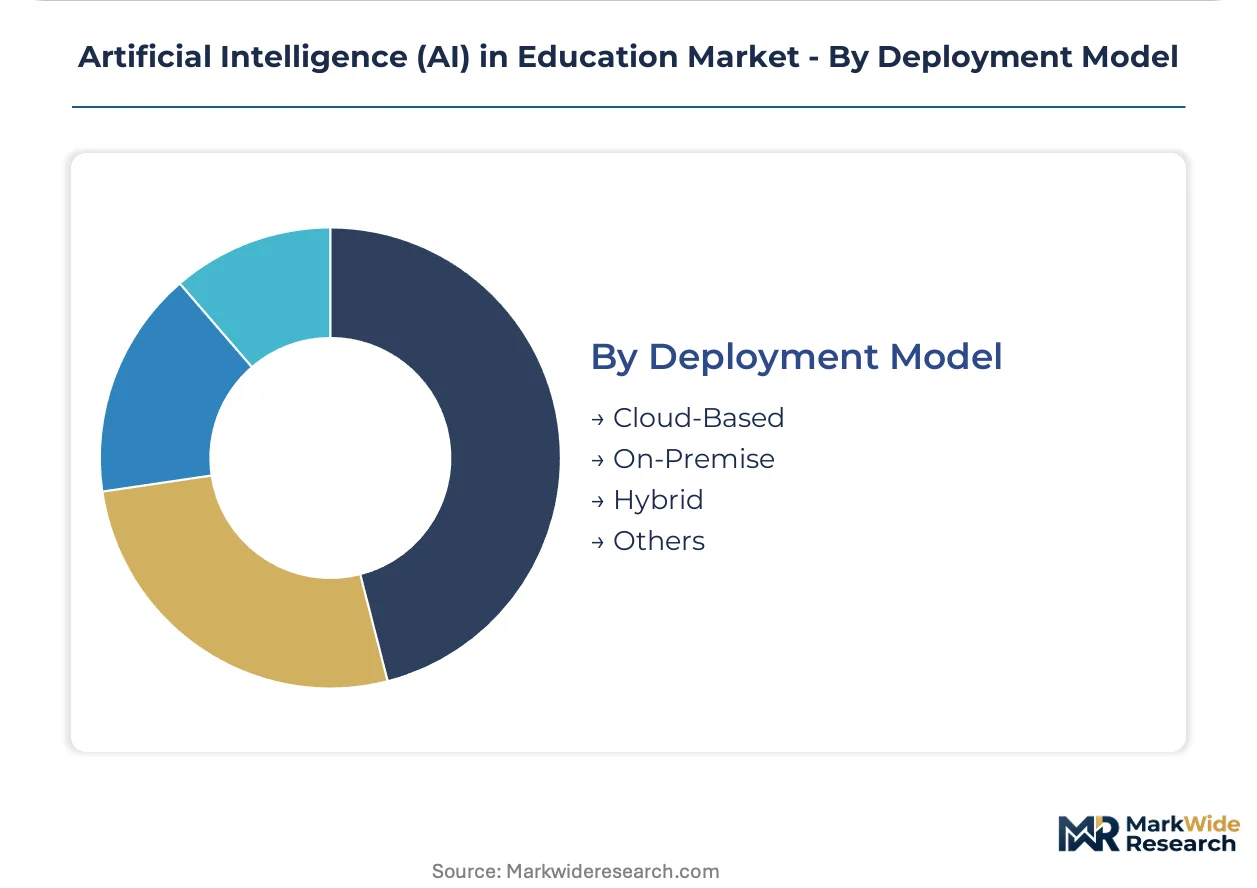
Deployment Model:
Data residency requirements and infrastructure control preferences shape architectural decisions.
- Cloud-Based:Serverless environments for elastic computational scaling of NLP workloads. Majority of new United States institutional contracts favor this model, supported by Azure and Google Cloud education-specific service tiers.
- On-Premise:Local infrastructure for jurisdictions with strict data sovereignty requirements.
- Hybrid:Split architectures retaining sensitive student data on-site while leveraging cloud analytics. European markets with GDPR residency mandates maintain stronghold preference here, fragmenting vendor deployment strategies.
- Others:Edge computing and federated learning configurations for distributed processing.
Cloud-Based deployment leads by contract volume. Hybrid models are gaining traction fastest where regulatory complexity intersects with institutional risk tolerance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major education markets. United States institutions prioritize cloud-native adaptive platforms with FERPA-aligned data governance, while European procurement offices filter vendor selection through CE-marking conformity assessments under the EU AI Act. Asian markets concentrate deployment in skills credentialing and vocational training verticals.
United States
K-12 districts in Texas and Florida are expanding intelligent tutoring procurement through usage-based subscription contracts. FERPA and state-level student privacy statutes fragment compliance requirements across jurisdictions. The Austin-San Antonio corridor hosts concentrated edtech development activity for NLP-powered assessment engines.
Germany
Manufacturing and automotive sectors are procuring AI credentialing platforms to validate micro-competencies outside formal degree pathways. The EU AI Act mandates conformity assessment for high-risk educational scoring applications before market deployment. Bavaria's technical universities are piloting hybrid cloud architectures to satisfy GDPR data residency requirements.
India
Vocational training institutes and community colleges are driving demand for apprenticeship-matching platforms in manufacturing and healthcare verticals. BIS certification standards for educational software create structured entry pathways for platform vendors. Karnataka's Bangalore cluster anchors development activity for machine learning-based early-warning systems.
United Kingdom
Higher education institutions are migrating assessment automation workloads to serverless environments to reduce per-student computational costs. The Information Commissioner's Office enforces GDPR-aligned data governance for student analytics platforms. London's edtech corridor concentrates vendor development for multimodal proctoring and presentation skill evaluation.
Japan
Corporate training budgets are expanding procurement of Watson-powered skills platforms for workforce reskilling initiatives. METI guidelines shape algorithmic transparency expectations for educational AI deployments. The Tokyo-Osaka corridor hosts concentrated development of immersive simulation environments for healthcare and STEM laboratory training.
Artificial Intelligence (AI) in Education Market Vendor Landscape
Capability concentration sits with specialized instructional design firms; scale advantage sits with cloud infrastructure providers. The market structure tiers into three distinct archetypes: hyperscale platform integrators, adaptive learning specialists, and corporate skills credentialing vendors. Competitive positioning depends on compliance certification speed and pedagogical validation depth. M&A activity targets instructional design capabilities, while strategic partnerships concentrate on cloud infrastructure co-development.
Among hyperscale platform providers, Google LLC, Microsoft, and IBM Corporation occupy positions spanning cloud infrastructure, productivity suites, and enterprise AI services. These entities exemplify the compliance-capable incumbent tier that European procurement offices increasingly favor under CE-marking mandates. Adaptive learning specialists such as DreamBox Learning, Inc. and Carnegie Learning, Inc. represent the pedagogical depth archetype, anchoring product development around evidence-based instructional frameworks. Corporate training verticals in Germany and France are drawing competitive attention from skills credentialing platforms, with Pearson and Amazon Web Services, Inc. sitting within this segment.
| Leading Market Players |
|---|
| Google LLC |
| IBM Corporation |
| Microsoft |
| Pearson |
| Amazon Web Services, Inc. |
| DreamBox Learning, Inc. |
| BridgeU |
| Carnegie Learning, Inc. |
| Anthology Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwan's semiconductor fabrication clusters anchor GPU supply for AI education platform training workloads, concentrating upstream pricing power among a handful of foundry operators. This geographic concentration cascades into downstream cost structures for adaptive learning vendors, compressing margins for mid-tier platform developers while hyperscale incumbents absorb volatility through volume commitments.
Pricing Analysis
United States K-12 districts and European higher education institutions exhibit a 40-60% price spread for comparable intelligent tutoring deployments, driven by FERPA-aligned data governance premiums versus EU AI Act conformity assessment costs. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade platforms with full instructional design support from self-service modules. Cost compression in the standard tier is intensifying because GPU leasing rates fluctuate with foundry capacity allocation. Community colleges and vocational institutes demonstrate highest price sensitivity, while corporate training verticals in Germany and France tolerate premium positioning for skills credentialing validation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for educational hardware-dependent deployments like immersive simulation labs. GPU and specialized AI accelerator supply concentrates in Taiwan, South Korea, and the United States, while cloud infrastructure draws from hyperscaler data center networks across Virginia, Frankfurt, and Singapore. Raw material dependencies span advanced lithography equipment, high-bandwidth memory modules, and rare earth elements for sensor arrays. Single-source vulnerability in Taiwan-based foundry capacity threatens procurement lead-time certainty for platform developers training large language models. Distribution runs through direct enterprise sales teams for institutional contracts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI education market sits at a platform-economics inflection where interoperability standards and API consolidation are reconfiguring competitive moats. Vendors that control integration layers between legacy student information systems and modern analytics engines are capturing disproportionate value from content providers.
For Market Incumbents: Harden defensive positioning by acquiring instructional design capabilities to align adaptive algorithms with evidence-based pedagogical frameworks, neutralizing the learning science expertise scarcity that degrades product efficacy. Accelerate certification investment for EU AI Act high-risk system classification before notified body backlogs extend conformity assessment timelines. Prioritize backward integration into cloud infrastructure through strategic partnerships with hyperscalers to secure GPU allocation priority during supply crunches.
For New Entrants and Emerging Players: India's BIS-certified vocational training institutes represent the most penetrable entry point for apprenticeship-matching platforms serving manufacturing and healthcare verticals. Mid-market community colleges in Texas and Florida offer white-space opportunity through usage-based subscription models that displace perpetual license incumbents. Go-to-market execution should anchor on state-level privacy legislation compliance services, positioning algorithmic transparency tooling as a procurement differentiator against legacy vendors.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory fragmentation across FERPA, GDPR, and emerging algorithmic transparency mandates is consolidating vendor selection around certification-capable platforms. Acquisition targets should prioritize adaptive learning specialists with demonstrated pedagogical validation depth and established notified body relationships. The signal to watch is procurement office prioritization of pre-certified platforms under EU AI Act implementation, which would accelerate incumbent consolidation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API consolidation with legacy student information systems reduces implementation friction and professional services overhead for K-12 districts. |
| Acquisition of Specialist Firm | Pedagogical validation capabilities from instructional design firms accelerate EU AI Act conformity assessment timelines for scoring applications. |
| Strategic Partnership | Cloud infrastructure co-development with hyperscalers secures GPU allocation priority and serverless cost optimization for NLP workloads. |
| Geographic Expansion | BIS certification pathway entry into Indian vocational training markets opens manufacturing and healthcare apprenticeship matching revenue streams. |
| Product Launch | Multimodal assessment convergence of computer vision and speech recognition penetrates professional certification proctoring markets. |
Methodological Framework
A spread of perspectives from chief technology officers at K-12 districts, higher education procurement officers, platform engineering leads at adaptive learning vendors, and regulatory affairs specialists at cloud infrastructure providers converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings of hyperscale platform providers, EU AI Act implementation guidance documents, and state-level student privacy statute databases. Bottom-up triangulation across deployment model segmentation and top-down cross-check against cloud education-specific service tier disclosures anchored volume estimates.
Demand-supply-balance framing across the analysis window modeled enrollment-driven computational workload growth against foundry capacity expansion trajectories. Segmentation dimensions included application type, end user archetype, technology stack, and deployment model complexity. CAGRs derived from elasticity modeling of institutional procurement budgets and corporate training vertical expansion rates. Industry-specific inputs incorporated FERPA compliance cost inflation and EU AI Act conformity assessment timeline assumptions.
Practitioners should monitor GPU supply concentration dynamics, notified body capacity constraints for CE marking, and state-level privacy legislation proliferation for early signals of forecast deviation. Forecasts reflect documented assumptions about pedagogical validation acceptance timelines and interoperability standard adoption rates. Material shifts in Taiwan-based foundry allocation priorities or EU AI Act enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
SETM Education Market