
 K-12 Testing and Assessment Market | 2026-2036
K-12 Testing and Assessment Market Size, Share, and Industry Trends Forecast 2026-2036
K-12 Testing and Assessment Market Intelligence
Public school districts is rebalancing toward hybrid and remote delivery modes as permanent infrastructure investments replace emergency pandemic tools. Pearson Education leverages its institutional relationships and certification heritage to sustain dominance in high-stakes summative testing. Renaissance Learning anchors its competitive position in formative assessment through deep integration with classroom instructional workflows. Cambium Assessment competes aggressively for state-level contracts by specializing in large-scale online test administration platforms.
K-12 Testing and Assessment encompasses standardized measurement instruments, digital delivery platforms, and analytics engines designed to evaluate student learning progression against curriculum benchmarks and regulatory accountability frameworks. These systems integrate psychometric algorithms, item banks, and interoperability standards such as IMS Global's Question and Test Interoperability specification to enable secure, scalable administration across diverse device environments and network conditions. Formative assessment solutions capture expanding district budgets as educators prioritize real-time instructional feedback over terminal accountability metrics. AI-Driven technology segments attract disproportionate R&D investment as adaptive engines promise personalized difficulty calibration and automated essay scoring. Cloud-Based deployment dominates procurement specifications for state-level contracts due to elastic capacity requirements during peak spring testing windows.
The U.S. Department of Education enforces ESSA-mandated statewide accountability assessments while the FDA's software-as-medical-device framework increasingly governs cognitive diagnostic tools with clinical claims. State education agencies in California, Texas, and New York layer additional procurement compliance requirements atop federal baselines, fragmenting vendor certification pathways. Stakeholders must monitor evolving interoperability mandates and accessibility standards as procurement criteria shift from functional checklists toward ecosystem integration demands.
Market Dynamics
Adaptive psychometric engines are compressing traditional assessment cycles from terminal summative events into continuous embedded measurement, forcing vendors to rearchitect platforms for real-time data streaming rather than batch processing.
Growth Catalysts
- ESSA Accountability Mandates:The U.S. Department of Education's Every Student Succeeds Act requires annual statewide assessments, sustaining baseline procurement volumes for large-scale digital platforms across all 50 states and territories.
- AI-Driven Personalization:Machine learning algorithms now calibrate item difficulty in real-time, enabling individualized testing pathways that reduce student frustration while maintaining measurement precision.
- India's National Education Policy:The NEP 2020 framework mandates formative assessment integration into classroom practice, opening procurement channels for digital portfolio and competency-tracking tools in 1.5 million schools.
Market Restraints
- Cloud Infrastructure Concentration:Peak spring testing windows create elastic compute demands that concentrate vendor dependency on hyperscale providers, amplifying cost volatility and single-point-of-failure risk.
- Interoperability Friction:Legacy student information systems in U.S. districts often lack IMS Global OneRoster compliance, forcing expensive middleware development for data exchange between assessment and instructional platforms.
- Psychometric Talent Scarcity:The specialized workforce combining educational measurement expertise with machine learning engineering remains concentrated in a handful of university research centers and established testing organizations.
Strategic Opportunities
- United Kingdom Formative Expansion:England's Department for Education is piloting reception baseline assessments and multiplication tables checks, creating procurement entry points for classroom-embedded diagnostic tools.
- Neurodiverse Accommodation Tech:Text-to-speech engines, extended time algorithms, and sensory-friendly interfaces represent underdeveloped product categories where specialized vendors can command premium positioning.
- Parental Dashboard Convergence:Districts are consolidating family communication portals with assessment reporting, opening channel partnerships between testing platforms and student information system providers.
Industry Challenges
- Accessibility Certification Timelines:WCAG 2.1 AA compliance and Section 508 validation for new item types extend product development cycles by 8-14 months, compressing competitive windows for innovation.
- Legacy LMS Integration Complexity:Deep embedding of assessment workflows into Google Classroom, Canvas, and Schoology requires maintaining multiple API integrations that fragment engineering resources and create version-control fragility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | K-12 Testing and Assessment Market |
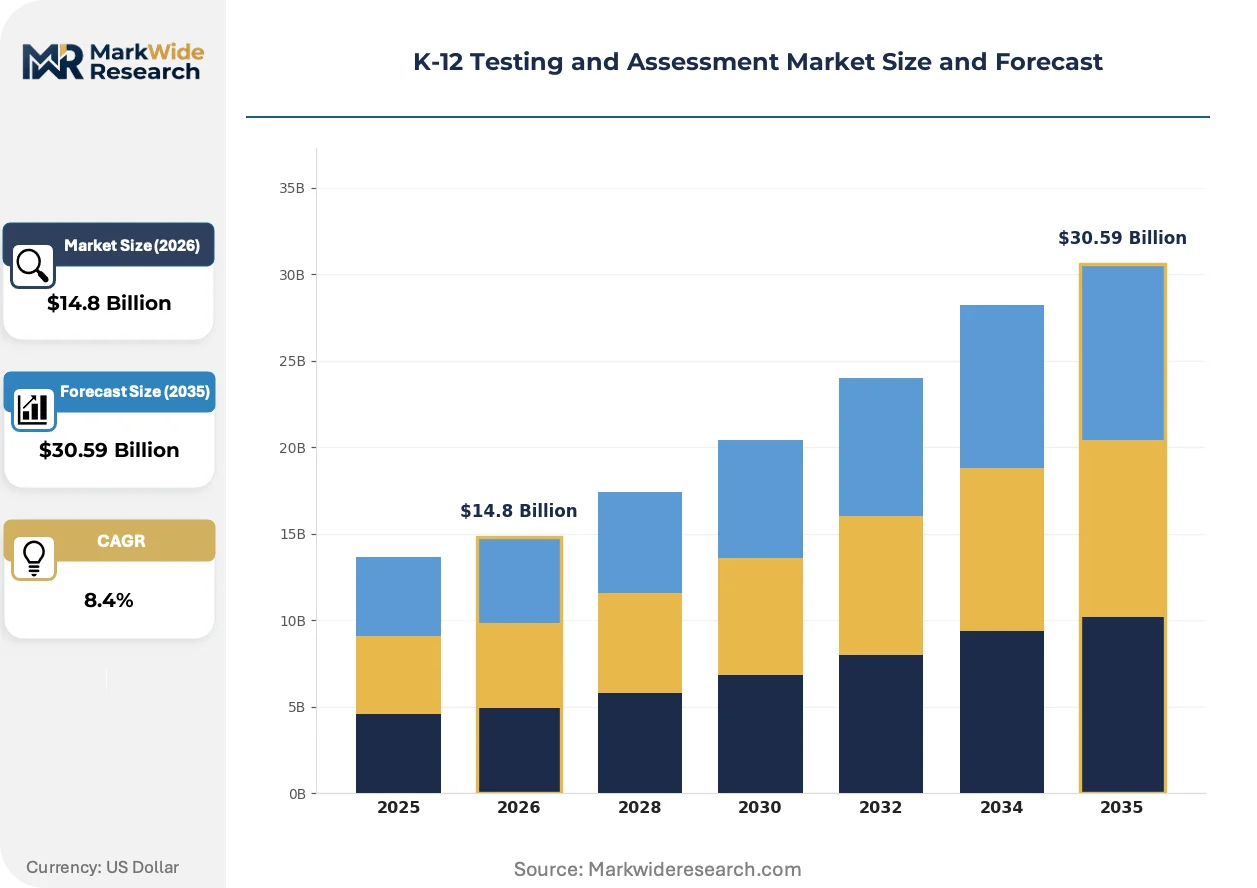
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
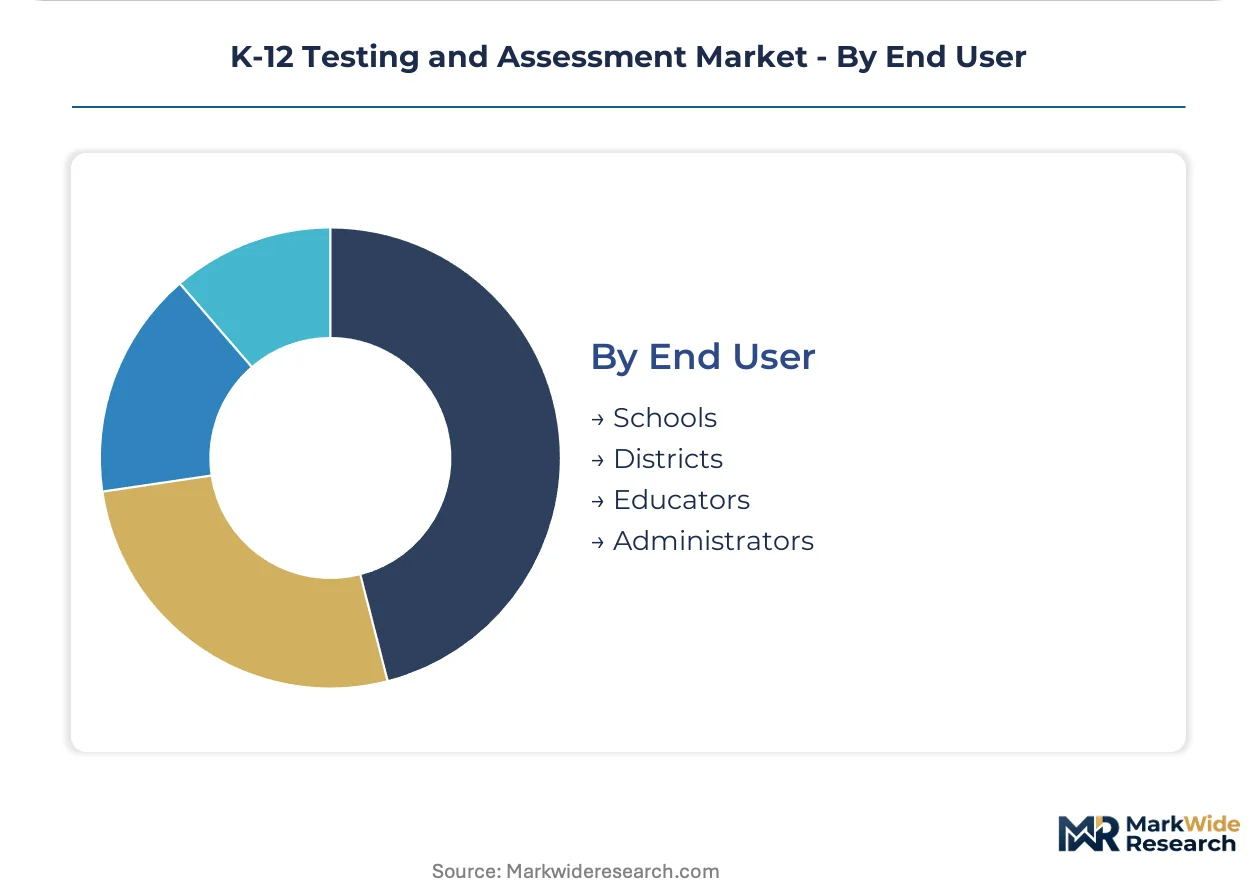
| Segmentation | Assessment Type: Formative, Summative, Diagnostic, Benchmark Delivery Mode: Online, Offline, Hybrid, Remote Technology: AI-Driven, Cloud-Based, Interactive, Mobile End User: Schools, Districts, Educators, Administrators |
| Companies Covered | D2L Corporation, Renaissance Learning, Pearson Education, MeritTrac Services, Cambium Assessment, Educational Testing Service (ETS), Instructure, Inc., CogniFit, Anthology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
K-12 Testing and Assessment Market Strategic Shifts & Innovations
Real-time data architectures are displacing batch-processing assessment models, compressing feedback loops from weeks to minutes and enabling instructional intervention at the point of misconception rather than after unit completion.
Computer-adaptive testing engines are consolidating market share among vendors with proprietary item response theory implementations. State education agencies in Texas and California now require adaptive algorithms for their accountability assessments, favoring platforms with decade-long psychometric investment over newer cloud-native entrants. The technology is consolidating procurement around vendors who control both the measurement science and the delivery infrastructure.
The U.S. Department of Education's enforcement of ESSA's 1% cap on alternate assessments for students with significant cognitive disabilities is reshaping product development priorities. Vendors must now build dual-track platforms serving both general and alternate assessment populations from unified item banks. Special education directors in New York and Florida districts are demanding single-sign-on solutions that eliminate redundant testing for students with IEPs.
District technology directors are unbundling assessment procurement from comprehensive curriculum contracts, creating standalone RFPs for interoperable platforms. This fragmentation favors specialized assessment vendors over integrated publishers in medium-sized districts with 10,000-50,000 students. Procurement patterns in Illinois and Ohio show explicit scoring criteria weighting interoperability certifications above content coverage breadth.
K-12 Testing and Assessment Market Segmentation

Segmentation in K-12 testing reveals how procurement priorities diverge across institutional budgets, technical infrastructure, and regulatory compliance requirements. Understanding these divides exposes where platform investments concentrate and which delivery models face obsolescence pressure.
Assessment Type:
Capital intensity varies sharply across assessment categories, with summative platforms requiring the heaviest upfront investment in psychometric validation and security infrastructure.
- Formative:Embedded classroom tools capture real-time learning data through low-stakes quizzes and exit tickets. Districts in Texas and California are expanding procurement of these solutions as ESSA accountability shifts toward growth metrics rather than terminal proficiency thresholds.
- Summative:High-stakes statewide assessments demand hardened delivery infrastructure, biometric proctoring, and decade-long item bank development. State education agencies concentrate procurement with vendors possessing existing federal peer review certifications, creating substantial barriers to new entrants.
- Diagnostic:Screening instruments identify learning gaps at semester start.
- Benchmark:Interim assessments track progress toward summative targets.
Most installed capacity flows through Summative. Expansion is steepest in Formative.
Delivery Mode:
Procurement patterns reveal which delivery models districts treat as permanent infrastructure versus pandemic-era temporary measures.
- Online:Browser-based and native app platforms dominate state-level contracts, with elastic cloud capacity handling spring testing surges. Illinois and Ohio now mandate online-first administration for all accountability assessments, with paper accommodations requiring explicit waiver documentation.
- Hybrid:Blended models combine scheduled in-person sessions with asynchronous remote components. Districts between 10,000 and 50,000 students favor this flexibility to accommodate transportation constraints and facility shortages.
- Offline:Local server deployments persist in rural districts with unreliable connectivity.
- Remote:Home-based proctored administration contracts sharply post-pandemic.
Procurement volume concentrates in Online. Hybrid is gaining share fastest among medium-sized districts.
Technology:
Engineering resource allocation splits between adaptive algorithms and infrastructure resilience.
- AI-Driven:Machine learning engines calibrate item difficulty in real-time and automate essay scoring. State agencies in Texas now require adaptive algorithms for accountability assessments, favoring vendors with proprietary item response theory implementations over newer cloud-native platforms.
- Cloud-Based:Elastic compute architectures handle peak spring testing windows without permanent overprovisioning. Procurement specifications increasingly mandate SOC 2 Type II certification and state-specific data residency requirements.
- Interactive:Multimedia item types with simulations and drag-drop interfaces.
- Mobile:Smartphone-optimized delivery for bring-your-own-device policies.
R&D investment concentrates in AI-Driven. Cloud-Based carries the largest contract value.
End User:
Budget authority and technical sophistication diverge across institutional purchaser types.
- Districts:Central offices manage statewide compliance testing and negotiate enterprise platform licenses. Large urban districts in New York and Florida are consolidating previously fragmented school-level contracts to extract volume pricing and standardize data interoperability.
- Schools:Individual sites purchase supplementary formative tools from discretionary budgets. Principals prioritize rapid implementation timelines and minimal professional development requirements over feature depth.
- Educators:Classroom teachers influence adoption through grassroots pilot programs.
- Administrators:Superintendents and assessment directors control high-stakes procurement decisions.
Contract value concentrates at District level. School-level procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors procurement volume for K-12 testing and assessment platforms, with state education agencies mandating adaptive algorithms for accountability assessments and driving vendor consolidation around psychometrically validated delivery infrastructure.
United States
The U.S. Department of Education enforces ESSA-mandated annual statewide assessments across all 50 states, sustaining baseline procurement volumes for large-scale digital platforms. California and New York layer additional accessibility compliance requirements atop federal baselines, fragmenting vendor certification pathways. Districts in Illinois and Ohio now mandate online-first administration for all accountability assessments.
United Kingdom
England's Department for Education pilots reception baseline assessments and multiplication tables checks, creating procurement entry points for classroom-embedded diagnostic tools. The UK regulatory framework emphasizes formative assessment integration, with local authorities in London and the Midlands expanding digital portfolio procurement. Scotland and Wales maintain distinct curriculum alignment requirements that complicate cross-border platform standardization.
India
The National Education Policy 2020 mandates formative assessment integration into classroom practice across 1.5 million schools, opening procurement channels for competency-tracking tools. State education boards in Maharashtra and Karnataka lead implementation of digital portfolio systems. The central government's DIKSHA platform establishes interoperability standards that influence vendor selection criteria.
Canada
Provincial education ministries in Ontario and British Columbia consolidate previously fragmented district-level contracts to extract volume pricing for assessment platforms. The Pan-Canadian Assessment Program establishes psychometric baselines that influence vendor qualification requirements. Urban districts in Toronto and Vancouver prioritize cloud-based deployment models with SOC 2 Type II certification.
Australia
The Australian Curriculum, Assessment and Reporting Authority oversees national testing protocols that shape state-level procurement specifications. New South Wales and Victoria education departments expand adaptive assessment pilots for literacy and numeracy screening. The national NAPLAN online transition concentrates vendor selection with platforms demonstrating proven elastic capacity management.
K-12 Testing and Assessment Market Key Industry Players
State-level contract consolidation dominates the current landscape as education agencies concentrate procurement with vendors possessing decade-long psychometric investment and federal peer review certifications. The vendor base stratifies into three tiers: established testing organizations with proprietary item banks, cloud-native platforms competing on interoperability, and specialized formative assessment providers. Strategic archetypes include psychometric-heavy incumbents defending summative positions, agile disruptors capturing formative budgets, and platform integrators bridging assessment-instructional workflows. M&A activity and interoperability certification races constitute the dominant competitive moves.
Among North American-based assessment specialists, Pearson Education, Renaissance Learning, and Cambium Assessment occupy distinct positioning archetypes. Pearson exemplifies the psychometric-incumbent model with institutional relationships and certification heritage sustaining summative dominance. Renaissance Learning anchors the formative-specialist tier through deep classroom workflow integration. Cambium Assessment represents the state-contract competitor archetype, specializing in large-scale online test administration platforms. Educational Testing Service and D2L Corporation sit within adjacent competitive spaces, with ETS occupying research-backed measurement positioning and D2L representing learning platform convergence toward embedded assessment.
| Leading Market Players |
|---|
| D2L Corporation |
| Renaissance Learning |
| Pearson Education |
| MeritTrac Services |
| Cambium Assessment |
| Educational Testing Service (ETS) |
| Instructure, Inc. |
| CogniFit |
| Anthology, Inc. |
| Others |
Cost & Logistics Intelligence
Captive cloud infrastructure investments by established testing organizations anchor both supply security and pricing power in state-level procurement. Pearson Education and Cambium Assessment maintain proprietary delivery networks that insulate contract margins from hyperscale provider volatility while locking out newer entrants lacking comparable capital reserves.
Pricing Analysis
Input-cost pass-through from cloud compute and psychometric talent scarcity shapes contract economics across vendor tiers. Three-tier pricing structure across premium adaptive platforms, standard online delivery, and economy paper-based accommodations dominates state RFPs. Price differentiation hinges on federal peer review certification status and adaptive algorithm sophistication. Pricing pressure stems from district unbundling of assessment from curriculum contracts. Small and rural districts exhibit highest price sensitivity; large urban districts with consolidated purchasing authority command volume discounts.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers concentrated in the United States, as peak spring testing windows create elastic compute demands that few alternative vendors can satisfy. Psychometric item banks draw from specialized workforce pools anchored in university research centers across the United States, the United Kingdom, and Australia. Supply chain risk centers on regulatory restriction: state data residency mandates fragment cloud deployment architectures. Distribution runs through state education agency procurement offices with multi-year contract cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The K-12 Testing and Assessment Market functions as a stable compounder, with ESSA-mandated annual assessments providing baseline demand visibility regardless of economic cycles.
For Market Incumbents: Lock in state contract renewals by accelerating WCAG 2.1 AA certification timelines ahead of accessibility mandate expansions in California and New York. Deepen psychometric talent pipelines through university research partnerships to counter workforce scarcity. Vertical integration into formative assessment workflows through acquisition of classroom-embedded tool providers defends against unbundling pressure from medium-sized districts. For New Entrants and Emerging Players: Direct-to-district SaaS channels bypass state procurement complexity that favors established vendors with federal peer review certifications. India's 1.5 million schools under NEP 2020 formative assessment mandates represent the most penetrable geography. Parental dashboard convergence with student information systems offers a partnership-based go-to-market angle without requiring state-level certification. For Investors and Strategic Acquirers: Consolidation pressure builds where formative assessment specialists lack adaptive algorithm capabilities to compete for state accountability contracts. Long-term viability favors vendors with dual-track platforms serving both general and alternate assessment populations from unified item banks. Watch for ESSA reauthorization debates as the signal indicating potential shifts in federal procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Algorithm Development | Texas and California now mandate adaptive engines for accountability assessments, favoring decade-long psychometric investment. |
| Accessibility Certification Acceleration | WCAG 2.1 AA compliance timelines extend product cycles by 8-14 months, compressing competitive windows for innovation. |
| Formative Workflow Integration | District unbundling of assessment from curriculum contracts creates standalone RFPs for interoperable classroom-embedded tools. |
| Cloud Infrastructure Captive Investment | Proprietary delivery networks insulate margins from hyperscale provider volatility during peak spring testing windows. |
| Interoperability Certification Race | IMS Global OneRoster compliance increasingly weights procurement scoring above content coverage breadth in Illinois and Ohio. |
Research Approach
Coverage spans the United States, the United Kingdom, India, Canada, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with state assessment directors, district technology officers, platform product managers, and psychometric research leads with secondary validation from U.S. Department of Education ESSA guidance documents, state procurement RFP databases, IMS Global interoperability certification records, and vendor federal peer review filings. Bottom-up district-level procurement tracking and top-down state budget appropriation analysis provide triangulation.
Rate-of-change decomposition across assessment type, delivery mode, technology segment, and end-user tier anchors the analytical framework. The projection horizon captures divergence between formative expansion and summative consolidation. CAGRs derive from segment-level growth rate blending weighted by current procurement volume. Industry-specific inputs include state ESSA implementation timelines, NEP 2020 rollout pace, and cloud infrastructure capacity expansion disclosures from hyperscale providers.
Regulatory reinterpretation of ESSA accountability requirements, adaptive algorithm performance validation failures, and hyperscale cloud service disruptions are the dominant revision risks. Forecasts reflect documented assumptions about procurement cycle continuity and interoperability standard adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Global Classroom Management Software Market
Education & Training
Human Resource Professional Services Market
Education & Training
Global Online Tutoring Software Market
Education & Training
Specific Gravity Bench Apparatus Market
Education & Training
Child Care Software Market
Education & Training
Talent As a Service Market
Education & Training
Global Adaptive Learning Market
Education & Training
Asia-Pacific School Furniture Market
Education & Training
Educational Content Development Service Market
Education & Training
Global Self-Paced E-Learning Market
Education & Training
Frontline Workers Training Market
Education & Training
Technical and Vocational Education Market
Education & Training
HSE Consulting Training Services Market
Education & Training
E-Learning Solutions Market
Education & Training
Braille Book Market
Education & Training
Global AI in Education Market