
 Specific Gravity Bench Apparatus Market | 2026-2036
Specific Gravity Bench Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
Specific Gravity Bench Apparatus Market Analysis
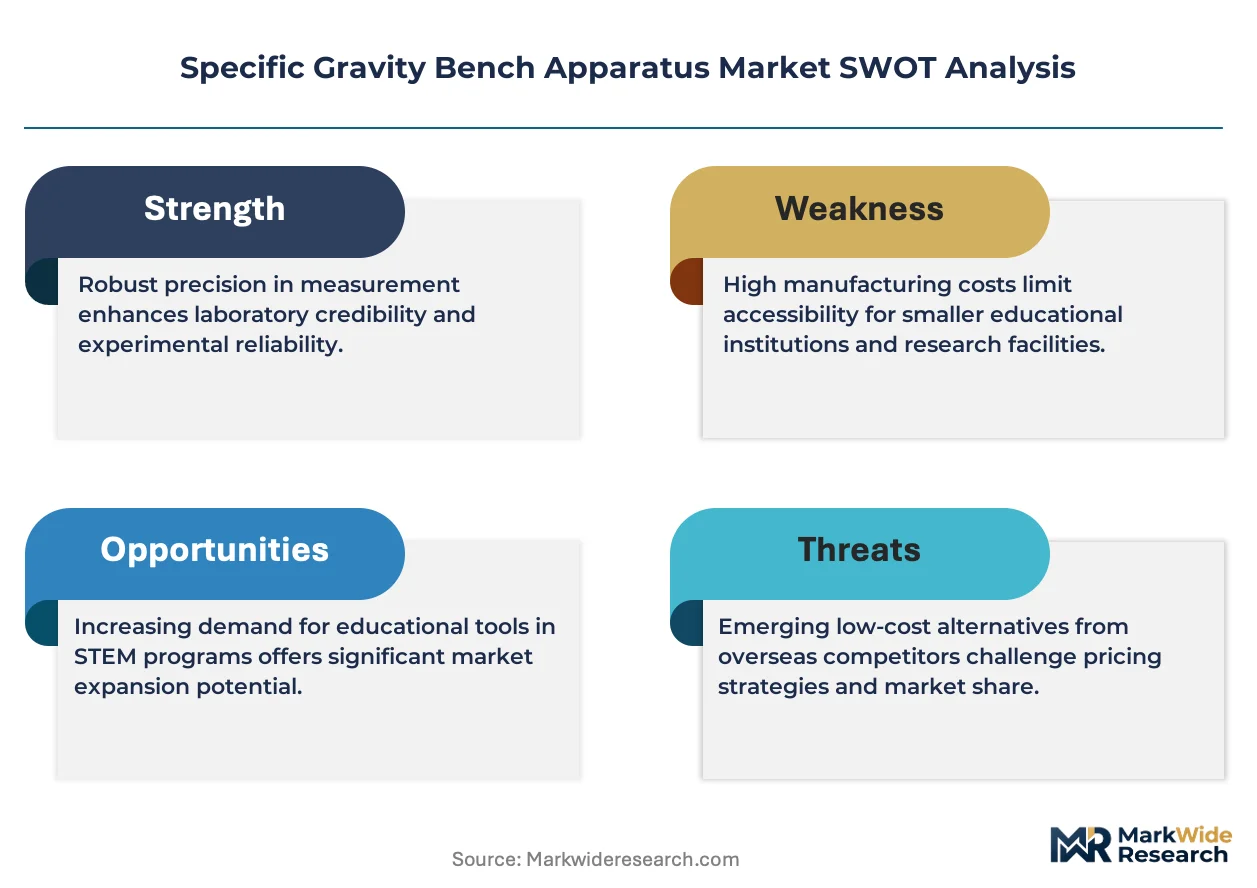
Geotechnical engineering laboratories are unwinding their historical reliance on educational institutions as the dominant buyer archetype, with quality control departments at construction materials firms now commanding larger order volumes. Humboldt Mfg. Co. anchors its position through captive manufacturing of precision water baths and calibrated weights. Controls S.p.A. competes by leveraging European metrology certifications that accelerate approval cycles for public infrastructure tenders. Gilson Company differentiates through specialized distribution networks serving state DOT laboratories across the American Midwest.
Specific gravity bench apparatus denotes precision laboratory equipment designed to measure the ratio of a material's density to that of water at standardized temperature, typically employing a rigid support frame, water tank, and suspended weighing mechanism capable of resolving to 0.1 gram for ASTM C127 and C128 compliance. The equipment serves primarily to verify aggregate and asphalt mixture specifications for transportation infrastructure durability assessment. Digital product configurations command premium positioning due to integrated data logging that eliminates transcription errors in high-throughput quality control environments. Hydrometer technology segments retain dominance in educational settings where cost sensitivity overrides precision requirements, while Archimedes principle displacement systems represent the fastest-growing category in research facilities pursuing automated specimen handling.
ASTM International shapes product design through C127 and C128 test method specifications that mandate equipment precision thresholds, while AASHTO T84 and T85 standards govern state-level highway agency procurement eligibility. The Federal Highway Administration indirectly steers demand through MAP-21 and subsequent infrastructure authorization requirements for certified materials testing. Stakeholders must monitor evolving ISO 17025 accreditation criteria for laboratory equipment calibration intervals, as these determine replacement cycles and aftermarket service revenue pools.
Market Dynamics
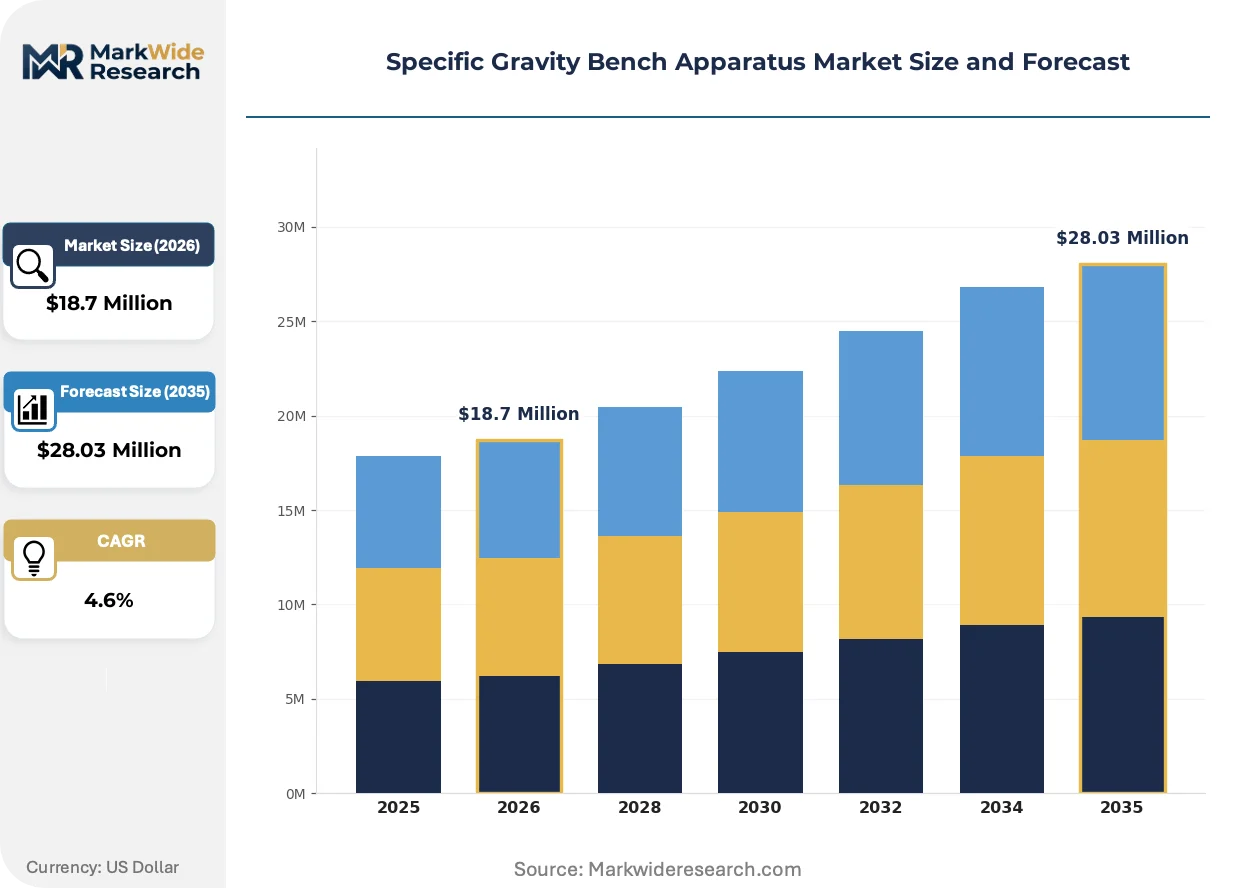
Federal infrastructure authorization requirements are compressing replacement cycles for materials testing equipment as state DOT laboratories face ISO 17025 recertification deadlines. ASTM C127 and C128 precision mandates are filtering procurement decisions toward digital configurations with integrated calibration tracking.
Growth Catalysts
- MAP-21 Authorization Extensions:Federal Highway Administration funding mechanisms require certified aggregate testing capacity at state level, forcing laboratory equipment upgrades.
- Water Displacement Automation:Archimedes principle systems with automated specimen handling are capturing share in high-throughput quality control environments.
- Geotechnical Sample Volume:Transportation infrastructure durability assessment protocols are expanding specimen testing frequency across construction materials firms.
Market Restraints
- Stainless Steel Input Volatility:Precision water bath fabrication depends on specialty alloy pricing, compressing margins for equipment manufacturers.
- Calibration Service Concentration:Third-party metrology providers cluster in industrial Midwest corridors, extending lead times for coastal laboratories.
- Hydrometer Substitution in Education:Cost-constrained university laboratories retain analog methods, capping premium digital penetration in this segment.
Strategic Opportunities
- State DOT Laboratory Modernization:American Midwest transportation agencies are consolidating testing facilities, creating volume procurement windows.
- Data Logging Integration:Elimination of transcription errors through integrated digital capture is opening premium positioning in commercial quality control departments.
- European Metrology Certification:CE marking and national accreditation schemes are accelerating approval cycles for public infrastructure tenders in EU member states.
Industry Challenges
- ISO 17025 Calibration Interval Management:Laboratory equipment recertification timelines are compressing aftermarket service revenue predictability.
- Legacy Equipment Integration:Digital bench apparatus must interface with existing laboratory information management systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specific Gravity Bench Apparatus Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Portable, Stationary Application: Laboratory, Education, Research, Quality Control End User: Educational Institutions, Research Facilities, Manufacturing, Healthcare Technology: Hydrometer, Displacement, Archimedes Principle, Others |
| Companies Covered | Cooper Research Technology, Forney LP, Durham Geo-Enterprises, Sun Labtek Equipments Manufacturing Private Limited, Humboldt Mfg. Co., Controls S.p.A., Gilson Company, Test Mark Industries, Houghton Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specific Gravity Bench Apparatus Market Emerging Trajectories
Digital measurement architectures are reconfiguring competitive advantage around data integrity rather than mechanical precision alone. Equipment vendors are repositioning around software-enabled calibration management and automated specimen handling.
Archimedes principle displacement systems with programmable specimen carriers are supplanting manual water bath configurations in commercial laboratories. State DOT quality control departments are adopting these units to meet throughput targets under federal funding timelines. The shift is compressing demand for conventional suspended weighing mechanisms in high-volume testing environments.
ASTM International is tightening C127 and C128 precision thresholds through supplementary requirements for temperature control documentation. Equipment manufacturers must now integrate continuous monitoring sensors to maintain compliance eligibility. Commercial construction materials laboratories are responding by specifying digital units with embedded data logging as baseline procurement requirements.
Quality control departments at construction materials firms are consolidating testing equipment procurement under centralized capital planning. Independent laboratory equipment distributors are losing share to manufacturer-direct channels serving multi-site operators. This concentration is most visible across American transportation corridor states where federal infrastructure spending has activated materials testing capacity expansion.
Specific Gravity Bench Apparatus Market Segmentation
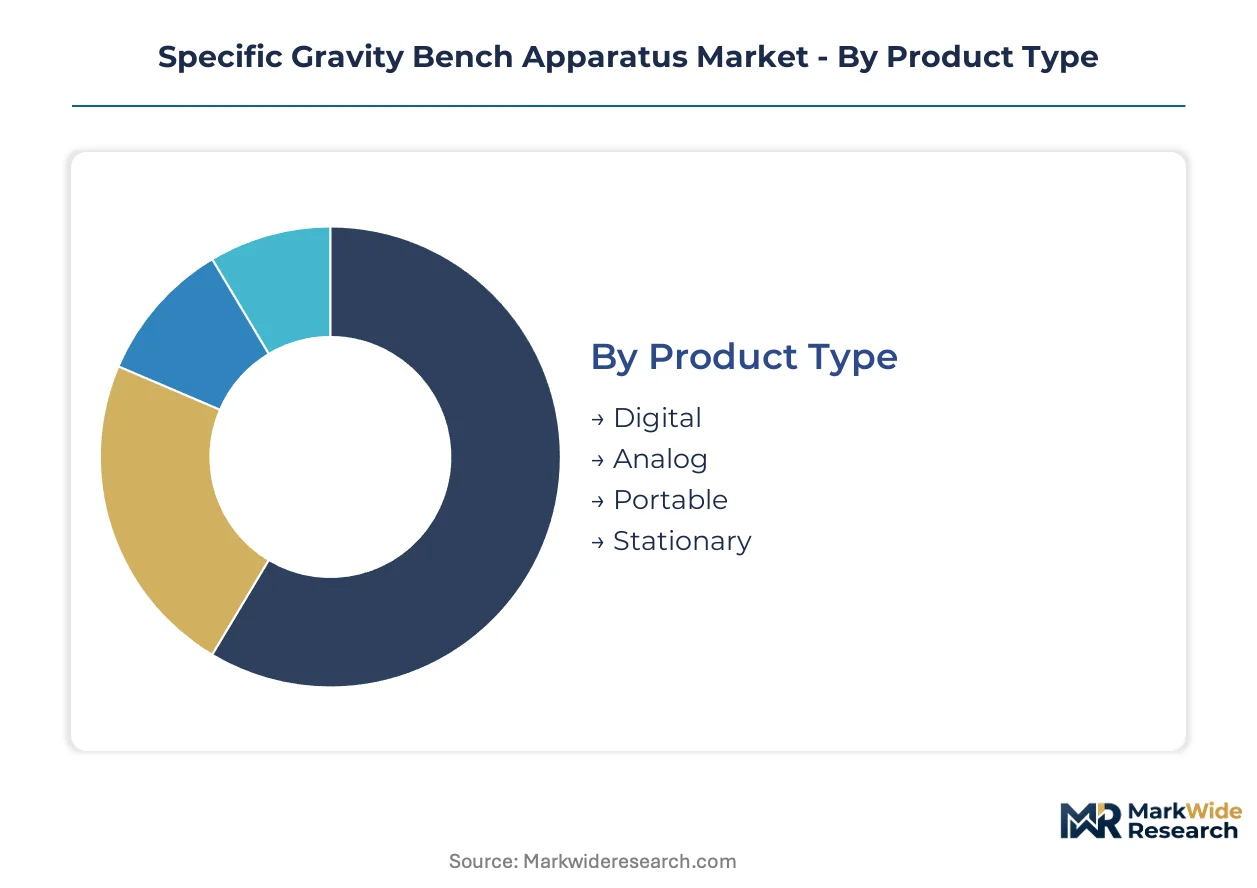
Segmentation in specific gravity bench apparatus reveals how procurement authority is migrating from educational budgets to commercial quality control operations. Understanding these divides exposes where substitution threats from lower-cost methods and where premium digital configurations command durable pricing power.
Product Type:
Substitution pressure concentrates heaviest on analog configurations as hydrometer methods and basic mechanical balances erode their position in cost-sensitive settings.
- Digital:Integrated data logging and calibration tracking eliminate transcription errors in high-throughput environments. Construction materials laboratories in the United States specify these units to meet ASTM C127 and C128 precision mandates under federal infrastructure authorization timelines.
- Analog:Mechanical suspended weighing mechanisms with manual temperature recording dominate educational procurement where capital constraints override precision requirements. University laboratories retain these configurations despite longer test cycles and higher operator error rates.
- Portable:Compact field-deployable units serve geotechnical site investigation teams requiring immediate aggregate verification. These configurations sacrifice water bath precision for operational flexibility.
- Stationary:Fixed laboratory installations with precision temperature-controlled baths anchor permanent quality control facilities. State DOT consolidation of testing capacity favors these high-volume configurations.
Stationary apparatus anchors the volume base while digital configurations gain share at the steepest rate.
Application:
Cost tier stratification separates specification-driven procurement from budget-constrained adoption, with commercial laboratories paying premiums for throughput advantages.
- Laboratory:Permanent testing facilities with ISO 17025 accreditation requirements drive replacement cycles for precision equipment. These installations prioritize calibration management and audit trail documentation.
- Education:University engineering departments and technical colleges prioritize capital efficiency over precision, sustaining demand for basic hydrometer and mechanical balance configurations despite inferior accuracy.
- Research:Advanced materials characterization facilities pursue automated specimen handling and programmable test sequences. Archimedes principle displacement systems with robotics integration serve this segment.
- Quality Control:Construction materials firms and independent testing laboratories face compressed turnaround requirements under transportation infrastructure contracts. Digital bench apparatus with embedded data capture eliminates bottlenecks in high-frequency aggregate verification.
Quality control applications anchor the volume base while research applications expand most quickly through automation adoption.
End User:
Customer type concentration determines channel strategy, with consolidated multi-site operators shifting procurement toward manufacturer-direct relationships.
- Educational Institutions:University engineering programs and technical colleges represent legacy demand characterized by extended replacement cycles and price sensitivity. These buyers retain analog methods despite digital precision advantages.
- Research Facilities:National laboratories and corporate R&D centers specify advanced configurations with programmable specimen handling and continuous temperature monitoring. These users drive technology roadmaps through collaborative equipment development.
- Manufacturing:Construction materials producers and aggregate suppliers operate centralized quality control departments with standardized equipment specifications across multiple sites. These consolidated buyers command volume pricing and dedicated service agreements.
- Healthcare:Medical device and pharmaceutical material characterization laboratories apply specific gravity testing to polymer and ceramic components. This niche segment prioritizes ISO 17025 compliance and documented calibration traceability.
Manufacturing end users anchor the volume base while research facilities command the steepest expansion trajectory through technology upgrade cycles.
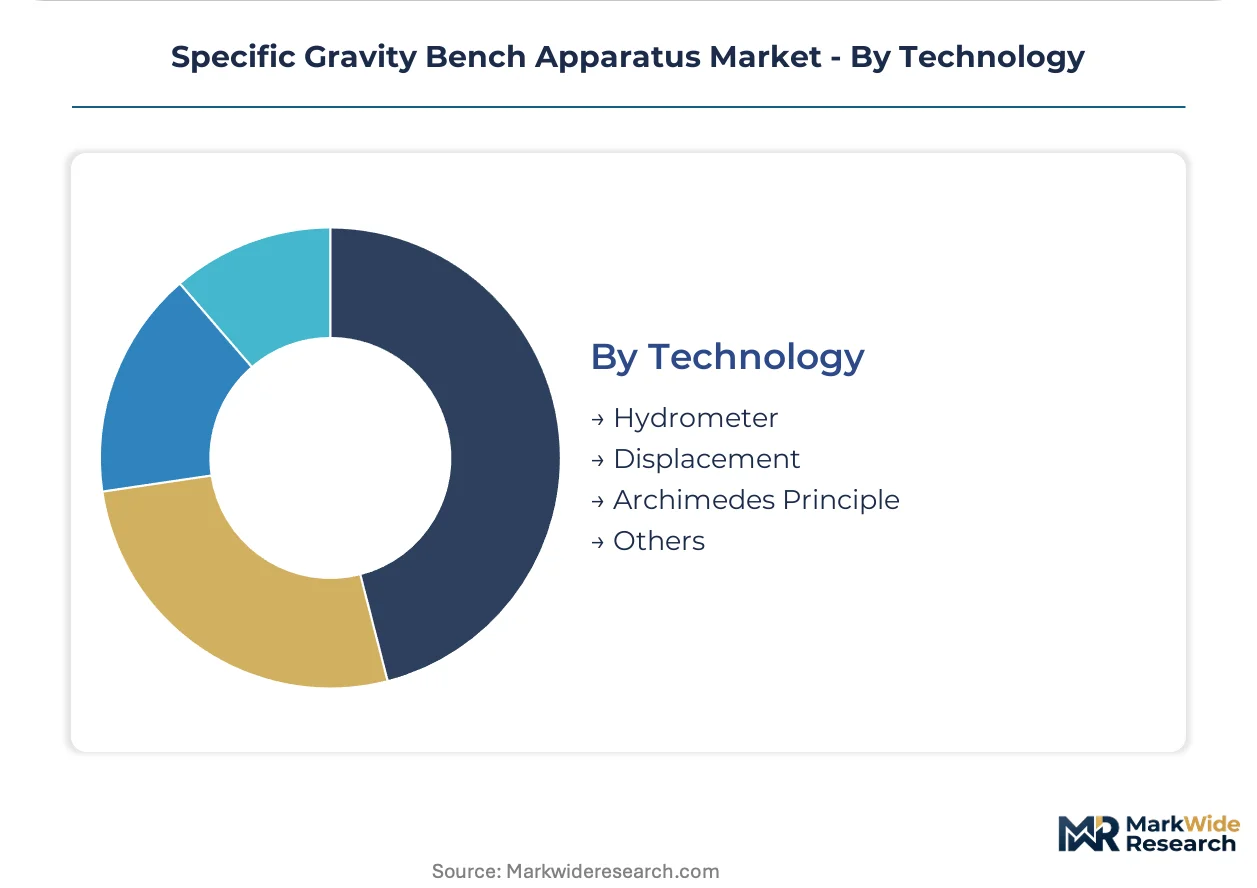
Technology:
Supply concentration among precision water bath fabricators shapes competitive dynamics, with captive manufacturing of calibrated weights creating defensive positions.
- Hydrometer:Float-based density measurement using graduated glass tubes persists in educational settings where equipment cost dominates procurement criteria. These methods suffer from operator-dependent reading errors and temperature sensitivity.
- Displacement:Water immersion techniques with manual volume measurement serve intermediate precision requirements in small commercial laboratories. These configurations face displacement by automated alternatives.
- Archimedes Principle:Automated weighing of submerged specimens with programmable temperature control and digital capture is displacing manual methods in high-throughput environments. State DOT laboratories adopt these systems to meet federal funding compliance timelines.
- Others:Pycnometer and gas displacement methods serve specialized applications in powder metallurgy and pharmaceutical porosity analysis. These techniques occupy narrow niches outside mainstream aggregate testing.
Hydrometer technology anchors the volume base through educational persistence while Archimedes principle systems climb the fastest through commercial quality control adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export specific gravity bench apparatus to Canadian provincial laboratories and Mexican construction materials firms under USMCA procurement harmonization. German fabricators supply precision water bath systems to Middle Eastern infrastructure testing facilities. Cross-border equipment certification reciprocity accelerates trade velocity among OECD member states with mutual recognition agreements.
United States
State DOT laboratories in Texas, California, and Illinois drive replacement cycles under MAP-21 funding timelines. The Federal Highway Administration mandates certified aggregate testing capacity at state level. Chicago and Houston anchor the highest concentration of commercial quality control departments consolidating multi-site procurement.
Germany
Bavarian and North Rhine-Westphalian construction materials laboratories prioritize CE-marked equipment with European metrology certifications. The country's national accreditation body enforces ISO 17025 calibration intervals that compress equipment replacement cycles. Stuttgart and Munich host precision water bath fabricators serving domestic and export markets.
China
Provincial transportation bureaus in Jiangsu and Guangdong expand materials testing capacity under national infrastructure investment programs. The Ministry of Transport issues equipment specifications aligned with GB standards for highway construction quality. Shanghai and Shenzhen laboratories adopt automated Archimedes principle systems for high-throughput aggregate verification.
India
State public works departments in Maharashtra and Tamil Nadu modernize highway materials testing facilities under central road infrastructure programs. The Bureau of Indian Standards governs equipment precision requirements for aggregate quality certification. Mumbai and Chennai construction materials firms centralize quality control procurement under volume agreements.
Japan
Prefectural road laboratories in Kanto and Kansai regions upgrade to digital configurations with integrated data logging. The Ministry of Land, Infrastructure, Transport and Tourism specifies JIS-compliant testing equipment for public works tenders. Tokyo and Osaka anchor corporate R&D facilities pursuing automated specimen handling technologies.
Specific Gravity Bench Apparatus Market Vendor Landscape
Player mix skews toward precision equipment specialists with captive manufacturing of calibrated components. The vendor base clusters around three strategic tiers: integrated laboratory equipment conglomerates with multi-product portfolios, regional fabricators serving domestic certification requirements, and specialized precision instrument makers focused on geotechnical applications. Competitive dynamics center on M&A activity consolidating distribution networks and strategic partnerships embedding equipment into laboratory information management systems.
Among precision instrument specialists, Humboldt Mfg. Co., Controls S.p.A., and Gilson Company exemplify distinct competitive positioning archetypes. Humboldt Mfg. Co. represents North American integrated manufacturing with captive production of water baths and calibrated weights. Controls S.p.A. occupies the European metrology certification tier, leveraging national accreditation schemes to accelerate public tender approvals. Gilson Company anchors specialized distribution density across American Midwest state DOT laboratories. These three entities collectively illustrate how geographic certification advantages and channel specialization create defensive market positions against generalized laboratory equipment suppliers.
| Leading Market Players |
|---|
| Cooper Research Technology |
| Forney LP |
| Durham Geo-Enterprises |
| Sun Labtek Equipments Manufacturing Private Limited |
| Humboldt Mfg. Co. |
| Controls S.p.A. |
| Gilson Company |
| Test Mark Industries |
| Houghton Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at precision water bath fabricators in the American Midwest and Bavaria anchors supply concentration and establishes price floors for digital configurations. Federal infrastructure spending compresses replacement cycles while stainless steel alloy volatility feeds margin pressure through the fabrication tier.
Pricing Analysis
Next-generation Archimedes principle displacement systems command 40-60% premiums over prior-generation manual water bath configurations, while educational hydrometer methods anchor the economy tier. Three-tier pricing structure across premium digital, standard analog, and economy hydrometer levels reflects certification grade differentiation and volume scale. Cost compression in the analog tier is intensifying because university budget constraints cap procurement authority. Educational institutions exhibit highest price sensitivity, whereas state DOT quality control departments prioritize throughput over unit cost.
Supply Chain Analysis
Strategic stockpiling of specialty stainless steel alloys characterizes fabricator procurement in Germany and the United States, while Chinese assemblers favor just-in-time component flows. Precision water bath manufacturing draws from German and American specialty alloy suppliers, with calibrated weight production concentrated in domestic captive operations. Single-source vulnerability in specialty stainless steel feedstock exposes margin stability to commodity price swings. Distribution runs through manufacturer-direct channels serving consolidated multi-site construction materials firms, bypassing independent laboratory equipment distributors in the American Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal MAP-21 authorization extensions and ASTM C127 precision mandate tightening constitute a dual regulatory inflection accelerating technology turnover in materials testing equipment.
For Market Incumbents: Secure captive manufacturing of temperature-controlled water bath components to defend against stainless steel input volatility and margin compression. Anchor service revenue through ISO 17025 calibration interval management software that locks laboratories into recurring aftermarket relationships. Digital configuration substitution by automated Archimedes principle systems threatens legacy suspended weighing mechanism portfolios. For New Entrants and Emerging Players: European metrology certification fast-track through CE marking and national accreditation schemes accelerates public infrastructure tender eligibility in EU member states. Target underpenetrated Indian state public works departments modernizing under central road infrastructure programs. Pursue white-label manufacturing partnerships with established precision instrument makers to bypass distribution channel development costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrument specialists with embedded software capabilities and recurring calibration service revenue. Long-term viability hinges on laboratory information management system integration depth and automated specimen handling intellectual property. Monitor ASTM International supplementary requirement releases as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Specimen Handling Integration | Archimedes principle displacement systems capture share in state DOT high-throughput environments. |
| Calibration Service Revenue Lock-in | ISO 17025 interval management software extends customer lifetime value beyond equipment sale. |
| European Metrology Certification Investment | CE marking and national accreditation accelerate public tender approval cycles in EU infrastructure. |
| Manufacturer-Direct Channel Expansion | Consolidated multi-site construction materials firms bypass independent distributor networks. |
| Stainless Steel Alloy Backward Integration | Captive supply of precision water bath components insulates margin from commodity volatility. |
Methodological Framework
Cross-validation between equipment procurement officers at state DOT laboratories and secondary trade data anchors the qualitative findings. Primary interviews with laboratory managers, quality control directors at construction materials firms, metrology service providers, and precision instrument R&D heads combined with ASTM International standard documentation, AASHTO equipment specifications, and Federal Highway Administration authorization records. Bottom-up unit shipment estimates triangulate against top-down infrastructure spending allocation models.
Sensitivity analysis around federal funding authorization timelines and ISO 17025 recertification schedules tests forecast robustness across the projection horizon. Segmentation dimensions span product type, application tier, end-user category, and technology generation, with regional regulatory cluster differentiation. CAGRs derive from replacement cycle compression rates and automation adoption curves in commercial quality control departments. Industry-specific inputs include MAP-21 funding flow distributions and ASTM C127/C128 precision threshold evolution.
Underlying assumptions cover sustained federal infrastructure authorization levels and stable stainless steel alloy pricing, with deviation risk concentrated in regulatory precision mandate acceleration and educational budget contraction. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Higher Education Technology Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
SETM Education Market